

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Marine Satellite Internet Hits $7,042M in 2026, 11.22% CAGR to 2032

Navigating the Connected Seas: Strategic Intelligence for the Marine Satellite Internet Market
The maritime connectivity landscape has reached an inflection point. As vessels transition from discretionary broadband to mission-critical digital infrastructure, the Worldwide Marine Satellite Internet System Market is reshaping how shipping companies, defense agencies, cruise operators, and offshore energy firms plan their procurement, network architecture, and long-term capital allocation. This market research publication is designed not as a retrospective ledger but as a forward-looking strategic instrument. For executives making multi-year fleet decisions in 2026, the intelligence contained within this study provides the analytical rigor needed to separate temporary technology hype from durable competitive advantage.
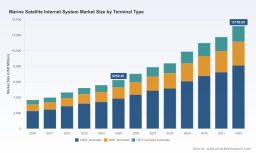
The sector has demonstrated remarkable momentum over the past half-decade. Between 2020 and 2025, global revenue climbed from approximately 3.7 billion USD to over 6.2 billion USD, reflecting both the maturation of high-throughput satellite ecosystems and the accelerating digitization of maritime operations. Looking toward 2032, the market trajectory points toward sustained expansion, with a compound annual growth rate of 11.22 percent. By the end of the forecast window, cumulative revenues will approach 13 billion USD, signaling that satellite internet is no longer a niche maritime add-on but a foundational layer of global maritime logistics. This growth is not merely a function of unit sales; it is being driven by a structural shift in how vessels are operated, maintained, and monetized at sea.
The Architecture of the Analysis
Any market study worth its weight must move beyond headline figures and into the operational mechanics of the industry. This report is structured to serve as a decision-support platform for procurement directors, network architects, fleet managers, and investment committees. The analysis covers terminal type evolution, end-user demand patterns, regional deployment dynamics, and the competitive maneuvers reshaping market concentration. Readers will find granular assessments of how VSAT terminals continue to anchor enterprise-grade reliability while LEO compact terminals and MSS terminals carve out specialized roles in crew welfare, safety communications, and rapid-deployment scenarios. The end-user breakdown examines how merchant shipping, cruise and leisure vessels, government and defense platforms, and offshore energy operators each impose distinct bandwidth profiles, latency tolerances, and redundancy requirements.
Beyond segmentation, the publication delivers actionable operational content. It maps the power consumption realities of maritime terminals, discusses the integration challenges of hybrid GEO and LEO architectures, and evaluates how regulatory developments across the United States, Europe, and Asia are influencing spectrum access, licensing frameworks, and lawful interception expectations. The report also addresses cybersecurity imperatives for fleets transitioning to always-on satellite connectivity, alongside the operational trade-offs between managed service models and self-operated terminal deployments. Each section is designed to translate market intelligence into procurement strategy, vendor evaluation criteria, and fleet-wide connectivity roadmaps.
Competitive Landscape: Who Shapes the Market
Market concentration remains a defining feature of the marine satellite internet ecosystem. The top three players capture a meaningful share of global revenue, while the top five collectively control the majority of high-value managed connectivity contracts. This concentration does not imply stagnation; rather, it reflects the high barriers to entry associated with orbital spectrum rights, terminal certification, global ground infrastructure, and long-term fleet service agreements. Yet the competitive field is increasingly dynamic, with incumbent GEO and hybrid service providers adapting to the low-latency promise of LEO networks while new entrants leverage phased-array terminals and unlimited data models to disrupt traditional pricing structures.
Viasat, operating through its Inmarsat Maritime division, has advanced a bonded multi-orbit strategy that pairs GEO high-throughput capabilities with LEO augmentation. The recent unveiling of the next phase of its NexusWave service, supported by a new VS60 maritime terminal engineered in partnership with Intellian and leveraging ViaSat-3 satellite capacity, illustrates how incumbents are investing in terminal hardware to unlock enterprise networking, video streaming, and mission-critical operations for commercial shipping, cruise, and offshore fleets. SpaceX Starlink Maritime has pursued a different trajectory, emphasizing high-speed, low-latency LEO connectivity through flat-panel phased-array terminals and unlimited data plans designed for crew welfare, operational connectivity, and vessel management across global routes. This approach has resonated strongly with operators seeking predictable bandwidth economics and rapid terminal deployment.
Iridium Communications continues to anchor the market in global LEO narrowband and broadband services, with Iridium Certus providing data, voice, and hybrid connectivity solutions tailored to vessels that require pole-to-pole coverage and reliable backup communications. Its recent selection by a major shipping line for hybridized fleet operations alongside Starlink underscores a broader industry pattern: operators are increasingly layering complementary networks rather than relying on a single provider. Marlink has built its position around managed hybrid satellite networks that integrate GEO VSAT, Starlink, and OneWeb LEO resources, with an emphasis on smart digital solutions, cybersecurity, and high-availability connectivity for commercial shipping and cruise lines. Speedcast brings deep expertise in VSAT and managed satellite communication services for maritime, offshore, and energy sectors, prioritizing reliability, network optimization, and large-fleet integration.
Equipment manufacturing remains a critical enabler. Intellian Technologies supplies high-performance maritime VSAT antennas and terminals, including systems designed for Viasat NexusWave and OneWeb-compatible architectures, spanning yachts to large commercial vessels. KVH Industries continues to deploy mini-VSAT broadband terminals and airtime services, with TracPhone systems engineered for global HTS coverage across yachts, commercial vessels, and crew connectivity applications. On the satellite operator side, Intelsat offers FlexMaritime and other GEO and hybrid VSAT solutions supporting enterprise networking and operational data across global shipping routes, while the Eutelsat Group, integrating OneWeb LEO capacity, delivers resilient high-throughput connectivity for vessels operating in remote areas. Hughes Network Systems, under EchoStar, has expanded its footprint with ruggedized transportable LEO terminals certified for Comms-on-the-Pause service and compatible with the Eutelsat OneWeb network, enabling rapid broadband deployment in mobility scenarios including maritime support.
The service ecosystem is further diversified by providers such as NSSLGlobal, Satcom Global, IEC Telecom, and AST Networks, each contributing specialized combinations of VSAT, L-band, Iridium, Inmarsat, and hybrid LEO offerings with regional expertise, fleet management tooling, and IoT-focused solutions. The competitive dynamics are not merely a roster of vendors; they reflect a strategic contest over managed service models, terminal standardization, multi-orbit bonding, and the ability to deliver predictable performance across harsh maritime environments.
Market Dynamics: Forces Reshaping Procurement and Deployment
Several structural forces are converging to redefine how marine satellite internet systems are evaluated and purchased in 2026. First, the terminal power envelope is becoming a more prominent operational consideration. Maritime VSAT and LEO terminals typically consume between 60 and 150 watts, with high-speed performance kits requiring elevated power budgets compared to traditional GEO systems. This reality has direct implications for vessel power management, installation design, and the economics of broadband operations on smaller or energy-constrained platforms. Second, safety and regulatory mandates are reinforcing demand for robust, certifiable connectivity. Iridium Certus GMDSS provides the only truly global maritime distress and safety system, encompassing distress alerts, safety voice, Maritime Safety Information, LRIT, and SSAS services, making it a non-negotiable element for operators prioritizing regulatory compliance and crew safety.
Third, spectrum policy is entering a period of active modernization. The FCC is advancing spectrum policy that includes auctions in the Upper C-Band and AWS-3 bands, alongside modernization of satellite regulations intended to support growing LEO and space operations. In parallel, the EU Open Internet Regulation and the proposed Digital Networks Act maintain net neutrality principles while addressing spectrum harmonization and satellite integration for digital sovereignty. These regulatory trajectories influence not only terminal certification and service availability but also the strategic calculus of operators seeking to operate seamlessly across jurisdictions. Governments are also asserting digital sovereignty through licensing, taxation, and lawful interception requirements for LEO satellite services that cross national borders, adding a layer of compliance complexity to global fleet deployments.
Fourth, the industry is navigating a phase of accelerated terminal and service evolution. The introduction of ruggedized transportable LEO terminals, new bonded connectivity services, and hybrid fleet configurations signals that the market is moving from single-orbit dependency to multi-orbit orchestration. Operators are increasingly designing networks that combine the throughput and latency advantages of LEO with the coverage reliability and service maturity of GEO, while maintaining safety-grade fallback. This hybridization trend is reshaping vendor evaluation criteria, as procurement teams now weigh not only bandwidth cost but also integration complexity, service continuity, cybersecurity posture, and regional support coverage.
Worldwide Marine Satellite Internet System Market
Why This Study Matters for 2026 Decision-Making
For organizations planning fleet upgrades, terminal standardization, or connectivity partnerships in 2026, the strategic value of this research lies in its ability to convert market complexity into actionable clarity. The report does not simply report what happened between 2020 and 2025; it maps the conditions that will determine which investments deliver durable advantage through 2032. Decision-makers will find structured analysis of how terminal types are evolving in response to bandwidth, latency, power, and safety requirements. End-user segments are examined through the lens of operational priorities, revealing why merchant shipping, cruise and leisure, government and defense, and offshore energy operators each demand distinct connectivity architectures. Regional dynamics are assessed in terms of deployment density, regulatory environments, and competitive intensity, without oversimplifying the heterogeneity of local market conditions.
Equally important, the study provides a framework for interpreting vendor strategies and market concentration trends. Understanding how leading providers are positioning multi-orbit services, managed hybrid networks, and next-generation terminals allows procurement leaders to anticipate pricing shifts, service bundling patterns, and potential consolidation risks. The competitive profiles and recent developments captured in this research highlight where innovation is materializing, which partnerships are gaining operational traction, and how terminal hardware is becoming a strategic differentiator rather than a commodity accessory.
Broadband Satellite Services Market
The report also addresses the operational realities that often fall outside high-level market summaries. It examines the implications of terminal power consumption for vessel integration, the role of safety-grade services in shaping baseline procurement requirements, and the regulatory landscape that influences spectrum access and cross-border service continuity. Cybersecurity considerations are treated as integral to connectivity strategy rather than as an afterthought, reflecting the reality that always-on maritime broadband expands both operational capability and attack surface. By weaving these dimensions together, the study equips readers to evaluate total cost of ownership, service resilience, and long-term scalability with greater confidence.
What You Will Gain by Going Deeper
This overview is intentionally designed as a strategic preview. It demonstrates the analytical depth, market context, and decision-oriented framing that the full report delivers, while leaving the precise segmentation values, regional revenue distributions, end-user percentages, and terminal-level financial breakdowns for the complete publication. Those details matter because they convert directional insight into procurement-ready intelligence. They allow organizations to benchmark fleet expenditure patterns, compare regional deployment economics, and align terminal selections with specific operational profiles rather than generic market averages.
The full study also expands the competitive analysis into a structured evaluation of service models, terminal compatibility, orbital strategy, and regional support coverage. It provides the context needed to assess where bonded multi-orbit architectures are delivering measurable performance gains, where LEO-only solutions are appropriate, and where GEO fallback remains essential for safety, redundancy, or regulatory compliance. For investment committees and strategic planners, the forecast period through 2032 offers a basis for modeling recurring connectivity spend, terminal refresh cycles, and the reallocation of operational budgets toward digital services.
Next Steps for Strategic Leaders
The Worldwide Marine Satellite Internet System Market is expanding at a pace that rewards disciplined analysis. Organizations that treat connectivity as a strategic utility rather than a tactical expense will be better positioned to manage fleet performance, crew welfare, compliance obligations, and operational resilience. This research publication is built to support that shift. It provides the market context, competitive intelligence, and segmentation logic required to make informed 2026 decisions with an eye toward the 2032 horizon.
To access the complete segmentation data, regional revenue distribution, end-user breakdowns, and the full competitive profiles accompanying this forecast, visit the source page for the Worldwide Marine Satellite Internet System Market research. The detailed tables, terminal-level analysis, and operator-level scenario discussions are available there, enabling procurement, network, and strategy teams to translate market momentum into concrete fleet and service decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Marine Satellite Internet System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com