

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Deicing Salt Market Hits $2.7B in 2025, Rises to $3.45B by 2032 at 3.55% CAGR

Strategic Imperatives in the Global Deicing Salt Market: A 2026 Outlook
Market Trajectory and Macroeconomic Context
The global deicing salt industry is entering a phase of measured but steady expansion, driven by recurring winter maintenance demands, infrastructure aging, and evolving regulatory frameworks across key geographies. According to the latest comprehensive assessment, the worldwide market reached approximately 2.7 billion USD in 2025, reflecting a consistent upward trajectory from the 2.27 billion USD recorded in 2020. Over the historical baseline period, revenue growth has been characterized by incremental volume gains, supply chain recalibration, and periodic cost pressures linked to energy markets and packaging logistics. Looking ahead, the forecast window through 2032 projects a cumulative valuation approaching 3.45 billion USD, supported by a compound annual growth rate of 3.55 percent.
This growth profile is neither explosive nor stagnant. It reflects an industry that has matured past the volatility of early-cycle commodity swings and now operates within a more predictable demand envelope. Municipal budgets, transportation authorities, and commercial facility managers continue to treat deicing salt as a non-negotiable operational input, even as they increasingly weigh environmental compliance, corrosion mitigation, and total lifecycle costs against unit pricing. For executive teams navigating procurement strategy, capacity planning, and geographic diversification in 2026, the macro trajectory provides a reliable foundation for medium-term forecasting. The exact valuation inflection points, regional contribution shifts, and application-specific demand curves are mapped in granular detail within the full report, enabling precise scenario modeling rather than reliance on broad industry heuristics.
Structural Drivers and Supply-Side Dynamics
Several interconnected forces are shaping the operational landscape for deicing salt producers and distributors. On the raw material side, underground mining operations have experienced meaningful cost escalation, with production expenses rising in the 8 to 12 percent range during 2024 due to higher energy consumption in subterranean extraction and hauling processes. Simultaneously, salt evaporation facilities in North America operated against natural gas price environments averaging around 3.50 USD per MMBtu in the fourth quarter of 2024, influencing the economics of solar and solution-based production pathways. These input cost dynamics are not uniform across all production methods, and they create divergent margin profiles depending on whether operators rely on deep-shaft mining, conventional solar evaporation, or blended chemical formulations.
On the regulatory front, compliance considerations are increasingly influencing product selection and procurement specifications. Environmental directives in Europe continue to limit chloride discharge from deicing applications into sensitive waterways, prompting municipalities and contractors to prioritize low-chloride alternatives in designated zones. In North America, environmental agencies have reinforced recommendations favoring magnesium chloride blends over pure sodium chloride to reduce infrastructure corrosion and ecological impact. Packaging and logistics costs have also been affected by trade policy adjustments, with certain container tariffs adding a measurable premium to imported packaged goods during 2024. These overlapping pressures are pushing buyers toward value-engineered specifications, blended formulations, and supplier partnerships that can demonstrate consistent quality, environmental documentation, and reliable winter-season delivery.
Competitive Landscape and Enterprise Positioning
The industry remains moderately fragmented, yet it is anchored by a cohort of scaled producers with integrated mining assets, evaporation facilities, and established distribution networks. Concentration metrics indicate that the top three participants collectively account for roughly 22.45 percent of total market revenue, while the top five extend their combined share to approximately 31.8 percent. This structure suggests that while large incumbents hold meaningful influence over pricing benchmarks, logistics standards, and product specifications, there remains sufficient room for regional specialists, niche blenders, and logistics-focused intermediaries to capture differentiated value.
Among the leading enterprises, Cargill stands out as the world's largest producer of deicing salt, supplying rock salt, solar salt, and treated products from mines and evaporation facilities across North America, Europe, and Asia, with a strong focus on both road and airport deicing applications. Morton Salt operates as a major supplier of rock salt and magnesium chloride-based products, drawing from underground mines in the United States and Canada and offering both bulk and packaged options tailored to highway maintenance programs. K+S has built a leading European position through rock salt production from mines in Germany and Poland, exporting to more than 100 countries and emphasizing anti-caking treated variants for broad operational compatibility. Compass Minerals manages the Goderich mine in Canada, recognized as North America's largest salt producer, and supplies treated rock salt alongside liquid brines to U.S. and Canadian markets. China National Salt Industry Corporation operates as a state-owned giant with massive coastal capacity, producing solar-evaporated salt for domestic deicing demand and export. Ineos Enterprises supplies rock salt from United Kingdom mines for winter road maintenance across Europe, including direct provisioning to national highways agencies. Cheetham Salt contributes Australian solar salt production for colder-region applications and exports into Asia-Pacific markets, while Sudsalz GmbH provides German rock salt from multiple underground sites to Central European customers.
Recent corporate activity underscores how incumbents are responding to the demand for capacity, product differentiation, and sustainability credentials. In late 2024, one major producer announced an expansion of deicing salt production at a Saskatchewan facility to align with North American demand expectations. Another key player introduced a treated deicing salt formulation with enhanced corrosion inhibition designed to protect infrastructure assets while maintaining deicing performance. A European operator meanwhile secured updated environmental certification for sustainable production practices at its German mining operations, signaling the growing importance of documented sustainability compliance in public-sector procurement. These moves illustrate a broader strategic theme: leaders are investing not only in volume but also in specification maturity, environmental documentation, and regional supply assurance.
Worldwide Deicing Salt Market
Segmentation Dynamics and Application Realities
The market's structure reveals clear hierarchy across product types, use cases, and geographic footprints. Rock salt continues to dominate the product mix, reflecting its cost efficiency, widespread availability, and long-standing acceptance among maintenance agencies. Magnesium chloride blends occupy a strategically important secondary position, gaining traction where corrosion concerns, temperature extremes, or environmental sensitivity make pure sodium chloride less desirable. A smaller but notable share of demand flows through alternative and specialty formulations that address specific operational requirements, including pre-wetting additives, treated variants, and liquid brine programs.
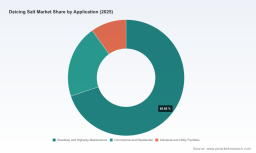
In terms of application, roadway and highway maintenance remains the dominant demand center, consistent with the scale of public infrastructure networks and the recurring need for winter roadway safety. Commercial and residential usage forms a substantial secondary segment, shaped by property management contracts, retail facility operations, and localized weather patterns. Industrial and utility facilities represent a more specialized demand pool, where deicing protocols are often integrated into broader asset-protection and operational continuity plans. Regional demand distribution is heavily influenced by climate exposure, municipal budgeting cycles, and transportation network density, with established northern markets sustaining consistent baseline consumption while certain emerging colder-region corridors show incremental uptake.
Ice Melter Market
Because segmentation outcomes are continually reshaped by weather variability, procurement specification changes, and local regulatory guidance, aggregate splits only tell part of the story. The full report decomposes these dynamics into actionable detail, highlighting where volume concentrations persist, where specification migration is underway, and how different product types interface with specific application requirements across regions.
Forward Outlook and Strategic Decision Levers for 2026
For organizations making procurement, pricing, and capacity decisions in 2026, the deicing salt market presents a set of clear strategic levers. First, cost management must account for the reality that energy-intensive extraction and evaporation pathways are exposed to volatile input pricing, while logistics and packaging components remain sensitive to trade policy and container availability. Second, specification strategy is increasingly decisive: buyers are evaluating blended formulations, treated products, and corrosion-mitigating options not simply as premium upgrades but as risk-management tools that can reduce long-term infrastructure maintenance exposure. Third, regional supply assurance is gaining importance as public agencies and large commercial operators prioritize reliable winter-season delivery, documented quality consistency, and environmental compliance records over narrow unit-price competition.
Growth over the forecast period will likely be shaped by incremental public-sector budget normalization, sustained investment in transportation network upkeep, and gradual specification shifts toward blends and treated variants in environmentally sensitive or corrosion-prone contexts. At the same time, regulatory continuity around chloride discharge, ongoing environmental recommendations favoring lower-impact formulations, and packaging cost pressures will continue to influence procurement behavior. Companies that can integrate production flexibility, specification documentation, and reliable distribution logistics will be best positioned to capture share in a market that rewards operational dependability as much as price competitiveness.
The complete Worldwide Deicing Salt Market research report translates these macro themes into detailed market sizing, segment trajectories, regional breakdowns, competitive profiling, and forward scenario analysis. It provides the structured intelligence needed to evaluate where demand is most durable, how product mix evolution may affect sourcing strategy, and which competitive moves are reshaping supply expectations across key geographies. For decision-makers requiring a precise basis for planning in 2026 and beyond, the full study offers the depth necessary to move beyond general market narratives and into executable, data-grounded strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Deicing Salt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com