

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Global Industrial Wiping Cloth Market to Reach $6.4 Billion by 2032 Growing at 5.15% CAGR

Strategic Intelligence for the Industrial Wiping Cloth Sector: Navigating Growth Through 2032
The global landscape for industrial wiping solutions is undergoing a structural transformation, driven by the convergence of manufacturing expansion, evolving sustainability mandates, and the increasing technical demands of modern production environments. For strategic planners, procurement leaders, and market entry teams operating in 2026, understanding the trajectory of this sector requires more than headline revenue figures. It demands a rigorous examination of material science shifts, supply chain regionalization, application-specific performance requirements, and the competitive dynamics that will dictate margin structures over the next seven years. Our newly released Worldwide Industrial Wiping Cloth Market research study provides an exhaustive, data-grounded blueprint designed to equip decision-makers with the precision intelligence required to allocate capital, optimize sourcing strategies, and position portfolios ahead of market inflection points.
This article serves as a strategic overview of the market's current architecture and the analytical framework embedded within the full report. It highlights the macroeconomic trajectory, the structural forces reshaping supply and demand, the competitive archetypes defining the industry, and the practical analytical modules that enterprise teams can immediately deploy to stress-test operational assumptions. Readers seeking granular regional valuations, detailed sub-segment penetration rates, company-level capacity assessments, and scenario-modeled forecasts will find those deliverables comprehensively housed within the complete study, accessible through our research portal.
Microfiber Cleaning Cloths Market
Market Architecture and Long-Term Growth Trajectory
The global industrial wiping cloth market has demonstrated consistent expansion across the historical evaluation window, advancing from approximately 3.51 billion USD in 2020 to an estimated 4.52 billion USD by 2025. This upward trajectory reflects steady industrial activity, sustained maintenance and repair operations, and the ongoing replacement of legacy cleaning protocols with higher-performance, application-specific wiping media. The momentum carries into the forecast horizon, with the market projected to reach approximately 4.81 billion USD in 2026 and continue its expansion toward a projected valuation exceeding 6.4 billion USD by the close of 2032.
At the core of this projection sits a compound annual growth rate of 5.15 percent, a pace that underscores durable demand while also signaling meaningful variation across product architectures, end-use verticals, and geographic supply ecosystems. A growth rate at this level typically indicates that volume expansion is being supplemented by value migration toward engineered materials, specialized absorbency profiles, and compliance-driven formulations. For enterprises evaluating capacity investments, distribution partnerships, or product development roadmaps, this trajectory suggests that broad-based commodity positioning will increasingly struggle to preserve margin integrity against competitors leveraging material differentiation and application engineering.
The historical record from 2020 through 2025 also reveals the market's resilience through periods of supply chain disruption and shifting industrial output patterns. Rather than experiencing structural contraction, the sector adapted through material substitution, localized sourcing adjustments, and the accelerated adoption of nonwoven and microfiber alternatives where traditional woven or cotton-based formats faced cost or availability constraints. These adaptive behaviors have permanently altered procurement expectations, pushing industrial buyers to prioritize consistency, contamination control, and lifecycle cost over lowest unit price.
Segmentation Dynamics and Strategic Implications
The market's internal structure is defined by distinct product architectures, application requirements, and regional supply-demand balances. Understanding how these layers interact is essential for any organization attempting to forecast capacity needs, design premium product lines, or enter new distribution channels. Our study maps these layers in detail, but even at the strategic level, several structural patterns merit executive attention.
Product Architecture Evolution
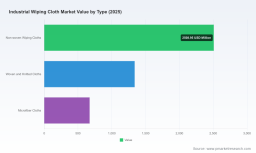
Industrial wiping formats span non-woven constructions, woven and knitted cloth architectures, and microfiber-based solutions, each serving different performance thresholds, absorption profiles, and end-use tolerances. The non-woven category has gained substantial operational relevance due to its manufacturability, consistency, and adaptability to engineered treatments such as controlled linting, chemical resistance, and specialized absorbency. Woven and knitted cloths continue to occupy important niches where tensile durability and reusability are critical, particularly in environments where wiping media must withstand repeated mechanical stress. Microfiber formats, meanwhile, have expanded in applications demanding particulate capture, fine surface preparation, and controlled contamination management, especially in precision manufacturing and sensitive equipment maintenance.
From a strategic vantage point, the material mix is not simply a product preference question. It is a reflection of how industrial buyers weigh total cost of use, process contamination risk, disposal or laundering logistics, and regulatory compliance. Product architectures that can demonstrate verifiable performance consistency, reduced downstream contamination, and alignment with sustainability cascades are gaining purchasing preference in competitive procurement environments.
Application-Driven Demand Patterns
Industrial wiping consumption is dispersed across multiple high-activity verticals, with demand shaped by output volumes, cleanliness standards, and maintenance intensity. Automotive and aerospace operations require wiping media capable of handling lubricants, solvents, and precision surface preparation without introducing particulate or fiber contamination. General industrial manufacturing represents a broad-demand base where absorbency, durability, and bulk availability drive purchasing decisions. Electronics and semiconductors push the performance envelope further, requiring ultra-low-lint, controlled-environment-compatible formats that support stringent cleanliness protocols. Healthcare and life sciences impose their own compliance and contamination-control requirements, while food and beverage processing environments demand materials compatible with sanitary workflows and regulatory expectations.
The strategic implication is that a single product strategy cannot efficiently serve these application clusters. Instead, successful operators are aligning product specifications, packaging formats, and quality assurance protocols to the distinct risk and performance profiles of each vertical. Procurement organizations, in turn, are moving from transactional purchasing toward application-engineered sourcing, where the cost of failure, rework, or compliance deviation is factored into material selection.
Geographic Distribution of Demand and Supply
Regional market architecture reflects differences in industrial density, manufacturing specialization, procurement maturity, and logistics infrastructure. The global demand footprint is distributed across major production zones and consumption hubs, with North America, Europe, and Asia Pacific representing substantial share of activity, while Latin America and the Middle East and Africa contribute incremental but strategically important growth corridors. Regional divergence is not merely a matter of volume; it influences supplier proximity strategies, freight cost exposure, lead-time expectations, and the competitiveness of localized versus imported wiping solutions.
For enterprises planning network expansion, distribution partnerships, or sourcing diversification, regional analysis must go beyond aggregate consumption estimates. The meaningful questions involve where capacity is located relative to end-use clusters, how regulatory and sustainability expectations vary by market, and which applications are most sensitive to supply continuity. The full study provides structured regional assessments that enable these judgments without relying on broad generalizations.
Competitive Landscape and Strategic Positioning
The industrial wiping cloth sector is characterized by a mix of established manufacturers, specialized material engineers, regional distributors, and service-oriented rental and replacement models. Competitive intensity is shaped not only by pricing, but by product reliability, application expertise, supply reliability, and the ability to support compliance-driven procurement requirements. Market concentration metrics indicate a moderately fragmented structure, meaning that while leading participants command meaningful presence, a broad field of regional and niche operators continues to compete on specialization, service models, and customer intimacy.
Competitive Archetypes
Several company profiles illustrate the strategic diversity within the sector. Some participants compete as regional manufacturing and wholesale distribution leaders, building durable advantage through localized supply chains, broad rag and cloth assortments, and strong relationships across automotive, industrial, janitorial, and food service channels. Others position around engineered cleaning wipes designed for critical manufacturing environments and controlled operations, where consistency, cleanliness, and performance repeatability are non-negotiable. Additional players emphasize durability and absorbency for manufacturing, automotive, and general maintenance applications, while long-established manufacturers leverage multi-decade distribution networks and sanitized cloth expertise to serve industrial users with dependable bulk supplies and microfiber options.
A further competitive dimension includes manufacturers focused on nonwoven fabrics and heavy-duty applications, where product design targets grease handling, waste reduction, and operational efficiency. There are also suppliers whose wiping products integrate into broader spill-control and safety portfolios, aligning wiping performance with workplace hazard management. On the service side, certain European providers emphasize rental wipers and absorption mats with scheduled pickup and replacement, giving industrial customers access to consistent supply without bearing the full burden of inventory management and disposal logistics. These varied models demonstrate that competitive advantage in this market is not monolithic; it can emerge from material engineering, service design, regional scale, or application-specific trust.
Strategic Implications of Fragmentation and Consolidation Pressure
With a moderately fragmented market structure, larger players often compete by broadening product ranges, strengthening quality assurance, and deepening customer-facing support, while smaller operators survive by specializing in niche applications, regional logistics, or cost-efficient material flows. Over time, sustainability requirements, compliance complexity, and the growing demand for engineered formats may exert consolidation pressure, particularly where scale enhances quality control, R&D capability, and supply reliability. Conversely, fragmentation may persist where application specificity and localized service deliver more value than centralized volume production.
For buyers, this environment rewards supplier evaluation frameworks that weigh not just unit economics but also defect rates, contamination risk, replenishment reliability, and technical support. For suppliers, the path to durable positioning increasingly depends on demonstrating measurable performance value and building resilient, transparent supply relationships.
Industry Dynamics Shaping the 2026–2032 Horizon
The forward trajectory of industrial wiping solutions is influenced by several interlocking dynamics that extend beyond simple volume growth. These forces are reshaping product design priorities, procurement behavior, and competitive differentiation.
Material Science and Formulation Innovation
Industrial wiping media are commonly manufactured from a range of input materials including cotton rags, polyester-based constructions, nonwoven fabrics such as spunlace, airlay, and meltblown polypropylene, and recycled textile streams. The strategic significance of this material diversity lies in how each input affects absorbency, lint generation, chemical compatibility, rework risk, and end-of-life handling. As manufacturing processes become more precise and sensitive, the performance expectations for wiping media rise accordingly, encouraging innovation in fiber selection, web formation, and treatment technologies.
Innovation is also being accelerated by industry gatherings and technical exchange forums where material developers, manufacturers, and end-users discuss advances in wipes materials, formulations, sustainability, and manufacturing technologies. These conversations are not merely promotional; they reflect real pressure on suppliers to improve consistency, reduce waste, and adapt products to stricter operational environments.
Sustainability, Circularity, and Procurement Expectations
Sustainability considerations are becoming integral to industrial wiping procurement rather than peripheral concerns. Recycled fabrics derived from post-consumer clothing are frequently cascaded into lower-value applications such as wiping cloths in manufacturing and custodial work, an approach that aligns with broader circular economy objectives while also offering cost and resource efficiency advantages. This cascading model creates both opportunities and challenges: it can lower input cost volatility and support ESG narratives, but it also requires careful quality control to ensure that material consistency and performance reliability are not compromised.
As corporate sustainability commitments deepen, buyers are increasingly attentive to lifecycle impact, material traceability, and the alignment of wiping products with broader waste-reduction and resource-efficiency goals. Suppliers that can document responsible sourcing, product durability, and appropriate end-of-life pathways are better positioned to participate in competitively evaluated procurement processes.
Regulatory Attention and Standards-Driven Quality Expectations
Industrial wipers and wipes are subject to ongoing scrutiny related to sustainability, advanced formulations, manufacturing technologies, and application-specific performance expectations. This scrutiny is reinforced through dedicated industry conferences and technical discourse that keep regulatory, compliance, and quality considerations in active focus. While wiping products may not always face the same regulatory intensity as direct-contact hygiene goods, their role in contamination control, chemical handling, and workplace safety ensures that quality standards, documentation, and process control remain strategically important.
For high-value applications in electronics, aerospace, and controlled manufacturing environments, compliance-adjacent expectations can materially influence purchasing decisions. Even where formal regulatory exposure is limited, customer audit requirements and internal quality systems often raise the effective bar for material consistency and documentation.
Worldwide Industrial Wiping Cloth Market
Macro Demand Support from Industrial Activity
Demand for industrial wiping solutions is supported by growth in manufacturing, automotive, metalworking, and maintenance sectors that require absorbent and durable cleaning materials. These sectors generate recurring consumption through routine maintenance, line changeovers, equipment servicing, spill management, and process cleanliness requirements. As industrial output expands and operating standards tighten, the demand for reliable wiping media becomes more structural rather than cyclical. This dynamic provides a foundational reason for the sector's long-term growth profile, but it also means that competitive success will depend on aligning product offerings with the specific operational rhythms and cleanliness demands of each vertical.
What the Worldwide Industrial Wiping Cloth Market Report Delivers
Our research study is designed to convert broad industry context into actionable strategic intelligence. It brings together historical performance data, forward projections, segmentation analysis, competitive profiling, and market dynamic assessment in a structured format that supports planning across multiple functional domains. The report is built for teams that need to make defensible decisions about product development, sourcing, capacity planning, market entry, and competitive positioning.
Core Analytical Modules
The study includes:
- Macro market sizing and growth projections extending from the base year through the forecast horizon, providing a consistent reference frame for revenue planning and investment appraisal.
- Detailed product-type analysis that examines the structural role of nonwoven, woven and knitted, and microfiber formats, including their performance positioning and commercial significance.
- Application-based assessment covering automotive and aerospace, general industrial manufacturing, electronics and semiconductors, healthcare and life sciences, and food and beverage processing, with focus on the distinct demand drivers and performance requirements within each vertical.
- Regional market evaluation that maps demand distribution and supply context across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, enabling geographic prioritization and sourcing strategy calibration.
- Competitive landscape profiling for key participants, including company capabilities, market orientation, and strategic positioning across manufacturing, distribution, engineered-wipe development, and rental or service-oriented models.
- Industry dynamics analysis covering materials, sustainability and circular economy practices, regulatory and standards-related expectations, and macro demand drivers linked to manufacturing, automotive, metalworking, and maintenance activity.
- Recent industry event and innovation context, including major trade shows and technical conferences shaping product development and market dialogue around wipes materials, formulations, sustainability, and manufacturing technologies.
Decision-Use Cases
The report is intended to support a range of high-value decisions, including:
- Evaluating whether to expand, consolidate, or reposition wiping product portfolios in response to material innovation and application-specific demand shifts.
- Assessing supplier selection criteria beyond unit price, particularly where contamination control, consistency, and compliance expectations influence total cost of ownership.
- Identifying regional opportunities where demand growth, industrial density, or supply gaps create favorable conditions for distribution expansion or local manufacturing.
- Understanding how sustainability expectations and recycled-material cascading may affect input sourcing, product positioning, and customer acceptance.
- Benchmarking competitive exposure by examining how different players compete on engineering, service, scale, specialization, and application trust.
- Informing capacity and inventory planning by integrating historical trend patterns with forward growth projections and segment-specific momentum.
Why This Study Matters for 2026 Decision-Making
The 2026 decision environment is defined by heightened attention to supply resilience, material performance, cost control, and sustainability alignment. In this context, industrial wiping cloths are not merely consumable inputs; they are process enablers whose selection can influence cleanliness outcomes, operational efficiency, compliance exposure, and downstream risk. Executives who treat wiping procurement and product strategy as purely tactical may miss the strategic implications of material migration, application engineering, and competitive specialization.
This study provides the evidentiary foundation needed to make more precise judgments. It links market size and growth rate to the structural factors that actually drive value migration, including product architecture, vertical-specific requirements, regional supply context, and competitive differentiation. By combining quantitative trajectory data with qualitative analysis of industry dynamics and company strategies, the report enables readers to test assumptions, prioritize initiatives, and anticipate where performance and compliance expectations will intensify.
The study also recognizes that detailed numbers matter, but only when interpreted within the right strategic frame. Aggregate growth is useful for headline planning; segment-specific insights are essential for portfolio architecture; regional breakdowns are critical for sourcing and distribution design; and competitive profiles are necessary for positioning and negotiation strategy. The full report integrates these layers into a coherent decision-support system rather than a static data table.
Accessing the Full Intelligence Package
Organizations that require detailed sub-segment analysis, regional revenue context, company-level competitive assessment, and forecast frameworks for planning cycles will find the complete study structured to support that depth. The full report is available through our research platform, where teams can access the comprehensive dataset, analytical commentary, and strategic frameworks needed for detailed internal review.
For strategy, procurement, operations, and commercial teams preparing for the 2026–2032 period, the Worldwide Industrial Wiping Cloth Market study offers a disciplined, evidence-based pathway to better-informed decisions. In a market where material performance, sustainability expectations, and application-specific requirements increasingly determine competitive outcomes, the ability to ground strategy in rigorous market intelligence is not optional. It is a core capability for sustainable growth.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Wiping Cloth Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com