

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Copper Hollow Conductors Market to Reach $403.9M by 2032, CAGR 5.49%

Strategic Intelligence for the Copper Hollow Conductors Market Through 2032
The copper hollow conductor sector is navigating a period of structural expansion shaped by electrical infrastructure modernization, medical equipment upgrading, and advanced thermal management requirements. Our latest Worldwide Copper Hollow Conductors Market study is designed to translate this evolving landscape into executable strategy for executives who need to allocate capital, plan capacity, and sharpen competitive positioning through 2032.
The report combines historical reconstruction, demand forecasting, and competitive profiling into a single decision framework. It is built for leaders who require more than top-line figures, offering a structured view of where capacity is expanding, where pricing power is shifting, and how leading manufacturers are differentiating in a moderately concentrated market.
Global Market Trajectory and 2026 Decision Context
The worldwide market for copper hollow conductors is estimated at approximately 277.65 million USD in 2025, reflecting sustained demand momentum after the 2020 to 2025 historical window. Over that period, the market grew from 212.45 million USD in 2020 to 277.65 million USD in 2025, with year-to-year movement shaped by project timing, regional capacity adjustments, and demand variability across industrial and high-technology end-use sectors.
Looking ahead, the market is projected to move from 288.24 million USD in 2026 toward 403.9 million USD by 2032, supported by a forecast CAGR of 5.49 percent. This growth path is not uniform across years or segments, and the report explains where growth is likely to be more resilient versus where it may be more sensitive to capital spending cycles, procurement timing, and raw material volatility.
For 2026 planning teams, the value of the study lies in disentangling short-term price noise from underlying demand structure. The market outlook is placed against a backdrop of pronounced copper price variability, including periods of elevated pricing that have tested margins and procurement strategies. The report shows how demand patterns across key end-use categories continue to shape order books and capacity utilization even as input costs fluctuate.
What the Study Covers and How It Supports Execution
This research is structured as a practical reference for strategy, sales, procurement, and operations teams. Instead of presenting abstract trends, it links market sizing to the operational realities that determine competitive outcomes. The study breaks the market into logical segments and analyzes demand behavior, product preferences, and regional development patterns without relying on oversimplified snapshots.
Key areas included in the report are:
- Market sizing for the historical period from 2020 through 2025 and forecasts across the 2026 to 2032 window
- Segment-level analysis by product form, including rectangular hollow conductors, square hollow conductors, and circular and other profiles
- Application-level analysis spanning power generation and transmission, medical imaging for MRI systems, industrial induction heating, and high-energy physics research
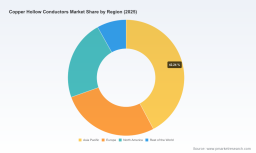
- Regional analysis covering Asia Pacific, Europe, North America, and the Rest of the World
- Competitive assessment of leading manufacturers, including headquarters location, product capabilities, and strategic focus areas
- Recent corporate developments, product emphasis updates, and industry initiatives that signal changing priorities
- Contextual analysis of market concentration, cost dynamics, and procurement considerations relevant to sourcing and pricing decisions
A central strength of the study is its focus on how segment dynamics interact. For example, demand for precision hollow conductors in specialized magnetic and thermal applications does not behave the same way as demand from broader electrical and industrial procurement channels. The report examines these differences qualitatively and quantitatively, helping readers understand which applications are likely to be more recession-resilient, which are tied to project cycles, and which are expanding due to technological upgrade activity.
Segment Structure and Demand Drivers
The market is organized around product geometry, application requirements, and regional demand conditions. These dimensions matter because they influence tooling requirements, manufacturing complexity, lead times, and end-customer expectations. Rectangular and square hollow conductors, for instance, are closely associated with specific coil and cooling configurations, while circular and other profiles serve different mechanical and electrical design needs.
The report also examines application demand in detail. Power generation and transmission continues to be a central demand area, reflecting the importance of conductors in electrical systems where performance, reliability, and thermal management are critical. Medical imaging, especially MRI applications, represents another high-value demand stream where precision and consistency can be decisive in supplier selection. Industrial induction heating adds further volume, driven by manufacturing process needs and energy-intensive production environments. High-energy physics research, while smaller in overall scale, contributes to demand for highly specialized conductor formats with stringent specification requirements.
Rather than presenting these categories as static silos, the report explores how they compete for capacity, how procurement priorities differ among end-users, and how manufacturers balance customization against volume efficiency. This perspective is particularly important for companies evaluating whether to invest in flexible production capabilities or to focus on standardized high-volume formats.
Competitive Landscape and Manufacturer Positioning
The competitive environment is moderately concentrated, with the top three companies accounting for approximately 42.5 percent of market revenue and the top five reaching around 58.2 percent. That concentration pattern indicates that scale, relationships, and product specialization still provide meaningful advantages, even though regional manufacturing footprints and customization capabilities create opportunities for a broader set of suppliers.
The study profiles the principal companies shaping the market and evaluates their strategic positioning. Luvata, headquartered in Pori, Finland, is recognized for custom-made copper hollow conductors for high magnetic field applications, including MRI scanners, electric vehicle stator direct cooling, power generators, and induction furnaces. Its offering emphasizes a wide range of tooling options across shapes and sizes, which supports shorter lead times for specialized orders.
KME, based in Germany, operates as a major European manufacturer of copper and copper alloy products, including bars, profiles, and hollow conductors for industrial and electrical applications. Its multi-plant footprint across Europe, Asia, and the USA gives it a broad production and distribution base capable of serving demanding customer requirements in multiple markets.
Proterial Metals, Ltd., formerly Hitachi Metals and headquartered in Japan, produces copper bar, rod, formed bars, and hollow conductors using tough pitch copper C1100. Its product set supports magnetic field coils for generators, particle accelerators, rectifiers, and heating furnaces, aligning it with applications that require reliable electromagnetic and thermal performance.
cunova, also based in Germany, is a leading producer of copper bars and sections, including solid and hollow sections manufactured with modern machinery for industrial applications. Its focus on section quality and production precision positions it in a segment where tolerance control and consistent output are important differentiators.
Fabmann, based in China, manufactures high-quality custom copper and copper alloy hollow conductors with complex to standard profile shapes, tight tolerances, and internally cooled channels. In addition to hollow conductor products, it offers edge wound and form wound coils, broadening its relevance in applications that require integrated component solutions.
Oriental Copper, headquartered in Thailand, produces copper hollow conductors through extrusion and drawing processes, delivering shiny smooth surfaces suitable for further machining and different cross-sections. Its process emphasis supports downstream manufacturing needs where surface finish and form consistency matter.
Extube, based in India, manufactures hollow conductors from high-conductivity oxygen-free copper with electrical conductivity of at least 100 percent IACS for demanding applications. This focus on material purity and conductivity targets end-use cases where performance margins are narrow and specification adherence is critical.
S&W Wire Co., operating in the United States, offers seamless high-purity hollow conductor tubing for electrical applications requiring water-cooled conductors and high thermal conductivity. Its product emphasis reflects the needs of systems where cooling, purity, and structural integrity must be managed together.
Channel Metal, also known as Zhangjiagang Channel Int'l Co., Ltd. and based in China, supplies customized hollow copper conductor tubes, including microwave hollow conductors in straight lengths, coils, and spools for magnet and electric industries. Its offering illustrates how customized formats continue to matter across specialty markets.
Steel Hollow Section Market
The report evaluates these companies not just as a roster of competitors, but as examples of different strategic plays. Some compete through customization and short lead times, others through material specification, while others rely on geographic reach, integrated coil supply, or process expertise. Understanding these positioning differences helps buyers and competitors anticipate where pricing pressure will emerge and where service value can support margin defense.
Recent Developments and Strategic Signals
Recent industry activity reinforces the importance of operational innovation and application-specific focus. In May 2025, KME published results from its BMBF research project KUPFERDIGITAL 2 on data collection along the production chain for copper and copper alloy connectors. This initiative highlights a broader industry push toward better data, traceability, and chain-wide process visibility, which can influence procurement confidence and manufacturing efficiency over time.
In March 2024, Luvata emphasized high-quality hollow conductors specifically for induction furnaces, underscoring the importance of shape and size options for demanding thermal and electrical performance. Moves like these matter because they show where suppliers are investing attention and where application-specific engineering is becoming a competitive advantage rather than a supplementary service.
These updates are placed in context within the report, allowing readers to interpret corporate announcements not as isolated events but as indicators of shifting product emphasis, market targeting, and operational priorities.
Raw Material Volatility and Market Dynamics
One of the most important decision challenges in this market is managing input cost variability while maintaining supply reliability. Copper prices reached record levels above 14,500 USD per metric tonne in January 2026 before moderating, with COMEX cash spot levels moving in the range of roughly 5.87 to 5.92 USD per pound by late April 2026. That kind of movement has direct implications for quotation strategies, inventory planning, and customer negotiations.
Looking at forward expectations, J.P. Morgan has forecast LME copper prices in the range of 11,600 to 13,500 USD per tonne across 2026 quarters, reflecting the influence of supply-demand dynamics on the pricing outlook. At the same time, IEA analysis has noted that despite record copper prices in early 2026, treatment and refining charges for smelters fell to all-time lows, placing pressure on the midstream sector. This combination of high headline prices and squeezed downstream economics is highly relevant for hollow conductor producers and their customers, because cost structures do not always move in lockstep with spot quotes.
The report also addresses the broader demand environment. Global copper markets experienced meaningful volatility as prices rose through 2025 into 2026, driven by electrification, AI-related data center activity, and power infrastructure demand. For copper hollow conductors, these forces matter indirectly and directly: electrification and power infrastructure affect demand for electrical components, while broader copper market conditions influence procurement confidence, project timing, and supplier negotiation dynamics.
By integrating these material dynamics with demand forecasts and competitive analysis, the study helps decision-makers separate cyclical price turbulence from structural opportunity. That distinction is essential for capacity planning, long-term contracting, and investment prioritization.
Strategic Value for 2026 and Beyond
This report is designed for organizations that need a rigorous, market-wide view without losing sight of operational detail. It supports several key decisions, including where to expand or consolidate product offerings, how to benchmark against leading competitors, which geographic markets deserve closer attention, and how to respond to raw material cycles without compromising service quality.
It is equally useful for buyers and suppliers. Procurement teams can use the analysis to evaluate where customization, purity, lead time, or regional availability creates real value. Manufacturers and investors can use it to assess demand durability across applications, identify where concentration creates pricing or capacity constraints, and recognize which competitive capabilities are becoming more important as the market matures.
Because the research is built around both historical evidence and a 2026 to 2032 outlook, it provides a basis for planning that is anchored in actual market movement rather than guesswork. The forecast period is long enough to be strategically useful, but the report also pays close attention to the near-term signals that shape 2026 decisions.
Conclusion: Why This Study Matters Now
The Worldwide Copper Hollow Conductors Market is entering a phase in which growth potential, competition, and input cost volatility all require more sophisticated planning than in prior years. The convergence of electrification trends, specialized medical and industrial demand, and a moderately concentrated supplier base means that competitive advantage will increasingly depend on product precision, manufacturing flexibility, regional reach, and informed procurement strategy.
Worldwide Copper Hollow Conductors Market
This study offers a comprehensive but actionable view of that environment. It gives executives the context needed to interpret market movement, evaluate competitors, and make better-informed decisions about product focus, sourcing, and growth timing. Its strength lies in combining market-level data with a practical understanding of how manufacturers and end-users actually compete and buy.
For a full assessment of segment dynamics, regional demand patterns, application-level growth coverage, and detailed competitive intelligence, the complete report provides the deeper data and analysis needed to support high-stakes strategy decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Copper Hollow Conductors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com