

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: ZDBC Market to Hit $602.82M by 2032, 5.12% CAGR Through 2032; Asia Pacific Leads

Strategic Intelligence for the Rubber Accelerator BZ (ZDBC) Market: Navigating the 2026–2032 Growth Cycle
In the rapidly evolving landscape of specialty chemicals, the rubber accelerator sector remains a critical enabler of manufacturing efficiency, material durability, and regulatory compliance. As industrial demand shifts toward high-performance vulcanization solutions, organizations operating across latex, tire, and industrial rubber supply chains require more than surface-level forecasts. PW Consulting’s latest Worldwide Rubber Accelerator BZ (ZDBC) Market study delivers the analytical rigor necessary to shape sourcing strategies, capacity planning, and competitive positioning through 2032. This overview outlines the report’s strategic foundation, market architecture, competitive dynamics, and operational insights, while preserving the granular intelligence that decision-makers will uncover in the full publication.
Market Trajectory and the 2026 Decision Window
The current market environment reflects a decade of measured but compounding growth, driven by sustained demand from downstream manufacturing and strategic product substitutions in vulcanization chemistry. Our historical analysis captures revenue progression from the early 2020s through the 2025 base year, establishing a clear trajectory that informs near-term procurement and investment decisions. The 2026 forecast period marks a pivotal inflection point, where consolidation patterns, feedstock pricing dynamics, and regional capability maturation begin to reshape procurement benchmarks and margin expectations.
By projecting forward through the end of the decade, the study maps how accelerated adoption of advanced accelerator formulations intersects with shifting production footprints. The compound annual growth rate across the forecast horizon reflects durable end-use demand and the incremental expansion of precision-grade accelerator offerings. Rather than presenting static snapshots, the analysis emphasizes momentum indicators, capacity utilization signals, and pricing elasticity patterns that procurement leaders and strategic planners can translate into operating models. The full report expands on this trajectory with scenario-based adjustments, enabling clients to test sensitivity around feedstock availability, regulatory timelines, and regional demand intensity.
Report Architecture: Translating Data into Operational Decisions
A high-quality market study is valuable only when it converts macro signals into executable intelligence. This publication is structured to support cross-functional teams, from procurement and R&D to sales strategy and corporate development. It begins with a comprehensive market sizing framework that aligns historical performance with forward-looking revenue pathways, then moves into segmentation design that reflects how buyers actually specify accelerator forms, applications, and regional supply arrangements.
Worldwide Rubber Accelerator BZ (ZDBC) Market
The report includes detailed profiling of product forms and application pathways, allowing readers to understand which specifications dominate procurement cycles and where performance-driven substitutions are gaining traction. Instead of presenting isolated tables, the analysis weaves volume and revenue considerations into a unified view of market structure, revealing where concentration is intensifying and where fragmentation creates negotiation opportunities. The study also incorporates a dedicated competitive section that evaluates how leading manufacturers differentiate through form design, certification portfolios, regional service networks, and application-specific technical support.
Decision-makers will find practical tools throughout the document, including supply-side capability maps, procurement sensitivity considerations, and segment-level commentary that highlights where demand is becoming more specification-sensitive. The full version extends this architecture with deeper regional demand breakdowns, application-level revenue distributions, and form-factor comparisons that are essential for detailed sourcing models and commercial forecasting.
Regional and Segmentation Dynamics Without the Noise
Effective strategy requires understanding where value is created and captured across the supply chain. In this market, regional demand patterns are shaped by manufacturing density, downstream rubber consumption, and the localization of specialty chemical production. Asia Pacific continues to represent a substantial share of total market activity, reflecting the scale of regional rubber processing and the proximity of accelerator production assets to end-user clusters. Europe and North America contribute sizable but more specialized demand, often characterized by stricter specification requirements, compliance-driven sourcing, and premium-grade product preferences. Latin America and the Middle East and Africa region account for smaller but strategically relevant volumes, where infrastructure development and selective industrial expansion can create localized demand pockets.
On the product side, form factors matter significantly because they influence handling, dispersion, dosing precision, and compatibility with downstream processing lines. Powder and granular formats remain central to many compounding workflows, while oiled variants and masterbatch offerings address the growing need for pre-dispersed convenience, reduced contamination risk, and improved mixing consistency. The balance among these forms is shifting as manufacturers seek operational efficiencies and as suppliers invest in formulations tailored to specific rubber systems.
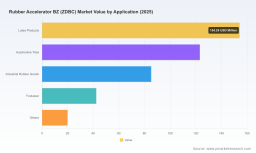
Application diversity further shapes purchasing behavior. Latex-based products, automotive tires, industrial rubber goods, footwear, and other end uses each impose different performance requirements and regulatory expectations. Tire production and latex manufacturing remain particularly influential in driving specification standards, especially where cure speed, scorch safety, and emissions-related considerations matter most. The complete report unpacks the revenue contributions by region, form, and application in greater detail, giving clients the comparative baselines they need to validate internal assumptions and refine category strategies.
Rubber Antioxidant Market
Competitive Landscape: Capability, Positioning, and Strategic Differentiation
The competitive field is defined by a blend of established specialty chemical producers, regionally anchored manufacturers, and suppliers focused on application-specific formulations. Western Reserve Chemical stands out for its WESTCO ZDBC offering, which is positioned around fast cures at low temperatures for natural and synthetic rubber and latex compounds, reinforcing its relevance in performance-driven compounding. Akrochem Corporation contributes both standard accelerator offerings and polymeric masterbatch solutions, such as its Akroform ZDBC-75/EPR/P line, extending its reach into EPDM and broader rubber applications where dispersion quality and polymer compatibility are priorities.
Global specialty chemical producers like Lanxess AG reinforce the market’s premium segment by emphasizing high-quality ZDBC solutions for vulcanization, supported by broader technical service and distribution networks. In China, large-scale producers such as China Sunsine Chemical Holdings underscore the importance of capacity scale and integrated supply capabilities in shaping regional pricing and availability. Additional manufacturers, including Taizhou Huangyan Donghai Chemical, Ningbo Actmix Rubber Chemicals, Shandong Stair Chemical & Technology, Willing New Materials Technology, Wellt Chemicals, Dalian Richon Chem, NOCIL Limited, Henan Kailun Chemical, and Shandong Yanggu Huatai Chemical, illustrate the breadth of technical focus across powder, granule, and masterbatch formats, as well as the increasing role of certification, consistency, and application coverage in competitive differentiation.
Recent developments highlight how competitors are actively reshaping market access and product positioning. In early 2026, ChemCeed partnered with PMI to introduce a high-performance rubber accelerator and antioxidant line for the U.S. market, including dithiocarbamate options such as ZDBC. This type of move signals continued interest in bundled performance portfolios and regional market entry strategies. Around the same time, Western Reserve Chemical reinforced its supply credibility through ISO 9001:2015 certification coverage extending into 2028, demonstrating how quality management and process reliability remain differentiators in procurement decisions. The full report provides a more complete competitive assessment, including positioning maps, service model nuances, and implications for sourcing strategy.
Market Drivers, Regulatory Forces, and Structural Risks
ZDBC demand does not evolve in isolation; it reflects a web of feedstock dependencies, compliance pressures, and downstream performance requirements. One of the most important structural inputs is zinc oxide, which serves not only as a key production feedstock but also as an activator in cross-linking during vulcanization. Fluctuations in zinc oxide availability and pricing can therefore influence both manufacturing costs and formulation economics, making feedstock awareness an essential part of strategic planning.
Regulatory considerations are equally influential. In the European Union, ZDBC falls under REACH frameworks governing chemical registration, evaluation, authorization, and restriction. This creates a compliance layer that affects product registration, documentation, and market access, especially for suppliers operating across multiple jurisdictions. At the same time, workplace safety and emissions-related expectations are accelerating the shift toward low-nitrosamine accelerators in tire and latex production. ZDBC’s role within that transition makes it relevant not only as a curing agent but also as part of a broader regulatory-response strategy for manufacturers seeking to align with evolving standards.
These dynamics introduce both opportunity and risk. On the opportunity side, demand for compliant, high-performance accelerators can support premium positioning and long-term supply agreements. On the risk side, regulatory timelines, feedstock variability, and specification tightening can disrupt procurement schedules and margin planning. The report evaluates these forces together, helping readers identify where resilience can be built through supplier diversification, formulation flexibility, and proactive compliance management.
Strategic Takeaways for 2026 and Beyond
For organizations making 2026 sourcing, capacity, and product strategy decisions, the central message is that ZDBC is not a commoditized input with a single buying rule. It is a specification-sensitive material whose value depends on form, application fit, regional compliance context, and supplier reliability. Procurement teams should evaluate not only price but also dispersion performance, masterbatch convenience, certification status, and technical support capability. R&D and production groups should consider how accelerator selection influences cure behavior, process safety, and regulatory alignment. Commercial leaders should track where consolidation, capacity expansion, and product-line launches are likely to alter supply availability and competitive intensity.
The most effective decisions will come from connecting these elements into a single strategic view. That requires market sizing that reflects real procurement patterns, segmentation that mirrors buyer behavior, and competitive analysis that explains how manufacturers create and defend advantage. This study is designed to provide that connective tissue, while leaving the most detailed revenue splits, regional contributions, and form- and application-level distributions for the full report, where they can be used directly in planning models.
Conclusion: Where Deep Intelligence Meets Actionable Strategy
The Worldwide Rubber Accelerator BZ (ZDBC) Market study from PW Consulting is built for leaders who need more than headline growth figures. It offers a disciplined look at how the market is structured, where competitive pressure is intensifying, how regulatory and feedstock realities shape supply, and what decision-makers should prioritize as they move through 2026 and beyond. By integrating historical performance, forward projections, segmentation logic, and competitive context, the report creates a foundation for sourcing strategy, product planning, and commercial execution.
To access the complete regional and application breakdowns, form-factor revenue distributions, concentration analysis, and full competitor profiles, readers are encouraged to explore the full market research on the PW Consulting website. The detailed intelligence within the publication is designed to be directly actionable, giving teams the specificity they need to convert market insight into confident strategic decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Rubber Accelerator BZ (ZDBC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com