

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Mine Shaft Elevator Market Hits $1.05B in 2025, Booms to $1.50B by 2032

Strategic Intelligence for 2026: Navigating the Worldwide Mine Shaft Elevator Market
The global mining industry stands at a critical inflection point where operational safety, capital efficiency, and technological modernization converge. For executives making capital allocation and procurement decisions in 2026, understanding the trajectory of vertical transport systems underground is no longer optional. It is a strategic imperative. Our latest Worldwide Mine Shaft Elevator Market research consolidates hard data, competitive dynamics, and regulatory shifts into a single decision-making framework. This introduction outlines the strategic value embedded in the full report, demonstrating how the analysis connects macroeconomic trajectories with actionable intelligence for boardrooms, engineering directors, and procurement leaders.
The central thesis of this study is straightforward: the market for mine shaft elevators and hoisting systems is expanding steadily while undergoing simultaneous transformation in technology, regulation, and competitive intensity. Companies that treat these systems as mere infrastructure purchases risk underinvesting in reliability and compliance. Those that integrate long-range market intelligence into their planning will secure better vendor partnerships, anticipate regulatory costs, and align capital projects with the most resilient technology segments.
Macro Market Signals and What They Mean for 2026 Planning
The firm foundation of this research is a rigorous historical reconstruction and forward-looking forecast. Drawing on a consolidated base year of 2025 and a historical window spanning 2020 through 2025, the study projects growth through 2032. The global market reached approximately USD 1,049.82 million in 2025, reflecting a recovery from an anomalous dip observed in 2024, when revenue briefly contracted to USD 963.1 million after peaking near USD 970.36 million in 2023. The overall compound annual growth rate across the forecast horizon rests at 5.25 percent, signaling a dependable expansion path rather than a speculative boom. By 2026, the market is projected to climb to roughly USD 1,142.69 million, and sustained growth is expected to carry the figure toward USD 1,502.0 million by 2032.
This growth trajectory is not merely a number on a spreadsheet. It reflects a structural reordering of mining logistics: deeper shafts, increased reliance on continuous and automated extraction, and a backlog of modernization projects that had been deferred during periods of commodity price volatility. For 2026 decision-makers, the message is clear. The demand floor is rising, and procurement windows are compressing. Equipment lead times, integration complexity, and lifecycle costs must be evaluated within a market that is scaling predictably rather than experiencing erratic spikes.
Equally important is market concentration. The analysis indicates that the top three competitors control approximately 42.5 percent of market revenue, while the top five account for roughly 61.2 percent. This concentration suggests that a handful of established providers hold meaningful leverage in pricing, technology roadmaps, and service contract structures. Yet it also implies that niche players and regional specialists retain viable openings, particularly in specialized shaft geometries, localized service ecosystems, and project-based delivery models. The full report dissects this competitive balance without reducing it to oversimplified rankings, enabling leaders to gauge where consolidation pressure is strongest and where differentiation remains achievable.
Competitive Landscape: Who Shapes the Market and How
Any strategic assessment of this market must grapple with the fact that a limited group of globally capable firms dominates the high-value segments of hoist design, engineering, and lifecycle service. Our report profiles the companies that are actively shaping standards, delivery methods, and technology transitions. Rather than presenting generic corporate descriptions, the study maps each player against the specific capabilities that matter in mine shaft applications: shaft geometry constraints, carrying capacity requirements, automation readiness, safety compliance, and service responsiveness across remote operational sites.
ABB remains a central reference point for hoist system integration. With more than a century of experience and over 1,000 installations worldwide, the company provides complete hoist solutions covering mechanical and electrical components as well as shaft equipment. Its positioning is especially relevant for organizations seeking integrated systems rather than component-level procurement. In late 2024, ABB formalized a collaboration with EcoHoist to build a scale demonstrator of vertical bucket elevator technology for mine shafts. The initiative targets reductions in capital cost and construction time, signaling a broader industry appetite for modular and potentially lower-cost vertical transport architectures. For 2026 strategists, this matters because it hints at future procurement pathways that could alter total cost models for new shafts and major refurbishments.
Worldwide Mine Shaft Elevator Market
SIEMAG TECBERG continues to function as a core supplier of shaft hoisting systems and associated equipment, delivering full mechanical and electrical solutions for production and service hoists. Its recent delivery footprint reinforces the point that large-scale international projects remain a primary demand driver. In May 2025, the company executed a cold start-up for the supply of five shaft hoisting systems serving two mines operated by India-based MOIL Limited. This kind of multi-system delivery underscores how project pipelines in key mining territories sustain revenue stability even as individual commodity cycles fluctuate. The full report situates such developments within regional demand patterns and project financing environments, allowing readers to distinguish between one-off wins and evidence of durable market engagement.
Alimak Group operates from a slightly different vantage, specializing in rack-and-pinion industrial elevators and construction hoists tailored to mining environments. Its portfolio spans permanent and temporary vertical access solutions used in mine shafts, smelters, processing plants, and underground operations. For organizations managing hybrid access requirements or prioritizing flexibility in shaft design, Alimak's capabilities represent a distinct value proposition relative to conventional drum or friction hoist suppliers.
Century Elevators addresses a practical constraint that many operators face: narrow shaftways. The company distributes and provides permanent mining elevators with controls and drives optimized for mine safety regulations and high-speed vertical transport in constrained geometries. In markets where shaft dimensions are dictated by legacy infrastructure or geological limitations, the ability to fit efficient transport systems into narrow openings becomes a decisive operational advantage.
KONE Corporation brings a complementary angle through customizable elevator solutions with energy-efficient designs suitable for underground mining environments, backed by extensive testing capabilities in deep mine shafts. While often associated with civilian vertical transport, KONE's underground-oriented engineering and testing infrastructure give it credibility in settings where reliability and energy performance intersect.
These profiles are not presented as isolated snapshots. The report examines how such companies compete on integration depth, service coverage, innovation timelines, and project execution. It also maps recent developments against long-term strategic positioning so that readers can evaluate whether observed collaborations, deliveries, or product demonstrations indicate incremental improvement or genuine portfolio shifts.
Segment Dynamics Without Over-Simplification
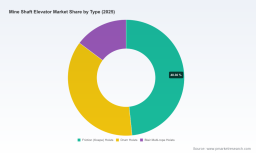
One of the deliberate strengths of this study is that it avoids the temptation to reduce a complex market to a small number of simplistic percentage splits. Instead, the report organizes segment analysis around engineering and operational logic. Hoist types differ not just in name but in mechanical behavior, maintenance profiles, and suitability for specific shaft configurations and load requirements. Friction-based systems, drum hoists, and multi-rope configurations each present distinct tradeoffs in terms of installation complexity, rope and brake management, speed envelopes, and service life. The report connects these technical distinctions to procurement considerations, so buyers can compare options based on total cost of ownership rather than sticker price alone.
Application context matters just as much. Metal mining operations, coal mining, and non-metal or industrial mineral extraction place different demands on vertical transport. The report analyzes how shaft depth, payload profiles, 교대 frequency, and regulatory exposure vary across these application domains and how those differences influence system selection, redundancy planning, and inspection regimes. Importantly, it ties those application dynamics to component-level realities. Steel wire ropes, for example, remain core components in mine shaft hoisting systems and are subject to regular nondestructive testing and visual examinations to monitor diameter loss, broken wires, and strength reduction. This is not a peripheral maintenance detail; it is a safety-critical input that affects inspection scheduling, rope replacement planning, and downtime forecasting. The report integrates such component realities into segment discussion so that planning is grounded in operational substance.
Regulatory and Safety Dynamics as Strategic Variables
Regulatory frameworks are not background noise in this market; they are decisive forces shaping procurement specifications, inspection cycles, service contracts, and retrofit timelines. In the United States, MSHA provides Mine Hoist and Elevator Inspection Program Training that covers inspection of mine hoist and elevators, the impact of the mine environment on components, and mechanical escape facilities. This type of training framework signals how seriously regulators treat the operational and human factors of vertical transport. It also implies that vendors and operators alike must maintain competency in inspection methodology, not merely equipment installation.
The regulatory environment is also tightening in specific technical areas. U.S. regulations require that hoists used to transport persons be equipped with overspeed, overwind, and automatic stop controls, along with brakes capable of stopping the fully loaded device. These requirements translate directly into design specifications and verification burdens for manufacturers and integrators. In December 2024, MSHA finalized updates to safety standards for electric motor-driven mine equipment, incorporating ANSI voluntary consensus standards that became effective in January 2025. For 2026 planning, this is especially relevant because compliance expectations can shift procurement lead times and influence whether a project chooses new equipment, retrofitted systems, or refurbished assets with updated control architectures.
The full report embeds these regulatory developments within the broader market dynamics section, showing how safety mandates interact with technology adoption, inspection costs, and competitive positioning. For executives overseeing compliance, risk, or capital planning, the value lies in understanding not just what the rules say but how enforcement patterns and standard revisions reshape commercial behavior across the industry.
Practical Utility: What the Report Delivers for Decision-Makers
This study is built for execution, not just intelligence consumption. It is structured to support several core workstreams that matter in 2026. First, it provides a market sizing and growth baseline that can anchor demand forecasts, capacity planning, and investment timing. Second, it presents competitive profiles and recent project activity in a format that helps procurement and engineering teams benchmark vendor capabilities and assess stable relationships versus opportunistic bids. Third, it links technology types and application contexts to operational realities, allowing readers to map system choices to shaft constraints, payload needs, and maintenance expectations. Fourth, it incorporates regulatory developments as dynamic variables, not static footnotes, so that compliance considerations are evaluated alongside cost and performance.
For companies planning new shafts, major hoist replacements, or phased modernization programs, the report can support three practical tasks: comparing total lifecycle value across hoist types, anticipating where service coverage and spare parts logistics will matter most, and timing investments to align with both regulatory cycles and regional demand momentum. For suppliers and investors, the same base of analysis can inform positioning decisions, partnership strategies, and identification of underserved segments with credible demand signals.
Crucially, the report does not stop at high-level narrative. It brings together historical performance, forward projections, segmentation logic, competitive profiles, recent developments, and regulatory context in a coordinated structure. That design reduces the risk of making decisions based on partial information. Instead of assembling scattered sources, leaders can work from a unified analytical frame that connects market size, competitive concentration, and operational requirements.
Why the Full Report Matters Now
The worldwide mine shaft elevator market is large enough to attract strategic attention and dynamic enough to reward careful analysis. USD 1,049.82 million in 2025 base revenue, a 5.25 percent CAGR through 2032, and a forecast exceeding USD 1.5 billion by the end of the period all point to a market with durable expansion. At the same time, the competitive set is concentrated, regulatory expectations are evolving, and technology pathways are being tested through demonstrator projects and specialized delivery programs. This combination means that intuition alone is insufficient for 2026 planning.
What this introduction has provided is a credible preview of the analytical depth and practical relevance available in the complete study. It has shown how market growth, competitive positioning, segment logic, and safety regulation are woven together into a decision-ready framework. What it has not done, by design, is expose the granular regional and application-level breakdowns, company-specific metric comparisons, and exact segmentation values that empower more precise planning. Those detailed calculations, benchmark tables, and scenario-ready figures are reserved for the full report, where they can be used without dilution and applied directly to procurement, investment, and risk-management workflows.
For executives and analysts who need to move beyond trend commentary into actionable strategy, the complete Worldwide Mine Shaft Elevator Market research offers the structure and specificity required to make confident decisions in 2026 and beyond.
Elevators Market
For detailed analysis of this topic, please visit the official page: Worldwide Mine Shaft Elevator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com