

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting Forecast: Worldwide Phlegm Suction Tube Market to Rise from USD 650 Million in 2025 to USD 926.9 Million by 2032 at a 5.2% CAGR
By pmarketresearch, 2026-08-18
Worldwide Phlegm Suction Tube Market — Strategic Preview for 2026: PW Consulting’s New Market Intelligence
Executive Summary
PW Consulting today releases a forward-looking executive preview of our full market research report on the Worldwide Phlegm Suction Tube market. Built on an audited historical baseline (2020–2025) and a seven-year forecast (2026–2032), the study synthesizes clinical, commercial, regulatory, and operational intelligence that will directly inform buy-side, sell-side and policy-making decisions in 2026.
Offshore Wind Foundation Market
Key headline metrics: the global market expanded from approximately USD 510.5 million in 2020 to USD 650.0 million in 2025. Under the scenarios modeled in this research, the market reaches roughly USD 926.9 million by 2032, representing a 2026–2032 compound annual growth rate (CAGR) of about 5.2%. Market concentration is moderate: the top three players account for roughly 42.6% of market value and the top five for about 58.4% — a structure that supports both consolidation and continued opportunity for specialist innovators.
Worldwide Disc Grinder Market
Why this study matters for 2026 decision-makers
- Timing: 2026 is a strategic inflection point — suppliers that lock in supply-chain resilience, regulatory clarity, and differentiated clinical value now will secure preferred-provider status as procurement cycles accelerate.
- Margin preservation: Rising demand for disposable systems and biocompatible materials increases procurement complexity and cost pressure. Buyers and manufacturers need forward-looking price benchmarking and material-sourcing playbooks to protect margins.
- Regulatory and reimbursement alignment: Recent shifts in standards and coding make early alignment a competitive advantage. The report clarifies what compliance investments produce outsized commercial return in 2026 and beyond.
What PW Consulting’s full report delivers (practical, operational content)
This release is a strategic preview. The full report is designed as a hands-on toolkit for commercial leaders, procurement officers, R&D heads and M&A teams. Key deliverables include:
Power Plant Lightning Protection Market
- Market sizing and scenario-based forecasts (base year 2025; historical period 2020–2025; forecast 2026–2032) with sensitivity analyses and breakouts by product architecture, clinical setting, and geography (note: granular segment datapoints are available in the full report).
- Supply chain and cost stack mapping that identifies single-source risks, material cost drivers (PVC, silicone, specialty polymers), and tiered supplier scorecards for near-term sourcing decisions.
- Regulatory and reimbursement navigator: a practical matrix mapping ISO and FDA requirements, key HCPCS codes and payer triggers, plus a compliance-impact calculator to prioritize investments that unlock access to critical markets.
- Buyer’s playbook for procurement teams: contract language templates, inventory buffers calibrated to lead times, and a supplier qualification checklist focused on sterility assurance and radiation/irradiation process controls.
- Clinical adoption roadmaps for closed vs. open suction systems, with use-case analytics across hospital ICU, emergency, ambulatory, and home-care pathways — highlighting cost-per-procedure, infection-control trade-offs, and clinician adoption barriers.
- Commercial intelligence dossier on 12+ manufacturers including product portfolios, differentiators, manufacturing footprint, and go-to-market strategies — complemented by a near-term M&A heatmap and partnership scenarios.
- Price and margin benchmarks, product-level gross margin estimates, and suggested strategic pricing levers tailored to hospitals, GPOs, and home-care distributors.
Competitive Landscape — strategic reads on core players
The market combines global medical-disposables incumbents with nimble regional manufacturers. Our qualitative and quantitative benchmarking indicates four recurring strategic postures: scale players focusing on portfolio breadth and distribution; cost-leaders emphasizing high-volume disposable supply; specialized innovators introducing value-added design (e.g., closed-system features, directional valves); and contract manufacturers serving OEMs.
- Cardinal Health — leverages broad distribution and clinical relationships to position Argyle™ and Medi-Vac™ lines as procurement-safe, hospital-ready options. Strength: channel reach and integrated supply agreements. Watch: margin pressure in commoditized SKU lines.
- BD (Becton Dickinson) and Medline Industries — compete on clinical trust and product hygiene design; their emphasis on kit solutions and procedural convenience resonates with busy OR/ICU buyers. Strength: trust and product standardization. Risk: exposure to commoditization absent continuous product differentiation.
- Teleflex and Smiths Medical — position higher on critical-care specificity and sterile, performance-tested assemblies. Strategic strength in high-acuity settings where clinicians accept premium for reliability.
- Regional manufacturers (Angiplast, Suzhou Sunmed, Shanghai Teamstand, Dispowell, Luck Medical, Amsino, Sunset Healthcare Solutions) — deliver cost-competitive, high-volume products and increasingly pursue regulatory approval to enter western markets. Strategic play: targeted regulatory investments can unlock rapid share gains in export markets.
Recent credible events underscore dynamic competitive risks and opportunities. For example, a 510(k) clearance secured in mid-2025 illustrates how targeted regulatory wins accelerate access to procedure-grade applications in developed markets; conversely, a high-profile recall in early 2025 highlighted sterility-process risk for closed systems and the reputational damage such events can impose across a supplier’s portfolio. These developments shift procurement criteria: buyers prioritize demonstrable sterility assurance and supplier transparency as much as unit price.
Market dynamics: regulation, reimbursement, and material drivers
- Standards and device classification: Suction catheters are governed by ISO standards that set dimensions, flow performance and sleeve design; many tracheobronchial kits are Class II under FDA regulations with nuanced 510(k) requirements. Manufacturers that embed ISO and FDA expectations into early-stage design significantly reduce time-to-market risk.
- Reimbursement environment: Updated payer guidance (including recent Medicare coding clarifications) modifies the economics of device selection in post-acute and home-care channels. The report’s reimbursement model converts coding changes into facility-level P&L implications.
- Raw materials and manufacturing: Demand for biocompatible PVC and silicone, and the broader U.S. medical tubing market dynamics, are primary upstream cost drivers. The report quantifies elasticity points where polymer substitution, process automation, or strategic VMI (vendor-managed inventory) can improve margins.
Strategic implications and recommended 2026 actions
PW Consulting’s practical guidance for leadership teams entering 2026 centers on five priorities:
- Secure sterility assurance: Audit irradiation contracts and sterile-process validation now; the cost of remediation after a sterility event materially exceeds pre-emptive validation spend.
- Segment the go-to-market approach: Differentiate offerings between acute-care closed systems and high-volume open suction devices for ambulatory/home settings. Tailored contracting and clinical evidence packages increase win rates.
- Cost-to-serve optimization: Rebalance SKU portfolios to reduce low-turn SKUs, negotiate polymer supply contracts indexed to transparent indices, and pilot regionalized production to shorten lead times for major buying clusters.
- Regulatory arbitrage and market entry: Prioritize 510(k) and other market clearances for differentiated devices where premium pricing is viable — and use export-focused OEM partnerships to scale commodity SKUs.
- M&A and partnerships: Pursue tuck-ins for capability gaps (sterility analytics, polymer processing, closed-system valves) or strategic supplier agreements to secure critical polymer throughput.
How PW Consulting’s report supports execution
The full deliverable provides executable artifacts — supplier RFP templates, a regulatory-cost impact calculator, and a procurement negotiation playbook — enabling commercial teams to translate market intelligence into immediate operational moves. Financial-model annexes convert top-line forecasts into SKU-level revenue targets and margin scenarios under alternate raw-material and pricing assumptions.
Next steps & how to access the full intelligence
This preview intentionally surfaces the analysis framework and strategic conclusions while withholding granular segmentation datapoints that are included in the full report. Clients and decision-makers who require the underlying split-by-region, type, and application matrices, the detailed company scorecards and the downloadable tools should contact PW Consulting for access to the full Worldwide Phlegm Suction Tube Market report and supporting datasets.
In 2026, the players who win will not only understand the market’s steady mid-single-digit growth trajectory, but also operationalize sterility, supply-chain control, and targeted regulatory investments to capture disproportionate share. PW Consulting’s study is designed to be the operational blueprint for those choices.
For detailed analysis of this topic, please visit the official page: Worldwide Phlegm Suction Tube Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Phenolic Curing Agent Market Set for 5.12% CAGR — Key Growth Drivers and Regional Leaders Unveiled
By pmarketresearch, 2026-08-18
Worldwide Phenolic Curing Agent Market — Strategic Outlook for 2026: Why This Report Will Be a Boardroom Imperative
PW Consulting’s latest market study on the Worldwide Phenolic Curing Agent Market is published with a clear mandate: equip senior executives, commercial leaders and M&A teams with an executable intelligence set to make confident decisions in 2026. The market reached an estimated USD 861.3 Million in our 2025 base year and, under our central forecast, expands at a compound annual growth rate (CAGR) of 5.12% over 2026–2032 toward just over USD 1.22 Billion by 2032. Those headline numbers capture growth momentum — but the report’s strategic value lies in the operationally-focused tools and scenario framings that translate that momentum into concrete choices for procurement, product strategy, and inorganic growth.
Worldwide Traval Retail Cosmetic Market
Why boards and strategy teams will rely on this study
-
Actionable, not academic: beyond topline sizing, the report delivers supplier scorecards, margin-impact models and a commercial playbook that to-the-dollar estimates how raw-material moves and customer mix shifts will flow to your P&L.
Worldwide Tubing Connections Market -
Risk-to-return mapping: we quantify and stress-test the market under multiple raw-material and regulatory shock scenarios — enabling procurement and R&D leaders to prioritize hedging, reformulation, or vertical options.
Head Mirror Market -
Competitive clarity: a focused benchmarking of leading participants and capability gaps helps identify targets for bolt-on acquisitions, strategic partnerships, or joint development agreements.
Key themes shaping 2026 strategic choices
-
Price and margin pressure from raw-material volatility — Phenol and formaldehyde price swings are no longer episodic. Our monitoring through April 2026 registered substantial increases in key Asian and European phenol hubs and a material step-up in U.S. formaldehyde prices in late 2024. These cost moves are compressing gross margins for producers that cannot pass through rapidly or reformulate toward lower-cost chemistries.
-
Regulatory complexity is increasing — Recent regulatory activity (for example, reporting obligations introduced for certain phenolic derivatives under TSCA’s SNURs) imposes new compliance burdens and potential time-to-market friction for product introductions and reformulations in North America. This alters the calculus for product launches and for acquiring technology or plants that serve regulated uses.
-
Demand pockets remain durable but selectively evolving — End-use engines such as electronics encapsulation, industrial coatings systems, adhesives and advanced composites continue to anchor demand. Within these pockets, formulators are asking for higher-functionality resins, lower-VOC solutions and improved thermal/electrical performance — providing premium niches for suppliers that can invest in application-specific R&D.
-
Moderate market concentration creates maneuvering room — Market concentration metrics indicate a market where the top three vendors account for a meaningful share, and the top five for just over half of industry volume. That structure enables regional champions and specialty players to carve defensible positions while also leaving opportunities for M&A consolidation that meaningfully alters competitive dynamics.
Competitive landscape — what the leading suppliers signal for 2026 strategy
Our report profiles manufacturers and specialty suppliers across the value chain, from global resin platforms to toll processors and niche phenolic houses. Public and private participants — including established resin majors, integrated chemical producers, and specialty tollers — show differentiated plays:
-
Global resin majors bring scale and integrated upstream capabilities, enabling them to navigate raw-material cycles and support large industrial accounts with global supply footprints.
-
Specialty phenolic houses and toll manufacturers offer agility, formulation depth and the ability to service strict application requirements such as electronics and high-performance composites.
-
Some players emphasize coating-grade novolac and resole crosslinkers, while others focus on epoxy-curing compatibility for molding compounds — these strategic choices define customer segments, margin profiles and capital intensity.
To be concrete about names (and why they matter): major global suppliers, integrated chemical producers and specialized phenolic manufacturers are all active in the market. Their positioning ranges from broad aftermarket and OEM supply networks to focused toll-manufacturing and application-driven R&D. This mix means that commercial strategies in 2026 must be calibrated by supplier type — negotiating differently with a captive-volume global player versus a specialty toller capable of rapid reformulation support.
Operational playbook embedded in the report
For executives who need to move from insight to implementation, the study contains a practical set of tools and templates, including:
-
Supplier risk matrix: ranks counterparties by concentration exposure, price-transmission elasticity, and regulatory footprint to prioritize secure, cost-efficient sourcing.
-
Raw-material sensitivity models: quantify EBITDA impact across multiple phenol and formaldehyde price scenarios, enabling finance teams to model forward curves and set appropriate hedge ratios.
-
Reformulation decision tree: a roadmap that links performance targets to reformulation levers, R&D cost estimates, and expected time-to-market under current regulatory timelines.
-
M&A playbook: a prioritized target-screening framework emphasizing capability gaps, regional footprint, and near-term integration risks — and a valuation approach that captures price-cycle volatility inherent to chemical intermediates.
-
Commercial acceleration kit: win/loss frameworks and sample contract clauses (price adjustment language, force majeure drafting aligned with raw-material volatility) that legal and commercial teams can deploy immediately.
Scenario planning — three plausible market pathways for 2026–2028
-
Baseline (central) — Continuation of steady demand and partial pass-through of raw-material cost increases: the market grows in line with our 5.12% medium-term CAGR as formulators accommodate higher input costs through a mix of price adjustments and modest reformulation.
-
Up-cycle (price shock mitigated) — If phenol/formaldehyde supply tightness eases or feedstock prices retreat, producers with underutilized capacity could regain margin through volume recovery and reinvestment in higher-spec products, accelerating premium segment adoption.
-
Regulatory-constrained (cost of compliance rises) — Heightened regulatory actions or new reporting/registration requirements elevate compliance costs and time-to-market barriers, favoring larger integrated firms and creating acquisition windows for smaller players seeking liquidity.
What leadership teams should do in the next 12 months
-
Embed raw-material scenarios into quarterly planning: update price-pass-through triggers for customer contracts and revise capex prioritization to favor flexible, lower-capital intensity projects.
-
Fast-track supplier diversification and strategic inventory: secure multi-sourcing for critical phenolic intermediates and evaluate toll-manufacturing partnerships where capital deployment is undesirable.
-
Accelerate application-focused innovation: invest selectively in higher-margin niches — e.g., electronic-grade curing systems and specialty coating crosslinkers — that demonstrate insensitivity to small-volume cost shocks.
-
Use M&A opportunistically: target regional specialists and tollers whose integration can reduce sourcing risk, add formulation capability, and provide footholds in priority geographies.
Report contents — what you will find inside (high level)
-
Independent market sizing and method notes (historical 2020–2025; base year 2025) and scenario-based forecasts through 2032.
-
Cost and pricing analytics: forward-looking phenol and formaldehyde curves, plus margin impact models.
-
Segment and application demand narratives that identify durable demand pockets and emerging premium opportunities (note: detailed, proprietary subsegment tables and regional splits are available in full report access only).
-
Supplier profiles and competitive benchmarking against capability, capacity and regulatory coverage metrics.
-
Actionable annexes: sourcing playbooks, sample contract clauses, and an M&A target filter.
Closing strategic takeaway
For leadership teams preparing 2026 budgets and strategic roadmaps, the phenolic curing agent market presents both pressure and optionality. The near-term environment is defined by raw-material volatility and tighter regulatory scrutiny; yet, demand durability — backed by applications in electronics, coatings, adhesives and composites — supports disciplined investment in differentiation. PW Consulting’s report provides the analytical foundation and the executable toolset to convert market trajectories into defensible commercial and capital-allocation moves. We present the evidence you need to prioritize: whom to partner with, what to build, and where to acquire — while reserving the granular subsegment datasets that are central to deal and procurement execution for licensed access.
To access the full dataset, proprietary segment tables, and the interactive scenario toolset that management teams will use in 2026 planning cycles, visit the official report page or contact PW Consulting’s industry desk for a briefing and tailored advisory engagement.
For detailed analysis of this topic, please visit the official page: Worldwide Phenolic Curing Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Robust 12.5% CAGR for Worldwide Next‑Generation Data Storage Market Through 2032
By pmarketresearch, 2026-08-18
Worldwide Next-Generation Data Storage Market — Executive Strategic Briefing (PW Consulting)
Introduction
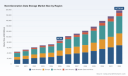
As enterprises finalize technology budgets and strategic roadmaps for 2026, PW Consulting’s new Worldwide Next-Generation Data Storage Market report delivers the market context and decision-grade tools needed to make high-stakes infrastructure choices with confidence. Built on a rigorous historical baseline (2020–2025) and a detailed forecast window (2026–2032), the study models the transition dynamics across traditional and emerging storage paradigms and quantifies the commercial runway for next-generation solutions. The market is sizable and accelerating: our base-year snapshot (2025) places the global market at USD 86,700 Million, rising to an estimated USD 102,547 Million in 2026 and projected to approach USD 197,736 Million by 2032—reflecting an aggregate forecast CAGR of 12.5% (USD, revenue unit: Million).
Disposable Morcellator Blade Market
Why this report matters for 2026 decision-makers
-
Timing and capacity planning — The combination of strong near-term growth and sustained mid-term expansion creates a narrow window for locking in the right balance of capacity, performance, and cost-efficiency. Procurement cycles started in H2 2025 will collide with vendor roadmaps and supply-chain rhythms in 2026; our report identifies optimal staging points for capacity refresh, expansion, and diversification.
Worldwide Utilities¡¯ Customer Information System (CIS) Software Market -
Technology bet sizing — Organizations must weigh incremental upgrades to flash and software-defined platforms against strategic pilots of MRAM, DNA storage, and other emerging persistent-memory technologies. The report’s readiness assessments and scenario modelling help quantify where pilot investment is justified versus where mainstream deployments will deliver ROI in the 2026–2028 window.
Standalone Photovoltaic Water Pump System Market -
Risk and resilience — With concentration metrics indicating meaningful market power among leading vendors (CR3: 38.5%; CR5: 56.4%), the report highlights supplier lock-in risks and contingency strategies for supply disruption, pricing pressure, and interoperability constraints—critical inputs for enterprise risk committees and CIOs.
-
Energy, sustainability and compliance — New KPIs and standards (ISO/IEC 30134 series, evolving IEEE work on AI environmental measurement, and tighter ISO 27001 expectations) are re-shaping procurement and operational requirements. The study offers actionable guidance on aligning storage choices with PUE/WUE/carbon benchmarks and information-security audit readiness.
What the report contains — practical, operational intelligence
-
Consolidated market sizing and growth modelling: a transparent methodology covering historical 2020–2025 data and detailed projections for 2026–2032 with sensitivity bands and scenario alternatives to support board-level investment decisions.
-
Technology readiness and adoption roadmaps: maturity matrices for core and emerging storage classes, including operational triggers for migrating to all-flash, hybrid architectures, software-defined storage, MRAM, and DNA-based archival systems.
-
Procurement playbook and TCO models: configurable CapEx/Opex templates, lifecycle cost illustrations, and vendor negotiation checklists that translate market-level trends into procurement-level actions for 2026 RFPs.
-
Vendor scorecards and partnership archetypes: synthesis of strategic positioning, product strengths, ecosystem fit, and go-to-market motions for leading vendors—designed to accelerate vendor shortlisting while flagging partnership and co-innovation opportunities.
-
Regulatory and infrastructure impact analysis: applied implications of ISO and IEEE standards, data-center utility constraints (including grid connection wait-time dynamics), and compliance controls that materially affect deployment timelines and TCO.
-
Executive decision frameworks: one-page decision matrices, prioritization rubrics, and a short list of “must-ask” vendor questions for 2026 procurement reviews.
Competitive landscape — strategic takeaways
The market is shaped by an interplay of legacy incumbents, flash and silicon specialists, and emergent platform innovators. Below are high-level strategic positions derived from company-level analysis; the report contains expanded vendor dossiers and a detailed assessment of partnership opportunities.
-
IBM Corporation — Positioned around enterprise-class systems and research-driven innovation, IBM couples advanced tape and archival capabilities with AI-optimized data-management platforms. IBM’s R&D footprint and enterprise services strength make it a default partner for large-scale, regulated archival initiatives.
-
Hewlett Packard Enterprise (HPE) — HPE’s emphasis on hybrid cloud, all-flash arrays, and software-defined architectures targets scalability for AI workloads. Expect HPE to compete on integrated solutions that blend on-prem performance with cloud-native management.
-
Dell Technologies — Dell’s portfolio, anchored by PowerStore and PowerMax families, is focused on high-performance, AI-driven, hybrid-cloud deployments. Dell remains a go-to for enterprises that need tightly integrated stack performance and broad channel coverage.
-
NetApp — Specializes in unified storage and hybrid cloud data services with a strong story for data mobility and tiering; strategically relevant for organizations prioritizing data lifecycle management across private and public clouds.
-
Pure Storage — A pure-play all-flash vendor with a sustainability and Evergreen subscription ethos; attractive for rapid performance refreshes and operational simplicity.
-
Micron, Samsung, Western Digital, Seagate — These suppliers drive the component-level roadmap (NAND, DRAM, HDD, HAMR, SSD). Their product roadmaps and capacity commitments are the critical upstream levers that influence vendor time-to-market and pricing dynamics.
-
Everspin Technologies — MRAM specialist with practical validation for high-reliability applications; relevant to edge and high-end transactional use cases where endurance and persistence matter.
-
Twist Bioscience, Atlas Data Storage — Pioneers in DNA-based archival storage: their roadmaps and commercialisation advances (including Atlas Eon 100) mark the beginning of a new long-term archival option. These players are best suited for early-adopter pilots focused on ultra-dense, ultra-long-retention use cases.
-
Hitachi Vantara, Huawei — Enterprise-focused platforms with strong data-management capabilities and regionally differentiated market approaches; important to consider in multi-cloud, multinational deployments from a geopolitical and compliance lens.
Recent market developments and practical implications
-
Atlas Data Storage’s partnerships and commercial platform launches (late 2025 into 2026) reduce a portion of the execution risk for DNA archival pilots—making 2026 a viable year for controlled production experiments with clear archival use-cases.
-
Patent activity and product innovations (e.g., TEAMGROUP’s patents, PROMISE Technology’s AI-optimized RAID systems, Everspin’s MRAM validation) indicate an acceleration of both performance and security features; these developments should shorten vendor evaluation cycles for proof-of-concept projects.
-
On the standards and compliance front, ISO/IEC 30134 and updates to ISO 27001—together with IEEE efforts to measure AI’s environmental footprint—are creating new procurement specs. Enterprises that bake these into RFPs today will avoid rework and compliance risk in 2026–2027 deployments.
-
Infrastructure constraints—specifically extended grid connection lead times in key data-center markets—are materially shaping deployment architecture decisions: more buyers are factoring behind-the-meter generation and colocated battery solutions into storage rollouts. The report models the cost and timeline impact of these alternatives.
Actionable 60–90 day playbook for CIOs and procurement leads
-
Reassess capacity forecasts against updated market growth curves and vendor roadmap timelines; prioritize modular purchases that preserve optionality for 2027–2028.
-
Launch targeted pilots for one emerging technology where the business case is clear (e.g., MRAM for endurance-critical workloads or DNA for long-term archival), coupled with measurable KPIs tied to cost-per-TB-equivalent and durability.
-
Embed sustainability and security KPIs (aligned to ISO/IEC 30134 and ISO 27001 expectations) into RFP evaluation matrices to avoid retrofitting solutions post-deployment.
-
Stress-test vendor supply commitments against upstream component constraints and include clear contractual remedies for delayed delivery or quality variances.
-
Update disaster recovery and data-mobility strategies to reflect multi-tier storage economics—ensure that archival tiers are decoupled operationally from hot AI/transactional tiers.
Next steps and how to access the full intelligence
This briefing highlights the strategic contours of the next-generation storage landscape and the near-term choices that will determine competitive advantage in 2026 and beyond. For procurement-ready figures, regional and application splits, detailed vendor scorecards, customizable TCO models, and RFP templates, access the full PW Consulting Worldwide Next-Generation Data Storage Market report. The report is designed to be operational: download the complete dataset and playbooks to accelerate 2026 execution, or contact our advisory team to commission a tailored vendor shortlisting and procurement strategy workshop.
For detailed analysis of this topic, please visit the official page: Worldwide Next-Generation Data Storage Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Modified Polyurethane Dispersion Market to Reach USD 2,646.81 Million by 2032, Driven by a 6.98% CAGR
By pmarketresearch, 2026-08-18
PW Consulting Releases Strategic Preview: Worldwide Modified Polyurethane Dispersion Market — Essential Guidance for 2026 Decision-Makers
PW Consulting today publishes a strategic preview of our forthcoming Worldwide Modified Polyurethane Dispersion (PUD) Market report, providing a targeted briefing for executive teams preparing 2026 budgets, procurement strategies, and growth initiatives. Built on a transparent methodology and actionable intelligence, the report synthesizes historical performance (2020–2025), establishes 2025 as the analytical base year, and delivers a scenario-based forecast for 2026–2032. The market is projected to grow at a compound annual growth rate (CAGR) of 6.98% over the forecast period, expanding from a 2025 base to reach a materially larger market by 2032 — a trajectory that demands concrete operational responses from manufacturers, formulators, and buyers alike.
Worldwide LIMS Software Market
Why this report matters for 2026 strategy
-
Timing: 2026 is a pivot year. After several years of raw-material volatility, capacity additions, and regulatory tightening, the market is moving from stabilization into differentiated growth. The report pinpoints tactical windows for commercial action during this transition.
Worldwide Automatic Voltage Regulator (AVR) Market -
Cost and margin pressure: Upstream cost shocks — notably recent isocyanate pricing movements and supplier price adjustments — are forcing manufacturers and OEMs to revisit pricing, sourcing, and formula optimization. Our analysis links MDI/TDI cost signals to downstream margin sensitivity and highlights pass-through mechanics that are practical for procurement teams.
Residential Concierge Software Market -
Regulatory acceleration: Stricter VOC standards and evolving paint/coatings regulations in major markets continue to accelerate adoption of waterborne, modified PUD systems. The report maps regulatory thresholds to product development requirements and compliance pathways, crucial for 2026 product roadmaps.
Key macro view — market trajectory you can act on
Our model shows a clear recovery and steady expansion after 2025: following multi-year growth from 2020 through 2025, the global modified PUD market is forecast to grow at c.7% CAGR during 2026–2032. This macro momentum is driven by a combination of regulatory substitution away from solvent systems, accelerated demand in selected end-use categories, and targeted capacity investments by major chemical producers. PW Consulting’s scenario set translates this macro trajectory into three operational pathways — base, upside, and downside — each tied to concrete triggers such as raw-material pricing normalization, regulatory rollouts, and adoption rates for next-generation chemistries.
What the report contains — practical, decision-ready analysis
We designed the report to serve as an execution toolkit for senior leaders. Highlights include:
-
Actionable market sizing and forecast models (global and by major markets) with sensitivity levers that procurement, commercial, and strategy teams can plug into their internal planning tools.
-
Cost-to-serve and pass-through playbooks that translate upstream price moves into distributor and OEM margin outcomes under multiple contractual models.
-
Technology and product roadmaps comparing modified chemistries (acrylic, silicone, epoxy and other modification approaches) on performance, unit cost, and regulatory fit for prioritized applications.
-
Regulatory matrix and compliance checklists for key jurisdictions, including pragmatic timelines and certification requirements to support go-to-market plans.
-
Supplier scorecards and fit-for-purpose procurement strategies (dual-sourcing templates, tolling vs. finished goods economics, and regional inventory playbooks).
-
M&A & partnership playbook: transaction priorities, integration risks, and valuation benchmarks tailored to players in waterborne resin value chains.
-
Executive dashboards and raw data appendices for in-house analysis — we intentionally withhold detailed segment-level data from public previews to preserve client value, while providing straight-path access for licensed users.
Competitive landscape — how market leaders are positioning
The modified PUD space displays moderate concentration, with the top three and top five suppliers collectively commanding meaningful shares, a dynamic reflected in our concentration metrics. This structure creates an industry where scale and integrated supply advantages coexist with pockets of premium differentiation — especially around low-VOC, shear-stable, and bio-renewable formulations.
-
Covestro AG — Covestro’s waterborne polyurethane portfolio and Baybond line target fiber sizing, coatings, and high-performance use cases with an emphasis on low-VOC and shear-stable chemistries. Their positioning is suited to customers prioritizing application performance and regulatory compliance.
-
BASF SE — A vertically integrated player, BASF is actively tuning its dispersion capacity footprint and pricing strategy in response to upstream cost pressures. Recent site expansions to better serve architectural and construction demand signal a deliberate push into low-CO2, low-VOC dispersions — an important consideration for partners locking long-term supply arrangements.
-
The Lubrizol Corporation — Lubrizol’s emphasis on high-performance and bio-based oil-modified grades positions it well for sustainable wood coatings and abrasion-resistant applications; their technical sales model supports premium placement in value-chain segments.
-
Wanhua Chemical Group — Large-scale capacity additions in recent years increase Wanhua’s influence in waterborne resins. For global buyers, this translates to an alternative source for aliphatic-modified PUDs that balances cost and performance.
-
Specialized and regional players — Firms such as Alberdingk Boley, UBE, Mitsui’s Anderson Development, Incorez, Perstorp, Hauthaway, Essential Polymers, Stahl, and NANPAO each bring differentiated technical capabilities, regional customer relationships, or niche formulations that matter when technical fit and service levels outweigh commodity pricing. Our supplier heatmaps rank these providers across capability, capacity, and commercial flexibility.
Recent industry movements — including upstream price adjustments by major suppliers and targeted capacity builds — are shaping commercial leverage for 2026. PW Consulting’s report decodes these events into near-term tactical steps and medium-term strategic moves.
Market dynamics and a 2026 playbook
-
Procurement & supply continuity: Implement layered sourcing with a primary supplier capable of scale, a secondary specialized supplier for high-performance grades, and a tactical tolling or contract-manufacture partner to manage spot volatility. Where contracts permit, build raw-material indexation clauses to cushion margin erosion.
-
Product strategy: Prioritize low-VOC and mass-balance enabled offerings with clear substitution narratives for solvent systems. Invest in application-centric R&D (e.g., mar and scratch resistance, adhesion to new substrates) to capture premium spread.
-
CapEx & manufacturing footprint: Reassess planned investments against the backdrop of announced capacity expansions in waterborne resins. For mid-size players, consider co-location, contract production, or asset-light partnerships rather than greenfield builds in high-cost regions.
-
Pricing and commercial models: Use differentiated pricing tiers aligned to formulation complexity, certification, and service. Embrace value-based selling for high-performance grades while protecting commodity margins through optimized logistics and formulation cost-outs.
-
M&A & alliances: Sophisticated investors will find opportunities in vertical strengthening (building downstream formulation capabilities) and bolt-on tech plays (bio-based modifiers, additive packages). Our report provides deal screening criteria and target shortlists mapped to strategic objectives.
Data, methodology, and next steps
PW Consulting’s analysis uses 2025 as the base year, with a historical window covering 2020–2025 and a forecast horizon of 2026–2032. All values are reported in USD (Million) and the central forecast CAGR for the period is 6.98%. Concentration metrics and supplier analyses are included to help users judge competitive intensity and negotiation posture. The full report contains granular models, downloadable data tables, and customizable dashboards; this preview preserves the high-level implications while directing practitioners to the source for the complete dataset and segment-level numbers.
To access the full dataset, company scorecards, and the downloadable decision-support workbook — or to schedule a tailored executive briefing that translates these insights into a 90-day implementation plan — please visit the PW Consulting report page or contact our industry practice.
PW Consulting: we turn market signals into operational advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Modified Polyurethane Dispersion Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Flexible IBCs Market to Expand from USD 6.2B in 2025 to USD 9.42B by 2032 at a 6.15% CAGR — Asia‑Pacific Leads with USD 2.48B; Chemicals and U‑Panel Bags Top Segments
By pmarketresearch, 2026-08-18
Worldwide Flexible Intermediate Bulk Containers Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting’s latest market intelligence release on the Worldwide Flexible Intermediate Bulk Containers (FIBC) market is designed as a strategic playbook for organizations making high‑stakes decisions in 2026. Our independent analysis shows the global FIBC market reached approximately USD 6.2 billion in 2025 and is positioned to expand steadily from the 2026 base to an estimated USD 9.4 billion by 2032, reflecting a compound annual growth rate (CAGR) of 6.15% over the 2026–2032 forecast window. This briefing summarizes the report’s strategic value, highlights the operational levers that will matter most next year, and outlines the practical decision tools embedded in the full study. For full datasets, interactive models and downloadable templates, readers are encouraged to consult the full report on our website.
Worldwide Fire Retardant Additives Market
Why this report matters in 2026
-
Market trajectory meets operational complexity: an expanding market with mid‑single digit CAGR presents both strategic growth opportunities and significant execution risks tied to raw materials, regulation and supply network design.
Worldwide Integrated Pest Management Pheromones Market -
Material and regulatory shocks are no longer hypothetical: procurement and product teams must reconcile higher polymer volatility and incoming regulatory regimes with short product lifecycles and rising customer sustainability expectations.
Oxidation Ditch System Market -
Fragmented supplier landscape: the sector remains structurally fragmented, which creates options for buyers to negotiate on service and circularity rather than pure price, while giving strategic acquirers attractive consolidation targets.
Key market dynamics and implications
-
Demand fundamentals: Growth is being driven by continued industrial activity across chemicals, food & pharma, construction and agricultural segments, alongside rising adoption of customized, higher‑specification bags (e.g., aseptic liners, Type C/D electrical protection and baffle designs). While segments perform unevenly, the overall market expansion offers predictable volume growth for suppliers that can capture service and product differentiation.
-
Raw material dependency and cost pressure: FIBCs are predominantly produced from woven polypropylene — a single feedstock that accounts for the majority of volume. Polypropylene price volatility has moved from a sporadic concern to a strategic risk factor; purchasers and manufacturers should model scenarios for prolonged price elevation and build hedging or pass‑through mechanisms into contracts.
-
Regulatory inflection points create winners and losers: The EU Packaging and Packaging Waste Regulation (PPWR) and similar policy initiatives are changing economics for traditional plastics packaging by linking extended producer responsibility (EPR) fees to recyclability and recycled content. Compliance will require investments in traceability, design‑for‑recycling, and reporting capability — and will materially affect sourcing choices in 2026.
-
Circular economy as competitive advantage: A small but growing cohort of suppliers is moving beyond product sales to circular services — reconditioning, closed‑loop takeback and rPET manufacturing. Recent industry moves show large suppliers delivering reconditioning services at scale and new entrants commissioning rPET capacity. These capabilities are proving to be a differentiator in procurement dialogs where both cost and sustainability performance matter.
Competitive landscape — strategic themes, not scorecards
The market comprises a mix of global industrial packaging groups, regional specialists and focused FIBC manufacturers. Leading industrial packaging companies emphasize end‑to‑end solutions (aseptic liners, standardized quality systems, and circular service programs), while small and medium manufacturers compete on responsiveness, customization and local cost structures. Rather than attempting to list share by geography or application here, the most actionable takeaways are structural:
-
Scale + service wins: Large producers leverage global footprints and value‑added services (e.g., on‑demand inventory, reconditioning networks and food‑grade certifications) to capture higher margin segments.
-
Specialists capture niche economics: High‑quality weavers and regional producers continue to command business where rapid turn, customization or local compliance matters.
-
Innovation is bifurcated: technological/product innovation (e.g., enhanced aseptic liners, multilayer designs) sits alongside material innovation (e.g., rPET and recycled polypropylene). Successful suppliers combine both to respond to procurement requirements influenced by EPR and sustainability procurement policies.
Illustrative recent developments underscore these themes. A major global producer announced product launches targeting aseptic and pharma applications while simultaneously reporting millions of containers reconditioned under a circularity program. Parallel moves include new rPET plant commissioning and launches of 100% rPET FIBCs claiming significant lifecycle carbon reductions. Together these initiatives show how incumbents and new entrants are aligning product and service innovations to shifting buyer preferences and regulatory pressure.
What the PW Consulting report delivers — practical, actionable content
Designed for commercial leaders, procurement teams, investors and R&D officers, the full report delivers a set of hands‑on tools and analyses intended to accelerate 2026 decision cycles without requiring months of internal modeling. Key deliverables include:
-
Proprietary market model (2020–2032): dynamic, downloadable spreadsheet with top‑level market size, growth scenarios and sensitivity levers so clients can stress test assumptions against polymer price, regulatory costs and demand shocks.
-
Scenario playbooks: three 2026‑ready pathways (base, accelerated circular adoption, and high‑input price stress) with operational actions, capex timelines and P&L impact illustrations.
-
Supplier scoring and negotiation toolkit: templates and weighted scorecards for evaluating suppliers across service, sustainability, price volatility exposure and compliance readiness.
-
Regulatory impact matrix: concise, region‑aware implications of PPWR‑style rules and EPR fee structures mapped to product design and procurement clauses.
-
Sustainability and LCA toolkit: guidance on measuring recycled content, estimating cradle‑to‑gate carbon impacts and a simple ROI calculator for rPET versus virgin resin investments.
-
Commercial due‑diligence and M&A map: assessment criteria for identifying and valuing bolt‑on targets in low‑cost regions, plus integration playbooks focused on quality control and regulatory harmonization.
-
Case studies and implementation checklists: real‑world examples of reconditioning programs, on‑demand inventory roll‑outs and product migrations to higher‑specification bags with timeline and cost benchmarks.
Direct 2026 actions — recommended playbook
-
Procurement: shift from spot buying to layered procurement strategies — mix index‑linked contracts, shorter tactical purchases and strategic long‑term agreements with recyclate supply commitments.
-
Product and sustainability teams: pilot recycled content initiatives with clear KPIs and third‑party verification; prioritize modular designs that enable reconditioning and reuse.
-
Operations and supply chain: conduct a rapid supplier resilience audit (60–90 days) and develop contingency plans for elevated polypropylene costs and logistics disruption; include tariff exposure checks for import categories.
-
Investors and corporate development: target acquisition pipelines that add either circular capability (reconditioning, rPET feedstock) or complementary geographies; valuation should reflect likely margin benefits from service monetization and regulatory positioning.
-
Regulatory & compliance teams: implement traceability and reporting upgrades ahead of enforcement dates for EPR‑style regimes and build supplier documentation requirements into purchase orders.
How PW Consulting’s analysis reduces execution risk
Our report is intentionally engineered as a decision‑support package: the market model ties demand to discrete operational levers; the scenario playbooks convert regulatory and raw material uncertainties into portfolio‑level actions; and supplier scorecards allow procurement to move beyond lowest‑price sourcing. Collectively, these resources shorten the time between insight and action, enabling organizations to lock in 2026 strategies with quantifiable risk‑reward tradeoffs.
Next steps and how to access the full report
This public briefing is a strategic preview: it outlines the trends, risks and recommended responses that should be central to any 2026 planning cycle involving FIBCs. For corporate teams planning capital allocation, procurement changes, product launches or M&A in 2026, the full report provides the datasets, interactive models and operational templates required to move from strategy to execution.
To explore the complete market model, segmented forecasts, company profiles, and downloadable playbooks, please visit the PW Consulting report page for the Worldwide Flexible Intermediate Bulk Containers Market. Our analysts are available for tailored briefings and scenario workshops to help translate these insights into a 90‑day operational roadmap.
For detailed analysis of this topic, please visit the official page: Worldwide Flexible Intermediate Bulk Containers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting report: Worldwide Flexible Microporous Insulation Panel market to expand at a 4.52% CAGR during 2026–2032
By pmarketresearch, 2026-08-18
Worldwide Flexible Microporous Insulation Panel Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s new market study on the Worldwide Flexible Microporous Insulation Panel market is released as organizations recalibrate thermal-insulation strategies for an environment of higher raw-material volatility, differentiated product innovation, and tightened capital allocation. This briefing provides senior executives, corporate strategists, and investment teams an executive-level synthesis of the report’s strategic value — enough to orient 2026 planning — while preserving the detailed segment-level intelligence that resides in the full report.
Worldwide Metal Diaphragm Compressor Market
Market snapshot: growth trajectory and what it implies for 2026
The flexible microporous insulation panel market has demonstrated steady expansion through the early 2020s: from a mid-single‑hundreds million USD base in 2020 it rose to approximately USD 172.5 Million in our base year (2025). Our forecast period (2026–2032) embeds a compound annual growth rate (CAGR) of 4.52%, taking the market towards the high‑hundreds of millions by the end of 2032. That growth profile reflects a mix of steady industrial demand, accelerating adoption in specialized end‑markets (notably high-temperature industrial and aerospace segments), and improving manufacturability of higher-performance formulations.
Industrial Paper Shredder Market
For corporate leaders planning 2026 budgets, this dynamic signals two immediate priorities: (1) treat microporous panels as a strategic components category — not a commoditized consumable — and (2) reconcile near-term margin pressure from raw-material fluctuations with medium-term product premiumization opportunities. The full report supplies the granular scenario sensitivities that translate this macro CAGR into revenue and margin forecasts by strategic option.
Worldwide URL Shortener Market
Why this market matters now: three strategic inflection points for 2026
- Raw-material cost volatility — The value chain is being reshaped by materials price moves that directly impact production economics. Notable movements in fumed silica pricing and increases in key silane precursors (such as MTMS and TEOS) materially change input cost assumptions for silica‑dominated formulations. Opacifier supply-side constraints and price uplifts — driven by shifts in mineral flows — further complicate sourcing and product cost curves.
- Product differentiation and end‑market pull — Performance characteristics (thermal conductivity at thin cross-sections, mechanical flexibility, vibration resistance) are driving premiumization, particularly where mass, volume, and thermal budgets are critical (e.g., aerospace, high‑efficiency industrial heaters). Manufacturers that can industrialize higher-performance variants or tailor-fit solutions are positioned to capture disproportionate margin uplift.
- Concentration and competitive positioning — Market concentration shows a mid-range oligopolistic structure; a small set of specialized producers controls a significant share of supply, while a diverse set of regional players competes on cost, customization, and channel relationships. This structural reality makes strategic partnerships, selective capacity expansion, and targeted M&A viable levers in 2026.
Material and supply-chain dynamics: what the report clarifies for procurement and R&D
The report dedicates a substantive module to material science and input economics. Key takeaways relevant to 2026 planning include:
- Fumed silica remains the cornerstone of most microporous formulations. Price levels have been elevated and volatile; during the 2025–2026 window spot prices tracked in a band that meaningfully raises cost-of-goods for silica‑dominant products. Procurement teams must model multi‑scenario price ramps and design hedging or long‑term contracting strategies accordingly.
- Opacifiers and specialty additives are a second order driver of cost and performance. Recent supply disruptions and price upticks in zirconium‑silicate opacifiers — driven by changes in regional mineral exports — increase the importance of alternative opacifier qualification and localized second‑source strategies.
- Silane precursors used in gel systems have seen upward price pressure, which reweights the tradeoff between higher‑performance chemistries and cost parity. R&D roadmaps that prioritize raw‑material efficiency, recyclable formulations, and simplified processing stand to shorten the payback on premium products.
In short: procurement, manufacturing, and R&D leaders should treat input-cost scenarios as a core determinant of product strategy in 2026 rather than a peripheral risk.
Competitive landscape: mapped for action
The market is served by a mix of longstanding specialty-material multinationals and regional manufacturers that supply niche and cost‑sensitive demand. Our competitive analysis synthesizes product portfolios, technical differentiators, channel footprints, and manufacturing footprints for the leading participants. Representative companies profiled include:
- Promat (Etex Group) — known for a diversified MICROTHERM® family that spans slit/slatted, overstitched, and aerogel‑enhanced flexible panels for industrial and aerospace applications.
- Morgan Advanced Materials — with advanced composite and VIP cores in its Min‑K® and related systems, focused on aerospace and high‑performance industrial niches.
- Several China‑based producers (manufacturer examples include Firebird Refractories, North Refractories, Luyang, Nanovix, and others) — offering competitive regional manufacturing, customization, and a growing export orientation.
- US and India players (e.g., ThermoDyne, Wedge Industries) — serving local industrial and specialized sectors where service, speed, and cost competitiveness matter.
The report’s competitor profiles go beyond catalog descriptions: we map technology roadmaps, production capacities, product margins, recent investments, and strategic intent indicators (e.g., channel expansion, co‑development agreements). That intelligence enables acquirers and incumbents to prioritize targets for partnerships, bolt‑on M&A, or technology licensing in 2026.
What the full report contains (practical, operational modules)
PW Consulting’s study is structured as an operational playbook for executives making 2026 decisions. Without divulging the granular segmentation tables that our clients use for transaction and procurement diligence, the report includes actionable modules such as:
- Market sizing and five‑case demand scenarios (base, upside, downside, disruption, and rapid‑adoption) driven by macro‑industrial indicators and end‑market adoption curves.
- Detailed supplier and cost modeling templates that translate raw‑material price moves into product-level margin impacts under multiple capacity-utilization scenarios.
- Technology maturity maps that rank formulations and processing routes by readiness, capital intensity, and expected lifecycle TCO benefits for customers.
- Go‑to‑market archetypes and channel economics for OEMs, distributors, and system integrators — including recommended pricing strategies for premium vs. commodity segments.
- Decision frameworks for capital allocation — including a prioritized list of capability investments (quality control automation, opacifier qualification labs, VIP integration cells) and M&A screening criteria.
- Operational checklists for qualification and certification protocols in safety‑critical end‑markets such as aerospace and power generation.
Strategic recommendations for 2026 (executive checklist)
- Adopt a dual‑track procurement strategy: secure multi‑year supply on critical silica and opacifier inputs while qualifying lower‑cost/same‑performance alternatives to mitigate single‑sourcing risk.
- Prioritize product lines with defensible technical differentiation — thin‑section, high‑temperature stability, or vibration resilience — where customers pay a premium and switching costs rise.
- Use targeted M&A or joint ventures to acquire niche capability (e.g., VIP cores or aerogel integration) rather than broad capacity expansion; the latter risks commoditization under price pressure.
- Invest in cost-to-serve analytics for regional markets: compute landed cost breakevens at different raw‑material scenarios to steer channel investments and localized production decisions.
- Embed raw‑material scenario modeling in quarterly planning: the 2025–2026 episode shows price shocks can shift product-level economics within months.
How corporate users and investors should use this briefing
This preview is designed to translate market-level indicators — an established base in 2025 and a moderate mid‑single‑digit CAGR into 2032 — into the strategic choices firms face in 2026. For executives, the report functions as both a decision-support workbook and a diligence dossier: it enables fast, defensible choices on procurement contracts, R&D prioritization, channel strategy, and M&A screening.
Investors will find the competitive-profiles and concentration analysis particularly useful for triaging targets; strategic acquirers will benefit from the value‑capture frameworks that quantify synergy potential from technology consolidation, footprint rationalization, and aftermarket capture.
Next step: where to access the full intelligence
This article highlights the principal market drivers and PW Consulting’s strategic prescriptions for 2026. The full research release contains the proprietary segment-level demand matrices, pricing‑sensitivity tables, regional go‑to‑market breakouts, and vendor benchmarking that are indispensable to transactional and operational planning. For access to the complete dataset, interactive models, and supplier playbooks, please visit the report landing page referenced in PW Consulting’s release distribution.
PW Consulting remains available to conduct bespoke scenario workshops, M&A screening, or supplier sourcing optimization projects that leverage the report’s underlying models and primary‑research interviews.
For detailed analysis of this topic, please visit the official page: Worldwide Flexible Microporous Insulation Panel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Cruet Market to Expand at a 4.92% CAGR During 2026–2032
By pmarketresearch, 2026-08-18
PW Consulting: Worldwide Cruet Market — Strategic Preview for 2026 Corporate Decision-Making
Executive snapshot
As companies prepare budgets and strategic plans for 2026, the worldwide cruet market presents a mix of steady expansion, cost-side volatility and clear differentiation opportunities. Our new market model — which uses 2025 as the base year and covers historical performance from 2020–2025 with a forward-looking forecast through 2032 — shows a market that moved from the high hundreds of millions in 2020 to an estimated USD 858.0 Million in 2025 and is projected to reach approximately USD 1,200.9 Million by 2032. The forecast horizon (2026–2032) is driven by a compounded annual growth rate of 4.92% and a set of structural dynamics that should inform procurement, product, channel and M&A decisions for the coming planning cycle.
Standalone Solar Water Pump Controller Market
Why this matters for 2026 planning
-
Predictable top-line expansion coupled with input-cost risk: the market’s steady CAGR masks material cost tailwinds and regulatory shocks that will disproportionately affect players with exposed supply chains.
Worldwide Condenser Lens Market -
Fragmented competitive structure: market concentration metrics indicate a fragmented field, creating both room for niche premium players and incentives for scale-focused consolidation strategies.
Concrete Vibrating Tamper Market -
Fast-moving regulatory and sustainability drivers: emerging carbon border measures and rising recycled content expectations are reshaping sourcing and manufacturing economics now — not later.
Key dynamics shaping 2026 strategic choices
-
Raw material volatility. Glass-based cruets remain cost- and energy-intensive to produce. Upstream inputs such as soda ash and silica sand experienced notable price appreciation into 2025, and soda ash alone is projected to represent a multibillion-dollar market by 2026, driven in large part by glass manufacturing demand. These swings create material-cost sensitivity for glass-reliant portfolios and favor tactics that reduce exposure — e.g., increased cullet usage, long-term offtake and supplier hedges.
-
Carbon and trade policy friction. Implementation of mechanisms like the EU’s carbon-adjustment rules introduces a new layer of landed-cost risk for imported high-carbon glass products. Organizations that rely on cross-border glass flows should expect tariffs and adjustment levies to influence sourcing decisions, accelerate nearshoring, or prompt investment in lower-carbon furnaces.
-
Sustainability as a design and cost lever. Modern plants are already incorporating recycled glass (cullet) at meaningful rates to achieve both energy and cost reductions. Manufacturers that can commercialize higher-cullet content cruets without compromising clarity and durability will unlock margin and regulatory advantages.
-
Channel bifurcation and premiumization. Tabletop presentation and foodservice demand are diverging: premium, design-led offerings coexist with highly cost-optimized foodservice sets. This bifurcation rewards portfolio segmentation, differentiated packaging and channel-specific go-to-market plays.
What the report delivers — practical tools, not just theory
PW Consulting’s Worldwide Cruet Market report is built for decision-makers. Beyond headline sizing and growth curves, the deliverables include:
-
Methodology and reproducible market models covering 2020–2032; downloadable assumptions for scenario analysis.
-
Product and material cost model that isolates raw-material, energy and labor drivers for glass, ceramic, stainless steel and alternative formulations.
-
Regulatory impact simulations including CBAM-style tariff scenarios and their effect on landed cost across common manufacturing footprints.
-
Supplier risk heatmaps and procurement playbooks (including cullet aggregation strategies, strategic hedging approaches and contractual templates for long-lead inputs).
-
Channel playbooks and margin-to-volume optimization frameworks for retail, foodservice and e-commerce distribution.
-
SKU rationalization tools and a product-differentiation matrix to balance premiumization against unit-cost pressure.
-
Commercial scenarios and an M&A decision tree highlighting where scale, brand or vertical integration add value.
-
Benchmarked case studies and competitive intelligence profiles on leading producers, designers and foodservice suppliers.
Competitive landscape — practical implications for 2026 strategy
The cruet market blends heritage glassmakers, tabletop design houses, foodservice suppliers and value-oriented distributors. That diversity explains the low-to-moderate concentration levels and the variety of routes to growth.
-
Bormioli Rocco — European glass heritage and broad tableware assortment provide a platform for premiumization and design-led line extensions. Strategy consideration: leverage brand and technical glass know-how to introduce higher-cullet, lower-carbon SKUs that retain premium finishes.
-
Libbey — strong foodservice positioning and multi-piece service offering; attractive for operators seeking standardized tabletop solutions. Strategy consideration: emphasize system solutions for hospitality that bundle durability, hygiene and reorder simplicity.
-
Anchor Hocking — premium tabletop presence in North American markets. Strategy consideration: build co-branded hospitality programs and limited-edition collections that command premium price points.
-
Tablecraft — distribution and catalog strength with frequent product refreshes; demonstrates how breadth and catalog cadence can win institutional buyers. Strategy consideration: exploit catalog leadership to accelerate new pourer technologies and streamline cross-sell with complementary tabletop items.
-
Winco — value-focused product range for foodservice; a natural partner for private-label programs. Strategy consideration: operational excellence and scale in cost control create opportunities to capture price-sensitive contract business during periods of input-price pressure.
-
Bodum — engineering focus on pour precision and anti-drip design; appeals to retail and DTC consumers. Strategy consideration: defend margin through design IP and premium after-sale services.
-
Mepra — design-led stainless/glass combinations showcased at major trade markets, signaling the ongoing premium-design opportunity. Strategy consideration: collaboration with design houses and hospitality partners to pilot high-margin, limited-run assortments.
-
Villeroy & Boch — porcelain and decorative design capability that enables cross-category bundling in premium tabletop segments. Strategy consideration: use lifestyle positioning to capture gift and specialty retail channels.
Across these players, the underlying strategic choices for 2026 converge on three themes: cost resilience, product differentiation, and channel-specific commercialization. The market’s fragmentation means regional or channel-focused advantages remain viable alternatives to broadscale roll-ups — but consolidation will intensify around distribution and procurement scale.
Recommended 2026 playbook — immediate actions
-
Execute a 90-day supplier stress test: map exposure to soda ash and silica, validate cullet access, and sign at least one medium-term procurement agreement to limit spot-price exposure.
-
Run a CBAM-scenario impact analysis on every import lane: quantify tariff and documentation costs and prepare alternative nearshoring or tolling scenarios for 2026 procurement cycles.
-
Prioritize SKU rationalization in foodservice channels to reduce working-capital and simplify replacements; concurrently pilot premium, high-margin SKUs in hospitality and DTC.
-
Invest in product-level carbon accounting and create EPD-ready specification sheets for key SKUs to support both compliance and commercial differentiation.
-
Test DTC and subscription channels for design-led cruets with embedded education on quality and care; use digital A/B testing to refine price elasticity before broad roll-out.
-
Identify 2–3 strategic M&A or partnership targets that would provide cullet aggregation, distribution scale or premium brand equity.
Near-term signals to monitor
-
Sustained raw material price moves or supply interruptions in soda ash and silica.
-
Published enforcement guidance and tariff schedules from carbon-adjustment authorities.
-
Trade-show traction for premium designer cruets and new pourer technologies (recent examples include award finalists and high-profile product exhibitions).
-
Catalog and procurement cycles in the foodservice sector, which can rapidly shift reorder patterns after major catalog updates.
Concluding perspective
For executives building 2026 plans, the cruet market reads as a classic product-category battleground: modest growth at the top line, meaningful margin volatility driven by inputs and policy, and clear routes to win via design, channel specialization and procurement discipline. PW Consulting’s report translates these strategic implications into executable tools: reproducible models, procurement playbooks, regulatory stress tests and commercialization frameworks tailored to the realities of manufacturers, distributors and retail brands.
Note: this preview intentionally highlights strategic findings and actionable frameworks while omitting granular, segment-level splits and proprietary model outputs. To access the full dataset, downloadable models and in-depth competitive profiles that underpin these conclusions, please consult the PW Consulting Worldwide Cruet Market report page or contact our research team for a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Cruet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Greenhouse Harvest Trolley Market at USD 255.42 Million in 2025 — Europe Leads with USD 105.85M as Market Eyes 6.85% CAGR Through 2032
By pmarketresearch, 2026-08-18
Worldwide Greenhouse Harvest Trolley Market — Strategic Outlook and Action Playbook for 2026
PW Consulting’s latest market study on the Worldwide Greenhouse Harvest Trolley Market synthesizes seven years of historical performance (2020–2025) and an actionable forecast horizon (2026–2032) to deliver decision-grade intelligence for executives planning capital allocation, product strategy, supply chain resilience, and go‑to‑market execution in 2026. Our base-year analysis shows the market at USD 255.42 Million in 2025, following steady expansion since 2020. The market is modelled to grow at a compound annual growth rate (CAGR) of 6.85% over 2026–2032, reaching approximately USD 406.15 Million by 2032 under our base case scenario.
Worldwide Print Fulfillment Software Market
Why this report matters for 2026 planning
- Investment timing and scale: The mid-single-digit CAGR and multi-year runway indicate a market large enough to warrant targeted product/plant investment, but not so consolidated that fast movers cannot materially improve share within 12–24 months. Our modelling isolates inflection points where incremental capex yields outsized ROI versus gradual expansion.
- Product roadmap prioritization: Demand is shifting toward performance, ergonomic design, and automation readiness. Companies must balance investments across electric and automated platforms while preserving lower-cost manual options for certain use-cases. The report maps feature‑level willingness to pay by buyer cohort so R&D and product management can sequence features to maximize early adoption.
- Supply-chain and component focus: Materials (galvanized and powder‑coated steel), hydraulic systems, electric drives, batteries, and safety subsystems are identified as key cost and lead‑time drivers. We provide a supplier-risk heat map and practical mitigations for 2026 procurement cycles.
- Regulatory and workforce compliance: Equipment design and operating procedures must reflect FDA Produce Safety Rule considerations and applicable OSHA requirements. Our compliance checklist reduces time-to-certification and helps avoid costly field retrofits.
- M&A and partnership playbook: With market concentration moderate (CR3 ~32.5%; CR5 ~45.1%), there is room for strategic acquisitions and partnerships to accelerate capability buildout. The report identifies profiles of targets that deliver immediate scale, geographic reach, or technology adjacency.
What the report delivers — practical, executable content
- Comprehensive market model (2020–2032) with monthly and annual scenarios, sensitivity testing and three strategic outlooks (base, downside, upside) tailored for board-level stress testing.
- Buyer segmentation and procurement behaviour frameworks enabling sales teams to design tiered commercial offers (financeable capex, subscription, pay-per-harvest models) that convert trials into fleet purchases.
- Feature‑level economic models that translate product attributes (lift height, payload, automation integration, sanitation features) into TCO and payback periods for grower decision-makers.
- Supply‑chain playbook with alternate sourcing strategies, critical-component monitoring, and a prioritized list of supplier categories to insource or hedge via strategic agreements.
- Regulatory compliance toolkit aligning design, documentation and sanitation processes with relevant produce safety and occupational standards to minimize sales friction and warranty risk.
- Competitive battlecards for market participants, including capability matrices, service model comparisons, and aftermarket strategies to protect installed base revenue.
- Implementation roadmaps and pilot templates for technology adoption (e.g., electrification retrofits, automation pilots, modular pipe-rail integration) with KPIs to measure success within 90–180 days.
Competitive landscape — what winning looks like in 2026
The greenhouse harvest trolley ecosystem is populated by a mix of long-standing niche manufacturers and more recent entrants specializing in modular or automated systems. Market concentration is moderate, leaving meaningful opportunity for both incumbents and fast followers. Below we summarize the strategic positioning of leading suppliers and the commercial tactics that will matter in 2026.
Worldwide Hydronic Manometers Market
- Berg Hortimotive (Netherlands): A recognized pioneer in pipe-rail systems and self-propelled adjustable-height trolleys. Their strength is deep product engineering for high-throughput operations and an installed-services approach that supports long-term contracts. Strategy implication: incumbents with strong installed bases can monetize upgrades and service contracts—competitors should evaluate aftermarket offers or joint service agreements.
- Bogaerts Greenhouse Logistics (Belgium): Focused on hydraulic adjustable-height and specialized tire-based trolleys for facilities without fixed pipe rails. They compete through product breadth and adaptability—an attractive partner for distributors addressing diverse greenhouse footprints.
- PRECIMET H.C.E. (Poland): Offers multi-level, crop‑specific solutions for tomatoes, cucumbers, strawberries and similar crops. Their emphasis on crop application engineering positions them well for growers seeking productivity gains; product differentiation is based on fit-for-crop design.
- Berkvens Greenhouse Mobility (Netherlands): Brings a portfolio that spans pipe-rail trolleys, scissor lifts, and AGVs—useful for adopters aiming to phase into automated logistics. Their integrated approach lowers system integration risk for buyers.
- Richel Group (France): Known for battery-powered harvesting trolleys and locomotive systems; a focus on electrification and fleet-level operations is commercially relevant where decarbonization and TCO pressures are rising.
- Aytekin Greenhouse System (Turkey), Novagric (Spain), Carretillas Amate (Spain), FPHU Maryniaczyk (Poland), Kingpeng (China): These vendors supply robust, cost-efficient, or highly customizable units serving specific regional demand. Their ability to offer galvanized, corrosion-resistant designs and localized service is a competitive lever.
Notable recent market movements include customized electric-hydraulic scissor lift deliveries that illustrate customer demand for integrated safety and efficiency, modular pipe-rail systems enabling automated bench movement, and expanded product catalogues spotlighting manual, electric and hydraulic models. These developments reinforce two trends that will dominate 2026 purchasing decisions: modularity (ease of retrofit and future-proofing) and service-led differentiation.
Worldwide Yard Management Software Market
Market dynamics, risks and scenario variables
- Raw materials and manufacturing cost pressure: Galvanized and powder-coated metals are industry staples because of humidity and corrosion exposure. Fluctuations in steel and surface-treatment costs materially affect margin—our supplier heat map identifies nodes where cost pass-through is feasible.
- Labor productivity and automation: Harvest trolleys materially reduce labor intensity by streamlining movement and enabling safe elevated harvesting. The economics of automation (AGVs, pipe-rail automation) hinge on facility scale and labor cost trajectories; the report models break-even thresholds for different farm profiles.
- Regulation and safety compliance: Equipment must be designed and maintained to minimize biological hazards and meet workplace safety obligations. Non-compliance introduces downtime, recall, or reputational risk; our compliance module provides prioritized remediations and audit-ready documentation templates.
- Supply disruption and component scarcity: Batteries, hydraulic components, and specialized electrical drives can become constraining factors. The report models inventory buffers and alternative architectures to protect delivery promises during 2026 procurement cycles.
- Service and aftermarket economics: As fleets grow, aftermarket service, spare parts, and retrofits represent high-margin, recurring revenue opportunities—critical for sustaining profitability as unit growth follows a measured path.
Practical recommendations for executives planning in 2026
- Segment capex into pilots and scale phases: Begin with modular pilots focusing on electrified, adjustable-height units integrated with sanitation features; validate ROI in 1–2 harvest cycles before committing to fleet rollouts.
- Design products for retrofit and automation readiness: Offer upgrade paths (e.g., sensor mounts, power interfaces) so buyers can adopt automation incrementally, preserving upgrade revenue and minimizing entry friction.
- Hedge supply risk by qualifying dual suppliers for critical components: Prioritize agreements for batteries, drives, and hydraulic assemblies and maintain strategic spares to avoid seasonal delivery failures.
- Monetize service and retrofit: Build subscription or outcome-based maintenance offerings to convert installed base into recurring revenue and to deepen customer relationships.
- Use regulatory compliance as a sales enabler: Leverage audit-ready compliance packages to shorten procurement cycles for larger growers where traceability and sanitation are procurement gates.
- Evaluate M&A selectively: Targets that add geographic reach, automation capabilities, or a differentiated aftermarket platform will accelerate growth more effectively than bolt-on volume plays.
Next steps — access the full intelligence
This briefing highlights the strategic contours PW Consulting expects to shape decisions in 2026, grounded in our full quantitative model and primary/secondary research. The complete report contains detailed segment models, regional and application splits, company share tables, deployment-level TCO templates, and customisable scenario tools designed for boardroom decision-making. To obtain the full report, schedule a tailored executive briefing, or request the data model for financial planning, please visit PW Consulting’s report page or contact our advisory team for a confidential walkthrough.
For detailed analysis of this topic, please visit the official page: Worldwide Greenhouse Harvest Trolley Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Liquid Propylene Glycol Market Valued at USD 5,008.8 Million in 2025, Set to Reach USD 6,825.5 Million by 2032 at a 4.52% CAGR
By pmarketresearch, 2026-08-18
Worldwide Liquid Propylene Glycol Market: Strategic Imperatives for 2026
PW Consulting’s latest market study on the Worldwide Liquid Propylene Glycol market delivers a focused intelligence package for decision-makers preparing for 2026 and beyond. The market reached USD 5,008.83 Million in 2025 and is projected to expand to USD 6,825.45 Million by 2032, equivalent to a compound annual growth rate (CAGR) of approximately 4.52% over the 2026–2032 forecast window. These headline metrics belie a more nuanced landscape: evolving feedstock economics, regulatory interventions, supply-chain fragility, and accelerating demand for sustainable and bio-based glycols are redefining strategic priorities across the value chain.
Arbitrary Wave Function Generator Market
Why this report matters to executives in 2026
- Tactical foresight for procurement and sourcing: Recent supply shocks and coordinated price moves by major producers underscore the need for active procurement playbooks. The report translates macro drivers into procurement triggers and inventory rules of thumb calibrated to the current supply risk environment.
- Regulatory and formulation readiness: New regulatory actions (federal and state-level) are already reshaping permissible use-cases and compliance burden. Our analysis links regulatory scenarios to product portfolios and reformulation pathways.
- Investment and M&A prioritization: With a moderately concentrated supply base (CR3 ≈ 43.15%; CR5 ≈ 59.4%), the study identifies high-impact acquisition and capacity-investment levers that can deliver defensible market positions.
- Sustainability and differentiation strategy: Growing commercial interest in bio-circular and ISCC-certified feedstocks is creating new routes to premium pricing and buyer stickiness — the report maps where these options generate the greatest commercial value.
Market outlook — what the headline numbers mean for strategy
The market’s trajectory from 2020–2025 and the 4.52% forecast CAGR through 2032 reflects steady demand across industrial and specialty end markets, tempered by episodic supply disruptions and policy shifts. In 2026 the market is projected to expand further from the 2025 base (USD 5,008.83 Million), and our scenario analysis models the sensitivity of revenue and margins to feedstock price swings, capacity outages and accelerated substitution into bio-based glycols.
Worldwide Automotive Shark Fin Antenna Market
Key structural forces captured in the report include: feedstock volatility driven by propylene oxide pricing; downstream demand growth in pharmaceutical, cosmetics, and polymer resins; and a parallel rise in regulatory scrutiny of certain glycol-related uses. Together these forces increase the value of a playbook that blends procurement agility, product-differentiation, and regulatory hedging.
Ambient Illuminance Sensors Market
Immediate dynamics that require board-level attention
- Supply shocks and operational risk: The March 2026 fire and subsequent force majeure at a major propylene oxide/propylene glycol producing complex demonstrated how a single-site event can reverberate through global supply. Boards should stress-test continuity plans and evaluate multi-sourcing and tolling options to mitigate single-point-of-failure exposure.
- Upstream price signals: Propylene oxide pricing remains regionally divergent (recent market checks showed material differences across Northeast Asia, Europe and North America). These regional spreads change the calculus for regional procurement, tolling economics, and arbitrage opportunities for integrated producers.
- Producer pricing actions: In early 2026, leading producers implemented price increases in quick succession — a sign of tighter market balances and an opportunity window for competitors to reassess margin capture versus market share strategies.
- Regulatory tightening: Recent U.S. regulatory action under TSCA and state-level bans affecting food uses signal an elevated compliance bar. This is particularly material for manufacturers supplying the food, beverages, and pharmaceutical value chains.
Competitive landscape — how the major players are shaping outcomes
The market is served by a mix of integrated chemicals majors, specialty producers, and bio-based suppliers. Our competitive analysis synthesizes publicly announced capacity moves, certification and sustainability initiatives, and product-positioning strategies to create a practical view of rivalry and partnership opportunities.
- Integrated majors have leaned on feedstock integration and broad product portfolios to defend margins and secure offtake (examples include producers operating integrated propylene oxide/glycol platforms). Their advantages include scale, feedstock access and global distribution networks.
- Specialty and pharma-grade suppliers compete on quality, regulatory track record and customer qualification pipelines. For companies targeting pharmaceutical, personal care and high-purity industrial applications, certification and consistent supply are the differentiators.
- Bio-based entrants are rapidly moving from niche to scalable options by leveraging renewable glycerin feedstocks and ISCC/certification schemes. These players present both competitive pressure and partnership opportunities for incumbents seeking sustainable product lines.
PW Consulting’s profiles of leading companies include an assessment of strategic assets (capacity, certifications, vertical integration), recent commercial actions (price moves, capacity expansions, ISCC certification), and vulnerability analysis under disruption scenarios. We translate those company-level signals into practical guidance for suppliers, buyers, and investors.
Tactical playbook — eight priority actions for 2026
- Dynamic sourcing and inventory layering: Move to a multi-tier stocking strategy that combines safety inventories at critical nodes with short-cycle replenishment and contractual flexibility (force majeure clauses, flex volumes).
- Supplier segmentation and preferred-partner programs: Reclassify suppliers by strategic value (risk, cost-to-qualify, sustainability credentials) and deploy preferred-partner agreements that balance guaranteed volumes with price resets tied to transparent indices.
- Hedge and pricing hygiene: Link customer contracts to transparent cost indices where possible, and consider financial hedging for feedstock exposures in regions with high price volatility.
- Regulatory playbooks and product stewardship: Create “regulatory-ready” product variants and documentation bundles for markets facing tightened controls; accelerate qualification for alternative excipients where regulatory bans are imminent.
- Portfolio pivot to sustainability: Prioritize ISCC or equivalent certification for facilities where payback from premium positioning is achievable; assess tolling or JV routes to secure bio-based feedstocks.
- Capex and partnership prioritization: Use scenario-based NPV to evaluate brownfield debottlenecking versus greenfield investments; favor modular capacity additions and strategic tolling agreements where execution risk is lower.
- R&D and formulation resilience: Invest in formulation workstreams to reduce sensitivity to any single glycol type; accelerate substitution trials and customer co-development to maintain share if regulatory or supply shifts constrain certain uses.
- Scenario-enabled pricing and commercial playbooks: Prepare layered go-to-market strategies that flex price, grade and delivery model by scenario—tight market, balanced, and oversupplied—so sales teams can act decisively as conditions change.
What PW Consulting’s report contains (practical deliverables)
- Market model with topline historicals and forward projections through 2032, including sensitivity and scenario outputs tied to feedstock, capacity and regulatory variables.
- Actionable supplier scorecards and a negotiated-contract clause library designed for procurement teams.
- Regulatory impact matrix linking regional rules and pending legislation to specific product uses and likely timetable for change.
- Competitive profiles of key incumbents with tactical implications for M&A, JV, and tolling strategies.
- Commercial playbooks for sustainability premium capture, including certification pathways and buyer segmentation by sustainability willingness-to-pay.
- Risk register and continuity plans, with prioritized mitigations for the most probable and high-impact disruption scenarios.
To preserve the strategic value of the study while encouraging direct engagement, this release highlights only the headline market size and growth rate and summarizes our practical recommendations. Detailed segment-level tables, regional splits by application and grade, and supplier-specific run-rate analyses are available only in the full report. That granular content is essential for crafting binding commercial terms, precise capital allocation decisions, and procurement KPIs.
How companies should use this research in 2026
- Boards and C-suite: incorporate the scenario outputs into annual planning and capital allocation reviews. Use the risk register to test the resilience of strategic plans.
- Procurement leaders: adopt the supplier segmentation templates and deploy the contractual clause library to harden supply positions.
- Business development and M&A teams: use the competition and capacity analyses to prioritize targets and to size bolt-on investments that materially shift CRx dynamics.
- R&D and regulatory functions: run the regulatory impact matrix alongside internal pipelines to accelerate qualification and to de-risk market access.
Next steps
For organizations that need to convert this high-level intelligence into executable plans for 2026, PW Consulting offers tailored workshops, bespoke scenario runs, and hands-on contract and tender support. To access the full dataset, segment-level analysis, and supplier scorecards, please consult the complete Worldwide Liquid Propylene Glycol Market report or contact our industrial chemicals practice to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Liquid Propylene Glycol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Multivalent Pneumococcal Conjugate Vaccine Market to Expand at an 8.82% CAGR Through 2026–2032
By pmarketresearch, 2026-08-18
Worldwide Multivalent Pneumococcal Conjugate Vaccine Market: Strategic Imperatives for 2026
PW Consulting’s new Worldwide Multivalent Pneumococcal Conjugate Vaccine Market report combines rigorous market modelling, competitive forensics, and executable strategy playbooks to guide executive decision-making in 2026. The global market has moved from a niche, program-driven product class into a high-stakes, innovation-led battleground. Our base-year modelling (2025) pegs the market at USD 11,050.0 Million, with an expected compound annual growth rate (CAGR) of 8.82% across the 2026–2032 forecast window and a projected market approaching USD 19,967.5 Million by 2032. These headline figures conceal rapid churn beneath the surface: new multivalent entrants, shifting national immunization policies, and supply-chain dynamics that will determine winners and losers in the next two to three years.
Industrial Noise Control System Market
Why this report matters for 2026 corporate strategy
CEOs, commercial leads, and R&D chiefs need an evidence-driven, pragmatic road map rather than an academic inventory of products. Our report translates market scale and growth drivers into specific action levers for 2026: portfolio rationalisation, capacity planning, tender and pricing playbooks, regulatory prioritisation, and targeted partnership strategies. We apply scenario stress-testing to quantify the impact of key inflection points — accelerated 20+ valency launches, biosimilar PCV13 entry after patent expiry, and changes in adult immunisation recommendations — so leadership teams can resource the right options and time market entry.
Worldwide Pusher Furnaces Market
Key market characteristics that should shape 2026 choices
- Rapid expansion in headline demand: From a market of approximately USD 7.4 Billion in 2020 to USD 11.05 Billion in 2025, the market is forecast to grow at an ~8.8% CAGR, reflecting both expanded adult indications and continued childhood program uptake.
- High concentration: The top three suppliers collectively account for an overwhelming majority of revenues (CR3 ≈ 92.4%), with the top five expanding that share further (CR5 ≈ 97.1%). This concentration creates both entry barriers and opportunity windows for challengers who can solve supply or price pain points.
- Regulatory and recommendation tailwinds: Updated adult vaccination guidance that includes higher-valency products has immediate implications for adult market dynamics and payer negotiations.
- Supply-chain and manufacturing realities: Complex conjugation technologies, constrained polysaccharide supply and cold-chain dependencies mean capital investment in manufacturing and logistics is a strategic must—not a tactical nice-to-have.
Actionable strategic priorities for 2026
Below are the prioritized decision areas where 2026 moves will most materially affect outcomes through 2032. Each item encapsulates the trade-offs we quantify in the full report.
Automotive Cross-domain Fusion Computing Platform Market
- Portfolio and indication strategy:
Prioritise candidates with differentiated valency and demonstrated immunogenic breadth for both pediatric and adult indications. For incumbent manufacturers, protect core franchise economics by accelerating lifecycle studies and real-world evidence generation; for challengers, define a clear value-proposition (price-performance or supply security) for tender buyers and national programmes.
- Manufacturing scale and vertical integration:
Given the limited supplier base for key conjugation inputs and polysaccharides, invest in capacity expansions or long-term toll-manufacturing agreements. Our scenario models show that delayed capacity investment can create multi-quarter supply shortfalls that compress pricing and market share.
- Cold-chain optimization and logistics:
Cold-chain represents a dominant portion of distribution cost and operational risk. Our synthesis of sector data flags that cold-chain logistics can account for roughly half of distribution costs; temperature excursions can jeopardise a material share of doses in lower-resource settings. For 2026, mitigation tactics such as regional depots, thermal management technologies, and third-party cold-chain partnerships should be elevated in capital plans.
- Market access and pricing tactics:
With many national immunisation programmes mature but still variable in coverage, nuanced tender-execution and differentiated pricing strategies for private vs public channels will be essential. Incorporate indication-based pricing for adult programmes and package performance guarantees for purchasers in emerging markets.
- M&A, alliances and geographic playbooks:
Strategic tie-ups — particularly between innovators and manufacturers with capacity or local market access — will accelerate scale. Our deal scenarios indicate that bolt-on acquisitions of regional manufacturers or capacity-lite manufacturing agreements can deliver faster time-to-market than greenfield builds in many markets.
- Regulatory and clinical development sequencing:
Given recent late-stage readouts and regulatory momentum toward higher-valency approvals, companies should sequence trials to capture pediatric, adolescent, and adult labels efficiently. Early engagement with regulators on immunobridging endpoints and post-marketing commitments reduces approval uncertainty.
Competitive landscape — what to watch in 2026
The market remains dominated by a handful of multinational vaccine leaders, with an expanding roster of regional and specialised challengers. Our competitive profiles identify where incumbents can be pressured and where new entrants can sustainably compete.
- Pfizer Inc. (New York, USA) — Established leader with multivalent offerings across pediatric and adult indications. Patents on older valency products are evolving, and competitive pressure on legacy franchises is a strategic focus.
- Merck & Co., Inc. (MSD) (Rahway, NJ, USA) — Active with higher-valency candidates and adult-focused approvals; recent positive Phase 3 data in adolescent populations has strengthened its adult franchise positioning.
- GlaxoSmithKline plc (London, UK) — Strong presence in pediatric national immunisation programs through established 10-valent offerings; continues to be a strategic partner for programmatic adoption.
- Sanofi (Paris, France) & SK bioscience (Seongnam, South Korea) — Their expanded collaboration and ongoing Phase 3 programs for >20-valency candidates mark them as contenders in the next wave of product competition, supported by capacity expansion investments.
- Large regional producers (e.g., Serum Institute of India, Walvax, various Chinese manufacturers) — Compete on affordability and programme access; improving technical capability is increasing supply diversity and creating competitive pressure on pricing in procurement markets.
- Small innovators (Vaxcyte, Inventprise) — Focused on next-generation valency and novel manufacturing approaches; recent positive early-phase readouts indicate potential for selective premium positioning or acquisition interest from larger players.
Recent developments that change the calculus
- Positive late-stage and dose-finding trial readouts from multiple developers have de-risked higher-valency candidates and accelerated regulatory conversations for adult indications.
- Expanded collaborations and facility investments by strategic producers reflect a shift from proof-of-concept to supply readiness — an essential step given projected demand growth.
- Updated immunisation advisory committee recommendations for adult use of higher-valency vaccines in specific age groups create immediate commercial upside in mature markets and add complexity to global procurement strategies.
- Patent expiries on legacy products will invite biosimilar and generic competition in certain markets; the timing and geographic scope of biogeneric entry will be a core scenario in 2026 planning.
What the PW Consulting report delivers (operational contents)
Our report is designed to be used by strategy teams as a decision-support toolkit, not a descriptive digest. Deliverables include:
- Proprietary market model (2020–2032) with scenario toggles for valency adoption curves, vaccine price trajectories, and supply disruptions.
- Competitive heatmaps and risk-assessment matrices that identify where incumbents are vulnerable and where challengers are advantaged.
- Regulatory and reimbursement playbook outlining accelerated approval pathways, immunobridging recommendations, and payer negotiation strategies tailored to adult vs pediatric markets.
- Manufacturing and supply-chain blueprints, including a supplier capability map, cold-chain cost optimisation levers, and capital investment prioritisation frameworks.
- Commercial execution templates for tendering, tiered pricing, and programmatic adoption to increase win probability in both public and private channels.
- M&A and partnership scoring tools to prioritise targets, estimate synergies, and model integration risks.
How to use these insights in board-level planning for 2026
We recommend boards and C-suite teams run three coordinated initiatives in 2026: (1) a 90-day tactical plan to shore up supply and tender readiness for immediate growth opportunities; (2) a 6–12 month strategic program to accelerate clinical and regulatory milestones for higher-valency candidates; and (3) a capital allocation review that biases toward modular manufacturing and logistics solutions to de-risk distribution. The full report contains executable timelines, investment estimates under multiple scenarios, and governance checklists to convert strategy into measurable outcomes.
Final note — the intelligence gap we close
High-level metrics tell the growth story, but competitive positioning, supply chain nuance, and regulatory sequencing determine who captures value. With a concentrated supplier base, imminent patent expiries, and a wave of higher-valency product launches, 2026 is a pivotal year. PW Consulting’s report converts these dynamics into clear strategic choices and near-term actions so organisations can convert headline growth into sustainable market share.
Next steps
For executives seeking the full data tables, granular scenario outputs, and the proprietary models referenced here, PW Consulting’s comprehensive report and strategy workshop packages are available. Contact our industry team to arrange a briefing and obtain access to the underlying datasets and playbooks that will be decisive for 2026 planning.
For detailed analysis of this topic, please visit the official page: Worldwide Multivalent Pneumococcal Conjugate Vaccine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com