

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting report: Worldwide Flexible Microporous Insulation Panel market to expand at a 4.52% CAGR during 2026–2032

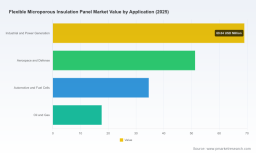
Worldwide Flexible Microporous Insulation Panel Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s new market study on the Worldwide Flexible Microporous Insulation Panel market is released as organizations recalibrate thermal-insulation strategies for an environment of higher raw-material volatility, differentiated product innovation, and tightened capital allocation. This briefing provides senior executives, corporate strategists, and investment teams an executive-level synthesis of the report’s strategic value — enough to orient 2026 planning — while preserving the detailed segment-level intelligence that resides in the full report.
Worldwide Metal Diaphragm Compressor Market
Market snapshot: growth trajectory and what it implies for 2026
The flexible microporous insulation panel market has demonstrated steady expansion through the early 2020s: from a mid-single‑hundreds million USD base in 2020 it rose to approximately USD 172.5 Million in our base year (2025). Our forecast period (2026–2032) embeds a compound annual growth rate (CAGR) of 4.52%, taking the market towards the high‑hundreds of millions by the end of 2032. That growth profile reflects a mix of steady industrial demand, accelerating adoption in specialized end‑markets (notably high-temperature industrial and aerospace segments), and improving manufacturability of higher-performance formulations.
Industrial Paper Shredder Market
For corporate leaders planning 2026 budgets, this dynamic signals two immediate priorities: (1) treat microporous panels as a strategic components category — not a commoditized consumable — and (2) reconcile near-term margin pressure from raw-material fluctuations with medium-term product premiumization opportunities. The full report supplies the granular scenario sensitivities that translate this macro CAGR into revenue and margin forecasts by strategic option.
Worldwide URL Shortener Market
Why this market matters now: three strategic inflection points for 2026
- Raw-material cost volatility — The value chain is being reshaped by materials price moves that directly impact production economics. Notable movements in fumed silica pricing and increases in key silane precursors (such as MTMS and TEOS) materially change input cost assumptions for silica‑dominated formulations. Opacifier supply-side constraints and price uplifts — driven by shifts in mineral flows — further complicate sourcing and product cost curves.
- Product differentiation and end‑market pull — Performance characteristics (thermal conductivity at thin cross-sections, mechanical flexibility, vibration resistance) are driving premiumization, particularly where mass, volume, and thermal budgets are critical (e.g., aerospace, high‑efficiency industrial heaters). Manufacturers that can industrialize higher-performance variants or tailor-fit solutions are positioned to capture disproportionate margin uplift.
- Concentration and competitive positioning — Market concentration shows a mid-range oligopolistic structure; a small set of specialized producers controls a significant share of supply, while a diverse set of regional players competes on cost, customization, and channel relationships. This structural reality makes strategic partnerships, selective capacity expansion, and targeted M&A viable levers in 2026.
Material and supply-chain dynamics: what the report clarifies for procurement and R&D
The report dedicates a substantive module to material science and input economics. Key takeaways relevant to 2026 planning include:
- Fumed silica remains the cornerstone of most microporous formulations. Price levels have been elevated and volatile; during the 2025–2026 window spot prices tracked in a band that meaningfully raises cost-of-goods for silica‑dominant products. Procurement teams must model multi‑scenario price ramps and design hedging or long‑term contracting strategies accordingly.
- Opacifiers and specialty additives are a second order driver of cost and performance. Recent supply disruptions and price upticks in zirconium‑silicate opacifiers — driven by changes in regional mineral exports — increase the importance of alternative opacifier qualification and localized second‑source strategies.
- Silane precursors used in gel systems have seen upward price pressure, which reweights the tradeoff between higher‑performance chemistries and cost parity. R&D roadmaps that prioritize raw‑material efficiency, recyclable formulations, and simplified processing stand to shorten the payback on premium products.
In short: procurement, manufacturing, and R&D leaders should treat input-cost scenarios as a core determinant of product strategy in 2026 rather than a peripheral risk.
Competitive landscape: mapped for action
The market is served by a mix of longstanding specialty-material multinationals and regional manufacturers that supply niche and cost‑sensitive demand. Our competitive analysis synthesizes product portfolios, technical differentiators, channel footprints, and manufacturing footprints for the leading participants. Representative companies profiled include:
- Promat (Etex Group) — known for a diversified MICROTHERM® family that spans slit/slatted, overstitched, and aerogel‑enhanced flexible panels for industrial and aerospace applications.
- Morgan Advanced Materials — with advanced composite and VIP cores in its Min‑K® and related systems, focused on aerospace and high‑performance industrial niches.
- Several China‑based producers (manufacturer examples include Firebird Refractories, North Refractories, Luyang, Nanovix, and others) — offering competitive regional manufacturing, customization, and a growing export orientation.
- US and India players (e.g., ThermoDyne, Wedge Industries) — serving local industrial and specialized sectors where service, speed, and cost competitiveness matter.
The report’s competitor profiles go beyond catalog descriptions: we map technology roadmaps, production capacities, product margins, recent investments, and strategic intent indicators (e.g., channel expansion, co‑development agreements). That intelligence enables acquirers and incumbents to prioritize targets for partnerships, bolt‑on M&A, or technology licensing in 2026.
What the full report contains (practical, operational modules)
PW Consulting’s study is structured as an operational playbook for executives making 2026 decisions. Without divulging the granular segmentation tables that our clients use for transaction and procurement diligence, the report includes actionable modules such as:
- Market sizing and five‑case demand scenarios (base, upside, downside, disruption, and rapid‑adoption) driven by macro‑industrial indicators and end‑market adoption curves.
- Detailed supplier and cost modeling templates that translate raw‑material price moves into product-level margin impacts under multiple capacity-utilization scenarios.
- Technology maturity maps that rank formulations and processing routes by readiness, capital intensity, and expected lifecycle TCO benefits for customers.
- Go‑to‑market archetypes and channel economics for OEMs, distributors, and system integrators — including recommended pricing strategies for premium vs. commodity segments.
- Decision frameworks for capital allocation — including a prioritized list of capability investments (quality control automation, opacifier qualification labs, VIP integration cells) and M&A screening criteria.
- Operational checklists for qualification and certification protocols in safety‑critical end‑markets such as aerospace and power generation.
Strategic recommendations for 2026 (executive checklist)
- Adopt a dual‑track procurement strategy: secure multi‑year supply on critical silica and opacifier inputs while qualifying lower‑cost/same‑performance alternatives to mitigate single‑sourcing risk.
- Prioritize product lines with defensible technical differentiation — thin‑section, high‑temperature stability, or vibration resilience — where customers pay a premium and switching costs rise.
- Use targeted M&A or joint ventures to acquire niche capability (e.g., VIP cores or aerogel integration) rather than broad capacity expansion; the latter risks commoditization under price pressure.
- Invest in cost-to-serve analytics for regional markets: compute landed cost breakevens at different raw‑material scenarios to steer channel investments and localized production decisions.
- Embed raw‑material scenario modeling in quarterly planning: the 2025–2026 episode shows price shocks can shift product-level economics within months.
How corporate users and investors should use this briefing
This preview is designed to translate market-level indicators — an established base in 2025 and a moderate mid‑single‑digit CAGR into 2032 — into the strategic choices firms face in 2026. For executives, the report functions as both a decision-support workbook and a diligence dossier: it enables fast, defensible choices on procurement contracts, R&D prioritization, channel strategy, and M&A screening.
Investors will find the competitive-profiles and concentration analysis particularly useful for triaging targets; strategic acquirers will benefit from the value‑capture frameworks that quantify synergy potential from technology consolidation, footprint rationalization, and aftermarket capture.
Next step: where to access the full intelligence
This article highlights the principal market drivers and PW Consulting’s strategic prescriptions for 2026. The full research release contains the proprietary segment-level demand matrices, pricing‑sensitivity tables, regional go‑to‑market breakouts, and vendor benchmarking that are indispensable to transactional and operational planning. For access to the complete dataset, interactive models, and supplier playbooks, please visit the report landing page referenced in PW Consulting’s release distribution.
PW Consulting remains available to conduct bespoke scenario workshops, M&A screening, or supplier sourcing optimization projects that leverage the report’s underlying models and primary‑research interviews.
For detailed analysis of this topic, please visit the official page: Worldwide Flexible Microporous Insulation Panel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com