

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
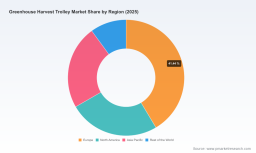
PW Consulting: Worldwide Greenhouse Harvest Trolley Market at USD 255.42 Million in 2025 — Europe Leads with USD 105.85M as Market Eyes 6.85% CAGR Through 2032

Worldwide Greenhouse Harvest Trolley Market — Strategic Outlook and Action Playbook for 2026
PW Consulting’s latest market study on the Worldwide Greenhouse Harvest Trolley Market synthesizes seven years of historical performance (2020–2025) and an actionable forecast horizon (2026–2032) to deliver decision-grade intelligence for executives planning capital allocation, product strategy, supply chain resilience, and go‑to‑market execution in 2026. Our base-year analysis shows the market at USD 255.42 Million in 2025, following steady expansion since 2020. The market is modelled to grow at a compound annual growth rate (CAGR) of 6.85% over 2026–2032, reaching approximately USD 406.15 Million by 2032 under our base case scenario.
Worldwide Print Fulfillment Software Market
Why this report matters for 2026 planning
- Investment timing and scale: The mid-single-digit CAGR and multi-year runway indicate a market large enough to warrant targeted product/plant investment, but not so consolidated that fast movers cannot materially improve share within 12–24 months. Our modelling isolates inflection points where incremental capex yields outsized ROI versus gradual expansion.
- Product roadmap prioritization: Demand is shifting toward performance, ergonomic design, and automation readiness. Companies must balance investments across electric and automated platforms while preserving lower-cost manual options for certain use-cases. The report maps feature‑level willingness to pay by buyer cohort so R&D and product management can sequence features to maximize early adoption.
- Supply-chain and component focus: Materials (galvanized and powder‑coated steel), hydraulic systems, electric drives, batteries, and safety subsystems are identified as key cost and lead‑time drivers. We provide a supplier-risk heat map and practical mitigations for 2026 procurement cycles.
- Regulatory and workforce compliance: Equipment design and operating procedures must reflect FDA Produce Safety Rule considerations and applicable OSHA requirements. Our compliance checklist reduces time-to-certification and helps avoid costly field retrofits.
- M&A and partnership playbook: With market concentration moderate (CR3 ~32.5%; CR5 ~45.1%), there is room for strategic acquisitions and partnerships to accelerate capability buildout. The report identifies profiles of targets that deliver immediate scale, geographic reach, or technology adjacency.
What the report delivers — practical, executable content
- Comprehensive market model (2020–2032) with monthly and annual scenarios, sensitivity testing and three strategic outlooks (base, downside, upside) tailored for board-level stress testing.
- Buyer segmentation and procurement behaviour frameworks enabling sales teams to design tiered commercial offers (financeable capex, subscription, pay-per-harvest models) that convert trials into fleet purchases.
- Feature‑level economic models that translate product attributes (lift height, payload, automation integration, sanitation features) into TCO and payback periods for grower decision-makers.
- Supply‑chain playbook with alternate sourcing strategies, critical-component monitoring, and a prioritized list of supplier categories to insource or hedge via strategic agreements.
- Regulatory compliance toolkit aligning design, documentation and sanitation processes with relevant produce safety and occupational standards to minimize sales friction and warranty risk.
- Competitive battlecards for market participants, including capability matrices, service model comparisons, and aftermarket strategies to protect installed base revenue.
- Implementation roadmaps and pilot templates for technology adoption (e.g., electrification retrofits, automation pilots, modular pipe-rail integration) with KPIs to measure success within 90–180 days.
Competitive landscape — what winning looks like in 2026
The greenhouse harvest trolley ecosystem is populated by a mix of long-standing niche manufacturers and more recent entrants specializing in modular or automated systems. Market concentration is moderate, leaving meaningful opportunity for both incumbents and fast followers. Below we summarize the strategic positioning of leading suppliers and the commercial tactics that will matter in 2026.
Worldwide Hydronic Manometers Market
- Berg Hortimotive (Netherlands): A recognized pioneer in pipe-rail systems and self-propelled adjustable-height trolleys. Their strength is deep product engineering for high-throughput operations and an installed-services approach that supports long-term contracts. Strategy implication: incumbents with strong installed bases can monetize upgrades and service contracts—competitors should evaluate aftermarket offers or joint service agreements.
- Bogaerts Greenhouse Logistics (Belgium): Focused on hydraulic adjustable-height and specialized tire-based trolleys for facilities without fixed pipe rails. They compete through product breadth and adaptability—an attractive partner for distributors addressing diverse greenhouse footprints.
- PRECIMET H.C.E. (Poland): Offers multi-level, crop‑specific solutions for tomatoes, cucumbers, strawberries and similar crops. Their emphasis on crop application engineering positions them well for growers seeking productivity gains; product differentiation is based on fit-for-crop design.
- Berkvens Greenhouse Mobility (Netherlands): Brings a portfolio that spans pipe-rail trolleys, scissor lifts, and AGVs—useful for adopters aiming to phase into automated logistics. Their integrated approach lowers system integration risk for buyers.
- Richel Group (France): Known for battery-powered harvesting trolleys and locomotive systems; a focus on electrification and fleet-level operations is commercially relevant where decarbonization and TCO pressures are rising.
- Aytekin Greenhouse System (Turkey), Novagric (Spain), Carretillas Amate (Spain), FPHU Maryniaczyk (Poland), Kingpeng (China): These vendors supply robust, cost-efficient, or highly customizable units serving specific regional demand. Their ability to offer galvanized, corrosion-resistant designs and localized service is a competitive lever.
Notable recent market movements include customized electric-hydraulic scissor lift deliveries that illustrate customer demand for integrated safety and efficiency, modular pipe-rail systems enabling automated bench movement, and expanded product catalogues spotlighting manual, electric and hydraulic models. These developments reinforce two trends that will dominate 2026 purchasing decisions: modularity (ease of retrofit and future-proofing) and service-led differentiation.
Worldwide Yard Management Software Market
Market dynamics, risks and scenario variables
- Raw materials and manufacturing cost pressure: Galvanized and powder-coated metals are industry staples because of humidity and corrosion exposure. Fluctuations in steel and surface-treatment costs materially affect margin—our supplier heat map identifies nodes where cost pass-through is feasible.
- Labor productivity and automation: Harvest trolleys materially reduce labor intensity by streamlining movement and enabling safe elevated harvesting. The economics of automation (AGVs, pipe-rail automation) hinge on facility scale and labor cost trajectories; the report models break-even thresholds for different farm profiles.
- Regulation and safety compliance: Equipment must be designed and maintained to minimize biological hazards and meet workplace safety obligations. Non-compliance introduces downtime, recall, or reputational risk; our compliance module provides prioritized remediations and audit-ready documentation templates.
- Supply disruption and component scarcity: Batteries, hydraulic components, and specialized electrical drives can become constraining factors. The report models inventory buffers and alternative architectures to protect delivery promises during 2026 procurement cycles.
- Service and aftermarket economics: As fleets grow, aftermarket service, spare parts, and retrofits represent high-margin, recurring revenue opportunities—critical for sustaining profitability as unit growth follows a measured path.
Practical recommendations for executives planning in 2026
- Segment capex into pilots and scale phases: Begin with modular pilots focusing on electrified, adjustable-height units integrated with sanitation features; validate ROI in 1–2 harvest cycles before committing to fleet rollouts.
- Design products for retrofit and automation readiness: Offer upgrade paths (e.g., sensor mounts, power interfaces) so buyers can adopt automation incrementally, preserving upgrade revenue and minimizing entry friction.
- Hedge supply risk by qualifying dual suppliers for critical components: Prioritize agreements for batteries, drives, and hydraulic assemblies and maintain strategic spares to avoid seasonal delivery failures.
- Monetize service and retrofit: Build subscription or outcome-based maintenance offerings to convert installed base into recurring revenue and to deepen customer relationships.
- Use regulatory compliance as a sales enabler: Leverage audit-ready compliance packages to shorten procurement cycles for larger growers where traceability and sanitation are procurement gates.
- Evaluate M&A selectively: Targets that add geographic reach, automation capabilities, or a differentiated aftermarket platform will accelerate growth more effectively than bolt-on volume plays.
Next steps — access the full intelligence
This briefing highlights the strategic contours PW Consulting expects to shape decisions in 2026, grounded in our full quantitative model and primary/secondary research. The complete report contains detailed segment models, regional and application splits, company share tables, deployment-level TCO templates, and customisable scenario tools designed for boardroom decision-making. To obtain the full report, schedule a tailored executive briefing, or request the data model for financial planning, please visit PW Consulting’s report page or contact our advisory team for a confidential walkthrough.
For detailed analysis of this topic, please visit the official page: Worldwide Greenhouse Harvest Trolley Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com