

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Worldwide Modified Polyurethane Dispersion Market to Reach USD 2,646.81 Million by 2032, Driven by a 6.98% CAGR

PW Consulting Releases Strategic Preview: Worldwide Modified Polyurethane Dispersion Market — Essential Guidance for 2026 Decision-Makers
PW Consulting today publishes a strategic preview of our forthcoming Worldwide Modified Polyurethane Dispersion (PUD) Market report, providing a targeted briefing for executive teams preparing 2026 budgets, procurement strategies, and growth initiatives. Built on a transparent methodology and actionable intelligence, the report synthesizes historical performance (2020–2025), establishes 2025 as the analytical base year, and delivers a scenario-based forecast for 2026–2032. The market is projected to grow at a compound annual growth rate (CAGR) of 6.98% over the forecast period, expanding from a 2025 base to reach a materially larger market by 2032 — a trajectory that demands concrete operational responses from manufacturers, formulators, and buyers alike.
Worldwide LIMS Software Market
Why this report matters for 2026 strategy
-
Timing: 2026 is a pivot year. After several years of raw-material volatility, capacity additions, and regulatory tightening, the market is moving from stabilization into differentiated growth. The report pinpoints tactical windows for commercial action during this transition.
Worldwide Automatic Voltage Regulator (AVR) Market -
Cost and margin pressure: Upstream cost shocks — notably recent isocyanate pricing movements and supplier price adjustments — are forcing manufacturers and OEMs to revisit pricing, sourcing, and formula optimization. Our analysis links MDI/TDI cost signals to downstream margin sensitivity and highlights pass-through mechanics that are practical for procurement teams.
Residential Concierge Software Market -
Regulatory acceleration: Stricter VOC standards and evolving paint/coatings regulations in major markets continue to accelerate adoption of waterborne, modified PUD systems. The report maps regulatory thresholds to product development requirements and compliance pathways, crucial for 2026 product roadmaps.
Key macro view — market trajectory you can act on
Our model shows a clear recovery and steady expansion after 2025: following multi-year growth from 2020 through 2025, the global modified PUD market is forecast to grow at c.7% CAGR during 2026–2032. This macro momentum is driven by a combination of regulatory substitution away from solvent systems, accelerated demand in selected end-use categories, and targeted capacity investments by major chemical producers. PW Consulting’s scenario set translates this macro trajectory into three operational pathways — base, upside, and downside — each tied to concrete triggers such as raw-material pricing normalization, regulatory rollouts, and adoption rates for next-generation chemistries.
What the report contains — practical, decision-ready analysis
We designed the report to serve as an execution toolkit for senior leaders. Highlights include:
-
Actionable market sizing and forecast models (global and by major markets) with sensitivity levers that procurement, commercial, and strategy teams can plug into their internal planning tools.
-
Cost-to-serve and pass-through playbooks that translate upstream price moves into distributor and OEM margin outcomes under multiple contractual models.
-
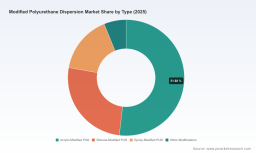
Technology and product roadmaps comparing modified chemistries (acrylic, silicone, epoxy and other modification approaches) on performance, unit cost, and regulatory fit for prioritized applications.
-
Regulatory matrix and compliance checklists for key jurisdictions, including pragmatic timelines and certification requirements to support go-to-market plans.
-
Supplier scorecards and fit-for-purpose procurement strategies (dual-sourcing templates, tolling vs. finished goods economics, and regional inventory playbooks).
-
M&A & partnership playbook: transaction priorities, integration risks, and valuation benchmarks tailored to players in waterborne resin value chains.
-
Executive dashboards and raw data appendices for in-house analysis — we intentionally withhold detailed segment-level data from public previews to preserve client value, while providing straight-path access for licensed users.
Competitive landscape — how market leaders are positioning
The modified PUD space displays moderate concentration, with the top three and top five suppliers collectively commanding meaningful shares, a dynamic reflected in our concentration metrics. This structure creates an industry where scale and integrated supply advantages coexist with pockets of premium differentiation — especially around low-VOC, shear-stable, and bio-renewable formulations.
-
Covestro AG — Covestro’s waterborne polyurethane portfolio and Baybond line target fiber sizing, coatings, and high-performance use cases with an emphasis on low-VOC and shear-stable chemistries. Their positioning is suited to customers prioritizing application performance and regulatory compliance.
-
BASF SE — A vertically integrated player, BASF is actively tuning its dispersion capacity footprint and pricing strategy in response to upstream cost pressures. Recent site expansions to better serve architectural and construction demand signal a deliberate push into low-CO2, low-VOC dispersions — an important consideration for partners locking long-term supply arrangements.
-
The Lubrizol Corporation — Lubrizol’s emphasis on high-performance and bio-based oil-modified grades positions it well for sustainable wood coatings and abrasion-resistant applications; their technical sales model supports premium placement in value-chain segments.
-
Wanhua Chemical Group — Large-scale capacity additions in recent years increase Wanhua’s influence in waterborne resins. For global buyers, this translates to an alternative source for aliphatic-modified PUDs that balances cost and performance.
-
Specialized and regional players — Firms such as Alberdingk Boley, UBE, Mitsui’s Anderson Development, Incorez, Perstorp, Hauthaway, Essential Polymers, Stahl, and NANPAO each bring differentiated technical capabilities, regional customer relationships, or niche formulations that matter when technical fit and service levels outweigh commodity pricing. Our supplier heatmaps rank these providers across capability, capacity, and commercial flexibility.
Recent industry movements — including upstream price adjustments by major suppliers and targeted capacity builds — are shaping commercial leverage for 2026. PW Consulting’s report decodes these events into near-term tactical steps and medium-term strategic moves.
Market dynamics and a 2026 playbook
-
Procurement & supply continuity: Implement layered sourcing with a primary supplier capable of scale, a secondary specialized supplier for high-performance grades, and a tactical tolling or contract-manufacture partner to manage spot volatility. Where contracts permit, build raw-material indexation clauses to cushion margin erosion.
-
Product strategy: Prioritize low-VOC and mass-balance enabled offerings with clear substitution narratives for solvent systems. Invest in application-centric R&D (e.g., mar and scratch resistance, adhesion to new substrates) to capture premium spread.
-
CapEx & manufacturing footprint: Reassess planned investments against the backdrop of announced capacity expansions in waterborne resins. For mid-size players, consider co-location, contract production, or asset-light partnerships rather than greenfield builds in high-cost regions.
-
Pricing and commercial models: Use differentiated pricing tiers aligned to formulation complexity, certification, and service. Embrace value-based selling for high-performance grades while protecting commodity margins through optimized logistics and formulation cost-outs.
-
M&A & alliances: Sophisticated investors will find opportunities in vertical strengthening (building downstream formulation capabilities) and bolt-on tech plays (bio-based modifiers, additive packages). Our report provides deal screening criteria and target shortlists mapped to strategic objectives.
Data, methodology, and next steps
PW Consulting’s analysis uses 2025 as the base year, with a historical window covering 2020–2025 and a forecast horizon of 2026–2032. All values are reported in USD (Million) and the central forecast CAGR for the period is 6.98%. Concentration metrics and supplier analyses are included to help users judge competitive intensity and negotiation posture. The full report contains granular models, downloadable data tables, and customizable dashboards; this preview preserves the high-level implications while directing practitioners to the source for the complete dataset and segment-level numbers.
To access the full dataset, company scorecards, and the downloadable decision-support workbook — or to schedule a tailored executive briefing that translates these insights into a 90-day implementation plan — please visit the PW Consulting report page or contact our industry practice.
PW Consulting: we turn market signals into operational advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Modified Polyurethane Dispersion Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com