

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Multivalent Pneumococcal Conjugate Vaccine Market to Expand at an 8.82% CAGR Through 2026–2032

Worldwide Multivalent Pneumococcal Conjugate Vaccine Market: Strategic Imperatives for 2026
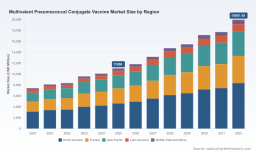
PW Consulting’s new Worldwide Multivalent Pneumococcal Conjugate Vaccine Market report combines rigorous market modelling, competitive forensics, and executable strategy playbooks to guide executive decision-making in 2026. The global market has moved from a niche, program-driven product class into a high-stakes, innovation-led battleground. Our base-year modelling (2025) pegs the market at USD 11,050.0 Million, with an expected compound annual growth rate (CAGR) of 8.82% across the 2026–2032 forecast window and a projected market approaching USD 19,967.5 Million by 2032. These headline figures conceal rapid churn beneath the surface: new multivalent entrants, shifting national immunization policies, and supply-chain dynamics that will determine winners and losers in the next two to three years.
Industrial Noise Control System Market
Why this report matters for 2026 corporate strategy
CEOs, commercial leads, and R&D chiefs need an evidence-driven, pragmatic road map rather than an academic inventory of products. Our report translates market scale and growth drivers into specific action levers for 2026: portfolio rationalisation, capacity planning, tender and pricing playbooks, regulatory prioritisation, and targeted partnership strategies. We apply scenario stress-testing to quantify the impact of key inflection points — accelerated 20+ valency launches, biosimilar PCV13 entry after patent expiry, and changes in adult immunisation recommendations — so leadership teams can resource the right options and time market entry.
Worldwide Pusher Furnaces Market
Key market characteristics that should shape 2026 choices
- Rapid expansion in headline demand: From a market of approximately USD 7.4 Billion in 2020 to USD 11.05 Billion in 2025, the market is forecast to grow at an ~8.8% CAGR, reflecting both expanded adult indications and continued childhood program uptake.
- High concentration: The top three suppliers collectively account for an overwhelming majority of revenues (CR3 ≈ 92.4%), with the top five expanding that share further (CR5 ≈ 97.1%). This concentration creates both entry barriers and opportunity windows for challengers who can solve supply or price pain points.
- Regulatory and recommendation tailwinds: Updated adult vaccination guidance that includes higher-valency products has immediate implications for adult market dynamics and payer negotiations.
- Supply-chain and manufacturing realities: Complex conjugation technologies, constrained polysaccharide supply and cold-chain dependencies mean capital investment in manufacturing and logistics is a strategic must—not a tactical nice-to-have.
Actionable strategic priorities for 2026
Below are the prioritized decision areas where 2026 moves will most materially affect outcomes through 2032. Each item encapsulates the trade-offs we quantify in the full report.
Automotive Cross-domain Fusion Computing Platform Market
- Portfolio and indication strategy:
Prioritise candidates with differentiated valency and demonstrated immunogenic breadth for both pediatric and adult indications. For incumbent manufacturers, protect core franchise economics by accelerating lifecycle studies and real-world evidence generation; for challengers, define a clear value-proposition (price-performance or supply security) for tender buyers and national programmes.
- Manufacturing scale and vertical integration:
Given the limited supplier base for key conjugation inputs and polysaccharides, invest in capacity expansions or long-term toll-manufacturing agreements. Our scenario models show that delayed capacity investment can create multi-quarter supply shortfalls that compress pricing and market share.
- Cold-chain optimization and logistics:
Cold-chain represents a dominant portion of distribution cost and operational risk. Our synthesis of sector data flags that cold-chain logistics can account for roughly half of distribution costs; temperature excursions can jeopardise a material share of doses in lower-resource settings. For 2026, mitigation tactics such as regional depots, thermal management technologies, and third-party cold-chain partnerships should be elevated in capital plans.
- Market access and pricing tactics:
With many national immunisation programmes mature but still variable in coverage, nuanced tender-execution and differentiated pricing strategies for private vs public channels will be essential. Incorporate indication-based pricing for adult programmes and package performance guarantees for purchasers in emerging markets.
- M&A, alliances and geographic playbooks:
Strategic tie-ups — particularly between innovators and manufacturers with capacity or local market access — will accelerate scale. Our deal scenarios indicate that bolt-on acquisitions of regional manufacturers or capacity-lite manufacturing agreements can deliver faster time-to-market than greenfield builds in many markets.
- Regulatory and clinical development sequencing:
Given recent late-stage readouts and regulatory momentum toward higher-valency approvals, companies should sequence trials to capture pediatric, adolescent, and adult labels efficiently. Early engagement with regulators on immunobridging endpoints and post-marketing commitments reduces approval uncertainty.
Competitive landscape — what to watch in 2026
The market remains dominated by a handful of multinational vaccine leaders, with an expanding roster of regional and specialised challengers. Our competitive profiles identify where incumbents can be pressured and where new entrants can sustainably compete.
- Pfizer Inc. (New York, USA) — Established leader with multivalent offerings across pediatric and adult indications. Patents on older valency products are evolving, and competitive pressure on legacy franchises is a strategic focus.
- Merck & Co., Inc. (MSD) (Rahway, NJ, USA) — Active with higher-valency candidates and adult-focused approvals; recent positive Phase 3 data in adolescent populations has strengthened its adult franchise positioning.
- GlaxoSmithKline plc (London, UK) — Strong presence in pediatric national immunisation programs through established 10-valent offerings; continues to be a strategic partner for programmatic adoption.
- Sanofi (Paris, France) & SK bioscience (Seongnam, South Korea) — Their expanded collaboration and ongoing Phase 3 programs for >20-valency candidates mark them as contenders in the next wave of product competition, supported by capacity expansion investments.
- Large regional producers (e.g., Serum Institute of India, Walvax, various Chinese manufacturers) — Compete on affordability and programme access; improving technical capability is increasing supply diversity and creating competitive pressure on pricing in procurement markets.
- Small innovators (Vaxcyte, Inventprise) — Focused on next-generation valency and novel manufacturing approaches; recent positive early-phase readouts indicate potential for selective premium positioning or acquisition interest from larger players.
Recent developments that change the calculus
- Positive late-stage and dose-finding trial readouts from multiple developers have de-risked higher-valency candidates and accelerated regulatory conversations for adult indications.
- Expanded collaborations and facility investments by strategic producers reflect a shift from proof-of-concept to supply readiness — an essential step given projected demand growth.
- Updated immunisation advisory committee recommendations for adult use of higher-valency vaccines in specific age groups create immediate commercial upside in mature markets and add complexity to global procurement strategies.
- Patent expiries on legacy products will invite biosimilar and generic competition in certain markets; the timing and geographic scope of biogeneric entry will be a core scenario in 2026 planning.
What the PW Consulting report delivers (operational contents)
Our report is designed to be used by strategy teams as a decision-support toolkit, not a descriptive digest. Deliverables include:
- Proprietary market model (2020–2032) with scenario toggles for valency adoption curves, vaccine price trajectories, and supply disruptions.
- Competitive heatmaps and risk-assessment matrices that identify where incumbents are vulnerable and where challengers are advantaged.
- Regulatory and reimbursement playbook outlining accelerated approval pathways, immunobridging recommendations, and payer negotiation strategies tailored to adult vs pediatric markets.
- Manufacturing and supply-chain blueprints, including a supplier capability map, cold-chain cost optimisation levers, and capital investment prioritisation frameworks.
- Commercial execution templates for tendering, tiered pricing, and programmatic adoption to increase win probability in both public and private channels.
- M&A and partnership scoring tools to prioritise targets, estimate synergies, and model integration risks.
How to use these insights in board-level planning for 2026
We recommend boards and C-suite teams run three coordinated initiatives in 2026: (1) a 90-day tactical plan to shore up supply and tender readiness for immediate growth opportunities; (2) a 6–12 month strategic program to accelerate clinical and regulatory milestones for higher-valency candidates; and (3) a capital allocation review that biases toward modular manufacturing and logistics solutions to de-risk distribution. The full report contains executable timelines, investment estimates under multiple scenarios, and governance checklists to convert strategy into measurable outcomes.
Final note — the intelligence gap we close
High-level metrics tell the growth story, but competitive positioning, supply chain nuance, and regulatory sequencing determine who captures value. With a concentrated supplier base, imminent patent expiries, and a wave of higher-valency product launches, 2026 is a pivotal year. PW Consulting’s report converts these dynamics into clear strategic choices and near-term actions so organisations can convert headline growth into sustainable market share.
Next steps
For executives seeking the full data tables, granular scenario outputs, and the proprietary models referenced here, PW Consulting’s comprehensive report and strategy workshop packages are available. Contact our industry team to arrange a briefing and obtain access to the underlying datasets and playbooks that will be decisive for 2026 planning.
For detailed analysis of this topic, please visit the official page: Worldwide Multivalent Pneumococcal Conjugate Vaccine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com