

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
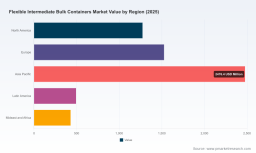
PW Consulting: Worldwide Flexible IBCs Market to Expand from USD 6.2B in 2025 to USD 9.42B by 2032 at a 6.15% CAGR — Asia‑Pacific Leads with USD 2.48B; Chemicals and U‑Panel Bags Top Segments

Worldwide Flexible Intermediate Bulk Containers Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting’s latest market intelligence release on the Worldwide Flexible Intermediate Bulk Containers (FIBC) market is designed as a strategic playbook for organizations making high‑stakes decisions in 2026. Our independent analysis shows the global FIBC market reached approximately USD 6.2 billion in 2025 and is positioned to expand steadily from the 2026 base to an estimated USD 9.4 billion by 2032, reflecting a compound annual growth rate (CAGR) of 6.15% over the 2026–2032 forecast window. This briefing summarizes the report’s strategic value, highlights the operational levers that will matter most next year, and outlines the practical decision tools embedded in the full study. For full datasets, interactive models and downloadable templates, readers are encouraged to consult the full report on our website.
Worldwide Fire Retardant Additives Market
Why this report matters in 2026
-
Market trajectory meets operational complexity: an expanding market with mid‑single digit CAGR presents both strategic growth opportunities and significant execution risks tied to raw materials, regulation and supply network design.
Worldwide Integrated Pest Management Pheromones Market -
Material and regulatory shocks are no longer hypothetical: procurement and product teams must reconcile higher polymer volatility and incoming regulatory regimes with short product lifecycles and rising customer sustainability expectations.
Oxidation Ditch System Market -
Fragmented supplier landscape: the sector remains structurally fragmented, which creates options for buyers to negotiate on service and circularity rather than pure price, while giving strategic acquirers attractive consolidation targets.
Key market dynamics and implications
-
Demand fundamentals: Growth is being driven by continued industrial activity across chemicals, food & pharma, construction and agricultural segments, alongside rising adoption of customized, higher‑specification bags (e.g., aseptic liners, Type C/D electrical protection and baffle designs). While segments perform unevenly, the overall market expansion offers predictable volume growth for suppliers that can capture service and product differentiation.
-
Raw material dependency and cost pressure: FIBCs are predominantly produced from woven polypropylene — a single feedstock that accounts for the majority of volume. Polypropylene price volatility has moved from a sporadic concern to a strategic risk factor; purchasers and manufacturers should model scenarios for prolonged price elevation and build hedging or pass‑through mechanisms into contracts.
-
Regulatory inflection points create winners and losers: The EU Packaging and Packaging Waste Regulation (PPWR) and similar policy initiatives are changing economics for traditional plastics packaging by linking extended producer responsibility (EPR) fees to recyclability and recycled content. Compliance will require investments in traceability, design‑for‑recycling, and reporting capability — and will materially affect sourcing choices in 2026.
-
Circular economy as competitive advantage: A small but growing cohort of suppliers is moving beyond product sales to circular services — reconditioning, closed‑loop takeback and rPET manufacturing. Recent industry moves show large suppliers delivering reconditioning services at scale and new entrants commissioning rPET capacity. These capabilities are proving to be a differentiator in procurement dialogs where both cost and sustainability performance matter.
Competitive landscape — strategic themes, not scorecards
The market comprises a mix of global industrial packaging groups, regional specialists and focused FIBC manufacturers. Leading industrial packaging companies emphasize end‑to‑end solutions (aseptic liners, standardized quality systems, and circular service programs), while small and medium manufacturers compete on responsiveness, customization and local cost structures. Rather than attempting to list share by geography or application here, the most actionable takeaways are structural:
-
Scale + service wins: Large producers leverage global footprints and value‑added services (e.g., on‑demand inventory, reconditioning networks and food‑grade certifications) to capture higher margin segments.
-
Specialists capture niche economics: High‑quality weavers and regional producers continue to command business where rapid turn, customization or local compliance matters.
-
Innovation is bifurcated: technological/product innovation (e.g., enhanced aseptic liners, multilayer designs) sits alongside material innovation (e.g., rPET and recycled polypropylene). Successful suppliers combine both to respond to procurement requirements influenced by EPR and sustainability procurement policies.
Illustrative recent developments underscore these themes. A major global producer announced product launches targeting aseptic and pharma applications while simultaneously reporting millions of containers reconditioned under a circularity program. Parallel moves include new rPET plant commissioning and launches of 100% rPET FIBCs claiming significant lifecycle carbon reductions. Together these initiatives show how incumbents and new entrants are aligning product and service innovations to shifting buyer preferences and regulatory pressure.
What the PW Consulting report delivers — practical, actionable content
Designed for commercial leaders, procurement teams, investors and R&D officers, the full report delivers a set of hands‑on tools and analyses intended to accelerate 2026 decision cycles without requiring months of internal modeling. Key deliverables include:
-
Proprietary market model (2020–2032): dynamic, downloadable spreadsheet with top‑level market size, growth scenarios and sensitivity levers so clients can stress test assumptions against polymer price, regulatory costs and demand shocks.
-
Scenario playbooks: three 2026‑ready pathways (base, accelerated circular adoption, and high‑input price stress) with operational actions, capex timelines and P&L impact illustrations.
-
Supplier scoring and negotiation toolkit: templates and weighted scorecards for evaluating suppliers across service, sustainability, price volatility exposure and compliance readiness.
-
Regulatory impact matrix: concise, region‑aware implications of PPWR‑style rules and EPR fee structures mapped to product design and procurement clauses.
-
Sustainability and LCA toolkit: guidance on measuring recycled content, estimating cradle‑to‑gate carbon impacts and a simple ROI calculator for rPET versus virgin resin investments.
-
Commercial due‑diligence and M&A map: assessment criteria for identifying and valuing bolt‑on targets in low‑cost regions, plus integration playbooks focused on quality control and regulatory harmonization.
-
Case studies and implementation checklists: real‑world examples of reconditioning programs, on‑demand inventory roll‑outs and product migrations to higher‑specification bags with timeline and cost benchmarks.
Direct 2026 actions — recommended playbook
-
Procurement: shift from spot buying to layered procurement strategies — mix index‑linked contracts, shorter tactical purchases and strategic long‑term agreements with recyclate supply commitments.
-
Product and sustainability teams: pilot recycled content initiatives with clear KPIs and third‑party verification; prioritize modular designs that enable reconditioning and reuse.
-
Operations and supply chain: conduct a rapid supplier resilience audit (60–90 days) and develop contingency plans for elevated polypropylene costs and logistics disruption; include tariff exposure checks for import categories.
-
Investors and corporate development: target acquisition pipelines that add either circular capability (reconditioning, rPET feedstock) or complementary geographies; valuation should reflect likely margin benefits from service monetization and regulatory positioning.
-
Regulatory & compliance teams: implement traceability and reporting upgrades ahead of enforcement dates for EPR‑style regimes and build supplier documentation requirements into purchase orders.
How PW Consulting’s analysis reduces execution risk
Our report is intentionally engineered as a decision‑support package: the market model ties demand to discrete operational levers; the scenario playbooks convert regulatory and raw material uncertainties into portfolio‑level actions; and supplier scorecards allow procurement to move beyond lowest‑price sourcing. Collectively, these resources shorten the time between insight and action, enabling organizations to lock in 2026 strategies with quantifiable risk‑reward tradeoffs.
Next steps and how to access the full report
This public briefing is a strategic preview: it outlines the trends, risks and recommended responses that should be central to any 2026 planning cycle involving FIBCs. For corporate teams planning capital allocation, procurement changes, product launches or M&A in 2026, the full report provides the datasets, interactive models and operational templates required to move from strategy to execution.
To explore the complete market model, segmented forecasts, company profiles, and downloadable playbooks, please visit the PW Consulting report page for the Worldwide Flexible Intermediate Bulk Containers Market. Our analysts are available for tailored briefings and scenario workshops to help translate these insights into a 90‑day operational roadmap.
For detailed analysis of this topic, please visit the official page: Worldwide Flexible Intermediate Bulk Containers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com