

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Phenolic Curing Agent Market Set for 5.12% CAGR — Key Growth Drivers and Regional Leaders Unveiled

Worldwide Phenolic Curing Agent Market — Strategic Outlook for 2026: Why This Report Will Be a Boardroom Imperative
PW Consulting’s latest market study on the Worldwide Phenolic Curing Agent Market is published with a clear mandate: equip senior executives, commercial leaders and M&A teams with an executable intelligence set to make confident decisions in 2026. The market reached an estimated USD 861.3 Million in our 2025 base year and, under our central forecast, expands at a compound annual growth rate (CAGR) of 5.12% over 2026–2032 toward just over USD 1.22 Billion by 2032. Those headline numbers capture growth momentum — but the report’s strategic value lies in the operationally-focused tools and scenario framings that translate that momentum into concrete choices for procurement, product strategy, and inorganic growth.
Worldwide Traval Retail Cosmetic Market
Why boards and strategy teams will rely on this study
-
Actionable, not academic: beyond topline sizing, the report delivers supplier scorecards, margin-impact models and a commercial playbook that to-the-dollar estimates how raw-material moves and customer mix shifts will flow to your P&L.
Worldwide Tubing Connections Market -
Risk-to-return mapping: we quantify and stress-test the market under multiple raw-material and regulatory shock scenarios — enabling procurement and R&D leaders to prioritize hedging, reformulation, or vertical options.
Head Mirror Market -
Competitive clarity: a focused benchmarking of leading participants and capability gaps helps identify targets for bolt-on acquisitions, strategic partnerships, or joint development agreements.
Key themes shaping 2026 strategic choices
-
Price and margin pressure from raw-material volatility — Phenol and formaldehyde price swings are no longer episodic. Our monitoring through April 2026 registered substantial increases in key Asian and European phenol hubs and a material step-up in U.S. formaldehyde prices in late 2024. These cost moves are compressing gross margins for producers that cannot pass through rapidly or reformulate toward lower-cost chemistries.
-
Regulatory complexity is increasing — Recent regulatory activity (for example, reporting obligations introduced for certain phenolic derivatives under TSCA’s SNURs) imposes new compliance burdens and potential time-to-market friction for product introductions and reformulations in North America. This alters the calculus for product launches and for acquiring technology or plants that serve regulated uses.
-
Demand pockets remain durable but selectively evolving — End-use engines such as electronics encapsulation, industrial coatings systems, adhesives and advanced composites continue to anchor demand. Within these pockets, formulators are asking for higher-functionality resins, lower-VOC solutions and improved thermal/electrical performance — providing premium niches for suppliers that can invest in application-specific R&D.
-
Moderate market concentration creates maneuvering room — Market concentration metrics indicate a market where the top three vendors account for a meaningful share, and the top five for just over half of industry volume. That structure enables regional champions and specialty players to carve defensible positions while also leaving opportunities for M&A consolidation that meaningfully alters competitive dynamics.
Competitive landscape — what the leading suppliers signal for 2026 strategy
Our report profiles manufacturers and specialty suppliers across the value chain, from global resin platforms to toll processors and niche phenolic houses. Public and private participants — including established resin majors, integrated chemical producers, and specialty tollers — show differentiated plays:
-
Global resin majors bring scale and integrated upstream capabilities, enabling them to navigate raw-material cycles and support large industrial accounts with global supply footprints.
-
Specialty phenolic houses and toll manufacturers offer agility, formulation depth and the ability to service strict application requirements such as electronics and high-performance composites.
-
Some players emphasize coating-grade novolac and resole crosslinkers, while others focus on epoxy-curing compatibility for molding compounds — these strategic choices define customer segments, margin profiles and capital intensity.
To be concrete about names (and why they matter): major global suppliers, integrated chemical producers and specialized phenolic manufacturers are all active in the market. Their positioning ranges from broad aftermarket and OEM supply networks to focused toll-manufacturing and application-driven R&D. This mix means that commercial strategies in 2026 must be calibrated by supplier type — negotiating differently with a captive-volume global player versus a specialty toller capable of rapid reformulation support.
Operational playbook embedded in the report
For executives who need to move from insight to implementation, the study contains a practical set of tools and templates, including:
-
Supplier risk matrix: ranks counterparties by concentration exposure, price-transmission elasticity, and regulatory footprint to prioritize secure, cost-efficient sourcing.
-
Raw-material sensitivity models: quantify EBITDA impact across multiple phenol and formaldehyde price scenarios, enabling finance teams to model forward curves and set appropriate hedge ratios.
-
Reformulation decision tree: a roadmap that links performance targets to reformulation levers, R&D cost estimates, and expected time-to-market under current regulatory timelines.
-
M&A playbook: a prioritized target-screening framework emphasizing capability gaps, regional footprint, and near-term integration risks — and a valuation approach that captures price-cycle volatility inherent to chemical intermediates.
-
Commercial acceleration kit: win/loss frameworks and sample contract clauses (price adjustment language, force majeure drafting aligned with raw-material volatility) that legal and commercial teams can deploy immediately.
Scenario planning — three plausible market pathways for 2026–2028
-
Baseline (central) — Continuation of steady demand and partial pass-through of raw-material cost increases: the market grows in line with our 5.12% medium-term CAGR as formulators accommodate higher input costs through a mix of price adjustments and modest reformulation.
-
Up-cycle (price shock mitigated) — If phenol/formaldehyde supply tightness eases or feedstock prices retreat, producers with underutilized capacity could regain margin through volume recovery and reinvestment in higher-spec products, accelerating premium segment adoption.
-
Regulatory-constrained (cost of compliance rises) — Heightened regulatory actions or new reporting/registration requirements elevate compliance costs and time-to-market barriers, favoring larger integrated firms and creating acquisition windows for smaller players seeking liquidity.
What leadership teams should do in the next 12 months
-
Embed raw-material scenarios into quarterly planning: update price-pass-through triggers for customer contracts and revise capex prioritization to favor flexible, lower-capital intensity projects.
-
Fast-track supplier diversification and strategic inventory: secure multi-sourcing for critical phenolic intermediates and evaluate toll-manufacturing partnerships where capital deployment is undesirable.
-
Accelerate application-focused innovation: invest selectively in higher-margin niches — e.g., electronic-grade curing systems and specialty coating crosslinkers — that demonstrate insensitivity to small-volume cost shocks.
-
Use M&A opportunistically: target regional specialists and tollers whose integration can reduce sourcing risk, add formulation capability, and provide footholds in priority geographies.
Report contents — what you will find inside (high level)
-
Independent market sizing and method notes (historical 2020–2025; base year 2025) and scenario-based forecasts through 2032.
-
Cost and pricing analytics: forward-looking phenol and formaldehyde curves, plus margin impact models.
-
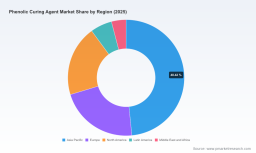
Segment and application demand narratives that identify durable demand pockets and emerging premium opportunities (note: detailed, proprietary subsegment tables and regional splits are available in full report access only).
-
Supplier profiles and competitive benchmarking against capability, capacity and regulatory coverage metrics.
-
Actionable annexes: sourcing playbooks, sample contract clauses, and an M&A target filter.
Closing strategic takeaway
For leadership teams preparing 2026 budgets and strategic roadmaps, the phenolic curing agent market presents both pressure and optionality. The near-term environment is defined by raw-material volatility and tighter regulatory scrutiny; yet, demand durability — backed by applications in electronics, coatings, adhesives and composites — supports disciplined investment in differentiation. PW Consulting’s report provides the analytical foundation and the executable toolset to convert market trajectories into defensible commercial and capital-allocation moves. We present the evidence you need to prioritize: whom to partner with, what to build, and where to acquire — while reserving the granular subsegment datasets that are central to deal and procurement execution for licensed access.
To access the full dataset, proprietary segment tables, and the interactive scenario toolset that management teams will use in 2026 planning cycles, visit the official report page or contact PW Consulting’s industry desk for a briefing and tailored advisory engagement.
For detailed analysis of this topic, please visit the official page: Worldwide Phenolic Curing Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com