

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting Report: Encrypted USB Market Hits $200M in 2025, Poised for 7.5% CAGR Growth Through 2032
By pmarketresearch, 2026-09-15
Strategic Imperatives in the Encrypted USB Flash Drives Market: A 2026 Outlook
In an era where data breaches can cripple reputations and incur billions in fines, the humble USB flash drive has evolved from a simple storage accessory into a critical endpoint security asset. As organizations navigate the complex intersection of remote work, stringent regulatory compliance, and escalating cyber threats, the demand for secure removable media is no longer optional—it is a foundational requirement for operational resilience. PW Consulting has released a comprehensive market research report detailing the trajectory of the Encrypted USB Flash Drives Market, offering vital intelligence for stakeholders looking to secure their data infrastructure through 2032.
This market has demonstrated remarkable resilience and growth over the past half-decade. Historical analysis from 2020 to 2025 reveals a consistent upward trend, with the overall market valuation climbing from 120.0 million USD to a projected 200.0 million USD by the base year. This trajectory underscores a shifting paradigm where security is prioritized over convenience. Looking forward, the forecast period from 2026 to 2032 suggests that this momentum will not only continue but accelerate, driven by tighter government mandates and enterprise security protocols.
Market Trajectory and Growth Dynamics
The financial outlook for this sector is robust. Starting from a valuation of 210.95 million USD in 2026, the market is expected to expand significantly, reaching 330.0 million USD by 2032. This growth is anchored by a compound annual growth rate (CAGR) of 7.5 percent over the forecast period. Such performance indicates that investment in encrypted storage solutions is becoming a standard line item in IT security budgets rather than a niche expenditure. The expansion is not merely a function of price increases but reflects a deepening penetration of secure storage solutions across diverse industry verticals.
Several key factors are fueling this expansion. First, the proliferation of remote and hybrid work models has decentralized data storage, increasing the risk surface associated with removable media. Employees moving between secure corporate networks and public spaces require portable storage that does not become a liability. Second, the regulatory landscape is hardening. Recent updates to state-level security standards, such as the Iowa Removable Storage Device Security Standard effective June 2025, mandate the use of 256-bit AES or stronger encryption for devices storing confidential data. Similarly, NIST SP 800-111 guidelines continue to require self-encrypting USB drives for federal agencies handling sensitive data on removable media.
Furthermore, the transition from FIPS 140-2 to FIPS 140-3 Level 3 validation represents a critical threshold for high-assurance government and defense applications. Cryptographic modules used in encrypted USB flash drives for these sectors must now meet stricter validation criteria, effectively creating a barrier to entry that favors established, compliant manufacturers. This regulatory pressure acts as a tailwind for the market, compelling organizations to upgrade their hardware to meet compliance standards, thereby driving volume and value.
Segmentation and Value Distribution
Understanding where value resides within the market is crucial for strategic positioning. The market is segmented by type, region, and application, each presenting unique opportunities and challenges. In terms of technology type, hardware-encrypted solutions dominate the landscape. This segment reflects a strong market preference for security that is independent of the host operating system. Hardware encryption ensures that data protection is intrinsic to the device, reducing the risk of software vulnerabilities or user error compromising the encryption key. Software encrypted and hybrid options occupy smaller shares, catering to specific use cases where flexibility or cost constraints are prioritized over maximum security assurance.
Geographically, the market reflects mature security infrastructures in certain regions alongside growing adoption in others. North America remains the largest revenue contributor, driven by high enterprise spending on cybersecurity and strict government procurement standards. Europe follows as a significant market, influenced by GDPR compliance requirements and robust public sector procurement. The Asia Pacific region represents a dynamic growth engine, where rapid digital transformation and increasing awareness of data sovereignty are prompting both enterprises and governments to invest in secure storage hardware. Latin America and the Middle East and Africa, while smaller in current valuation, are emerging markets where increased digitization is expected to drive incremental demand.
Application-wise, enterprise use cases capture the largest share of the market. Corporations are increasingly recognizing that data loss prevention strategies must extend to removable media. Government use is the second major pillar, heavily influenced by procurement mandates and defense-related security requirements. Consumer use, while present, remains a smaller fraction of the total revenue, as individual users often prioritize cost and capacity over advanced encryption features unless compelled by specific privacy concerns.
Competitive Landscape and Strategic Positioning
The market is characterized by a high degree of concentration, with the top three companies accounting for approximately 70 percent of market revenue and the top five firms holding around 85 percent. This consolidation suggests that scale, compliance certification, and established distribution channels are significant moats for incumbent players. However, innovation in encryption technology and form factor continues to provide avenues for differentiated positioning.
USB Drive Market
Kingston Technology Company, Inc., headquartered in Fountain Valley, California, stands as a leader in the hardware-encrypted space. Their IronKey series, including the Locker+ 50 G2 and D500S, exemplifies the market standard with 256-bit AES XTS hardware encryption and FIPS 140-3 Level 3 validation. In March 2026, Kingston released the next-generation IronKey Locker+ 50 G2, reinforcing their commitment to enterprise-grade security features and FIPS 197 certification. Earlier, in July 2025, they unveiled the IronKey D500S as the first FIPS 140-3 Level 3 flash drive meeting Trade Agreements Act rules, a critical milestone for government procurement eligibility.
Apricorn, based in Poway, California, specializes in software-free 256-bit AES XTS hardware-encrypted USB flash keys. Their Aegis Secure Key series is renowned for environmental hardening, making them suitable for harsh operational conditions. In May 2026, Apricorn updated the Aegis Secure Key 3 (ASK3) with faster speeds and improved environmental protection, while submitting for FIPS 140-3 Level 3 validation. This focus on ruggedness and pure hardware encryption appeals to sectors like defense, law enforcement, and industrial field operations.
DataLocker Inc. offers a strong value proposition through its Sentry series, which includes FIPS 140-2/3 Level 3 certified encrypted USB flash drives with SafeConsole remote management. Their March 2025 launch of the Sentry ONE drive highlighted capabilities such as remote wipe and multi-certifications including NIST, CSPN, and BSI/BSZ. This emphasis on management software alongside hardware security addresses the enterprise need for centralized control over distributed devices, ensuring compliance with regulations like HIPAA, GDPR, and CMMC.
Other key players further diversify the competitive landscape. Kanguru Solutions provides government-certified 256-bit hardware-encrypted secure USB drives with remote management and endpoint protection. iStorage, based in the United Kingdom, delivers hardware-encrypted drives like the datAshur PRO series, featuring PIN/password protection and FIPS-validated encryption for high-security data transfers. Clevy focuses on hardware-encrypted secure USB drives with advanced encryption and management tools for enterprise data security. Western Digital Corporation, through its SanDisk brand, provides encrypted USB flash drives featuring AES encryption and secure access software, leveraging its broad consumer and enterprise brand recognition to penetrate the secure storage market.
Strategic Implications for Decision Makers
For enterprise leaders, IT security officers, and procurement strategists, the insights contained in this market research extend beyond simple revenue forecasts. The shift toward hardware-encrypted dominance suggests that software-based encryption alone may increasingly fall short of compliance requirements for sensitive data. Organizations must evaluate whether their current portable storage strategies align with the 256-bit AES standards and FIPS 140-3 mandates that are becoming prevalent.
The concentration of market power among the top players indicates that supply chain stability and vendor longevity are critical considerations. Partnering with vendors who have a proven track record of maintaining certifications through regulatory updates is essential. The recent product launches by key competitors highlight a race toward higher performance, better durability, and stricter validation. For instance, the ability to remotely manage and wipe devices, as offered by DataLocker and Kanguru, is becoming a differentiator for enterprises managing large fleets of distributed workers.
Furthermore, the regional dynamics suggest that global organizations must adopt a nuanced approach. While North American and European markets demand strict adherence to local compliance frameworks, the Asia Pacific region may offer growth opportunities for vendors who can balance security with cost-effectiveness and local data sovereignty laws. The report provides a detailed breakdown of these regional nuances, helping stakeholders identify where to allocate resources for maximum impact.
Conclusion and Next Steps
The Encrypted USB Flash Drives Market is at a inflection point where security, compliance, and mobility converge. The projected growth to 330.0 million USD by 2032 is not just a number; it represents a structural change in how organizations handle sensitive data on the move. With regulatory pressures intensifying and cyber threats evolving, the choice of encrypted storage solutions is a strategic decision that impacts risk management, compliance posture, and operational efficiency.
Encrypted USB Flash Drives Market
This executive summary provides a high-level view of the market dynamics, competitive forces, and growth drivers. However, the full depth of the analysis contained in the PW Consulting report offers the granular data necessary to build detailed go-to-market strategies, investment models, and risk assessments. To access the complete segmentation data, detailed competitor profiles, and comprehensive regulatory impact analysis, we invite you to explore the full report. Equip your organization with the intelligence needed to navigate the secure storage landscape with confidence.
For detailed analysis of this topic, please visit the official page: Encrypted USB Flash Drives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Gate Bipolar Transistors STATCOM Market Hits $215M in 2025, 3x to $345M by 2032 at 6.98% CAGR
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Gate Bipolar Transistor STATCOM Market: Navigating the 2026–2032 Growth Arc
The global power grid is undergoing a structural transformation. As renewable penetration accelerates and transmission networks face heightened stability demands, the need for fast-acting reactive power compensation has moved from niche engineering requirement to central grid modernization imperative. At the heart of this shift lies the Gate Bipolar Transistor (GBT)-based STATCOM market. PW Consulting’s latest research report delivers a comprehensive, data-grounded assessment of this sector, covering historical performance from 2020 through 2025 and projecting forward across the 2026–2032 forecast horizon. For executives, procurement leaders, and technology strategists, the report serves as a decision-grade compass rather than a retrospective summary.
Why the 2026 Baseline Matters Now
Market participants often treat forecast years as abstract timelines. In reality, 2026 represents the first full operational cycle following a series of regulatory, technological, and infrastructural inflection points that will dictate competitive positioning for the remainder of the decade. The market closed 2025 at a valuation of 215.0 million USD, building on a consistent expansion trajectory that began at 163.15 million USD in 2020. This five-year historical window captures the early scaling phase of IGBT-driven static compensators as utilities and independent power producers moved beyond pilot deployments into standardized grid-edge integration.
Looking ahead, the forecast period projects a compound annual growth rate of 6.98 percent, with the market expected to reach 231.71 million USD in 2026 and continue its upward path toward 344.8 million USD by 2032. These figures are not merely top-line projections; they reflect an underlying shift in how grid operators prioritize voltage support, harmonic mitigation, and dynamic reactive power injection. For companies evaluating product roadmaps, capacity investments, or regional market entry, understanding the velocity and composition of this growth is essential. PW Consulting’s analysis isolates the structural drivers behind this trajectory while deliberately withholding granular segmentation breakdowns, ensuring that only stakeholders who engage with the full study can access the precise regional, application, and type-level intelligence required for tactical execution.
Market Structure and Demand Vectors
The STATCOM landscape is fundamentally shaped by voltage class, end-use application, and geographic deployment patterns. High Voltage STATCOM configurations continue to dominate total market value, reflecting the scale of transmission-level grid reinforcement projects and the technical requirements of large-scale renewable interconnection. Low Voltage STATCOM solutions, while smaller in aggregate revenue contribution, represent a strategically distinct segment driven by industrial microgrids, data center power quality upgrades, and localized distribution network stability initiatives.
IGBT Market
From an application perspective, renewable energy integration stands as the primary demand engine. The necessity for STATCOM systems to deliver voltage support with IGBT response times in the 1-to-5 millisecond range has become a defining performance criterion, as documented in recent grid integration research. Electric utilities form the second major demand pillar, leveraging GBT-based compensators for transmission congestion management, fault ride-through enhancement, and compliance with evolving harmonic distortion limits. Industrial and manufacturing sectors, along with specialized use cases in infrastructure and commercial power conditioning, complete the application mosaic, each imposing distinct reliability, scaling, and interface requirements on equipment manufacturers.
Regional deployment patterns reveal a highly distributed demand footprint, with mature grid modernization programs in established markets operating alongside rapid capacity build-out in emerging transmission corridors. This geographic diversification means that no single regional strategy can capture the full growth opportunity. Companies must evaluate supply chain localization, service network density, and regulatory alignment across multiple jurisdictions simultaneously. The complete regional and application-level quantification, including precise share distributions and revenue allocations, is reserved for the full report to preserve the analytical depth required for accurate market entry and resource allocation planning.
Regulatory Tailwinds and Technical Standardization
Policy and standards frameworks are no longer peripheral considerations; they actively shape procurement cycles, technology selection, and competitive barriers to entry. In Europe, EU Directive 2019/944 mandates market-based, transparent procurement of reactive power using STATCOM devices, forcing utilities and system operators to formalize sourcing processes and evaluate suppliers against structured performance and pricing criteria. Parallel developments in Germany point toward a reactive power market expected to commence in the early-to-mid 2025 window, requiring transmission system operator tenders specifically structured around STATCOM procurement to meet grid stability obligations.
On the technical side, IEEE Std 519-2014 and the updated IEEE Std 519-2025 continue to govern harmonic limits for IGBT-based STATCOM installations, establishing compliance benchmarks that directly influence converter topology selection, filtering architecture, and long-term operational acceptance. Standardization activity also extends to device-level comparisons, with recent IEEE Power & Energy Society analysis highlighting that T-STATCOM converter structures utilizing 3.3 kV silicon IGBTs deliver measurable overload handling advantages over silicon carbide MOSFET alternatives in high-voltage applications. These technical nuances have direct implications for product positioning, bill-of-materials strategy, and performance validation protocols.
Regulatory and standardization trajectories are accelerating procurement formalization, but they also introduce compliance complexity that favors organizations with robust engineering documentation, certification pathways, and tender response capabilities. PW Consulting’s report maps these regulatory shifts against demand timelines, helping clients anticipate tender windows, align product certifications, and structure proposal architectures that meet both technical specifications and procurement transparency requirements.
Competitive Landscape and Strategic Positioning
The Gate Bipolar Transistor STATCOM market operates with a moderately fragmented but highly capable participant base. The combined market share of the top three competitors sits at 24.6 percent, while the top five reach 26.2 percent, indicating that no single entity commands decisive pricing power and that technological differentiation, regional execution, and service integration remain the primary competitive levers. This concentration profile rewards companies that can combine reliable converter performance with localized project delivery and long-term grid operator relationships.
A diverse set of established and regional players defines the current competitive fabric. Siemens Energy brings comprehensive transmission-grade power electronics expertise and a structured approach to grid integration projects across Europe and global utility markets. ABB Ltd continues to leverage its broad electrification portfolio, emphasizing scalable STATCOM architectures and digital grid management interfaces. Rongxin Power Electronic Co., Ltd and Sieyuan Electric Co., Ltd represent China-based manufacturing capabilities that have expanded their footprint through cost-competitive product lines and growing international project participation. Hitachi Energy and Mitsubishi Electric Corporation contribute advanced converter technology and strong regional execution in Japan and selected export markets, while GE Vernova applies its grid solutions heritage to utility-scale reactive power infrastructure in North America and beyond.
Ingeteam adds specialized power conversion expertise with a focus on renewable-aligned grid support applications, and American Superconductor (AMSC) brings differentiated high-performance grid technology positioning. Hyosung Heavy Industries offers strong heavy electrical equipment integration capabilities, particularly relevant for combined transformer-converter STATCOM deployments. S&C Electric Company maintains a recognized presence in distribution-level grid protection and compensation solutions, while Fuji Electric Co., Ltd contributes mature power semiconductor and industrial control engineering to the competitive mix.
Competitive advantage in this environment rarely derives from volume alone. It emerges from the intersection of converter reliability, harmonic compliance documentation, turnaround speed on tender responses, service and maintenance coverage, and the ability to tailor voltage-class solutions to specific grid operator requirements. The full report provides detailed company-level strategic profiles, technology positioning assessments, and competitive move tracking, while withholding precise revenue allocations and share calculations to preserve the analytical exclusivity required for strategic planning.
What the Report Delivers for 2026 Decision-Making
PW Consulting’s Gate Bipolar Transistor STATCOM Market research is structured to support concrete executive and operational decisions rather than remain a descriptive market summary. The study integrates historical performance tracking, forward-looking valuation projections, segmentation mapping, competitive benchmarking, and regulatory-standards impact analysis into a unified decision framework. Readers gain access to a structured assessment of how demand vectors are evolving across voltage classes, application sectors, and regional deployment zones, alongside an evaluation of the procurement, compliance, and technical standardization factors that will shape supplier selection over the forecast period.
The report also provides operational intelligence relevant to product planning, capacity allocation, partnership strategy, and tender positioning. By aligning market trajectory data with technology performance criteria and regulatory timelines, the analysis enables clients to identify which segments offer the most defensible growth pathways, where service and localization investments will generate the strongest returns, and how to structure proposals in markets moving toward formalized reactive power procurement. To maintain the integrity of these insights for actionable use, core segmentation percentages, detailed regional and application-level valuations, and exact competitor revenue breakdowns are reserved for the complete study.
Gate Bipolar Transistors STATCOM Market
Strategic Recommendations for Market Participants
- Align product development and certification roadmaps with IEEE harmonic compliance expectations and emerging regional reactive power procurement mandates, ensuring that documentation and validation protocols are ready before tender cycles intensify.
- Evaluate high-voltage and low-voltage portfolio positioning as distinct strategic tracks, since each addresses different procurement authorities, technical specifications, and competitive dynamics.
- Prioritize regional execution capability over generalized global presence, focusing service network density, local engineering support, and supply chain responsiveness in markets where grid modernization budgets are accelerating.
- Use the moderately consolidated competitive structure as an opportunity to differentiate through performance reliability, tender response quality, and lifecycle service agreements rather than competing solely on initial equipment pricing.
- Incorporate 1-to-5 millisecond IGBT response performance and overload handling characteristics into product messaging and technical proposals, as these parameters are increasingly central to grid operator evaluation criteria for renewable integration and transmission support applications.
Conclusion: Securing the Intelligence Edge
The Gate Bipolar Transistor STATCOM market is entering a phase where growth is not only sustained but structurally reinforced by grid stability requirements, renewable integration acceleration, and formalized reactive power procurement frameworks. The historical expansion from 2020 through 2025 establishes a credible demand foundation, while the 2026–2032 forecast period points to continued value creation for organizations that can navigate technical standardization, regional procurement variation, and competitive differentiation with precision.
PW Consulting’s full market research report provides the depth, segmentation clarity, competitive profiling, and regulatory-aligned analysis required to convert this macro trajectory into executable strategy. To access the complete dataset, detailed segmentation valuations, regional and application-level breakdowns, and in-depth company strategic assessments, stakeholders are encouraged to visit the source report page and obtain the full intelligence package. In a market where timing, compliance readiness, and segment selection determine competitive outcomes, comprehensive and current intelligence is not optional. It is the foundation of effective 2026 decision-making.
For detailed analysis of this topic, please visit the official page: Gate Bipolar Transistors STATCOM Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Methyl Mercaptan Market to Reach $225M by 2032 with 6.5% CAGR
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Methyl Mercaptan Market 2026: Navigating Growth, Regulation, and Competitive Dynamics
The methyl mercaptan market stands at a pivotal juncture as industrial demand, supply chain restructuring, and tightening regulatory frameworks converge to reshape competitive positioning. For executives, procurement leaders, and strategic planners operating in specialty chemicals, animal nutrition, and industrial gas applications, understanding the trajectory of this market is no longer optional. Our latest market research report delivers a comprehensive, data-driven intelligence framework designed to inform capital allocation, supply strategy, and long-term portfolio decisions throughout the 2026–2032 forecast horizon.
This introductory analysis outlines the structural forces defining the market, highlights the operational and compliance dimensions that demand executive attention, and previews the analytical rigor embedded in our full research deliverable. The objective is clear: equip decision-makers with actionable strategic context while preserving the granular segmentation, pricing models, and regional breakdowns that form the core of our paid intelligence suite.
Macro Trajectory and Demand Architecture: Why 2026 Matters
The global market for methyl mercaptan has demonstrated consistent expansion over the past half-decade, recovering from pandemic-era disruptions and accelerating through renewed industrial activity. Historical revenue tracking from 2020 through 2025 illustrates a market that has matured beyond volatility, establishing a firmer growth baseline. Projected forward, the forecast period spanning 2026 to 2032 anticipates a compound annual growth rate of 6.5 percent, measured in USD millions. This growth cadence reflects sustained demand from odorant applications, specialty chemical intermediates, and expanding downstream synthesis needs.
Market size evolution tells a story of incremental but compounding value creation. Revenue figures climbed steadily from the 2020 baseline, absorbed supply chain bottlenecks through 2022, and reaccelerated as manufacturing capacity stabilized and end-use sectors regained momentum. By 2025, the market reached a consolidated valuation that sets the foundation for the current forecast cycle. The 2026 projection marks the first full year of the new strategic window, offering a clear reference point for capacity planning, contract negotiations, and investment prioritization.
Importantly, this growth is not uniformly distributed across applications or production pathways. The dominant demand driver continues to center on methane odorization, where regulatory mandates and infrastructure maintenance cycles sustain inelastic consumption. Secondary application streams contribute incremental volume, while certain chemical synthesis routes retain niche but high-value positioning. Understanding the relative weight of these demand pillars is essential for any organization evaluating exposure, pricing power, or substitution risk.
Raw Material Dynamics and the Methanol Connection
Commercial production of methyl mercaptan relies fundamentally on the reaction of hydrogen sulfide with methanol, making feedstock economics a primary lever of margin structure and supply reliability. Methanol pricing volatility, therefore, translates directly into production cost sensitivity for manufacturers operating methanol-based routes. Recent trading data from mid-2026 highlights spot price levels in China reaching notable thresholds, underscoring the continued relevance of regional feedstock markets and cross-border costpass-through dynamics.
Organizations evaluating supply contracts, long-term offtake agreements, or vertical integration opportunities must account for the interplay between methanol availability, sulfur feedstock logistics, and regional production economics. The market research report dissects these input dependencies across production types, offering clarity on how methanol-based, ethanol-based, and propane-based pathways compare in cost architecture, scalability, and end-market suitability. This segmentation lens enables buyers and producers alike to anticipate margin pressure points and identify where strategic hedging or supplier diversification delivers the greatest risk-adjusted benefit.
Regulatory and Safety Imperatives Reshaping Market Behavior
Methyl mercaptan operates within a dense regulatory environment that influences storage, transportation, handling, and waste management protocols. Compliance requirements are not peripheral considerations; they are structural cost drivers and operational constraints that shape facility design, insurance exposure, and customer qualification criteria. Recent industry context confirms the continued enforcement of multiple regulatory frameworks that organizations must navigate systematically.
In the United States, methyl mercaptan is subject to the Clean Air Act Section 112(r) Risk Management Program, with threshold quantities that trigger reporting and prevention planning obligations. Occupational safety standards under OSHA establish permissible exposure limits that directly affect workplace monitoring, engineering controls, and training requirements. Additionally, environmental regulations classify the substance under hazardous waste provisions, introducing reportable quantity thresholds that impact spill response, disposal logistics, and liability management.
For manufacturers, distributors, and end-users, these regulatory layers create both risk and differentiation opportunity. Companies that invest in robust compliance infrastructure, transparent safety documentation, and advanced handling capabilities can secure preferred-supplier status with risk-sensitive customers. Conversely, organizations with weaker compliance postures may face procurement exclusion, increased insurance premiums, or operational disruptions. The full report maps these regulatory dimensions across jurisdictions, providing a comparative framework for assessing market access barriers and compliance investment priorities.
Competitive Landscape: Concentration, Capability, and Regional Footprints
The methyl mercaptan market exhibits moderate concentration, with a concentrated set of established players holding meaningful share while regional and niche manufacturers maintain active participation. This structure creates a landscape where scale advantages, technical grade differentiation, and geographic proximity to demand centers all influence competitive positioning. Understanding the strategic profiles of core participants is essential for procurement strategy, partnership evaluation, and competitive benchmarking.
Chevron Phillips Chemical Company, headquartered in The Woodlands, Texas, operates as the largest-volume producer of methyl mercaptan and positions the compound as a key specialty chemical intermediate, particularly for methionine synthesis and related applications. Its scale advantage and integrated operational footprint provide a reference point for capacity leadership and supply reliability. Arkema S.A., based in Colombes, France, maintains an active manufacturing and global supply role through its Thiochemicals platform, offering high-purity grades and sodium methyl mercaptide alternatives for methionine production. This portfolio breadth illustrates how established chemical groups leverage multi-grade offerings to serve varied customer specifications.
Evonik Industries AG, headquartered in Essen, Germany, produces methyl mercaptan within its specialty chemical portfolio, targeting animal nutrition and chemical synthesis applications. Its positioning reflects the intersection of performance chemistry expertise and downstream demand from nutrition and synthesis markets. In the India-based manufacturing segment, Vizag Chemical International, located in Visakhapatnam, functions as an active producer and exporter of methanethiol or methyl mercaptan for industrial and export markets, while Triveni Interchem Private Limited, based in Valsad, Gujarat, operates as a supplier and producer focused on chemical intermediate applications. These regional participants highlight the importance of India as a manufacturing and export hub, where cost structures, export logistics, and domestic demand interact to shape competitive dynamics.
Market concentration metrics indicate that the top three players collectively account for a meaningful share of total revenue, while the top five expand that footprint further. This concentration pattern has implications for pricing stability, negotiation leverage, and supply continuity. Buyers must evaluate whether consolidated supply relationships deliver cost and reliability benefits or whether multi-sourcing strategies better mitigate concentration risk. The report's competitive analysis section provides deeper profiling of capabilities, capacity considerations, product grade emphasis, and strategic positioning, enabling more precise supplier evaluation.
What the Full Market Research Report Delivers
Our comprehensive Methyl Mercaptan Market research study is designed as an operational intelligence tool rather than a high-level overview. It combines historical reconstruction, forward-looking forecasting, segmentation analysis, and competitive profiling into a single decision-ready framework. The following elements define the scope and practical value of the full report:
- Historical revenue reconstruction from 2020 through the base year, enabling trend validation, cycle analysis, and baseline calibration for internal forecasting models.
- Forecast projections from 2026 through 2032, structured to support capacity planning, demand forecasting, and strategic scenario modeling under varying growth assumptions.
- Segment-level analysis across production types, application categories, and geographic regions, providing relative share context and growth drivers without exposing core proprietary splits in this preview.
- Regulatory and safety environment mapping, including compliance thresholds, exposure controls, and hazardous waste considerations that affect handling costs, market access, and operational risk.
- Raw material and feedstock linkage analysis, connecting methanol and hydrogen sulfide economics to production cost structures and supply chain sensitivity.
- Competitive profiling of leading manufacturers and regional suppliers, focusing on operational scale, product grade emphasis, end-market orientation, and strategic positioning.
- Strategic implications for procurement, capacity investment, supplier diversification, and compliance planning, translated into actionable recommendations for executive and operational teams.
The full report maintains a strict focus on decision-useful detail. Rather than presenting aggregated narrative alone, it provides structured data sets, comparative tables, and analytical commentary that can be integrated into internal strategic planning processes. Regional and application-level breakdowns, pricing context, and segment growth differentials are developed with sufficient granularity to support market entry evaluation, share-gain analysis, and risk assessment.
Worldwide Mercaptans Market
Strategic Priorities for 2026 Decision-Makers
As organizations move through the 2026 planning cycle, several strategic priorities emerge from the market structure and dynamics outlined above. First, demand planning must account for the continued dominance of odorant applications while monitoring the growth contribution of chemical synthesis and specialty intermediate markets. Second, cost management strategies should incorporate feedstock volatility awareness, particularly where methanol-based production routes are exposed to regional pricing fluctuations. Third, regulatory compliance and safety infrastructure should be treated as competitive enablers, not merely operational checkboxes, given the scrutiny associated with handling, transportation, and waste management requirements.
Methyl Mercaptan Market
Fourth, supplier strategy should reflect the market's moderate concentration profile. Organizations must weigh the reliability and scale benefits of leading producers against the diversification advantages of engaging regional manufacturers and niche specialists. Fifth, forward-looking capacity and investment decisions should align with the forecast trajectory, ensuring that capital deployment matches expected demand expansion rather than lagging or overcommitting relative to market cadence.
These priorities are interconnected. A shift in feedstock economics can alter supplier competitiveness. A change in regulatory enforcement can affect regional market access. Evolving demand patterns can shift the relative attractiveness of specific production types or application segments. The full market research report connects these threads into a coherent strategic narrative, giving executives the context needed to anticipate rather than react.
Accessing the Complete Intelligence Suite
This preview has outlined the structural framework, competitive context, regulatory considerations, and strategic priorities that define the methyl mercaptan market entering the 2026–2032 period. The macro growth trajectory, feedstock sensitivities, regulatory obligations, and competitive concentration patterns collectively establish a market environment where informed decision-making delivers measurable advantage.
To move from strategic context to detailed execution intelligence, organizations require segment-level data, regional comparisons, application-specific demand analysis, and supplier capability profiling at a depth that supports procurement negotiation, capacity planning, and market entry evaluation. The complete PW Consulting Methyl Mercaptan Market research report provides that comprehensive intelligence package, combining rigorous data architecture with practical strategic interpretation.
For executives and analysts seeking to translate market dynamics into concrete action plans, the full report offers the granularity and structure needed to support confident decision-making. We invite you to access the complete research deliverable for detailed segmentation, regional breakdowns, competitive profiling, and forward-looking analysis designed to strengthen your strategic positioning throughout the forecast period.
For detailed analysis of this topic, please visit the official page: Methyl Mercaptan Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: HNBR Hits $535M in 2025, Projects 7.45% CAGR to $883M by 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Next Decade: Inside the Global HNBR Market Outlook 2026–2032
As industrial manufacturers navigate an increasingly complex landscape of material performance requirements, regulatory shifts, and supply chain volatility, the Hydrogenated Nitrile Butadiene Rubber (HNBR) sector has emerged as a critical enabler of high-durability engineering solutions. PW Consulting is pleased to introduce our latest comprehensive market study, designed to equip strategy leaders, procurement directors, and R&D teams with the actionable intelligence needed to make confident decisions in 2026 and beyond. This report distills a rigorous five-year historical analysis and a seven-year forward projection into a structured, decision-ready format that bridges material science, commercial dynamics, and competitive strategy.
A Market at a Narrative Inflection Point
The global HNBR market has demonstrated consistent expansion over the past half-decade, evolving from a specialized elastomer niche into a cornerstone material for demanding sealing, fluid transport, and high-stress industrial applications. Drawing on verified shipment data, capacity disclosures, and price-tracking mechanisms, our analysis captures the trajectory from a baseline exceeding 535 million USD in 2025, with forward momentum accelerating through the second half of the decade. The compound annual growth rate projected across the 2026 to 2032 window reflects steady mid-single-digit expansion, driven by sustained demand from automotive powertrain evolution, energy sector reliability mandates, and industrial automation scaling.
This growth narrative is not uniform. Regional capacity investments, raw material corridors, and application-specific performance thresholds create divergent value pools that require targeted commercial strategies. Our report maps these structural shifts without resorting to surface-level summaries, instead providing decision-makers with the analytical scaffolding needed to prioritize geographic entry, capacity alignment, and product-mix optimization. By anchoring forecasts in transparent methodological assumptions and cross-validated supply-side indicators, we ensure that leadership teams can stress-test their strategies against multiple demand-and-supply scenarios.
What the Study Delivers: Decision-Ready Architecture
The HNBR Market Research report is structured to translate macro trends into executable insights. Rather than delivering a static data repository, the study is organized around the operational questions that shape capital allocation, supplier selection, and product roadmap planning. Readers will find a detailed examination of market sizing and forecasting frameworks, a breakdown of the principal grade categories that define competitive positioning, and a granular application mapping that connects end-use requirements to material selection criteria.
Each section is designed to support cross-functional alignment. Commercial teams will benefit from pricing trajectory analysis, capacity utilization indicators, and regional supply-demand balancing assessments. Technical and procurement stakeholders will find materials performance context, substitution dynamics, and regulatory influence mapping that clarify total cost-of-ownership considerations. Corporate development and investor relations groups will gain visibility into consolidation patterns, capacity expansion timelines, and the strategic implications of changing feedstock economics.
To maintain analytical rigor, the report integrates recent market developments directly into its forward-looking assessments. Capacity additions, production technology upgrades, pricing recalibrations, and product launches are evaluated not as isolated events but as components of a shifting competitive equilibrium. This approach allows readers to understand how individual corporate moves alter supply elasticity, influence regional price formation, and reshape customer procurement behavior.
Competitive Landscape: Leadership, Expansion, and Differentiation
The HNBR supply base is characterized by a concentrated group of established producers alongside regional players pursuing scale, cost efficiency, and application-specific differentiation. At the forefront of the global market stands Arlanxeo, headquartered in The Hague, Netherlands, recognized as the world's largest HNBR producer with an annual capacity approaching 16,000 tons. Its Therban grades serve automotive, oil and gas, and industrial sealing applications, and the company continues to reinforce its leadership through strategic capacity investments. In February 2026, Arlanxeo inaugurated a new 5,000 ton-per-year HNBR unit in Changzhou, China, backed by a 210 million USD investment and an oxidation process designed to reduce emissions by 80 percent, signaling a dual focus on scale and sustainability.
Hydrogenated Nitrile Butadiene Rubber (HNBR) Market
Nitrile Rubber (NBR) Market
Alongside this incumbent strength, Japanese material specialists maintain a strong presence through technology-driven product differentiation. ZEON Corporation, based in Tokyo, operates a 12,500 ton annual capacity and is known for its Zetpol grades tailored to extreme-temperature and aerospace applications. The company confirmed an expansion of its Zetpol production at its Pasadena, Texas facility, increasing global capacity by approximately 25 percent with completion targeted for early 2025. Kuraray Co., Ltd., also headquartered in Japan, supplies specialty elastomers under its own brand for high-temperature industrial and automotive applications, while JSR Corporation emphasizes high-performance grades for automotive and industrial use. Tosoh Corporation contributes additional depth to the Japanese specialty elastomer ecosystem with high-performance industrial and automotive HNBR offerings.
In South Korea, LG Chem manufactures HNBR under the Krynac brand, targeting oil-resistant and heat-stable applications with consistently high-quality grades. The competitive field also includes a growing set of Chinese producers who are expanding capacity and pursuing both domestic and export-market opportunities. Shandong Dawn Special Elastomer Material Co., Ltd. currently operates at 1,000 tons with plans to reach 3,000 tons, utilizing ruthenium catalysts and supplying both domestic and international channels; in June 2024, the company launched enhanced thermal stability HNBR polymers for high-performance applications. Sinopec Qilu Petrochemical brings low-cost, high-conversion capacity with conversion rates at or above 99 percent for industrial and automotive uses. Zannan SciTech Co., Ltd. continues to expand its presence through competitive pricing and an explicit focus on international market supply.
Compounding and distribution capabilities further shape the market's value chain. Rahco Rubber, Inc., based in the United States, operates as a compounder and distributor of HNBR for custom molded and extruded parts in seals, gaskets, and actuators, adding downstream flexibility for end-users requiring tailored formulations. Together, these players create a dynamic competitive environment where technology leadership, cost structure, regional proximity, and application specialization determine market share trajectories.
Market Dynamics: Cost, Regulation, and Demand Signals
HNBR pricing and procurement behavior do not evolve in isolation. They respond to raw material cost dispersion, regional inventory positioning, geopolitical feedstock disruptions, and regulatory substitution trends. Spot butadiene prices highlighted a significant regional gap in May 2025, ranging from 956 USD per ton in the US Gulf to 1,380 USD per ton in China, a 44 percent spread that directly influenced HNBR production cost structures and export competitiveness. Earlier, in February 2024, HNBR prices experienced a notable surge in the US market driven by strong demand, while Q1 2026 data showed North American prices rising by 2.39 percent quarter-over-quarter, reflecting inventory levels and near-term supply-demand balancing.
Feedstock volatility remains a persistent strategic consideration. Middle East conflict disruptions have increased naphtha and LPG feedstock costs, triggering volatility in NBR and HNBR production expenses and reminding buyers that input-cost sensitivity must be managed through contract design, sourcing diversification, and inventory planning. On the regulatory frontier, DuPont filed a PFAS-restriction dossier in March 2024 that named hydrogenated nitrile butadiene rubber as a non-fluorinated substitute for selected sealing duties. This type of regulatory reference reinforces HNBR's positioning as a high-performance alternative in applications where fluorinated materials face increasing scrutiny, expanding the material's relevance across both existing and emerging sealing requirements.
Beyond cost and regulation, competitive actions continue to reshape market conditions. In March 2025, Kingfa announced price adjustments for specialty elastomers including HNBR across multiple polymer categories, underscoring the interconnected nature of the elastomer landscape and the need for buyers to monitor broader polymer pricing signals. Taken together, these dynamics illustrate why static assumptions quickly become unreliable. Strategy teams require forward-looking, event-linked analysis that connects capacity moves, feedstock variability, pricing behavior, and regulatory developments into a coherent operating framework.
Structural Concentration and the Implications for Strategy
Market concentration remains a defining feature of the HNBR landscape. The leading producers collectively hold a substantial share of global capacity, creating a competitive environment where scale, process efficiency, and product differentiation carry disproportionate weight. High top-tier concentration often translates into pricing resilience for established suppliers, but it also intensifies the importance of customer-specific service, regional supply reliability, and technological edge. Buyers and investors alike must therefore assess not only headline market size but also the distribution of capacity, the accessibility of specialty grades, and the evolution of regional supply nodes.
Our report examines these concentration dynamics with a focus on practical implications. For procurement leaders, the analysis highlights where dual-sourcing, long-term agreements, and formulation flexibility can reduce exposure to concentrated supply risk. For corporate strategy and M&A teams, it clarifies where consolidation pressure may intensify and where regional expansion can create differentiated value. For R&D and product management groups, it identifies the performance thresholds and grade distinctions that separate commodity-adjacent offerings from premium high-performance solutions.
Why This Research Matters for 2026 Decision-Making
The 2026 decision environment calls for more than retrospective summaries. Materials strategy now intersects with decarbonization commitments, regional supply-chain reconfiguration, regulatory substitution pressure, and rapidly shifting demand profiles across automotive, energy, and industrial end markets. In that context, a well-constructed market study becomes a strategic asset rather than a reference document. It enables leadership to anticipate where capacity will be added, how pricing may respond to feedstock and demand fluctuations, which grades will capture premium positioning, and how regulatory signals may redirect material selection trends.
This publication is designed to support those decisions with clarity and discipline. It combines rigorous forecasting methodology with real-world corporate developments and supply-chain context, allowing readers to move from broad market awareness to specific, scenario-informed action. Whether the objective is to evaluate supplier consolidation risk, plan regional sourcing adjustments, align product roadmaps with performance requirements, or assess investment opportunities in high-growth application segments, the report provides the evidentiary basis needed to proceed with confidence.
Accessing the Full Intelligence Package
The overview presented here reflects the analytical direction and structural approach of the complete study, but the full strategic value resides in the detailed segmentation, company-level assessments, regional supply-demand balancing, pricing trajectory analysis, and scenario modeling included in the final report. To explore the complete market sizing framework, competitive benchmarking, application-specific growth drivers, and forward-looking strategic recommendations, we invite you to access the full report on the PW Consulting website. The complete intelligence package is structured for immediate use by strategy, procurement, technical, and corporate development teams seeking to align their 2026 plans with a clear and substantiated view of the HNBR market's trajectory through 2032.
For detailed analysis of this topic, please visit the official page: Hydrogenated Nitrile Butadiene Rubber (HNBR) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Bromine Market to Hit $4.47 Billion by 2032, 5.5% CAGR
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Bromine Market: Navigating Growth and Volatility Through 2032
As global industrial ecosystems evolve, the strategic importance of halogen supply chains has never been more pronounced. Bromine, a critical element underpinning sectors ranging from flame retardancy to pharmaceutical synthesis, is entering a transformative phase. PW Consulting is pleased to introduce our latest comprehensive market research publication, designed specifically to equip enterprise leaders with the actionable intelligence needed to navigate the 2026-2032 forecast horizon. This article serves as a strategic preview, outlining the macro trajectory, competitive contours, and dynamic forces that define the bromine landscape, while demonstrating the depth of analysis available in the full report.
Macro Trajectory and Growth Vectors
The bromine market is demonstrating resilient expansion, driven by entrenched demand in industrial safety and emerging applications in life sciences. Our analysis tracks revenue progression from a historical base of approximately 2,200 million USD in 2020 to a projected valuation of nearly 3,100 million USD in 2025. This foundation supports a conservative yet robust forecast period extending through 2032, where market valuations are anticipated to surpass 4,400 million USD.
Central to this outlook is a compound annual growth rate of 5.5 percent over the forecast window. This growth rate is not merely a statistical projection; it reflects underlying structural shifts in global manufacturing and resource allocation. The trajectory suggests that while cyclical pressures exist, the fundamental demand drivers remain intact, offering a stable environment for long-term capital planning. However, achieving optimal positioning within this growth curve requires nuanced understanding of regional supply dynamics and application-specific consumption patterns, details of which are granularly mapped in the complete study.
Competitive Landscape and Strategic Positioning
The industry is characterized by a concentrated oligopoly, where scale, geographic access to brine resources, and vertical integration dictate competitive advantage. The CR3 and CR5 concentration metrics indicate that a small cadre of global players controls the majority of market share, creating high barriers to entry and stabilizing pricing structures to a degree. This concentration underscores the importance of supply chain security for downstream users who cannot easily switch sources without operational risk.
Key incumbents define the strategic boundaries of the market. Albemarle Corporation, headquartered in Charlotte, North Carolina, remains one of the world's largest producers and distributors, offering elemental bromine and derivatives for diverse industrial and pharmaceutical applications. Their recent strategic moves highlight the trend toward securing upstream resources. Similarly, ICL Group Ltd, based in Tel Aviv, stands as a major global supplier extracting bromine from Dead Sea brines, with a strong focus on industrial solutions. LANXESS AG in Cologne continues to be a pivotal producer of organobromines essential for flame retardants and chemical intermediates, while Tosoh Corporation in Tokyo serves the organic chemicals and pharmaceutical sectors.
The competitive field also includes significant regional players and specialized manufacturers. Gulf Resources Inc. in China leads in export and production from natural brines. TETRA Technologies Inc. in the United States focuses on energy and oilfield applications. The Indian market features strong contenders such as Tata Chemicals Limited, Hindustan Salts Limited, Agrocel Industries Pvt. Ltd., Archean Chemical Industries Ltd., and Solaris ChemTech Industries Ltd., each carving niches in technical bromine, hydrobromic acid, agrochemicals, and high-purity pharmaceutical offerings. In Jordan, Jordan Bromine Company Ltd. operates as an exclusive producer supplying industrial and pharmaceutical grades, while Chemada Fine Chemicals in Israel specializes in intermediates. Honeywell International Inc. rounds out the landscape as a supplier for performance materials and industrial chemicals.
Lithium Bromide Market
The full report provides an in-depth profiling of these entities, analyzing their operational capacities, strategic alliances, and vulnerability to supply shocks. Understanding the relative strength of these competitors is vital for benchmarking and partnership strategies, yet the specific competitive assessment matrices and proprietary scoring models are reserved for subscribers seeking a decisive edge.
Recent Developments Shaping Industry Dynamics
Strategic maneuvering and product innovation are rapidly altering the market topology. In July 2025, Lupin Limited launched an Ipratropium Bromide Nasal Solution in the United States, introducing a bioequivalent to Atrovent Nasal Spray. This product launch exemplifies the downstream impact of bromine derivatives in healthcare, signaling sustained demand from the pharmaceutical sector for bromine-based active ingredients and formulations.
On the supply side, January 2025 marked a significant development when Arab Potash Company and Albemarle Corporation signed a joint investment agreement to expand bromine production capacity at Jordan Bromine Company. This collaboration highlights the strategic imperative to secure and expand production capabilities in key resource regions, mitigating long-term supply risks and reinforcing the integrated nature of major players operating across geographies.
These events are not isolated; they are symptomatic of broader trends that our report dissects in detail. For instance, the focus on capacity expansion in Jordan must be contextualized against the geopolitical and environmental headwinds facing other production hubs. The full intelligence brief connects these dots, offering a forward-looking assessment of how such developments will ripple through pricing, availability, and competitive power over the forecast period.
Market Dynamics: Raw Materials, Regulations, and Macro Trends
The bromine market does not operate in a vacuum; it is heavily influenced by raw material geography, regulatory frameworks, and macroeconomic shifts. A critical constraint is the dependence on natural brine resources, which are geographically concentrated. This concentration means that supply disruptions in specific regions can have outsized effects on production stability and manufacturing costs, particularly for high-value pharmaceutical intermediates that require consistent purity and availability.
Recent operational contexts illustrate these vulnerabilities. ICL Group and Jordan Bromine Company operations at the Dead Sea have faced tightening supply conditions. Environmental pressures related to water levels, coupled with brief disruptions stemming from the June 2025 Israel-Iran conflict, have introduced volatility into a traditionally stable supply node. This episode serves as a reminder of the geopolitical risk premium embedded in global chemical supply chains.
Bromine Market
Conversely, regulatory actions in China are reshaping regional dynamics. Environmental regulations in Shandong have tightened brine operations, contributing to declining domestic production and exerting upward pressure on prices for bromine used in pharmaceutical and specialty chemical synthesis. This regulatory tightening forces a re-evaluation of sourcing strategies for manufacturers reliant on Chinese intermediate supplies. Meanwhile, U.S. bromine production in Arkansas continues to provide a counterbalance. Operations by Albemarle Corporation and LANXESS in this region offer stable supply streams, effectively insulating North American buyers from the global price volatility driven by overseas brine processing and energy cost fluctuations. This bifurcation of supply stability between the U.S. and certain international sources presents a clear strategic choice for procurement and manufacturing footprint decisions.
On the demand side, macro trends are accelerating consumption. Rising pharmaceutical manufacturing activity in India and China is driving increased uptake of bromine derivatives. This includes synthesis for sedatives, antiseptics, and cancer treatments, areas where bromine chemistry remains indispensable. The growth in these therapeutic areas suggests that the life sciences segment will be a persistent growth engine, though the specific volume contributions and growth rates by therapeutic class are analyzed in depth within the report's application segmentation modules. Furthermore, the broader industrial base, including oil and gas drilling fluids and water treatment biocides, continues to consume significant volumes, though the interplay between energy market cycles and drilling activity adds complexity to demand forecasting for these segments. The full report disentangles these application-level dynamics, providing clear visibility into where demand is most resilient and where it is most sensitive to external shocks.
The Strategic Value of Deep-Dive Intelligence
For enterprise decision-makers in 2026, the bromine market presents a matrix of opportunities and risks. The 5.5 percent CAGR offers a backdrop of growth, but realizing value requires navigating geographic supply asymmetries, regulatory shifts, and a concentrated competitive field. Superficial market data cannot support the precision required for capacity planning, M&A evaluation, or supply chain redesign.
PW Consulting's Bromine Market Research delivers the granularity necessary to turn macro trends into micro strategies. The report goes beyond aggregate numbers to provide:
- Detailed segmentation analysis that isolates demand drivers and growth rates across applications, revealing which specific use cases are expanding fastest and which face headwinds.
- Regional supply and demand balances that help identify arbitrage opportunities and logistics risks, allowing for optimized sourcing and inventory strategies.
- Competitor profiling that maps strategic capabilities, recent moves, and potential vulnerabilities of key players, enabling better positioning relative to the oligopoly.
- Scenario analysis incorporating raw material constraints, regulatory trajectories, and geopolitical factors to stress-test business plans against plausible future states.
- Actionable recommendations for stakeholders across the value chain, from producers looking to optimize asset utilization to end-users seeking to mitigate supply volatility.
The excerpt provided here offers a high-level view of the market's architecture and the forces at play. However, the full report contains the specific data points, proprietary models, and forward-looking assessments that drive confident decision-making. To access the complete segmentation breakdowns, regional revenue trajectories, and detailed competitive intelligence, we invite you to visit the source page for the full market research package. In a market defined by concentration and complexity, the depth of insight is the differentiator between reactive management and strategic leadership.
For detailed analysis of this topic, please visit the official page: Bromine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Silica Gel Market Hits $215M in 2025, Projected 6.98% CAGR to $344.79M by 2032
By pmarketresearch, 2026-09-15
Strategic Imperatives in the Silica Gel Desiccant Market: A 2026 Outlook for Executive Decision-Makers
The global silica gel desiccant market stands at a critical inflection point as the industry transitions from steady post-pandemic growth into a more complex operating environment defined by raw material volatility, regulatory tightening, and accelerated automation. Our newly released Silica Gel Desiccant Market study maps this trajectory from a 2025 base year through a forecast period extending to 2032, delivering the analytical rigor that procurement leaders, supply chain architects, and corporate strategists require to navigate the next phase of market evolution.
The market closed 2024 at approximately 198.43 million USD and crossed the 215.0 million USD threshold in 2025, reflecting sustained demand pull across moisture-sensitive end-use sectors. The trajectory through 2026 places the market at an estimated 225.4 million USD, with the forecast window projecting a compound annual growth rate of 6.98 percent that carries the sector toward 344.79 million USD by 2032. This growth is not merely a function of incremental volume expansion; it reflects structural shifts in packaging automation, pharmaceutical compliance requirements, electronics miniaturization, and food safety expectations that are reshaping how desiccants are specified, manufactured, and integrated into downstream production lines.
For executives making capital allocation, supplier qualification, and geographic expansion decisions in 2026, the strategic question is no longer whether the market is growing, but where value will concentrate, which capability gaps will separate winners from laggards, and how cost structures will respond to feedstock dynamics. The following analysis outlines the market architecture, competitive contour, and operational dynamics that our study unpacks in granular detail, while preserving the specific breakdowns and quantified regional and segment insights reserved for the full report.
Market Architecture and the Growth Trajectory
The historical record from 2020 through 2025 establishes a clear pattern of resilience and incremental acceleration. After reaching 153.44 million USD in 2020, the market advanced to 166.72 million USD in 2021, 178.26 million USD in 2022, and 192.52 million USD in 2023. The 2024 to 2025 step-up from 198.43 million USD to 215.0 million USD signals a market that has absorbed pandemic-era supply disruptions and is now being driven by durable end-use demand rather than temporary inventory restocking.
The forward path from 2026 through 2032 reflects a market that continues to expand but does so against a backdrop of operational recalibration. The forecast series moves from 225.4 million USD in 2026 to 239.42 million USD in 2027, then steps more steeply toward 266.22 million USD in 2028, 271.81 million USD in 2029, and 292.34 million USD in 2030. The upper end of the window reaches 315.07 million USD in 2031 and 344.79 million USD in 2032. This profile suggests that growth will not be linear; rather, it will be punctuated by capacity decisions, compliance-driven specification changes, and regional demand shifts that create pockets of accelerated adoption alongside more modest expansion elsewhere.
Silica Gel Orange Desiccant Market
The concentration metrics embedded in the study underscore a market dominated by a relatively small group of scaled incumbents, with a three-firm concentration ratio of 68.2 percent and a five-firm concentration ratio of 82.4 percent. This level of consolidation has direct implications for pricing power, supplier diversification strategies, and the barriers that new entrants must clear to gain meaningful share. Commercial leaders evaluating channel partnerships, private-label arrangements, or backward integration need a clear read on how this concentration interacts with regional demand patterns and segment-specific specification requirements, which the full report addresses through detailed segmentation mapping.
Silica Gel Desiccant Market
Competitive Contours: Incumbents, Innovation, and Capacity Reconfiguration
The competitive landscape is defined by a cohort of established manufacturers that combine chemical processing expertise with application-specific desiccant engineering. Clariant AG, headquartered in Muttenz, Switzerland, manufactures Sorb-It silica gel desiccants and continuous strip desiccant packets designed for automated high-speed packaging lines. W.R. Grace & Co., based in Columbia, Maryland, produces silica gel desiccants and specialty silica solutions for pharmaceutical, packaging, and industrial moisture control applications. Evonik Industries AG, with its headquarters in Essen, Germany, offers AEROSIL and related silica gel products serving desiccant and moisture-protection uses in electronics packaging and pharmaceutical contexts.
Multisorb Technologies, located in Buffalo, New York, specializes in engineered silica gel desiccants and packets for pharmaceutical, food, and industrial packaging. Fuji Silysia Chemical Ltd., headquartered in Tokyo, develops and supplies synthetic silica gel for desiccant applications in chromatography, catalysts, and moisture control. Sorbent Systems, based in Cincinnati, Ohio, provides custom silica gel desiccants in bags and packets for flexible, printed packaging solutions. Desiccare, Inc., also in Cincinnati, manufactures indicating and non-indicating silica gel desiccants for industrial, food, and pharmaceutical use. AGM Container Controls, headquartered in Liverpool, New York, supplies silica gel desiccants in bags for containers, enclosures, and military and aerospace applications.
Recent developments through early 2026 illustrate how this group is positioning itself for the next growth cycle. In April 2026, Clariant AG launched continuous strip desiccant packets on reels for automated high-speed packaging lines, including Sorb-It silica gel strips with AI-based quality inspection and sustainability features. This move signals a push toward line integration, inspection consistency, and packaging sustainability that aligns with the broader industry shift toward automated production and compliance-ready materials. In January 2026, Evonik Industries AG commissioned a new Easy-to-Disperse fumed silica plant to support ongoing capacity growth for AEROSIL silica products including desiccant applications, reinforcing the link between upstream silica processing capability and downstream desiccant availability.
These actions do not occur in isolation. The market's concentration profile means that capacity decisions by a handful of suppliers can materially affect regional supply balance, specification availability, and lead-time reliability. Our study evaluates how these players are structuring their product portfolios, where they are investing in automation and quality systems, and how their geographic footprints intersect with demand centers. The complete competitive assessment, including relative positioning by type and application intensity, is detailed in the full report to support supplier selection and negotiation strategy.
Market Dynamics: Raw Materials, Regulation, and Sustainability Pressures
The operating environment in 2026 is shaped by a convergence of input cost pressure, regulatory evolution, and sustainability expectations that together redefine cost-to-serve and specification risk. On the raw material side, sodium silicate feedstock prices for silica gel production rose sharply in the fourth quarter of 2025, prompting manufacturers to pass through higher production costs. This dynamic introduces direct margin sensitivity for suppliers and procurement complexity for buyers, particularly where long-term contracts, volume commitments, and alternative specification pathways must be re-evaluated in light of input cost trajectories.
Regulatory alignment is increasingly a specification determinant rather than a compliance afterthought. Continuous strip desiccants now incorporate FDA and EU-compliant materials along with USP <670> options for nutraceutical and pharmaceutical packaging. This extends the strategic relevance of desiccant selection beyond moisture control alone, embedding it within broader quality systems and audit-ready documentation requirements. Clariant's strip desiccants support ISO-certified facilities and AI inspection for consistent quality across Americas and EMEA operations, reinforcing the connection between automation, inspection consistency, and regulatory conformity. At the same time, Evonik is optimizing production by closing two U.S. silica sites by mid-2026 as part of capacity reconfiguration, a move that illustrates how compliance, efficiency, and capacity strategy are being realigned in real time.
Sustainability is similarly moving from an aspiration to an operational requirement. Desi Pak ECO continuous strip packets feature plastic-free bio-based packaging and reclaimed mining sites to reduce environmental impact. For brands and manufacturers under pressure to reduce packaging waste and improve the environmental profile of moisture-control components, these attributes can become differentiators in supplier evaluation and customer-facing value propositions. The intersection of regulatory compliance, feedstock cost, and sustainability design creates a dynamic where specification decisions carry both cost and reputational consequences. Our study dissects these forces across the forecast horizon, providing the scenario context needed to anticipate how cost pass-through, compliance adoption, and eco-oriented product design will influence segment performance and regional demand, with full quantified segmentation reserved for the complete report.
Real-World Applications Across Pharmaceuticals, Food, Electronics, and Beyond
The strategic relevance of silica gel desiccants is rooted in their role as enabling components in sectors where moisture control directly affects product integrity, shelf life, and regulatory acceptability. In pharmaceuticals, desiccants support stability, packaging compliance, and manufacturing consistency, making them integral to formulations, secondary packaging, and distribution environments where moisture excursions can compromise efficacy or trigger quality events. In food packaging, moisture management intersects with preservation, safety, andconsumerexpectations around freshness, while in electronics, desiccants help protect sensitive components against humidity-related degradation during storage, transport, and assembly. The broader application base extends across industrial and specialty uses where moisture control remains a critical but often under-specified variable.
This application diversity means that market growth is not uniform across end uses; rather, it is shaped by differing compliance burdens, packaging formats, automation maturity, and regional demand rhythms. The interaction between application requirements and desiccant type, packet format, and indicating versus non-indicating variants creates a multi-dimensional decision space for procurement and product development teams. Our report maps these application-driven demand patterns and their implications for supplier capability, format selection, and specification strategy, while withholding the precise segment splits to preserve the full analytical detail for the downloadable study.
What the Full Study Delivers for 2026 Decision-Making
This market research is designed to convert macro trajectory and competitive context into actionable decision support. The full report includes a comprehensive segmentation analysis that isolates demand patterns by region and by type, enabling readers to assess where growth is concentrated and how product format preferences differ across markets. It also provides an application-level view that connects end-use requirements to specification logic, helping teams align desiccant selection with packaging architecture, compliance needs, and automation readiness.
Beyond segmentation, the study delivers a structured competitive assessment of the core companies shaping the market, including their product orientations, recent strategic moves, and implications for supply reliability and specification availability. The report incorporates a forward-looking dynamics section that traces how raw material cost movements, regulatory compliance pathways, and sustainability-oriented product design are likely to influence pricing, sourcing, and portfolio strategy through the forecast period. Historical performance from 2020 through 2025 is analyzed alongside the 2026 to 2032 outlook to give executives a coherent baseline for scenario planning, investment timing, and supplier negotiations.
For organizations evaluating market entry, capacity expansion, private-label partnerships, or regional sourcing shifts, the study provides the structured evidence base needed to move beyond anecdote and into quantified, segment-aware decision-making. The complete regional and type-based breakdowns, along with detailed application splits and company-level positioning, are presented in full within the report to support precise strategic action.
Conclusion: Turning Market Intelligence into Advantage
The silica gel desiccant market is entering a period in which growth, concentration, and operational complexity intersect. With the market expanding from 215.0 million USD in 2025 toward an estimated 344.79 million USD by 2032 at a compound annual growth rate of 6.98 percent, the opportunity is substantial, but so is the need for disciplined analysis. Raw material cost pressure, regulatory specification changes, sustainability-driven product innovation, and capacity reconfiguration among leading suppliers all point to a market where strategic advantage will accrue to organizations that understand not only the size of the opportunity, but the structure of the demand behind it.
This study provides that structure. It translates historical performance, forward forecasts, competitive actions, and industry dynamics into a decision-ready framework for 2026 and beyond. To access the full segmentation, complete competitive profiles, and detailed regional and type-based insights that underpin this outlook, download the full Silica Gel Desiccant Market report and equip your team with the intelligence needed to act with precision.
For detailed analysis of this topic, please visit the official page: Silica Gel Desiccant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Dewatering Pump Market to Hit $12,010 Million by 2032 at 6.4% CAGR
By pmarketresearch, 2026-09-15
Navigating the Future of Fluid Management: Strategic Insights from the 2026 Dewatering Pump Market Report
Executive Summary
In an era where infrastructure resilience and environmental compliance define operational success, the dewatering pump market stands as a critical backbone for global industrial activity. As we move deeper into 2026, stakeholders across construction, mining, and municipal sectors face a complex landscape shaped by shifting regulatory frameworks, technological advancements, and evolving power dynamics. PW Consulting's latest comprehensive study on the Dewatering Pump Market is not merely a collection of statistics; it is a strategic roadmap designed to guide enterprise decision-makers through the volatility and opportunity of the forecast period spanning 2026 to 2032.
This article serves as a preliminary insight into the depth and breadth of our upcoming research. It outlines the macro-economic trajectory, the competitive intensity, and the regulatory pressures that will define the next seven years. However, to truly capitalize on these trends, organizations require granular data that goes beyond high-level summaries. Our full report offers the precise segmentation and actionable intelligence necessary to refine procurement strategies, identify partnership opportunities, and mitigate risk.
Macro-Economic Trajectory and Growth Dynamics
The historical performance of the dewatering pump sector provides a robust foundation for confidence in future growth. Between 2020 and 2025, the market demonstrated a consistent upward trajectory, recovering from global disruptions and capitalizing on intensified infrastructure spending. Our analysis indicates that the market revenue, denominated in USD Million, has shown resilience despite supply chain constraints and fluctuating raw material costs. The total market size has expanded significantly over the last half-decade, reflecting the essential nature of water management in industrial processes.
Looking toward the forecast period from 2026 through 2032, the growth momentum is expected to accelerate. The projected Compound Annual Growth Rate (CAGR) of 6.4% underscores a healthy expansion phase driven by urbanization and resource extraction demands. By the end of the forecast window, the market volume is anticipated to reach new highs, surpassing current baselines substantially. This growth is not uniform; it is contingent upon specific technological adoptions and regional infrastructural developments which are detailed extensively in the full intelligence dossier.
Water Pumps Market
For strategic planners, understanding the velocity of this growth is crucial. A steady increase suggests sustained demand, but the nuances lie in the timing of peaks across different segments. Our report dissects these timelines to help clients align their capacity planning and inventory management with market rhythms. Without access to the specific year-over-year breakdowns provided in the complete study, businesses risk misaligning their capital expenditure with actual market demand surges.
Regulatory Pressures and Environmental Compliance
One of the most significant drivers reshaping the competitive landscape is the tightening grip of environmental regulation. In the United States, frameworks established by the Environmental Protection Agency (EPA) are compelling mining operators and construction firms to adopt sustainable water management practices. These regulations are not merely suggestions; they mandate the adoption of environmentally compliant dewatering systems often equipped with real-time monitoring capabilities. Failure to adhere can result in substantial fines and operational shutdowns, making compliance a priority over cost minimization.
Similarly, in the European Union, the Water Framework Directive and REACH chemical regulations are enforcing strict standards on discharge quality and filtration systems. These directives require industries to integrate advanced filtration into their dewatering processes, influencing the type of equipment purchased. The regulatory environment is pushing the market toward systems that minimize ecological impact while maintaining operational efficiency. Our analysis explores how these regulatory shifts create barriers to entry for non-compliant manufacturers while offering opportunities for innovators who can integrate smart monitoring and filtration technologies.
Technological Shifts: The Energy Transition and Power Sources
The source of power for dewatering equipment is undergoing a transformative shift. Historically, diesel engines have been the workhorse for remote construction and mining sites due to their portability and power density. However, progressive tightening of diesel engine emissions standards in both construction and mining sectors is adding compliance costs and driving a transition toward electric or hybrid alternatives. This shift is reshaping the demand curve for different power source categories within the market.
Electric solutions are gaining traction, particularly in areas where grid connectivity is reliable or where battery technology has advanced enough to support mobile operations. Hydraulic systems continue to hold relevance in specific heavy-duty applications where pressure and durability are paramount. Understanding the balance between these power sources is vital for suppliers and purchasers alike. The full report provides a detailed breakdown of how each power source segment is expected to perform, considering factors such as fuel costs, availability, and regulatory penalties.
Competitive Landscape and Key Industry Players
The market is characterized by a consolidated yet competitive environment. Our concentration analysis indicates that a handful of major players hold a significant share of the total revenue, creating a landscape where strategic positioning is key to maintaining market share. The top three competitors collectively account for a substantial portion of the market, while the top five extend their influence further. This concentration suggests that partnerships, mergers, and acquisitions could play a pivotal role in the coming years as companies seek to expand their technological portfolios and geographic reach.
Dewatering Pump Market
Several key companies define the current state of the industry, each bringing unique strengths to the table:
- Xylem Inc. (Stamford, Connecticut, USA): A dominant force leveraging brands like Godwin Dri-Prime and Flygt to serve construction, mining, and municipal sectors with a focus on intelligent water solutions.
- Sulzer Ltd. (Winterthur, Switzerland): Known for their JC/XJC and J/XJ centrifugal submersible pumps, alongside smart AquaTronic controls, catering heavily to mines and tunnels.
- Grundfos Holding A/S (Bjerringbro, Denmark): Provides robust submersible and centrifugal solutions specifically targeted at construction and industrial wastewater handling.
- Atlas Copco AB (Stockholm, Sweden): Their WEDA submersible electric range is a staple in mining and tunneling applications, emphasizing efficiency and durability.
- Tsurumi Manufacturing Co., Ltd. (Tokyo, Japan): Offers specialized submersible dewatering and slurry pumps critical for construction and wastewater projects.
- Gorman-Rupp Company (Mansfield, Ohio, USA): Focuses on centrifugal and self-priming pumps for municipal and industrial use, maintaining a strong legacy in the sector.
- Weir Group PLC (Glasgow, Scotland, UK): Specializes in dewatering and slurry pumps for demanding mining and industrial applications.
- KSB SE & Co. KGaA (Frankenthal, Germany): Delivers submersible and centrifugal pumps for construction and industrial sites, recently innovating with energy-efficient designs.
- Ebara Corporation (Tokyo, Japan): Provides submersible and dry-pit pumps essential for wastewater and industrial applications.
- Wilo SE (Dortmund, Germany): Focuses on submersible and centrifugal pumps for municipal and industrial water management.
- Pioneer Pump (Franklin Electric) (McAlester, Oklahoma, USA): Recently expanded their portfolio with NSF/ANSI 61-certified lines and diesel-driven packages, alongside a new service network.
- Flowserve Corporation (Irving, Texas, USA): Serves industrial and process applications with centrifugal and submersible solutions.
- Wacker Neuson SE (Munich, Germany): Geared heavily toward construction and infrastructure projects with specialized submersible units.
Recent developments highlight the dynamism of this group. For instance, in early 2026, KSB introduced the Omega 2 next-generation axially split volute casing pump, emphasizing improved hydraulic performance and energy efficiency. Similarly, Pioneer Pump launched an Expert Services Network in February 2026, offering factory-certified on-site service and 24/7 support, signaling a shift toward service-led revenue models alongside hardware sales. These moves indicate that competition is no longer just about pump specs; it is about lifecycle support and efficiency certifications.
Application Segments and Industry Use Cases
The demand for dewatering pumps is distributed across several critical application verticals. Construction remains a primary driver, where excavation sites require continuous water removal to ensure safety and progress. Mining follows closely, where large-scale operations depend on effective slurry and water handling to maintain throughput. Municipal wastewater management is another crucial segment, driven by the need to upgrade aging infrastructure and meet stricter discharge standards.
Additionally, the Oil and Gas sector utilizes specialized dewatering equipment for extraction and processing support, while other industrial applications contribute to the overall volume. Each of these segments has distinct requirements regarding capacity, material durability, and mobility. For example, mining operations often require pumps capable of handling abrasive slurries using High-Chrome Alloys, which offer significant wear life despite higher material costs. Understanding the specific volume contribution and growth potential of each application segment is essential for targeted marketing and product development. Our full report isolates these segments to reveal which areas offer the highest return on investment for specific stakeholders.
Capacity Considerations and Material Science
Beyond power and application, the capacity of the pump and the materials used in its construction are decisive factors in procurement. The market is segmented by horsepower capacity, ranging from small units up to 3 HP for light duty, to massive units above 50 HP for heavy industrial tasks. The mid-range capacities typically see the highest volume due to their versatility in general construction and municipal work.
Material science also plays a critical role. The use of High-Chrome Alloys (Cr27) has become standard for handling abrasive slurries in dewatering pumps, offering wear life spanning several months depending on operating conditions. The cost of these materials fluctuates, impacting the final price of the equipment. Procurement managers must balance the upfront cost of durable materials against the long-term maintenance costs and downtime risks. Our analysis includes cost-benefit scenarios that help quantify these trade-offs, which are not visible in summary data.
The Strategic Value of Detailed Intelligence
While the macro trends and key players outlined above provide a snapshot of the industry, they represent only the surface level of available intelligence. For a Chief Strategy Officer or a Procurement Director, knowing that the market is growing at a 6.4% CAGR is useful, but knowing exactly which capacity segment in which region will drive that growth in 2027 is invaluable. The difference between a generic strategy and a winning strategy lies in the granularity.
PW Consulting's full Dewatering Pump Market report delves into the specific revenue splits by region, application, power source, and capacity. It provides the historical context needed to validate models and the forecast data needed to plan capital allocation. It examines the specific tactics used by the market leaders to maintain their concentration share and identifies gaps in the market that new entrants or expanding incumbents can exploit.
Furthermore, the report contextualizes recent industry activities, such as trade fair participations by companies like Sempa Pump and Solidpump in 2026, which signal emerging technology showcases and potential partnership networks. These events are indicators of where the market attention is shifting, whether toward sustainable sewage solutions or rugged mining applications. Ignoring these signals can lead to strategic myopia.
Conclusion and Call to Action
The dewatering pump market is at a inflection point where regulatory pressure, energy transition, and technological innovation converge. The period from 2026 to 2032 promises substantial growth, but capturing that growth requires more than just observation; it requires precise data-driven decision-making. The high-level insights provided here confirm the market's vitality and the competitive intensity, but they are not sufficient for crafting a detailed execution plan.
To access the complete matrix of data, including specific regional revenue figures, detailed segmentation percentages, and proprietary forecasts, stakeholders are encouraged to acquire the full market research report. This document is designed to be the definitive reference for your strategic planning cycle, ensuring that your organization is not just reacting to market changes but anticipating them. Equip your team with the comprehensive intelligence needed to navigate the complexities of the global dewatering pump industry.
For detailed analysis of this topic, please visit the official page: Dewatering Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Bio Pharma Buffer Market Hits $1.08B in 2025, Projected 7.85% CAGR to 2032
By pmarketresearch, 2026-09-15
Strategic Imperatives in the Bio Pharma Buffer Market: A 2026 Outlook
The biopharmaceutical industry stands at a critical inflection point where process efficiency, raw material stability, and regulatory compliance converge to define competitive advantage. Central to this ecosystem is the biopharma buffer market, a foundational component that ensures pH stability, protein integrity, and reproducible outcomes across cell culture, purification, and diagnostic workflows. As manufacturing scales and therapeutic modalities grow more complex, the strategic importance of buffer supply chains has never been more pronounced. PW Consulting's latest comprehensive study on the Bio Pharma Buffer Market offers a rigorous, data-driven exploration of this landscape, designed specifically to inform executive decision-making throughout 2026 and beyond.
This market research does not merely catalog historical performance; it constructs a forward-looking analytical framework that maps revenue trajectories, competitive positioning, and structural shifts across the value chain. By integrating macroeconomic indicators, industry-specific operational constraints, and evolving regulatory expectations, the report equips leaders with the contextual intelligence needed to navigate procurement strategies, capacity planning, and partnership development. The insights presented herein are structured to serve as a strategic compass, enabling organizations to anticipate demand fluctuations, mitigate supply chain vulnerabilities, and align operational roadmaps with long-term growth objectives.
The following analysis distills the core themes of the study, highlighting the market's structural evolution, the competitive forces shaping supplier dynamics, and the operational realities that continue to influence cost structures and compliance frameworks. Importantly, this preview is designed to demonstrate the depth of our methodology and the actionable nature of our findings, while preserving the granular segmentation data that forms the analytical backbone of the full report. Readers seeking precise regional breakdowns, application-specific revenue allocations, and detailed type-level market shares are encouraged to access the complete publication, where these elements are presented with the granularity required for operational implementation.
Bio Pharma Buffer Market
Macro Trajectory and Structural Evolution
The biopharma buffer market has demonstrated consistent expansion over the past half-decade, reflecting the broader acceleration in biologics development, increasing clinical trial activity, and the formalization of manufacturing capabilities across multiple geographies. Historical revenue patterns from 2020 through 2025 reveal a steady upward climb, with the market progressing from a baseline of 0.68 billion USD to 1.08 billion USD by the close of the base year. This progression underscores a compound annual growth trajectory that has outpaced several adjacent life sciences segments, driven by sustained investment in upstream and downstream processing infrastructure.
Looking ahead, the forecast window spanning 2026 through 2032 projects continued momentum, with revenue expectations climbing toward 1.86 billion USD by the terminal year of the analysis. The implied CAGR of 7.85 percent positions the buffer segment as a resilient growth corridor within the larger biopharmaceutical supply ecosystem. This expansion is not merely a function of volume scaling; it is increasingly shaped by product differentiation, quality standardization, and the shift toward pre-formulated and automation-compatible buffer solutions that reduce preparation bottlenecks in high-throughput environments.
Several structural forces are reinforcing this trajectory. Buffer preparation remains highly manual and resource intensive, requiring rigorous regulatory oversight and significant holding tank infrastructure. As organizations seek to optimize operational expenditures, the industry is witnessing a gradual transition toward more standardized, reproducible formulations that minimize variability and support compliance with stringent quality frameworks. Regulatory bodies, including the USFDA, continue to advocate for the use of high-quality buffer systems to promote product safety and effectiveness, reinforcing the premium placed on suppliers capable of delivering consistent, well-documented, and audit-ready solutions.
Simultaneously, raw material dynamics have introduced new layers of complexity. Certain chemical inputs experienced notable price volatility in 2024 due to supply chain disruptions and environmental regulatory caps in key manufacturing regions. These fluctuations have prompted procurement teams to reevaluate sourcing strategies, explore dual-supplier arrangements, and integrate forward-looking cost modeling into their buffer procurement plans. The interplay between input cost variability, labor intensity in large-scale preparation, and the growing demand for automation-ready components creates a nuanced operating environment where strategic foresight directly translates into margin protection and supply continuity.
Competitive Architecture and Strategic Positioning
The competitive landscape of the biopharma buffer market is characterized by a concentrated yet diversified set of participants, each leveraging distinct technological capabilities, geographic footprints, and service models to capture share. The market structure reflects a balance between established multinational suppliers with broad life sciences portfolios and specialized manufacturers that focus on high-purity formulations, contract manufacturing, or automation-integrated preparation systems. Concentration metrics indicate that the top three players account for approximately 32.5 percent of aggregate revenue, while the top five extend their influence to roughly 47.2 percent, suggesting a moderately consolidated environment with room for targeted differentiation and regional expansion.
Thermo Fisher Scientific Inc. continues to anchor its position through process liquid preparation services and cGMP-grade buffer solutions tailored for biopharmaceutical manufacturing and purification workflows. Its integrated approach aligns with customers seeking end-to-end quality assurance and regulatory-ready documentation. Avantor, Inc. maintains a strong presence via its J.T.Baker® and dry powder buffer lines, emphasizing stable, reproducible bioprocessing and protein purification outcomes. These product architectures appeal to organizations prioritizing batch consistency and simplified storage logistics.
Merck KGaA leverages its Life Science and Process Solutions segment to deliver high-purity buffer systems designed for biopharmaceutical production, reinforcing its reputation for analytical rigor and scaling reliability. Sartorius AG complements this landscape with BioPAT® and pre-formulated buffer systems optimized for bioprocessing workflows and biologics manufacturing, targeting customers who value process analytical technology integration and workflow streamlining. Lonza Group Ltd. contributes a contract manufacturing dimension, offering buffer solutions and raw materials for drug substance production, which appeals to developers seeking flexible capacity and specialized expertise without capital-intensive internal expansion.
GE Healthcare (Cytiva) supplies buffer components and systems for downstream processing in biologics manufacturing, positioning itself at a critical juncture where purification efficiency directly impacts overall yield and cost per gram. Bio-Rad Laboratories, Inc. advances the research and early development segment with BufferEZ™ and pre-formulated buffer solutions for protein purification and biopharma research, serving teams that require rapid iteration and reproducible assay conditions. Becton, Dickinson and Company (BD) rounds out the reagent ecosystem with laboratory buffers supporting cell culture and biopharmaceutical applications, reinforcing its broader life sciences instrumentation and consumables footprint.
Promega Corporation focuses on biochemical buffers for protein expression, purification, and biopharma assay development, bridging research-grade performance with translational workflows. Hamilton Company addresses the automation imperative through systems and components for buffer preparation in biopharmaceutical manufacturing, appealing to facilities seeking to reduce manual handling, improve repeatability, and integrate buffer preparation into broader liquid handling architectures. On the international front, Shandong Xingzhilian Biotechnology Co., Ltd. supplies a bio-buffer series to global biopharmaceutical companies, reflecting the growing participation of Asian manufacturers in the broader supply network. Sisco Research Laboratories Pvt. Ltd. (SRL) contributes PrimeDx and biochemical buffer lines for research and biopharma applications, further illustrating the diversity of participants catering to both discovery-phase and production-phase requirements.
This competitive mosaic is not static. Suppliers are increasingly competing on quality documentation, regulatory alignment, supply resilience, and the ability to support scale-up transitions. Customers are responding by prioritizing partners who can offer transparent sourcing, robust quality management systems, and flexible service models that adapt to shifting development timelines and manufacturing volumes. The full report dissects these positioning strategies in greater detail, mapping competitive overlap, geographic strengths, and service differentiation without revealing the precise allocation metrics that underpin the quantitative scoring models used in our analysis.
Operational Realities and Procurement Implications
Beyond headline growth figures, the operational realities of buffer utilization continue to shape how biopharmaceutical organizations structure their procurement, production, and compliance functions. Buffer preparation remains highly manual and resource intensive, a characteristic that exerts pressure on labor costs, scheduling flexibility, and facility throughput. In large-scale bioprocessing, the labor intensity and reliance on holding tanks make buffer preparation a meaningful cost driver, prompting engineers and operations leaders to evaluate process redesign, pre-diluted formulations, and automated preparation platforms as levers for efficiency improvement.
Electroporation Buffer Market
Regulatory expectations further complicate operational planning. Oversight of buffer preparation processes requires documented procedures, quality checks, and traceability that align with broader good manufacturing practices. The USFDA's continued emphasis on high-quality buffer systems to promote product safety and effectiveness reinforces the need for suppliers and end-users alike to maintain rigorous quality assurance disciplines. Organizations that embed these requirements into their sourcing criteria and internal standard operating procedures are better positioned to reduce batch failures, accelerate audit readiness, and maintain consistent process performance across production campaigns.
Raw material volatility remains another critical consideration. Price spikes observed in certain chemical inputs during 2024 highlighted the exposure of buffer cost structures to upstream supply disruptions and environmental regulatory actions. Procurement teams are increasingly incorporating scenario planning, safety stock optimization, and multi-source qualification into their buffer strategies. This shift is particularly relevant for organizations operating across multiple geographies or managing concurrent programs with differing formulation requirements, where the ability to adapt quickly to input cost changes can protect margins and preserve delivery timelines.
The market's evolution also reflects a broader preference for solutions that reduce variability and support reproducibility. Pre-formulated buffers, dry powder formats, and automation-compatible components are gaining traction as organizations seek to streamline preparation steps, minimize human error, and standardize workflows across sites. These preferences are not uniform across all applications; cell culture, protein purification, and molecular biology and diagnostics each impose distinct performance criteria, stability requirements, and scale considerations. The full study examines these application-specific drivers in depth, providing the qualitative and quantitative context necessary to align buffer selection with process objectives while preserving the segmentation granularity that supports precise planning.
Methodology, Scope, and Decision-Ready Intelligence
The Bio Pharma Buffer Market study is structured to deliver decision-ready intelligence across multiple dimensions of the value chain. The analytical framework integrates historical revenue tracking, forecast modeling, segmentation analysis, competitive profiling, and regulatory context into a cohesive narrative that supports strategic planning, sourcing optimization, and market entry evaluation. The report covers the historical period from 2020 through 2025, using 2025 as the base year, and extends the forecast horizon through 2032 to capture medium-term demand trajectories, capacity considerations, and competitive shifts.
Readers will find detailed examination of market sizing dynamics, growth rate implications, and the structural factors influencing revenue distribution across major categories. The study explores how type-level preferences, application-specific requirements, and regional operating conditions interact to shape procurement patterns and supplier selection criteria. Competitive profiling extends beyond product descriptions to address service models, quality positioning, automation readiness, and the strategic rationale behind recent portfolio and capability investments. The influence of raw material price movements, labor intensity in preparation, and regulatory emphasis on buffer quality is woven throughout the analysis to illustrate how macro and micro factors converge in real-world decision environments.
Importantly, the report is designed to function as both a strategic overview and a practical reference tool. Executive summaries, segmentation narratives, competitive comparisons, and operational context are organized to support cross-functional discussions among procurement, manufacturing, quality, and business development teams. The full publication contains the detailed segmentation splits, regional revenue allocations, application-level breakdowns, and type-level market shares that underpin the quantitative models. These elements are presented with the precision required for scenario planning, target setting, and vendor evaluation, while the preview provided here intentionally retains the strategic narrative without exposing the core numeric partitions that form the report's analytical foundation.
Strategic Takeaways for 2026 and the Road Ahead
As biopharmaceutical organizations advance their development pipelines and scale manufacturing operations, the biopharma buffer market will remain a critical enabler of process reliability, quality consistency, and cost management. The growth trajectory projected through 2032 reflects sustained demand for high-quality, reproducible buffer solutions, supported by regulatory alignment, automation adoption, and the ongoing formalization of bioprocessing infrastructure. At the same time, the market's operational complexity—shaped by labor-intensive preparation, raw material price variability, and evolving compliance expectations—demands a proactive, information-rich approach to sourcing and planning.
PW Consulting's study is purpose-built to support this approach. It provides the contextual depth, competitive intelligence, and market structure insights necessary to evaluate supplier capabilities, anticipate cost and supply risks, and align buffer strategy with broader business objectives. The analysis emphasizes practical decision points: how quality documentation and cGMP readiness influence partner selection, how automation-compatible solutions can reduce preparation bottlenecks, and how geographic and application-specific dynamics inform procurement architecture. By translating these themes into actionable intelligence, the report enables leaders to move from reactive procurement to strategic supply chain design.
The complete market research contains the precise segmentation data, regional revenue distributions, application-level shares, and type-level allocations that operational teams require for granular planning and forecasting. Those interested in accessing the full dataset, competitive scoring frameworks, and detailed segmentation narratives are invited to visit the report's source page, where the comprehensive intelligence is available for immediate strategic use. In a market defined by both resilience and complexity, informed decision-making begins with the right evidence—and this study is engineered to deliver exactly that.
For detailed analysis of this topic, please visit the official page: Bio Pharma Buffer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Iodine Market Hits $1.75B in 2025, Projects 4.26% CAGR to $2.36B by 2032
By pmarketresearch, 2026-09-15
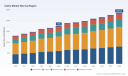
Strategic Intelligence for the Iodine Market: Navigating Growth, Supply Dynamics, and Competitive Forces in 2026
In an era where critical raw materials increasingly dictate competitive advantage across healthcare, advanced electronics, and specialty chemicals, iodine has emerged as a strategically pivotal element. The global iodine market has demonstrated consistent expansion over the past half-decade, transitioning from a niche industrial commodity to a multifaceted value chain that intersects pharmaceutical manufacturing, diagnostic imaging, display technologies, and agricultural nutrition. As executives and strategic planners calibrate their portfolios for the forecast period, understanding the structural drivers, supply chain vulnerabilities, and competitive realignments within this market has become indispensable. Our newly released Iodine Market research report delivers a comprehensive, data-grounded intelligence framework designed specifically to inform corporate strategy, capital allocation, and risk mitigation through 2032. This article outlines the strategic architecture of the study, contextualizes its macroeconomic trajectory, and demonstrates how forward-looking organizations can leverage its insights to secure positioning in an increasingly consolidated and regulated landscape.
Market Trajectory and Structural Growth Drivers
The historical baseline from 2020 through 2025 reveals a steady upward inflection, with the market expanding from approximately 1,300 million USD to an estimated 1,750 million USD by the base year. This trajectory reflects compounding demand across multiple end-use sectors, underpinned by population health initiatives, diagnostic imaging proliferation, and the uninterrupted scaling of high-purity chemical manufacturing. Looking ahead, the forecast horizon extends through 2032, projecting continued growth that culminates in a market valuation surpassing 2,355 million USD. The compound annual growth rate across the forecast window registers at 4.26 percent, a figure that may appear moderate at first glance but masks significant variation in sectoral intensity, regional adoption curves, and supply-side elasticity.
What distinguishes this growth narrative is not merely the aggregate expansion but the structural transitions occurring beneath the surface. Iodine’s dual role as both a bulk chemical feedstock and a highly purified pharmaceutical-grade reagent creates bifurcated demand profiles. Healthcare applications, particularly those tied to contrast media and sterile manufacturing environments, impose stringent quality protocols that constrain supplier qualification cycles and elevate barriers to entry. Simultaneously, industrial and electronics applications demand consistent volume reliability, forcing producers to balance capacity utilization across disparate downstream markets. The report deconstructs these dynamics by mapping how source availability, extraction economics, and processing pathways influence marginal pricing behavior and long-term supply resilience.
Supply-Side Architecture and Sourcing Heterogeneity
Iodine production is inherently tied to geological and operational specificities that vary dramatically across geographies. The market relies on a diversified but concentrated set of sourcing pathways, including caliche ore extraction, underground brine processing, seaweed-derived recovery, and emerging recycling streams. Each pathway carries distinct capital intensity profiles, environmental compliance burdens, and geographic exposure. Caliche ore operations, historically anchored in South America, offer scale advantages but are subject to weather variability, water management constraints, and regulatory scrutiny around extraction practices. Brine-based extraction, conversely, benefits from integration with natural gas and oilfield infrastructure, enabling co-production efficiencies but exposing operators to energy price volatility and subsurface management risks.
The strategic implication for procurement and supply chain leaders is that sourcing diversification cannot be treated as a passive inventory tactic. It requires active portfolio management that accounts for production uptime reliability, assay consistency, and the logistical complexity of moving high-purity intermediates across borders. The report provides a granular assessment of how these sourcing architectures interact with regional demand centers, mapping where supply surpluses and deficits are likely to emerge as capacity additions materialize and as downstream manufacturing footprints shift. Importantly, the analysis avoids oversimplified regional generalizations, instead presenting a nuanced evaluation of how trade flows, freight dynamics, and local regulatory environments shape actual availability at the plant gate.
Demand Ecosystem and Application Interdependence
The demand landscape for iodine is characterized by pronounced application interdependence. Diagnostic imaging remains a cornerstone of value creation, with iodine-based contrast agents representing a critical input for radiological procedures worldwide. The pharmaceutical sector absorbs significant volumes not only for active pharmaceutical ingredient synthesis but also for sterilization, formulation stabilization, and specialized halogen chemistry. In parallel, the display and electronics industries utilize iodine derivatives in polarizing films and precision manufacturing processes, linking market performance to consumer electronics cycles and industrial automation trends. Agricultural feed supplementation and industrial catalysis further broaden the demand base, introducing cyclicality tied to livestock production economics and process optimization schedules.
Bromine Market
For strategic decision-makers, the key insight is that these application segments do not expand in isolation. Capacity adjustments in one vertical reverberate across pricing behavior, inventory positioning, and supplier negotiation leverage in others. When diagnostic imaging demand accelerates due to aging demographics or healthcare infrastructure investment, the resulting tightness propagates to pharmaceutical-grade supply pipelines, which in turn influences the economics of bulk chemical allocations. The report models these cross-segment sensitivities, enabling users to simulate how demand shocks or capacity expansions in specific verticals will cascade through the broader market. This level of structural modeling is particularly valuable for organizations that manage multi-application supply contracts or that evaluate vertical integration opportunities spanning raw material extraction through finished-product formulation.
Competitive Concentration and Strategic Positioning
Market concentration has become a defining feature of the iodine landscape. The report highlights a consolidated competitive structure in which a limited number of producers command a substantial share of global output. This concentration is not accidental; it reflects the technical complexity of high-purity iodine refinement, the capital requirements of brine and caliche infrastructure, and the regulatory qualification cycles demanded by pharmaceutical and healthcare customers. As a result, the barrier landscape favors operators with established extraction assets, vertically integrated processing capabilities, and long-standing qualification relationships with downstream buyers.
Leading producers illustrate divergent strategic archetypes. Companies anchored in South America leverage caliche ore and brine operations to achieve scale, while simultaneously expanding capacity to meet growing healthcare and industrial demand. Their positioning is reinforced by geographic proximity to key sourcing geology and established logistics corridors. Japanese manufacturers emphasize refined iodine extracted from natural gas brine, focusing on high-specification chemical and pharmaceutical inputs that integrate with Asian downstream manufacturing ecosystems. United Kingdom-based producers have pursued vertical integration through specialized extraction technologies, converting oilfield brines into crystalline iodine and halogen-based specialty chemicals, thereby linking upstream resource recovery with mid-stream pharmaceutical formulation. United States-based operators contribute through brine well extraction and recycling pathways, servicing pharmaceutical, healthcare, and industrial customers with high-purity compounds. Several Chilean enterprises operate caliche and brine assets that supply pharmaceutical and healthcare applications, reinforcing the country’s role as a foundational production hub. In parallel, specialized manufacturers and distributors in Japan and the United States provide pharmaceutical-grade iodine, high-purity compounds, and formulated products that bridge raw material supply with healthcare and research requirements.
These competitive archetypes are not static. The report tracks capacity expansion announcements, production ramp timelines, and strategic realignments that signal where market share may shift over the forecast period. Recent operational disclosures underscore a pattern of deliberate capacity enhancement: one major producer announced expansion of its caliche extraction operations to increase annual iodine output, while another enterprise reported a production capacity increase designed to sustain industrial demand growth. Such moves illustrate how incumbents are proactively aligning supply with anticipated demand trajectories rather than reacting to shortages after they occur. For market entrants and incumbent strategists alike, understanding the timing, scale, and geographic focus of these expansions is essential for evaluating competitive threat surfaces and partnership opportunities.
Regulatory Catalysts and Supply Chain Sensitivity
Regulation and supply chain governance increasingly shape iodine market behavior. Medical product oversight has attracted heightened attention, with iodine-containing contrast media identified as a critical supply chain factor amid broader concerns about drug availability and manufacturing resilience. The inclusion of certain medical supply vulnerabilities on high-risk monitoring lists has reinforced the imperative for diversified sourcing, qualified secondary suppliers, and transparent inventory planning. Simultaneously, regulatory pathways for new contrast media formulations have advanced, with key submissions progressing through established approval mechanisms and expected agency determinations accelerating the timeline for market entry.
Trade policy dynamics add another layer of strategic complexity. Certain pharmaceutical import flows may be insulated from proposed tariff measures, altering the cost calculus for cross-border sourcing strategies and prompting reassessment of regional procurement architectures. In parallel, environmental and operational certifications have become meaningful differentiators, with select production divisions achieving recognized standards for energy management and environmental compliance, thereby strengthening their positioning in quality-sensitive downstream markets. These regulatory and compliance developments are not peripheral footnotes; they are structural inputs that influence supplier qualification lead times, contract risk allocation, and the long-term viability of specific sourcing relationships. The report integrates these factors into a cohesive risk framework, helping users anticipate where regulatory momentum will compress decision windows and where compliance leadership will become a competitive moat.
What the Report Delivers for Decision-Makers
The Iodine Market research study is structured to convert macro-level intelligence into actionable strategic guidance. It encompasses a full-spectrum assessment of market sizing across historical and forecast periods, segmentation analysis that maps how demand distributes across applications and sourcing pathways, and regional evaluations that identify where supply-demand balance is likely to tighten or loosen. Competition profiling extends beyond corporate descriptions to examine operational capabilities, capacity trajectories, and strategic positioning relevant to procurement, partnership, and entry decisions.
Beyond static market snapshots, the study provides practical tooling for scenario planning and operational calibration. It examines recent capacity and production developments to contextualize near-term availability, analyzes regulatory and trade developments that affect cost structures and sourcing options, and evaluates concentration metrics that signal negotiation leverage and supply resilience. The report also addresses production economics, qualification pathways for pharmaceutical-grade inputs, and the implications of vertical integration strategies that span extraction, refinement, and downstream formulation. For organizations evaluating capital deployment, supplier consolidation, geographic diversification, or product portfolio expansion, the study supplies a structured evidentiary base that reduces uncertainty and supports defensible strategic choices.
Strategic Imperatives for 2026 and Beyond
As market participants advance into the forecast window, several strategic imperatives become clear. First, supply chain architecture must be treated as a dynamic capability rather than a static contract portfolio. Qualification lead times, regulatory volatility, and capacity expansion timing all reward early mapping of secondary sources, prequalified alternate suppliers, and contingency inventory designs that align with actual production risk rather than theoretical coverage.
Second, competitive positioning will increasingly reward operators and buyers that can align quality assurance with cost discipline. The bifurcated nature of the market means that premium pharmaceutical-grade supply and volume-sensitive industrial supply follow different economics. Organizations that can segment their iodine demand by specification criticality, lead-time tolerance, and substitution feasibility will be better equipped to negotiate, source, and allocate without sacrificing operational continuity.
Third, geographic and regulatory awareness must be embedded into procurement forecasting. Tariffs, approval timelines, environmental certifications, and oversight scrutiny are not isolated externalities; they alter the relative attractiveness of sourcing regions and the speed at which new capacity becomes commercially usable. The organizations that integrate these variables into their planning cycles will be better positioned to avoid reactive purchasing, mitigate concentration risk, and capture favorable terms as market conditions evolve.
Iodine Market
Conclusion
The iodine market stands at a point where steady macroeconomic expansion intersects with intensifying competitive concentration, regulatory sensitivity, and sourcing complexity. Growth at a compound annual rate of 4.26 percent across the forecast horizon to 2032, building on a base of approximately 1,750 million USD and progressing toward a valuation above 2,355 million USD, provides a compelling directional signal. Yet the strategic value of that signal depends entirely on the depth of the underlying intelligence used to interpret it. Our Iodine Market research report is designed to deliver precisely that depth: a disciplined, operationally oriented analysis that informs procurement strategy, competitive positioning, capacity planning, and risk governance. For executives seeking to convert market visibility into durable advantage, the full study provides the granular segmentation, competitive assessment, and scenario-sensitive analysis necessary to move from insight to execution.
For detailed analysis of this topic, please visit the official page: Iodine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aspheric Lens Market Hits $9.49B in 2025, Forecast 8.4% CAGR to $16.59B by 2032
By pmarketresearch, 2026-09-15
Beyond the Curve: Strategic Intelligence for the Aspheric Lens Market (2026–2032)
Executive Overview
The global optical landscape is undergoing a structural transformation. Precision, miniaturization, and performance efficiency are no longer competitive differentiators; they are baseline requirements. At the center of this shift sits the aspheric lens, a component that has evolved from a specialized optical solution into an indispensable element across consumer electronics, automotive systems, medical imaging, and advanced photonics. As we enter 2026, organizations that treat the aspheric lens market as a static supply chain commodity will find themselves outpaced by competitors who understand its trajectory as a dynamic, multi-variable growth engine.
Our latest market research publication delivers exactly that understanding. Built on a rigorous analytical framework spanning historical baselines through 2032, this report translates complex optical market dynamics into actionable strategic intelligence. It is designed not merely to describe where the market has been, but to equip decision-makers with the predictive clarity required to allocate capital, shape product roadmaps, negotiate supply agreements, and anticipate competitive disruptions in the years ahead.
GRIN Lenses Market
The Macro Trajectory: What the Numbers Signal for 2026 Decision-Making
The market’s recent performance reflects more than cyclical recovery; it demonstrates sustained structural expansion. Following a five-year historical arc, the total market crossed the $9.4 billion threshold in the 2025 base year. Forward projections indicate continued momentum, with valuation pathways mapped through the end of the decade. By 2026, the market is positioned to surpass the $10 billion mark, and the trajectory steepens thereafter, reaching a projected valuation above $16.5 billion by 2032.
An 8.4% compound annual growth rate across the forecast period is not a superficial headline. It is a strategic signal that demands interpretation. Growth at this scale and consistency implies:
- Secular demand drivers are compounding rather than peaking, particularly as imaging systems become more integrated into everyday hardware and industrial automation stacks.
- Supply-side constraints are intensifying alongside demand, creating both margin pressure and differentiation opportunities for firms that can optimize manufacturing throughput and material efficiency.
- Market concentration remains meaningful, with the top three players accounting for a substantial share of revenue and the top five extending that footprint further. This concentration shapes pricing power, partnership dynamics, and barrier-to-entry calculations for new and existing participants.
For executives planning 2026 initiatives, these figures underscore the need to move beyond aggregate market sizing and interrogate the structural forces that will determine which segments, geographies, and product architectures capture disproportionate value. The report does exactly that, unpacking the consolidated trajectory into layered analytical dimensions while preserving the strategic confidentiality of granular breakdowns.
Beyond Aggregate Sizing: What the Report Delivers
A market research document that stops at top-line projections is useful for quarterly updates, but insufficient for multi-year strategy. The Aspheric Lens Market research is constructed to function as an operational playbook. It bridges high-level valuation trends with the tactical realities of product development, procurement, manufacturing, and competitive positioning.
Inside, readers will find a comprehensive architecture of analysis designed to support cross-functional decision-making:
- Segment-level strategic mapping across type, application, and geography. Rather than presenting flat segmentation tables, the analysis contextualizes each split within the operational and commercial logic that drives it. The report examines how material choices between glass and plastic aspheric lenses interact with end-use performance requirements, cost structures, and volume scalability. It explores how application-led demand from consumer electronics, automotive platforms, and healthcare and medical systems creates distinct adoption curves, specification sensitivities, and procurement behaviors.
- Regional demand and supply dynamics evaluated through a strategic lens. The study evaluates how mature optical manufacturing ecosystems, emerging production capacity, and localized demand patterns shape competitive access. It identifies where regional advantages in precision manufacturing, skilled labor, and established supplier networks create durable moats, and where cost, logistics, and regulatory considerations alter market entry calculus.
- Manufacturing and cost-structure analysis grounded in production reality. Aspheric optics remain inherently more complex to produce than spherical counterparts. The report addresses how precision grinding, polishing, molding, and diamond-turning approaches influence throughput, yield, lead times, and unit economics. These operational factors are analyzed not as isolated technical details, but as strategic variables that determine scalability, margin resilience, and supply chain negotiation leverage.
- Standards, compliance, and certification pathways. Reliable optical deployment depends on repeatable specifications and transparent documentation. The research incorporates the role of standardized drawing and testing conventions in reducing design-to-production friction, while also examining how regulation and certification requirements affect time-to-market across regulated sectors such as medical imaging and defense-adjacent applications.
- Supply chain sensitivity and raw material dynamics. High-precision optical fabrication depends on consistent access to quality inputs. The report assesses how material availability, sourcing stability, and input cost volatility influence production planning, especially for organizations scaling high-specification lens output.
The objective is not to overwhelm readers with volume, but to isolate the variables that matter most when translating market growth into internal execution. Each section is designed to answer a practical question: Where should we invest? What constraints should we design around? Which customer segments offer the cleanest path to scaled adoption? Which manufacturing decisions will define our long-term cost position?
Competitive Positioning in a Concentrated but Differentiated Landscape
The aspheric lens market is shaped by a mix of established optical giants, specialized manufacturing firms, and regional players with distinct capability profiles. This concentration creates a competitive environment where scale, technological depth, and application-specific expertise determine market influence. Rather than treating competitors as a static roster, the report evaluates them through the strategic logic of their positioning: which firms compete on integrated optical systems, which focus on high-precision component supply, and which build value through customization and rapid prototyping support.
The competitive landscape includes organizations with globally recognized optical expertise and deep integration into camera, industrial, and semiconductor imaging ecosystems, alongside firms that specialize in stock and custom aspheric solutions for scientific, industrial, and photonics applications. European and Japanese manufacturers bring strong heritage in precision optical engineering and high-end system integration. U.S.-based suppliers contribute broad catalogs, custom engineering capability, and strong alignment with research, laser, and advanced imaging markets. Asian manufacturers, particularly in Taiwan and Japan, have scaled precision production capabilities that support high-volume consumer and industrial deployments.
This diversity matters strategically. In concentrated markets, competitive advantage often comes not from matching every competitor on every dimension, but from identifying where differentiation is structurally defensible. The report examines how firms use different levers:
- Precision system integration and brand authority in high-specification imaging and measurement applications.
- Customization capability, rapid iteration, and specialized support for medical, defense, and LiDAR-oriented deployments.
- Manufacturing process expertise in precision glass molding, ultra-precision CNC, and diamond turning to balance performance with volume economics.
- Vertical alignment with specific end markets, including mobile imaging, vision care, and industrial instruments, where application knowledge creates recurring demand relationships.
Recent industry activity reinforces the need for continuous competitive monitoring. Throughout early 2026, suppliers and manufacturers have been actively sharpening their technical messaging and operational capabilities. One notable development includes the release of an application note addressing manufacturing considerations for custom aspheric lenses, with emphasis on polymer injection molding, tolerance sensitivity, and integrated supply chain coordination to reduce lead times. In parallel, industry events have been convened to deepen expertise around aspheric lens manufacturing and metrology, reflecting how process precision and measurement reliability remain central to competitive credibility.
For organizations evaluating partnerships, procurement strategies, or market entry plans, the report translates these competitive signals into practical implications. It helps answer which capabilities are becoming table stakes, which are still differentiating, and where consolidation or specialization is likely to reshape commercial access over the forecast period.
Structural Pressures and the Strategic Response
No growth trajectory exists in isolation. The market’s expansion is interwoven with operational and external pressures that influence execution risk and opportunity. The report integrates these forces directly into its strategic assessment so that readers can anticipate friction points rather than react to them.
One persistent challenge lies in production complexity. The grinding and polishing techniques required for aspheric geometries elevate manufacturing cost and constrain throughput relative to simpler optical elements. This reality makes process optimization, yield improvement, and tooling strategy central to margin management. Organizations that treat manufacturing complexity as a fixed cost of doing business risk underpricing their capability; those that engineer around it can unlock meaningful competitive separation.
Material supply introduces another layer of strategic sensitivity. The availability of high-quality raw materials for high-precision lens fabrication can constrain expansion and create potential production delays. In a market where specification integrity and performance consistency are non-negotiable, sourcing resilience becomes a competitive asset rather than a back-office function. The research explores how procurement strategy, supplier diversification, and production planning interact under these conditions.
Aspheric Lens Market
Externally, regulatory and trade dynamics add complexity to regional operating models. For example, carbon-related regulatory mechanisms in the EU introduce tariff implications for carbon-intensive imported products, affecting cost structures and compliance planning for optical manufacturers and system integrators engaged in cross-border supply chains. Simultaneously, standardized technical conventions for optical drawings and testing requirements continue to shape how manufacturers communicate specifications and validate output, reinforcing the importance of documentation discipline and quality assurance processes.
Rather than treating these pressures as peripheral news items, the report incorporates them as strategic variables. The central question is not whether such dynamics exist, but how they alter the relative attractiveness of different manufacturing approaches, regional footprints, customer segments, and partnership models.
Why This Research Matters for 2026 Planning
Strategic decisions made in 2026 will cascade across the rest of the decade. Procurement contracts, R&D allocation, capacity investments, geographic expansion, and competitive positioning all benefit from foresight that is specific enough to act on and robust enough to withstand market volatility. This report is built to support that decision environment.
It provides leadership teams with a shared analytical baseline, reducing reliance on fragmented assumptions or anecdotal supplier intelligence. It enables product and engineering leaders to align specification choices with market demand patterns and manufacturing feasibility. It helps commercial and supply chain teams evaluate where lead-time reduction, customization capability, and material resilience can be converted into commercial advantage. It gives executives a clearer view of where market concentration creates pricing risk, where segmentation creates expansion opportunity, and where technological differentiation is most likely to persist.
What Is Intentionally Held Back—and Why
A high-value intelligence asset earns trust not by disclosing everything at once, but by demonstrating analytical rigor and reserving the most decision-critical detail for those prepared to act on it. To preserve the strategic integrity of the research and ensure its utility for serious planning, the full segmentation breakdowns, regional valuation splits, application-level revenue distribution, and company-specific competitive quantification are reserved within the complete report.
This is not an omission; it is a design choice. Aggregate growth trends and qualitative structural analysis can guide initial orientation, but precise market share distributions, segment-level dollar values, and localized demand splits are exactly the type of intelligence that should inform committed capital allocation, pricing strategy, and partnership decisions. Those details are available in the full research release, where they are presented alongside the analytical context needed to interpret them correctly.
Moving from Insight to Action
The aspheric lens market is expanding at a pace that rewards preparation and penalizes hesitation. Over the 2026–2032 forecast window, value will accrue to organizations that combine optical expertise with disciplined manufacturing strategy, resilient sourcing, and clear application focus. Growth alone will not guarantee success; the winners will be those who understand the underlying mechanics well enough to act early and precisely.
This research is intended to provide that understanding. It offers a structured, evidence-based view of where the market is heading, what forces are shaping it, and how competing firms are positioning themselves within it. For decision-makers who need more than a high-level summary, the full report delivers the depth, segmentation clarity, and competitive intelligence required to convert market opportunity into executable strategy.
The complete analysis, including detailed segmentation pathways, regional assessments, application-level demand patterns, and competitive benchmarking, is available through the full market research publication. For teams planning 2026 investments, supply strategies, and product roadmaps, that deeper layer of intelligence is where strategic confidence begins.
For detailed analysis of this topic, please visit the official page: Aspheric Lens Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com