

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Dewatering Pump Market to Hit $12,010 Million by 2032 at 6.4% CAGR

Navigating the Future of Fluid Management: Strategic Insights from the 2026 Dewatering Pump Market Report
Executive Summary
In an era where infrastructure resilience and environmental compliance define operational success, the dewatering pump market stands as a critical backbone for global industrial activity. As we move deeper into 2026, stakeholders across construction, mining, and municipal sectors face a complex landscape shaped by shifting regulatory frameworks, technological advancements, and evolving power dynamics. PW Consulting's latest comprehensive study on the Dewatering Pump Market is not merely a collection of statistics; it is a strategic roadmap designed to guide enterprise decision-makers through the volatility and opportunity of the forecast period spanning 2026 to 2032.
This article serves as a preliminary insight into the depth and breadth of our upcoming research. It outlines the macro-economic trajectory, the competitive intensity, and the regulatory pressures that will define the next seven years. However, to truly capitalize on these trends, organizations require granular data that goes beyond high-level summaries. Our full report offers the precise segmentation and actionable intelligence necessary to refine procurement strategies, identify partnership opportunities, and mitigate risk.
Macro-Economic Trajectory and Growth Dynamics
The historical performance of the dewatering pump sector provides a robust foundation for confidence in future growth. Between 2020 and 2025, the market demonstrated a consistent upward trajectory, recovering from global disruptions and capitalizing on intensified infrastructure spending. Our analysis indicates that the market revenue, denominated in USD Million, has shown resilience despite supply chain constraints and fluctuating raw material costs. The total market size has expanded significantly over the last half-decade, reflecting the essential nature of water management in industrial processes.
Looking toward the forecast period from 2026 through 2032, the growth momentum is expected to accelerate. The projected Compound Annual Growth Rate (CAGR) of 6.4% underscores a healthy expansion phase driven by urbanization and resource extraction demands. By the end of the forecast window, the market volume is anticipated to reach new highs, surpassing current baselines substantially. This growth is not uniform; it is contingent upon specific technological adoptions and regional infrastructural developments which are detailed extensively in the full intelligence dossier.
Water Pumps Market
For strategic planners, understanding the velocity of this growth is crucial. A steady increase suggests sustained demand, but the nuances lie in the timing of peaks across different segments. Our report dissects these timelines to help clients align their capacity planning and inventory management with market rhythms. Without access to the specific year-over-year breakdowns provided in the complete study, businesses risk misaligning their capital expenditure with actual market demand surges.
Regulatory Pressures and Environmental Compliance
One of the most significant drivers reshaping the competitive landscape is the tightening grip of environmental regulation. In the United States, frameworks established by the Environmental Protection Agency (EPA) are compelling mining operators and construction firms to adopt sustainable water management practices. These regulations are not merely suggestions; they mandate the adoption of environmentally compliant dewatering systems often equipped with real-time monitoring capabilities. Failure to adhere can result in substantial fines and operational shutdowns, making compliance a priority over cost minimization.
Similarly, in the European Union, the Water Framework Directive and REACH chemical regulations are enforcing strict standards on discharge quality and filtration systems. These directives require industries to integrate advanced filtration into their dewatering processes, influencing the type of equipment purchased. The regulatory environment is pushing the market toward systems that minimize ecological impact while maintaining operational efficiency. Our analysis explores how these regulatory shifts create barriers to entry for non-compliant manufacturers while offering opportunities for innovators who can integrate smart monitoring and filtration technologies.
Technological Shifts: The Energy Transition and Power Sources
The source of power for dewatering equipment is undergoing a transformative shift. Historically, diesel engines have been the workhorse for remote construction and mining sites due to their portability and power density. However, progressive tightening of diesel engine emissions standards in both construction and mining sectors is adding compliance costs and driving a transition toward electric or hybrid alternatives. This shift is reshaping the demand curve for different power source categories within the market.
Electric solutions are gaining traction, particularly in areas where grid connectivity is reliable or where battery technology has advanced enough to support mobile operations. Hydraulic systems continue to hold relevance in specific heavy-duty applications where pressure and durability are paramount. Understanding the balance between these power sources is vital for suppliers and purchasers alike. The full report provides a detailed breakdown of how each power source segment is expected to perform, considering factors such as fuel costs, availability, and regulatory penalties.
Competitive Landscape and Key Industry Players
The market is characterized by a consolidated yet competitive environment. Our concentration analysis indicates that a handful of major players hold a significant share of the total revenue, creating a landscape where strategic positioning is key to maintaining market share. The top three competitors collectively account for a substantial portion of the market, while the top five extend their influence further. This concentration suggests that partnerships, mergers, and acquisitions could play a pivotal role in the coming years as companies seek to expand their technological portfolios and geographic reach.
Dewatering Pump Market
Several key companies define the current state of the industry, each bringing unique strengths to the table:
- Xylem Inc. (Stamford, Connecticut, USA): A dominant force leveraging brands like Godwin Dri-Prime and Flygt to serve construction, mining, and municipal sectors with a focus on intelligent water solutions.
- Sulzer Ltd. (Winterthur, Switzerland): Known for their JC/XJC and J/XJ centrifugal submersible pumps, alongside smart AquaTronic controls, catering heavily to mines and tunnels.
- Grundfos Holding A/S (Bjerringbro, Denmark): Provides robust submersible and centrifugal solutions specifically targeted at construction and industrial wastewater handling.
- Atlas Copco AB (Stockholm, Sweden): Their WEDA submersible electric range is a staple in mining and tunneling applications, emphasizing efficiency and durability.
- Tsurumi Manufacturing Co., Ltd. (Tokyo, Japan): Offers specialized submersible dewatering and slurry pumps critical for construction and wastewater projects.
- Gorman-Rupp Company (Mansfield, Ohio, USA): Focuses on centrifugal and self-priming pumps for municipal and industrial use, maintaining a strong legacy in the sector.
- Weir Group PLC (Glasgow, Scotland, UK): Specializes in dewatering and slurry pumps for demanding mining and industrial applications.
- KSB SE & Co. KGaA (Frankenthal, Germany): Delivers submersible and centrifugal pumps for construction and industrial sites, recently innovating with energy-efficient designs.
- Ebara Corporation (Tokyo, Japan): Provides submersible and dry-pit pumps essential for wastewater and industrial applications.
- Wilo SE (Dortmund, Germany): Focuses on submersible and centrifugal pumps for municipal and industrial water management.
- Pioneer Pump (Franklin Electric) (McAlester, Oklahoma, USA): Recently expanded their portfolio with NSF/ANSI 61-certified lines and diesel-driven packages, alongside a new service network.
- Flowserve Corporation (Irving, Texas, USA): Serves industrial and process applications with centrifugal and submersible solutions.
- Wacker Neuson SE (Munich, Germany): Geared heavily toward construction and infrastructure projects with specialized submersible units.
Recent developments highlight the dynamism of this group. For instance, in early 2026, KSB introduced the Omega 2 next-generation axially split volute casing pump, emphasizing improved hydraulic performance and energy efficiency. Similarly, Pioneer Pump launched an Expert Services Network in February 2026, offering factory-certified on-site service and 24/7 support, signaling a shift toward service-led revenue models alongside hardware sales. These moves indicate that competition is no longer just about pump specs; it is about lifecycle support and efficiency certifications.
Application Segments and Industry Use Cases
The demand for dewatering pumps is distributed across several critical application verticals. Construction remains a primary driver, where excavation sites require continuous water removal to ensure safety and progress. Mining follows closely, where large-scale operations depend on effective slurry and water handling to maintain throughput. Municipal wastewater management is another crucial segment, driven by the need to upgrade aging infrastructure and meet stricter discharge standards.
Additionally, the Oil and Gas sector utilizes specialized dewatering equipment for extraction and processing support, while other industrial applications contribute to the overall volume. Each of these segments has distinct requirements regarding capacity, material durability, and mobility. For example, mining operations often require pumps capable of handling abrasive slurries using High-Chrome Alloys, which offer significant wear life despite higher material costs. Understanding the specific volume contribution and growth potential of each application segment is essential for targeted marketing and product development. Our full report isolates these segments to reveal which areas offer the highest return on investment for specific stakeholders.
Capacity Considerations and Material Science
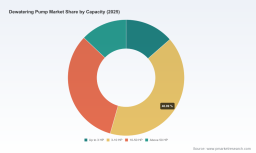
Beyond power and application, the capacity of the pump and the materials used in its construction are decisive factors in procurement. The market is segmented by horsepower capacity, ranging from small units up to 3 HP for light duty, to massive units above 50 HP for heavy industrial tasks. The mid-range capacities typically see the highest volume due to their versatility in general construction and municipal work.
Material science also plays a critical role. The use of High-Chrome Alloys (Cr27) has become standard for handling abrasive slurries in dewatering pumps, offering wear life spanning several months depending on operating conditions. The cost of these materials fluctuates, impacting the final price of the equipment. Procurement managers must balance the upfront cost of durable materials against the long-term maintenance costs and downtime risks. Our analysis includes cost-benefit scenarios that help quantify these trade-offs, which are not visible in summary data.
The Strategic Value of Detailed Intelligence
While the macro trends and key players outlined above provide a snapshot of the industry, they represent only the surface level of available intelligence. For a Chief Strategy Officer or a Procurement Director, knowing that the market is growing at a 6.4% CAGR is useful, but knowing exactly which capacity segment in which region will drive that growth in 2027 is invaluable. The difference between a generic strategy and a winning strategy lies in the granularity.
PW Consulting's full Dewatering Pump Market report delves into the specific revenue splits by region, application, power source, and capacity. It provides the historical context needed to validate models and the forecast data needed to plan capital allocation. It examines the specific tactics used by the market leaders to maintain their concentration share and identifies gaps in the market that new entrants or expanding incumbents can exploit.
Furthermore, the report contextualizes recent industry activities, such as trade fair participations by companies like Sempa Pump and Solidpump in 2026, which signal emerging technology showcases and potential partnership networks. These events are indicators of where the market attention is shifting, whether toward sustainable sewage solutions or rugged mining applications. Ignoring these signals can lead to strategic myopia.
Conclusion and Call to Action
The dewatering pump market is at a inflection point where regulatory pressure, energy transition, and technological innovation converge. The period from 2026 to 2032 promises substantial growth, but capturing that growth requires more than just observation; it requires precise data-driven decision-making. The high-level insights provided here confirm the market's vitality and the competitive intensity, but they are not sufficient for crafting a detailed execution plan.
To access the complete matrix of data, including specific regional revenue figures, detailed segmentation percentages, and proprietary forecasts, stakeholders are encouraged to acquire the full market research report. This document is designed to be the definitive reference for your strategic planning cycle, ensuring that your organization is not just reacting to market changes but anticipating them. Equip your team with the comprehensive intelligence needed to navigate the complexities of the global dewatering pump industry.
For detailed analysis of this topic, please visit the official page: Dewatering Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com