

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Bio Pharma Buffer Market Hits $1.08B in 2025, Projected 7.85% CAGR to 2032

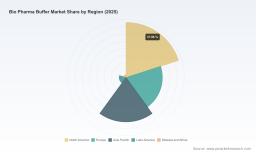
Strategic Imperatives in the Bio Pharma Buffer Market: A 2026 Outlook
The biopharmaceutical industry stands at a critical inflection point where process efficiency, raw material stability, and regulatory compliance converge to define competitive advantage. Central to this ecosystem is the biopharma buffer market, a foundational component that ensures pH stability, protein integrity, and reproducible outcomes across cell culture, purification, and diagnostic workflows. As manufacturing scales and therapeutic modalities grow more complex, the strategic importance of buffer supply chains has never been more pronounced. PW Consulting's latest comprehensive study on the Bio Pharma Buffer Market offers a rigorous, data-driven exploration of this landscape, designed specifically to inform executive decision-making throughout 2026 and beyond.
This market research does not merely catalog historical performance; it constructs a forward-looking analytical framework that maps revenue trajectories, competitive positioning, and structural shifts across the value chain. By integrating macroeconomic indicators, industry-specific operational constraints, and evolving regulatory expectations, the report equips leaders with the contextual intelligence needed to navigate procurement strategies, capacity planning, and partnership development. The insights presented herein are structured to serve as a strategic compass, enabling organizations to anticipate demand fluctuations, mitigate supply chain vulnerabilities, and align operational roadmaps with long-term growth objectives.
The following analysis distills the core themes of the study, highlighting the market's structural evolution, the competitive forces shaping supplier dynamics, and the operational realities that continue to influence cost structures and compliance frameworks. Importantly, this preview is designed to demonstrate the depth of our methodology and the actionable nature of our findings, while preserving the granular segmentation data that forms the analytical backbone of the full report. Readers seeking precise regional breakdowns, application-specific revenue allocations, and detailed type-level market shares are encouraged to access the complete publication, where these elements are presented with the granularity required for operational implementation.
Bio Pharma Buffer Market
Macro Trajectory and Structural Evolution
The biopharma buffer market has demonstrated consistent expansion over the past half-decade, reflecting the broader acceleration in biologics development, increasing clinical trial activity, and the formalization of manufacturing capabilities across multiple geographies. Historical revenue patterns from 2020 through 2025 reveal a steady upward climb, with the market progressing from a baseline of 0.68 billion USD to 1.08 billion USD by the close of the base year. This progression underscores a compound annual growth trajectory that has outpaced several adjacent life sciences segments, driven by sustained investment in upstream and downstream processing infrastructure.
Looking ahead, the forecast window spanning 2026 through 2032 projects continued momentum, with revenue expectations climbing toward 1.86 billion USD by the terminal year of the analysis. The implied CAGR of 7.85 percent positions the buffer segment as a resilient growth corridor within the larger biopharmaceutical supply ecosystem. This expansion is not merely a function of volume scaling; it is increasingly shaped by product differentiation, quality standardization, and the shift toward pre-formulated and automation-compatible buffer solutions that reduce preparation bottlenecks in high-throughput environments.
Several structural forces are reinforcing this trajectory. Buffer preparation remains highly manual and resource intensive, requiring rigorous regulatory oversight and significant holding tank infrastructure. As organizations seek to optimize operational expenditures, the industry is witnessing a gradual transition toward more standardized, reproducible formulations that minimize variability and support compliance with stringent quality frameworks. Regulatory bodies, including the USFDA, continue to advocate for the use of high-quality buffer systems to promote product safety and effectiveness, reinforcing the premium placed on suppliers capable of delivering consistent, well-documented, and audit-ready solutions.
Simultaneously, raw material dynamics have introduced new layers of complexity. Certain chemical inputs experienced notable price volatility in 2024 due to supply chain disruptions and environmental regulatory caps in key manufacturing regions. These fluctuations have prompted procurement teams to reevaluate sourcing strategies, explore dual-supplier arrangements, and integrate forward-looking cost modeling into their buffer procurement plans. The interplay between input cost variability, labor intensity in large-scale preparation, and the growing demand for automation-ready components creates a nuanced operating environment where strategic foresight directly translates into margin protection and supply continuity.
Competitive Architecture and Strategic Positioning
The competitive landscape of the biopharma buffer market is characterized by a concentrated yet diversified set of participants, each leveraging distinct technological capabilities, geographic footprints, and service models to capture share. The market structure reflects a balance between established multinational suppliers with broad life sciences portfolios and specialized manufacturers that focus on high-purity formulations, contract manufacturing, or automation-integrated preparation systems. Concentration metrics indicate that the top three players account for approximately 32.5 percent of aggregate revenue, while the top five extend their influence to roughly 47.2 percent, suggesting a moderately consolidated environment with room for targeted differentiation and regional expansion.
Thermo Fisher Scientific Inc. continues to anchor its position through process liquid preparation services and cGMP-grade buffer solutions tailored for biopharmaceutical manufacturing and purification workflows. Its integrated approach aligns with customers seeking end-to-end quality assurance and regulatory-ready documentation. Avantor, Inc. maintains a strong presence via its J.T.Baker® and dry powder buffer lines, emphasizing stable, reproducible bioprocessing and protein purification outcomes. These product architectures appeal to organizations prioritizing batch consistency and simplified storage logistics.
Merck KGaA leverages its Life Science and Process Solutions segment to deliver high-purity buffer systems designed for biopharmaceutical production, reinforcing its reputation for analytical rigor and scaling reliability. Sartorius AG complements this landscape with BioPAT® and pre-formulated buffer systems optimized for bioprocessing workflows and biologics manufacturing, targeting customers who value process analytical technology integration and workflow streamlining. Lonza Group Ltd. contributes a contract manufacturing dimension, offering buffer solutions and raw materials for drug substance production, which appeals to developers seeking flexible capacity and specialized expertise without capital-intensive internal expansion.
GE Healthcare (Cytiva) supplies buffer components and systems for downstream processing in biologics manufacturing, positioning itself at a critical juncture where purification efficiency directly impacts overall yield and cost per gram. Bio-Rad Laboratories, Inc. advances the research and early development segment with BufferEZ™ and pre-formulated buffer solutions for protein purification and biopharma research, serving teams that require rapid iteration and reproducible assay conditions. Becton, Dickinson and Company (BD) rounds out the reagent ecosystem with laboratory buffers supporting cell culture and biopharmaceutical applications, reinforcing its broader life sciences instrumentation and consumables footprint.
Promega Corporation focuses on biochemical buffers for protein expression, purification, and biopharma assay development, bridging research-grade performance with translational workflows. Hamilton Company addresses the automation imperative through systems and components for buffer preparation in biopharmaceutical manufacturing, appealing to facilities seeking to reduce manual handling, improve repeatability, and integrate buffer preparation into broader liquid handling architectures. On the international front, Shandong Xingzhilian Biotechnology Co., Ltd. supplies a bio-buffer series to global biopharmaceutical companies, reflecting the growing participation of Asian manufacturers in the broader supply network. Sisco Research Laboratories Pvt. Ltd. (SRL) contributes PrimeDx and biochemical buffer lines for research and biopharma applications, further illustrating the diversity of participants catering to both discovery-phase and production-phase requirements.
This competitive mosaic is not static. Suppliers are increasingly competing on quality documentation, regulatory alignment, supply resilience, and the ability to support scale-up transitions. Customers are responding by prioritizing partners who can offer transparent sourcing, robust quality management systems, and flexible service models that adapt to shifting development timelines and manufacturing volumes. The full report dissects these positioning strategies in greater detail, mapping competitive overlap, geographic strengths, and service differentiation without revealing the precise allocation metrics that underpin the quantitative scoring models used in our analysis.
Operational Realities and Procurement Implications
Beyond headline growth figures, the operational realities of buffer utilization continue to shape how biopharmaceutical organizations structure their procurement, production, and compliance functions. Buffer preparation remains highly manual and resource intensive, a characteristic that exerts pressure on labor costs, scheduling flexibility, and facility throughput. In large-scale bioprocessing, the labor intensity and reliance on holding tanks make buffer preparation a meaningful cost driver, prompting engineers and operations leaders to evaluate process redesign, pre-diluted formulations, and automated preparation platforms as levers for efficiency improvement.
Electroporation Buffer Market
Regulatory expectations further complicate operational planning. Oversight of buffer preparation processes requires documented procedures, quality checks, and traceability that align with broader good manufacturing practices. The USFDA's continued emphasis on high-quality buffer systems to promote product safety and effectiveness reinforces the need for suppliers and end-users alike to maintain rigorous quality assurance disciplines. Organizations that embed these requirements into their sourcing criteria and internal standard operating procedures are better positioned to reduce batch failures, accelerate audit readiness, and maintain consistent process performance across production campaigns.
Raw material volatility remains another critical consideration. Price spikes observed in certain chemical inputs during 2024 highlighted the exposure of buffer cost structures to upstream supply disruptions and environmental regulatory actions. Procurement teams are increasingly incorporating scenario planning, safety stock optimization, and multi-source qualification into their buffer strategies. This shift is particularly relevant for organizations operating across multiple geographies or managing concurrent programs with differing formulation requirements, where the ability to adapt quickly to input cost changes can protect margins and preserve delivery timelines.
The market's evolution also reflects a broader preference for solutions that reduce variability and support reproducibility. Pre-formulated buffers, dry powder formats, and automation-compatible components are gaining traction as organizations seek to streamline preparation steps, minimize human error, and standardize workflows across sites. These preferences are not uniform across all applications; cell culture, protein purification, and molecular biology and diagnostics each impose distinct performance criteria, stability requirements, and scale considerations. The full study examines these application-specific drivers in depth, providing the qualitative and quantitative context necessary to align buffer selection with process objectives while preserving the segmentation granularity that supports precise planning.
Methodology, Scope, and Decision-Ready Intelligence
The Bio Pharma Buffer Market study is structured to deliver decision-ready intelligence across multiple dimensions of the value chain. The analytical framework integrates historical revenue tracking, forecast modeling, segmentation analysis, competitive profiling, and regulatory context into a cohesive narrative that supports strategic planning, sourcing optimization, and market entry evaluation. The report covers the historical period from 2020 through 2025, using 2025 as the base year, and extends the forecast horizon through 2032 to capture medium-term demand trajectories, capacity considerations, and competitive shifts.
Readers will find detailed examination of market sizing dynamics, growth rate implications, and the structural factors influencing revenue distribution across major categories. The study explores how type-level preferences, application-specific requirements, and regional operating conditions interact to shape procurement patterns and supplier selection criteria. Competitive profiling extends beyond product descriptions to address service models, quality positioning, automation readiness, and the strategic rationale behind recent portfolio and capability investments. The influence of raw material price movements, labor intensity in preparation, and regulatory emphasis on buffer quality is woven throughout the analysis to illustrate how macro and micro factors converge in real-world decision environments.
Importantly, the report is designed to function as both a strategic overview and a practical reference tool. Executive summaries, segmentation narratives, competitive comparisons, and operational context are organized to support cross-functional discussions among procurement, manufacturing, quality, and business development teams. The full publication contains the detailed segmentation splits, regional revenue allocations, application-level breakdowns, and type-level market shares that underpin the quantitative models. These elements are presented with the precision required for scenario planning, target setting, and vendor evaluation, while the preview provided here intentionally retains the strategic narrative without exposing the core numeric partitions that form the report's analytical foundation.
Strategic Takeaways for 2026 and the Road Ahead
As biopharmaceutical organizations advance their development pipelines and scale manufacturing operations, the biopharma buffer market will remain a critical enabler of process reliability, quality consistency, and cost management. The growth trajectory projected through 2032 reflects sustained demand for high-quality, reproducible buffer solutions, supported by regulatory alignment, automation adoption, and the ongoing formalization of bioprocessing infrastructure. At the same time, the market's operational complexity—shaped by labor-intensive preparation, raw material price variability, and evolving compliance expectations—demands a proactive, information-rich approach to sourcing and planning.
PW Consulting's study is purpose-built to support this approach. It provides the contextual depth, competitive intelligence, and market structure insights necessary to evaluate supplier capabilities, anticipate cost and supply risks, and align buffer strategy with broader business objectives. The analysis emphasizes practical decision points: how quality documentation and cGMP readiness influence partner selection, how automation-compatible solutions can reduce preparation bottlenecks, and how geographic and application-specific dynamics inform procurement architecture. By translating these themes into actionable intelligence, the report enables leaders to move from reactive procurement to strategic supply chain design.
The complete market research contains the precise segmentation data, regional revenue distributions, application-level shares, and type-level allocations that operational teams require for granular planning and forecasting. Those interested in accessing the full dataset, competitive scoring frameworks, and detailed segmentation narratives are invited to visit the report's source page, where the comprehensive intelligence is available for immediate strategic use. In a market defined by both resilience and complexity, informed decision-making begins with the right evidence—and this study is engineered to deliver exactly that.
For detailed analysis of this topic, please visit the official page: Bio Pharma Buffer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com