

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Iodine Market Hits $1.75B in 2025, Projects 4.26% CAGR to $2.36B by 2032

Strategic Intelligence for the Iodine Market: Navigating Growth, Supply Dynamics, and Competitive Forces in 2026
In an era where critical raw materials increasingly dictate competitive advantage across healthcare, advanced electronics, and specialty chemicals, iodine has emerged as a strategically pivotal element. The global iodine market has demonstrated consistent expansion over the past half-decade, transitioning from a niche industrial commodity to a multifaceted value chain that intersects pharmaceutical manufacturing, diagnostic imaging, display technologies, and agricultural nutrition. As executives and strategic planners calibrate their portfolios for the forecast period, understanding the structural drivers, supply chain vulnerabilities, and competitive realignments within this market has become indispensable. Our newly released Iodine Market research report delivers a comprehensive, data-grounded intelligence framework designed specifically to inform corporate strategy, capital allocation, and risk mitigation through 2032. This article outlines the strategic architecture of the study, contextualizes its macroeconomic trajectory, and demonstrates how forward-looking organizations can leverage its insights to secure positioning in an increasingly consolidated and regulated landscape.
Market Trajectory and Structural Growth Drivers
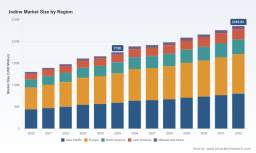
The historical baseline from 2020 through 2025 reveals a steady upward inflection, with the market expanding from approximately 1,300 million USD to an estimated 1,750 million USD by the base year. This trajectory reflects compounding demand across multiple end-use sectors, underpinned by population health initiatives, diagnostic imaging proliferation, and the uninterrupted scaling of high-purity chemical manufacturing. Looking ahead, the forecast horizon extends through 2032, projecting continued growth that culminates in a market valuation surpassing 2,355 million USD. The compound annual growth rate across the forecast window registers at 4.26 percent, a figure that may appear moderate at first glance but masks significant variation in sectoral intensity, regional adoption curves, and supply-side elasticity.
What distinguishes this growth narrative is not merely the aggregate expansion but the structural transitions occurring beneath the surface. Iodine’s dual role as both a bulk chemical feedstock and a highly purified pharmaceutical-grade reagent creates bifurcated demand profiles. Healthcare applications, particularly those tied to contrast media and sterile manufacturing environments, impose stringent quality protocols that constrain supplier qualification cycles and elevate barriers to entry. Simultaneously, industrial and electronics applications demand consistent volume reliability, forcing producers to balance capacity utilization across disparate downstream markets. The report deconstructs these dynamics by mapping how source availability, extraction economics, and processing pathways influence marginal pricing behavior and long-term supply resilience.
Supply-Side Architecture and Sourcing Heterogeneity
Iodine production is inherently tied to geological and operational specificities that vary dramatically across geographies. The market relies on a diversified but concentrated set of sourcing pathways, including caliche ore extraction, underground brine processing, seaweed-derived recovery, and emerging recycling streams. Each pathway carries distinct capital intensity profiles, environmental compliance burdens, and geographic exposure. Caliche ore operations, historically anchored in South America, offer scale advantages but are subject to weather variability, water management constraints, and regulatory scrutiny around extraction practices. Brine-based extraction, conversely, benefits from integration with natural gas and oilfield infrastructure, enabling co-production efficiencies but exposing operators to energy price volatility and subsurface management risks.
The strategic implication for procurement and supply chain leaders is that sourcing diversification cannot be treated as a passive inventory tactic. It requires active portfolio management that accounts for production uptime reliability, assay consistency, and the logistical complexity of moving high-purity intermediates across borders. The report provides a granular assessment of how these sourcing architectures interact with regional demand centers, mapping where supply surpluses and deficits are likely to emerge as capacity additions materialize and as downstream manufacturing footprints shift. Importantly, the analysis avoids oversimplified regional generalizations, instead presenting a nuanced evaluation of how trade flows, freight dynamics, and local regulatory environments shape actual availability at the plant gate.
Demand Ecosystem and Application Interdependence
The demand landscape for iodine is characterized by pronounced application interdependence. Diagnostic imaging remains a cornerstone of value creation, with iodine-based contrast agents representing a critical input for radiological procedures worldwide. The pharmaceutical sector absorbs significant volumes not only for active pharmaceutical ingredient synthesis but also for sterilization, formulation stabilization, and specialized halogen chemistry. In parallel, the display and electronics industries utilize iodine derivatives in polarizing films and precision manufacturing processes, linking market performance to consumer electronics cycles and industrial automation trends. Agricultural feed supplementation and industrial catalysis further broaden the demand base, introducing cyclicality tied to livestock production economics and process optimization schedules.
Bromine Market
For strategic decision-makers, the key insight is that these application segments do not expand in isolation. Capacity adjustments in one vertical reverberate across pricing behavior, inventory positioning, and supplier negotiation leverage in others. When diagnostic imaging demand accelerates due to aging demographics or healthcare infrastructure investment, the resulting tightness propagates to pharmaceutical-grade supply pipelines, which in turn influences the economics of bulk chemical allocations. The report models these cross-segment sensitivities, enabling users to simulate how demand shocks or capacity expansions in specific verticals will cascade through the broader market. This level of structural modeling is particularly valuable for organizations that manage multi-application supply contracts or that evaluate vertical integration opportunities spanning raw material extraction through finished-product formulation.
Competitive Concentration and Strategic Positioning
Market concentration has become a defining feature of the iodine landscape. The report highlights a consolidated competitive structure in which a limited number of producers command a substantial share of global output. This concentration is not accidental; it reflects the technical complexity of high-purity iodine refinement, the capital requirements of brine and caliche infrastructure, and the regulatory qualification cycles demanded by pharmaceutical and healthcare customers. As a result, the barrier landscape favors operators with established extraction assets, vertically integrated processing capabilities, and long-standing qualification relationships with downstream buyers.
Leading producers illustrate divergent strategic archetypes. Companies anchored in South America leverage caliche ore and brine operations to achieve scale, while simultaneously expanding capacity to meet growing healthcare and industrial demand. Their positioning is reinforced by geographic proximity to key sourcing geology and established logistics corridors. Japanese manufacturers emphasize refined iodine extracted from natural gas brine, focusing on high-specification chemical and pharmaceutical inputs that integrate with Asian downstream manufacturing ecosystems. United Kingdom-based producers have pursued vertical integration through specialized extraction technologies, converting oilfield brines into crystalline iodine and halogen-based specialty chemicals, thereby linking upstream resource recovery with mid-stream pharmaceutical formulation. United States-based operators contribute through brine well extraction and recycling pathways, servicing pharmaceutical, healthcare, and industrial customers with high-purity compounds. Several Chilean enterprises operate caliche and brine assets that supply pharmaceutical and healthcare applications, reinforcing the country’s role as a foundational production hub. In parallel, specialized manufacturers and distributors in Japan and the United States provide pharmaceutical-grade iodine, high-purity compounds, and formulated products that bridge raw material supply with healthcare and research requirements.
These competitive archetypes are not static. The report tracks capacity expansion announcements, production ramp timelines, and strategic realignments that signal where market share may shift over the forecast period. Recent operational disclosures underscore a pattern of deliberate capacity enhancement: one major producer announced expansion of its caliche extraction operations to increase annual iodine output, while another enterprise reported a production capacity increase designed to sustain industrial demand growth. Such moves illustrate how incumbents are proactively aligning supply with anticipated demand trajectories rather than reacting to shortages after they occur. For market entrants and incumbent strategists alike, understanding the timing, scale, and geographic focus of these expansions is essential for evaluating competitive threat surfaces and partnership opportunities.
Regulatory Catalysts and Supply Chain Sensitivity
Regulation and supply chain governance increasingly shape iodine market behavior. Medical product oversight has attracted heightened attention, with iodine-containing contrast media identified as a critical supply chain factor amid broader concerns about drug availability and manufacturing resilience. The inclusion of certain medical supply vulnerabilities on high-risk monitoring lists has reinforced the imperative for diversified sourcing, qualified secondary suppliers, and transparent inventory planning. Simultaneously, regulatory pathways for new contrast media formulations have advanced, with key submissions progressing through established approval mechanisms and expected agency determinations accelerating the timeline for market entry.
Trade policy dynamics add another layer of strategic complexity. Certain pharmaceutical import flows may be insulated from proposed tariff measures, altering the cost calculus for cross-border sourcing strategies and prompting reassessment of regional procurement architectures. In parallel, environmental and operational certifications have become meaningful differentiators, with select production divisions achieving recognized standards for energy management and environmental compliance, thereby strengthening their positioning in quality-sensitive downstream markets. These regulatory and compliance developments are not peripheral footnotes; they are structural inputs that influence supplier qualification lead times, contract risk allocation, and the long-term viability of specific sourcing relationships. The report integrates these factors into a cohesive risk framework, helping users anticipate where regulatory momentum will compress decision windows and where compliance leadership will become a competitive moat.
What the Report Delivers for Decision-Makers
The Iodine Market research study is structured to convert macro-level intelligence into actionable strategic guidance. It encompasses a full-spectrum assessment of market sizing across historical and forecast periods, segmentation analysis that maps how demand distributes across applications and sourcing pathways, and regional evaluations that identify where supply-demand balance is likely to tighten or loosen. Competition profiling extends beyond corporate descriptions to examine operational capabilities, capacity trajectories, and strategic positioning relevant to procurement, partnership, and entry decisions.
Beyond static market snapshots, the study provides practical tooling for scenario planning and operational calibration. It examines recent capacity and production developments to contextualize near-term availability, analyzes regulatory and trade developments that affect cost structures and sourcing options, and evaluates concentration metrics that signal negotiation leverage and supply resilience. The report also addresses production economics, qualification pathways for pharmaceutical-grade inputs, and the implications of vertical integration strategies that span extraction, refinement, and downstream formulation. For organizations evaluating capital deployment, supplier consolidation, geographic diversification, or product portfolio expansion, the study supplies a structured evidentiary base that reduces uncertainty and supports defensible strategic choices.
Strategic Imperatives for 2026 and Beyond
As market participants advance into the forecast window, several strategic imperatives become clear. First, supply chain architecture must be treated as a dynamic capability rather than a static contract portfolio. Qualification lead times, regulatory volatility, and capacity expansion timing all reward early mapping of secondary sources, prequalified alternate suppliers, and contingency inventory designs that align with actual production risk rather than theoretical coverage.
Second, competitive positioning will increasingly reward operators and buyers that can align quality assurance with cost discipline. The bifurcated nature of the market means that premium pharmaceutical-grade supply and volume-sensitive industrial supply follow different economics. Organizations that can segment their iodine demand by specification criticality, lead-time tolerance, and substitution feasibility will be better equipped to negotiate, source, and allocate without sacrificing operational continuity.
Third, geographic and regulatory awareness must be embedded into procurement forecasting. Tariffs, approval timelines, environmental certifications, and oversight scrutiny are not isolated externalities; they alter the relative attractiveness of sourcing regions and the speed at which new capacity becomes commercially usable. The organizations that integrate these variables into their planning cycles will be better positioned to avoid reactive purchasing, mitigate concentration risk, and capture favorable terms as market conditions evolve.
Iodine Market
Conclusion
The iodine market stands at a point where steady macroeconomic expansion intersects with intensifying competitive concentration, regulatory sensitivity, and sourcing complexity. Growth at a compound annual rate of 4.26 percent across the forecast horizon to 2032, building on a base of approximately 1,750 million USD and progressing toward a valuation above 2,355 million USD, provides a compelling directional signal. Yet the strategic value of that signal depends entirely on the depth of the underlying intelligence used to interpret it. Our Iodine Market research report is designed to deliver precisely that depth: a disciplined, operationally oriented analysis that informs procurement strategy, competitive positioning, capacity planning, and risk governance. For executives seeking to convert market visibility into durable advantage, the full study provides the granular segmentation, competitive assessment, and scenario-sensitive analysis necessary to move from insight to execution.
For detailed analysis of this topic, please visit the official page: Iodine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com