

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: HNBR Hits $535M in 2025, Projects 7.45% CAGR to $883M by 2032

Strategic Intelligence for the Next Decade: Inside the Global HNBR Market Outlook 2026–2032
As industrial manufacturers navigate an increasingly complex landscape of material performance requirements, regulatory shifts, and supply chain volatility, the Hydrogenated Nitrile Butadiene Rubber (HNBR) sector has emerged as a critical enabler of high-durability engineering solutions. PW Consulting is pleased to introduce our latest comprehensive market study, designed to equip strategy leaders, procurement directors, and R&D teams with the actionable intelligence needed to make confident decisions in 2026 and beyond. This report distills a rigorous five-year historical analysis and a seven-year forward projection into a structured, decision-ready format that bridges material science, commercial dynamics, and competitive strategy.
A Market at a Narrative Inflection Point
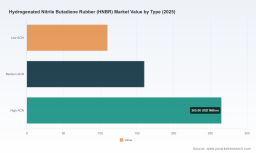
The global HNBR market has demonstrated consistent expansion over the past half-decade, evolving from a specialized elastomer niche into a cornerstone material for demanding sealing, fluid transport, and high-stress industrial applications. Drawing on verified shipment data, capacity disclosures, and price-tracking mechanisms, our analysis captures the trajectory from a baseline exceeding 535 million USD in 2025, with forward momentum accelerating through the second half of the decade. The compound annual growth rate projected across the 2026 to 2032 window reflects steady mid-single-digit expansion, driven by sustained demand from automotive powertrain evolution, energy sector reliability mandates, and industrial automation scaling.
This growth narrative is not uniform. Regional capacity investments, raw material corridors, and application-specific performance thresholds create divergent value pools that require targeted commercial strategies. Our report maps these structural shifts without resorting to surface-level summaries, instead providing decision-makers with the analytical scaffolding needed to prioritize geographic entry, capacity alignment, and product-mix optimization. By anchoring forecasts in transparent methodological assumptions and cross-validated supply-side indicators, we ensure that leadership teams can stress-test their strategies against multiple demand-and-supply scenarios.
What the Study Delivers: Decision-Ready Architecture
The HNBR Market Research report is structured to translate macro trends into executable insights. Rather than delivering a static data repository, the study is organized around the operational questions that shape capital allocation, supplier selection, and product roadmap planning. Readers will find a detailed examination of market sizing and forecasting frameworks, a breakdown of the principal grade categories that define competitive positioning, and a granular application mapping that connects end-use requirements to material selection criteria.
Each section is designed to support cross-functional alignment. Commercial teams will benefit from pricing trajectory analysis, capacity utilization indicators, and regional supply-demand balancing assessments. Technical and procurement stakeholders will find materials performance context, substitution dynamics, and regulatory influence mapping that clarify total cost-of-ownership considerations. Corporate development and investor relations groups will gain visibility into consolidation patterns, capacity expansion timelines, and the strategic implications of changing feedstock economics.
To maintain analytical rigor, the report integrates recent market developments directly into its forward-looking assessments. Capacity additions, production technology upgrades, pricing recalibrations, and product launches are evaluated not as isolated events but as components of a shifting competitive equilibrium. This approach allows readers to understand how individual corporate moves alter supply elasticity, influence regional price formation, and reshape customer procurement behavior.
Competitive Landscape: Leadership, Expansion, and Differentiation
The HNBR supply base is characterized by a concentrated group of established producers alongside regional players pursuing scale, cost efficiency, and application-specific differentiation. At the forefront of the global market stands Arlanxeo, headquartered in The Hague, Netherlands, recognized as the world's largest HNBR producer with an annual capacity approaching 16,000 tons. Its Therban grades serve automotive, oil and gas, and industrial sealing applications, and the company continues to reinforce its leadership through strategic capacity investments. In February 2026, Arlanxeo inaugurated a new 5,000 ton-per-year HNBR unit in Changzhou, China, backed by a 210 million USD investment and an oxidation process designed to reduce emissions by 80 percent, signaling a dual focus on scale and sustainability.
Hydrogenated Nitrile Butadiene Rubber (HNBR) Market
Nitrile Rubber (NBR) Market
Alongside this incumbent strength, Japanese material specialists maintain a strong presence through technology-driven product differentiation. ZEON Corporation, based in Tokyo, operates a 12,500 ton annual capacity and is known for its Zetpol grades tailored to extreme-temperature and aerospace applications. The company confirmed an expansion of its Zetpol production at its Pasadena, Texas facility, increasing global capacity by approximately 25 percent with completion targeted for early 2025. Kuraray Co., Ltd., also headquartered in Japan, supplies specialty elastomers under its own brand for high-temperature industrial and automotive applications, while JSR Corporation emphasizes high-performance grades for automotive and industrial use. Tosoh Corporation contributes additional depth to the Japanese specialty elastomer ecosystem with high-performance industrial and automotive HNBR offerings.
In South Korea, LG Chem manufactures HNBR under the Krynac brand, targeting oil-resistant and heat-stable applications with consistently high-quality grades. The competitive field also includes a growing set of Chinese producers who are expanding capacity and pursuing both domestic and export-market opportunities. Shandong Dawn Special Elastomer Material Co., Ltd. currently operates at 1,000 tons with plans to reach 3,000 tons, utilizing ruthenium catalysts and supplying both domestic and international channels; in June 2024, the company launched enhanced thermal stability HNBR polymers for high-performance applications. Sinopec Qilu Petrochemical brings low-cost, high-conversion capacity with conversion rates at or above 99 percent for industrial and automotive uses. Zannan SciTech Co., Ltd. continues to expand its presence through competitive pricing and an explicit focus on international market supply.
Compounding and distribution capabilities further shape the market's value chain. Rahco Rubber, Inc., based in the United States, operates as a compounder and distributor of HNBR for custom molded and extruded parts in seals, gaskets, and actuators, adding downstream flexibility for end-users requiring tailored formulations. Together, these players create a dynamic competitive environment where technology leadership, cost structure, regional proximity, and application specialization determine market share trajectories.
Market Dynamics: Cost, Regulation, and Demand Signals
HNBR pricing and procurement behavior do not evolve in isolation. They respond to raw material cost dispersion, regional inventory positioning, geopolitical feedstock disruptions, and regulatory substitution trends. Spot butadiene prices highlighted a significant regional gap in May 2025, ranging from 956 USD per ton in the US Gulf to 1,380 USD per ton in China, a 44 percent spread that directly influenced HNBR production cost structures and export competitiveness. Earlier, in February 2024, HNBR prices experienced a notable surge in the US market driven by strong demand, while Q1 2026 data showed North American prices rising by 2.39 percent quarter-over-quarter, reflecting inventory levels and near-term supply-demand balancing.
Feedstock volatility remains a persistent strategic consideration. Middle East conflict disruptions have increased naphtha and LPG feedstock costs, triggering volatility in NBR and HNBR production expenses and reminding buyers that input-cost sensitivity must be managed through contract design, sourcing diversification, and inventory planning. On the regulatory frontier, DuPont filed a PFAS-restriction dossier in March 2024 that named hydrogenated nitrile butadiene rubber as a non-fluorinated substitute for selected sealing duties. This type of regulatory reference reinforces HNBR's positioning as a high-performance alternative in applications where fluorinated materials face increasing scrutiny, expanding the material's relevance across both existing and emerging sealing requirements.
Beyond cost and regulation, competitive actions continue to reshape market conditions. In March 2025, Kingfa announced price adjustments for specialty elastomers including HNBR across multiple polymer categories, underscoring the interconnected nature of the elastomer landscape and the need for buyers to monitor broader polymer pricing signals. Taken together, these dynamics illustrate why static assumptions quickly become unreliable. Strategy teams require forward-looking, event-linked analysis that connects capacity moves, feedstock variability, pricing behavior, and regulatory developments into a coherent operating framework.
Structural Concentration and the Implications for Strategy
Market concentration remains a defining feature of the HNBR landscape. The leading producers collectively hold a substantial share of global capacity, creating a competitive environment where scale, process efficiency, and product differentiation carry disproportionate weight. High top-tier concentration often translates into pricing resilience for established suppliers, but it also intensifies the importance of customer-specific service, regional supply reliability, and technological edge. Buyers and investors alike must therefore assess not only headline market size but also the distribution of capacity, the accessibility of specialty grades, and the evolution of regional supply nodes.
Our report examines these concentration dynamics with a focus on practical implications. For procurement leaders, the analysis highlights where dual-sourcing, long-term agreements, and formulation flexibility can reduce exposure to concentrated supply risk. For corporate strategy and M&A teams, it clarifies where consolidation pressure may intensify and where regional expansion can create differentiated value. For R&D and product management groups, it identifies the performance thresholds and grade distinctions that separate commodity-adjacent offerings from premium high-performance solutions.
Why This Research Matters for 2026 Decision-Making
The 2026 decision environment calls for more than retrospective summaries. Materials strategy now intersects with decarbonization commitments, regional supply-chain reconfiguration, regulatory substitution pressure, and rapidly shifting demand profiles across automotive, energy, and industrial end markets. In that context, a well-constructed market study becomes a strategic asset rather than a reference document. It enables leadership to anticipate where capacity will be added, how pricing may respond to feedstock and demand fluctuations, which grades will capture premium positioning, and how regulatory signals may redirect material selection trends.
This publication is designed to support those decisions with clarity and discipline. It combines rigorous forecasting methodology with real-world corporate developments and supply-chain context, allowing readers to move from broad market awareness to specific, scenario-informed action. Whether the objective is to evaluate supplier consolidation risk, plan regional sourcing adjustments, align product roadmaps with performance requirements, or assess investment opportunities in high-growth application segments, the report provides the evidentiary basis needed to proceed with confidence.
Accessing the Full Intelligence Package
The overview presented here reflects the analytical direction and structural approach of the complete study, but the full strategic value resides in the detailed segmentation, company-level assessments, regional supply-demand balancing, pricing trajectory analysis, and scenario modeling included in the final report. To explore the complete market sizing framework, competitive benchmarking, application-specific growth drivers, and forward-looking strategic recommendations, we invite you to access the full report on the PW Consulting website. The complete intelligence package is structured for immediate use by strategy, procurement, technical, and corporate development teams seeking to align their 2026 plans with a clear and substantiated view of the HNBR market's trajectory through 2032.
For detailed analysis of this topic, please visit the official page: Hydrogenated Nitrile Butadiene Rubber (HNBR) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com