

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Machinery & Automotive
PW Consulting: Cooperage Equipment Market Hits $210.5M in 2025, Projects 6.85% CAGR to 2032
By pmarketresearch, 2026-09-16
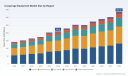
Strategic Intelligence for the Cooperage Equipment Market: Navigating the 2026 Landscape
Executive Overview
The global cooperage equipment market is undergoing a structural transformation, driven by tightening quality standards in premium winemaking, evolving spirits aging protocols, and continuous automation across production facilities. Our latest market research provides decision-makers with a rigorous, forward-looking assessment of how equipment procurement, capacity planning, and competitive positioning will evolve through 2032. For executives operating in food and beverage manufacturing, industrial packaging, or specialized barrel production, this intelligence report delivers the analytical framework needed to align capital allocation with long-term operational resilience.
Drawing on historical performance data spanning 2020 through 2025 and projecting forward across the forecast period, the study maps a clear trajectory of sustained expansion. The overall market revenue reached approximately 210.5 million USD in 2025, reflecting a compound annual growth rate of 6.85 percent projected across the forecast horizon. By 2032, the sector is positioned to surpass 336 million USD in total revenue. These figures represent more than isolated growth metrics; they signal a maturing equipment ecosystem that is increasingly defined by precision engineering, workflow integration, and selective automation. For corporate strategists, understanding where value is concentrated and how purchasing priorities are shifting will determine competitive advantage in the coming cycle.
Market Trajectory and Strategic Implications
The historical arc from 2020 to 2025 reveals a consistent upward trend, with periodic accelerations tied to capacity expansions and technology adoption cycles. Revenue climbed from 142.35 million USD in 2020 to 151.89 million USD in 2021, then to 164.46 million USD in 2022, before reaching 173.91 million USD in 2023. The pace quickened notably as manufacturers invested in modernization, pushing figures to 202.97 million USD in 2024 and stabilizing at 210.5 million USD in 2025. This progression illustrates how post-pandemic operational restructuring and sustained demand for high-quality aging containers have reinforced investment confidence.
Looking ahead, the forecast period outlines a steady climb: 228.85 million USD in 2026, followed by 252.72 million USD in 2027. A brief normalization is expected in 2028 at 251.36 million USD, after which the market resumes its expansion toward 273.85 million USD in 2029, 290.19 million USD in 2030, 302.36 million USD in 2031, and 336.32 million USD in 2032. This pattern reflects a market that is not merely growing but recalibrating around efficiency, durability, and process control. Strategists should interpret these movements as indicators of where procurement budgets will be allocated, which equipment categories will face supply constraints, and how regional production networks will respond to shifting input costs.
Category Architecture and Operational Demand
The report dissects the market through multiple lenses, beginning with equipment type. Automatic equipment currently commands the larger revenue share, reflecting a broader industry preference for integrated handling, precision toasting, and repeatable finishing workflows. Manual equipment maintains a substantial presence, particularly among smaller production houses and specialty operations that prioritize flexibility and lower upfront capital exposure. The balance between these two categories continues to evolve as labor availability, throughput expectations, and quality assurance requirements reshape purchasing criteria.
Cooperage Equipment Market
Application segmentation further clarifies how demand is distributed across end-use environments. The food and beverage sector anchors the majority of equipment consumption, driven by beverage maturation, barrel maintenance, and hygiene-focused processing requirements. Industrial applications follow as a secondary but strategically important segment, while other specialized uses contribute additional demand where customized barrel construction or niche finishing processes are required. Understanding how these application streams interact with procurement cycles, maintenance schedules, and technology upgrade paths is essential for forecasting equipment utilization and capital replacement timing.
Wine Fermentation Equipment Market
Geographic Distribution and Supply Chain Considerations
Regional dynamics play a defining role in how equipment demand materializes. Europe represents the most significant market concentration, reflecting the depth of traditional barrel craftsmanship, established winery infrastructure, and sustained investment in aging-related processing. North America follows as a major demand center, shaped by large-scale beverage production, expanding distillery operations, and ongoing facility modernization. Asia Pacific, Latin America, and the Middle East and Africa collectively add further layers of growth, with each region exhibiting distinct procurement rhythms, import dependencies, and capacity-building timelines.
For strategic planners, regional variation is not simply a geographic breakdown but a signal of where service networks, parts availability, and technical support must be positioned. Companies evaluating expansion, distributor partnerships, or localized service capabilities will find the report’s regional analysis instrumental in mapping execution risk and identifying where equipment deployment is likely to face the strongest operational pull.
Competitive Landscape and Enterprise Positioning
The market’s competitive structure remains moderately concentrated, with the top three participants accounting for approximately 38.5 percent of revenue and the top five reaching about 52.7 percent. This concentration indicates a landscape where established suppliers hold meaningful influence over product standardization, service ecosystems, and technological direction, while still leaving room for specialized players to differentiate through application expertise, regional reach, and targeted product lines.
Within this environment, several companies illustrate the breadth of strategic approaches shaping the sector. Prospero Equipment Corporation, headquartered in Windsor, California, supplies cooperage equipment including barrel washers, hoop drivers, and stave planers designed for wine and spirits producers. Its recent expansion of an updated product catalog in October 2025, featuring enhanced barrel toasting and steaming equipment lines, underscores how suppliers are aligning product portfolios with production efficiency and quality consistency.
Winequip, based in Melbourne, Australia, provides cooperage machinery such as barrel repair tools, toasting equipment, and automated barrel handling systems. Its product breadth highlights the growing importance of post-production maintenance, repair capabilities, and workflow automation in sustaining long-term equipment utilization. Vintner Vault, operating from Paso Robles, California, distributes cooperage equipment including barrel racks, washing systems, and maintenance tools tailored for commercial wineries. Its distribution-oriented model demonstrates how channel strategies continue to influence equipment accessibility and implementation speed for operating facilities.
These enterprises represent different facets of the same competitive logic: product reliability, application-specific support, and the ability to meet evolving throughput expectations. The report evaluates how such players position themselves across product lines, geographic coverage, and service intensity, giving buyers and investors a structured view of where partnerships, procurement consolidation, or competitive displacement may emerge.
Operational Pressures and Input Market Reality
Equipment strategy cannot be separated from the material environment in which it operates. In 2025, French oak stave prices increased by 12 percent year-over-year due to supply constraints from European forests. This shift directly affects barrel production economics and, by extension, the demand profile for equipment that improves yield, reduces waste, and standardizes finishing outcomes. When raw material volatility intensifies, manufacturers and distributors increasingly look to equipment investments that enhance process control, improve throughput predictability, and support more consistent aging results.
For procurement leaders, this dynamic reinforces the importance of evaluating equipment not only on purchase price but on total operational value: durability, serviceability, integration with existing line configurations, and the capacity to adapt to material variability. The study incorporates these considerations into its analytical framework, helping decision-makers weigh capital deployment against the backdrop of input cost pressure and supply chain uncertainty.
What the Research Delivers for 2026 Decision-Making
This market research is structured to support practical strategic action rather than abstract observation. It combines historical trend analysis, forward-looking projections, category-level segmentation, and competitive profiling into a single decision-support framework. Readers will gain clarity on how equipment demand is evolving across major application streams, where automation is reshaping purchasing priorities, and how leading suppliers are adjusting their portfolios in response to production and material conditions.
The report also provides guidance on evaluating procurement timing, assessing service and maintenance requirements, and interpreting regional demand signals that influence deployment strategy. By integrating market size progression, concentration patterns, and company-level developments into a coherent narrative, the study enables executives to benchmark internal plans against broader market movement and to identify where strategic investment may yield the strongest operational return.
Conclusion
The cooperage equipment market is entering a phase where growth is increasingly tied to operational precision, automation maturity, and responsiveness to material cost dynamics. With revenue projected to advance from 228.85 million USD in 2026 toward 336.32 million USD by 2032, the sector presents both opportunity and execution risk for organizations navigating equipment procurement, production scaling, and competitive positioning. This research report is designed to give strategists, purchasing leaders, and industry executives the context needed to make informed decisions with confidence. To access the complete segmentation analysis, regional breakdowns, application-level demand patterns, and full competitive profiling, visit the source page for the complete intelligence package.
For detailed analysis of this topic, please visit the official page: Cooperage Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Commercial Vehicle Power Steering Pump Market to Grow 5.85% CAGR to $8,084.85M by 2032
By pmarketresearch, 2026-09-16
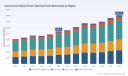
Navigating the Shift: Why the Commercial Vehicle Power Steering Pump Market Demands Strategic Attention in 2026
The commercial vehicle landscape is undergoing a quiet but decisive transformation. Where brute mechanical force once dictated steering architecture, today’s OEMs are prioritizing energy efficiency, electronic integration, and compliance with tightening emissions mandates. At the center of this evolution sits the power steering pump—a component that has transitioned from a standard hydraulic accessory to a strategic node in vehicle dynamics, fuel economy, and electro hydraulic system architecture. For supply chain leaders, mobility investors, and tier-one strategists, understanding where this market is heading is no longer optional. It is a prerequisite for positioning ahead of the 2026–2032 cycle.
Our newly released Commercial Vehicle Power Steering Pump Market study delivers a structured, decision-ready view of this landscape. Rather than offering a static snapshot, the analysis is built to support scenario planning, portfolio evaluation, and competitive positioning as the sector moves through its next phase of consolidation and technology migration.
A Market Built on Measured Growth and Functional Transition
The commercial vehicle power steering pump market has demonstrated consistent expansion over the past half-decade, with total revenue climbing from approximately USD 4.1 billion in 2020 to an estimated USD 5.4 billion in 2025. That trajectory reflects more than volume growth; it signals a structural shift in how commercial fleets balance performance, operating cost, and regulatory exposure. Looking forward, the market is projected to advance at a compound annual growth rate of 5.85 percent across the 2026–2032 forecast horizon, reaching a valuation close to USD 8.1 billion by 2032.
Commercial Vehicle Power Steering Pump Market
This pace is neither explosive nor incremental in a vacuum. It is shaped by overlapping forces: the continued deployment of medium and heavy commercial platforms, the gradual substitution of traditional hydraulic assemblies with electro hydraulic and variable-displacement alternatives, and the pressure on manufacturers to reduce parasitic engine loads without compromising steering feel or safety. For decision-makers, the implication is clear. Growth in this segment will increasingly reward players who can align product roadmaps with efficiency benchmarks, electronics readiness, and regional compliance requirements rather than those who compete solely on volume or legacy supplier relationships.
What the Study Delivers: An Operational Lens on a Complex Ecosystem
The report is designed as a working reference for teams that need to translate market signals into sourcing, R&D, pricing, and partnership decisions. It combines historical reconstruction with forward-looking scenario analysis, giving readers a base year of 2025 and a forecast window extending through 2032. The structure supports both strategic overview and tactical interrogation, allowing users to examine demand drivers, product migration paths, and the competitive mechanics that shape supplier leverage.
Key analytical dimensions include:
Worldwide Automotive Power Steering Market
- Demand architecture across commercial vehicle segments , examining how light commercial vehicles, heavy commercial trucks, and buses/coaches place different performance, durability, and packaging requirements on steering pump systems.
- Product-type evolution , contrasting conventional hydraulic power steering pumps with electro hydraulic variants as OEMs pursue energy recovery, power-on-demand functionality, and reduced idle load.
- Regional demand distribution , mapping how mature commercial vehicle markets and high-volume manufacturing corridors differ in adoption timing, procurement behavior, and technology acceptance.
- Competitive intensity and supplier positioning , evaluating concentration patterns, differentiation levers, and the strategic moves that define current market leadership.
- Input cost and regulatory sensitivity , assessing how metal pricing volatility and emissions-driven mandates alter cost structures and accelerate the case for more efficient steering architectures.
- Recent product and technology milestones , capturing the launches, showcases, and system-level innovations that indicate where incumbent suppliers are placing their bets.
Each section is built to be actionable. Historical series provide a calibration baseline. Forecast logic ties together vehicle production assumptions, component substitution trends, and efficiency requirements. Competitive profiling goes beyond nameplate recognition to examine how suppliers are structuring their portfolios for medium and heavy commercial applications. The result is a research instrument that can support procurement hedging, engineering prioritization, M&A screening, and regional entry planning without requiring the reader to assemble disparate data points from multiple sources.
Competitive Landscape: Concentration, Differentiation, and the Push Toward Efficiency
The commercial vehicle power steering pump space is not a fragmented commodity market. It is a concentrated arena where technical differentiation, application expertise, and integration capability determine bargaining power. Current market concentration indicators point to a moderately consolidated environment, with the leading trio of suppliers accounting for a substantial share of revenue and the top five players extending that footprint further. In practical terms, this means scale, portfolio breadth, and proximity to OEM platform decisions still matter enormously.
Several established players illustrate the strategic directions shaping the segment. German suppliers continue to reinforce the link between steering hydraulics and vehicle-level efficiency. Bosch has built a recognizable position around hydraulic and electro hydraulic power steering systems for medium and heavy commercial vehicles, including variable displacement pump technology designed to reduce consumption. Its recent showcasing of a fourth-generation electro hydraulic steering system for commercial trucks—emphasizing ADAS compatibility and power-on-demand operation—signals a clear move toward steering architectures that interact more closely with advanced driver assistance and electronic control layers. Earlier presentations of electro hydraulic generations for heavy vehicles, with production timing aligned to the mid-2024 cycle, reinforce a sustained push into more integrated steering solutions.
ZF Friedrichshafen AG occupies a similarly influential position, offering ball-and-nut power steering systems and energy-efficient hydraulic pump variants alongside advanced electro hydraulic options for trucks and buses. Its portfolio reflects the broader industry tension between maintaining hydraulic performance expectations and lowering energy draw across duty cycles. Across the Atlantic, Nexteer Automotive has sharpened its focus on hydraulic power steering systems and pumps optimized for fuel efficiency and advanced driver assistance in heavy-duty trucks and commercial vehicles. Recent activity underscores that focus: a rear-wheel steering system developed to improve maneuverability in heavy vehicles, and a high-output electrified power steering solution targeting increased steering assist capacity for larger commercial platforms. These moves highlight how steering is being treated less as an isolated component category and more as part of a vehicle maneuverability and control strategy.
The landscape also includes suppliers with specialized engineering angles. Evamo has emphasized variable displacement vane pumps and electro hydraulic power steering pumps for medium to heavy commercial vehicles, with a stated emphasis on efficiency and CO₂ reduction—an increasingly relevant framing as fleet operators and regulators scrutinize total energy consumption. JTEKT Corporation supplies variable-flow steering pumps and hydraulic power steering solutions across commercial and light commercial applications, while Astemo has concentrated on power steering pumps with cast aluminum housing designed for commercial vehicle durability and efficiency. Concentric AB has taken a different route, developing electro hydraulic steering pumps for hybrid, fuel cell, and electric trucks and buses, directly addressing the displacement of conventional engine-driven pumps as powertrain architectures diversify. Maval Industries rounds out the field with power steering pumps and gears tailored to heavy-duty commercial and truck applications.
Together, these profiles reveal a market where competitive advantage is increasingly tied to efficiency claims, electronics compatibility, packaging for heavy-duty use, and the ability to support OEM transitions toward electrified or hybrid commercial platforms. The report examines these positions in greater depth, including how recent product activity is reshaping procurement conversations and where supplier vulnerability may emerge as regulations and powertrain mixes shift.
Industry Dynamics: Regulation, Input Costs, and the Efficiency Imperative
External pressures are not peripheral to this market; they are actively reordering priorities. Regulatory direction is one of the most consequential. European policy proposals targeting substantial carbon emission reductions for new heavy-duty commercial vehicles by 2030 are accelerating the search for components that contribute to lower overall energy consumption. In that context, a power steering pump is no longer judged only by steering performance. It is increasingly evaluated for parasitic load, duty-cycle efficiency, and compatibility with electrified or hybrid drivetrains.
Compliance expectations are also tightening on the operational side. Inspection-oriented regulations such as FMCSA Regulation 393.209, which requires commercial vehicle power steering systems to remain leak-free during inspections, reinforce the importance of reliability and sealing integrity in heavy-duty applications. For suppliers and fleet operators alike, this creates a dual mandate: improve efficiency without sacrificing durability or regulatory conformance.
Input cost volatility adds another layer of complexity. Fluctuations in aluminum and steel prices directly influence manufacturing economics for metal-housed power steering pumps, particularly where castings and structural components constitute a meaningful share of bill-of-materials cost. In an environment where procurement teams are already balancing performance upgrades against cost control, raw material exposure can determine margin resilience and pricing strategy. The research integrates these dynamics to help readers evaluate where cost risk is likely to concentrate and how suppliers may respond through design optimization, material strategy, or portfolio segmentation.
Why the 2026 Decision 윈도우 Requires a Deeper Read
The forecast period beginning in 2026 is not simply another year in a growth curve. It is a point where several trajectories converge: the maturation of electro hydraulic offerings, the continued presence of hydraulic pumps in cost-sensitive and high-duty applications, and the increasing need for steering systems that can coexist with ADAS features and alternative powertrains. In that environment, decisions made on the basis of aggregate market size alone will be insufficient.
Companies that want to act with confidence need to understand how demand is distributed across commercial vehicle types, which product types are gaining or losing relative share, where regional procurement patterns favor local content or imported systems, and how the leading suppliers are positioning their roadmaps against efficiency and electrification pressures. They also need a realistic view of competitive concentration: in a market where the leading suppliers hold a sizable revenue share, entry, expansion, or renegotiation strategies must account for the fact that incumbents are not standing still.
This is precisely the gap the full study is built to fill. The published analysis preserves the strategic framing outlined here while extending into the level of detail required for internal planning: scenario assumptions, segment-level demand logic, supplier positioning, technology migration patterns, and the cost and regulatory variables that shape near-term competitiveness.
Target Audience and Use Cases
The report is intended for teams that need a credible, structured foundation for commercial vehicle steering market decisions. Typical applications include:
- Component sourcing and procurement strategy , where understanding demand trends and supplier concentration supports supplier evaluation, negotiation stance, and risk diversification.
- R&D and product planning , where the shift between hydraulic and electro hydraulic solutions, variable displacement architectures, and electronics integration informs engineering priorities.
- Competitive and market intelligence , where recent product showcases, launches, and system-level announcements are placed in context rather than read as isolated press milestones.
- Investment screening and portfolio review , where market size, growth trajectory, concentration, and regulatory exposure help frame attractiveness and risk.
- Regional expansion or market-entry assessment , where demand distribution and application mix provide a starting point for more detailed local analysis.
Final Perspective: From Aggregate Growth to Strategic Positioning
The commercial vehicle power steering pump market is moving on a foundation of steady expansion, but its real story lies in the forces reshaping how value is created within that growth. Efficiency expectations, regulatory direction, powertrain diversification, and the steady integration of steering with broader vehicle electronics are all pushing suppliers and buyers toward more differentiated, more technically grounded decisions. In a market where the top suppliers already hold a meaningful revenue share and recent product activity points toward higher functionality and lower parasitic loss, the winners will be those who can interpret the signals early and align their strategies accordingly.
The full study translates that landscape into a usable intelligence platform. To access the complete segmentation logic, regional and application-level demand context, supplier competitive assessment, and forecast detail needed for 2026 planning, request the full report through our official research portal.
For detailed analysis of this topic, please visit the official page: Commercial Vehicle Power Steering Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Aerospace & Marine Data Recorders Market to Hit $3,512.35 Million by 2032, 5.85% CAGR
By pmarketresearch, 2026-09-16
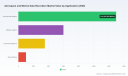
The Unblinking Eye: Strategic Intelligence in the Aerospace and Marine Data Recorders Market Through 2032
In an era where data integrity defines operational resilience, the aerospace and marine data recorders market stands as a critical infrastructure layer for global transportation safety, regulatory compliance, and fleet optimization. As aviation and maritime operators navigate tightening certification frameworks, expanding voyage logging mandates, and the steady digitization of legacy monitoring systems, the ability to anticipiate demand shifts, technology migration paths, and competitive positioning has moved from optional to indispensable. Our latest market intelligence study, spanning historical performance from 2020 through 2025 and a forward-looking forecast window from 2026 to 2032, provides decision-makers with a rigorous, scenario-tested foundation for capital allocation, procurement strategy, and partnership development. This briefing outlines the structural drivers, competitive architecture, and regulatory tailwinds shaping the sector, while highlighting the analytical depth available in the full report.
The market has demonstrated steady, compounding growth over the past half-decade, reflecting both replacement-cycle maturity and incremental adoption of advanced recording architectures across commercial fleets, military platforms, and merchant marine operations. By 2025, the global market reached a baseline valuation that anchors our six-year projection period, with the trajectory pointing toward a compound annual growth rate of 5.85 percent through 2032. That growth is not merely a function of fleet expansion; it is increasingly driven by mandate-driven retrofits, higher-duration recording requirements, solid-state crash-survival standards, and the convergence of flight and voyage data into unified analytics pipelines. For executives planning multi-year programs, understanding where growth concentrates, which product families are gaining traction, and how regional procurement cycles align with certification timelines is essential for de-risking investment and capturing share in a moderately concentrated landscape.
Market Trajectory and Structural Dynamics
The historical record from 2020 to 2025 reveals a market that has consistently expanded beyond the pace of general transportation GDP, underscoring the regulatory and safety-driven nature of demand. The transition from older magnetic-tape and low-capacity solid-state units toward higher-density, networked, and longer-duration recording platforms has accelerated replacement cycles across both aerospace and marine end markets. Over the forecast horizon, the market is projected to climb steadily, crossing the mid-2020s threshold and advancing toward a valuation exceeding 3.5 billion dollars by 2032. This path is supported by durable demand for flight data recorders and cockpit voice recorders in commercial aviation, complemented by voyage data recorders and simplified voyage data recorders in maritime applications, alongside specialized quick access recorders that serve maintenance, engineering, and flight-safety analytics workflows.
Several structural forces underpin this trajectory. First, regulatory milestones are reshaping minimum equipment lists. In commercial aviation, federal and European certification authorities have moved to require cockpit voice recorders capable of at least 25 hours of continuous audio recording on new aircraft, with solid-state, crash-survivable designs becoming the norm. Parallel international civil aviation standards continue to specify minimum recording parameters and survivability thresholds for flight data recorders, effectively locking in baseline demand for upgraded units across narrow-body, wide-body, and freighter fleets. In the maritime domain, international maritime organization performance standards and associated classification society interpretations mandate voyage data recording on passenger ships and cargo vessels above defined tonnages, while simplified voyage data recorder requirements extend coverage to a broader segment of the merchant fleet. These requirements create a non-discretionary demand floor that sustains volume even when cyclical procurement budgets tighten.
Second, the operational value proposition of data recorders is expanding beyond accident investigation and compliance. Airlines, cargo operators, business jet fleets, and naval programs increasingly treat recorded data as an input to predictive maintenance, pilot training analytics, route optimization, and fleet reliability programs. Quick access recorders and data acquisition units have gained relevance as intermediaries that feed ground-side analytics platforms, enabling operators to extract actionable insights without waiting for post-incident retrieval. This functional expansion supports higher attachment rates for advanced recorder configurations and encourages vendors to bundle hardware with data handling software, download tools, and integration services. Third, supply chain normalization and component availability have improved the feasibility of large-scale retrofit programs, allowing operators to phase in 25-hour recording architectures and solid-state survivability upgrades across in-service fleets rather than deferring until next-generation deliveries.
Geography and application mix further shape the growth pattern. Demand in North America remains anchored by mature commercial aviation fleets, active business aviation channels, and sustained defense-related procurement, while European markets benefit from stringent certification alignment and strong MRO networks. Asia Pacific reflects a combination of airline capacity growth, new aircraft deliveries, and expanding maritime trade infrastructure, creating incremental recorder demand across commercial and naval use cases. Latin America and the Middle East and Africa contribute more specialized but strategically important volumes tied to regional airline development, offshore marine activity, and government procurement cycles. Across applications, commercial aviation represents the largest demand pool, supported by recurring fleet refreshes and mandate-driven upgrades, while military aviation, commercial marine, and naval marine segments each present distinct purchasing rhythms, performance requirements, and integration constraints.
Regulatory Catalysts and Technology Migration
Regulation is the single most reliable demand catalyst in this market, and the current cycle introduces requirements that are reshaping both product design and lifecycle economics. The move to 25-hour cockpit voice recording mandates on new aircraft platforms compels operators and manufacturers to adopt recorder configurations that can sustain longer continuous capture without compromising crash survivability or retrieval reliability. Solid-state architectures have become the default expectation, offering greater resilience, faster data access, and improved compatibility with ground-side download and analysis workflows. These design shifts are not cosmetic; they influence bill-of-materials costs, qualification timelines, and the competitive positioning of incumbent suppliers versus newer entrants offering integrated connected-recorder solutions.
In the maritime sector, voyage data recorder mandates under international maritime organization performance standards and related code requirements continue to expand the addressable base across passenger vessels and cargo ships. The availability of simplified voyage data recorder options has broadened compliance pathways for smaller tonnage segments, while classification society expectations and port-state control scrutiny elevate the importance of certified, maintainable recording equipment. The practical effect is a market where compliance hardware must also satisfy operational durability, environmental hardening, and integration with bridge monitoring and ship performance systems. This dual mandate—regulatory conformity plus operational utility—favors suppliers that can deliver certified recorders alongside dependable data retrieval and performance monitoring capabilities.
Technology migration is also evident in the growing emphasis on connectivity and standardized data handling. Connected recorder platforms designed for extended voice and flight data capture are increasingly expected to interface cleanly with airline maintenance ecosystems and aircraft manufacturer distribution channels. Recent platform-specific availability announcements for major narrow-body and wide-body programs illustrate how recorder upgrades are being slotted into existing OEM and MRO pipelines, reducing installation friction and accelerating fleet-wide adoption. At the same time, data download tooling and interoperability arrangements are becoming strategic differentiators, as operators seek to streamline post-flight data extraction, minimize ground-time penalties, and integrate recorder outputs into broader flight data management environments.
Competitive Landscape and Strategic Positioning
The market exhibits a moderately concentrated structure, with a leading cohort of specialized aerospace and marine instrumentation providers commanding a significant share of qualified demand. This concentration reflects the certification-heavy nature of the sector, where qualification timelines, type-certification alignment, and long-term support commitments create meaningful barriers to entry. Incumbents with deep black-box heritage, established relationships with airframe and ship-equipment programs, and proven crash-survival pedigrees retain a durable advantage, while selective partnerships and licensing arrangements are reshaping how data handling features are commercialized.
Honeywell International remains a defining presence in the aerospace recording segment, drawing on more than sixty years of black-box technology experience to supply flight recorders for commercial aviation platforms. Its connected recorder series for extended cockpit voice and flight data recording has become particularly relevant as operators prepare for 25-hour voice mandates, and recent platform-specific availability for major airframer programs signals how recorder upgrades are being integrated into established delivery and service channels. Curtiss-Wright Defense Solutions complements this ecosystem with its own flight recorder portfolio and collaboration on extended-duration CVR/FDR systems for commercial, cargo, and business jet applications, reinforcing the trend toward shared architectures that reduce qualification duplication and broaden installation options.
Acron Aviation, formerly known in the commercial aviation solutions space, contributes cockpit voice and flight data recorder configurations tailored to commercial and specialized aircraft applications, with combined recording units that simplify installation and data management for operators seeking compact, reliable solutions. HR Smith Group addresses adjacent aerospace needs through combined position indicators with memory modules for recorder data storage and emergency locator beacons, illustrating how complementary subsystems increasingly intersect with the broader data recording value chain. Teledyne Controls rounds out the aerospace-focused cohort with data acquisition units, flight data management systems, and support for recorder data handling across aerospace platforms, positioning the company to benefit from the growing emphasis on post-recording analytics and ground-side data workflows.
On the marine side, Danelec Marine and Furuno Electric anchor a strong maritime recording segment, with Danelec emphasizing voyage data recorders and ship performance monitoring systems, while Furuno delivers voyage data recorder and simplified voyage data recorder product lines aligned with international maritime organization standards for merchant marine vessels. AMI Marine and Consilium further expand the maritime roster, offering voyage data recorder and simplified voyage data recorder systems for a range of vessel types and emphasizing compliance with international maritime organization and international electrodotechnical commission standards. Together, these providers reflect a competitive field in which certification readiness, environmental durability, and integration with vessel monitoring architectures are decisive differentiators.
Aerospace and Marine Data Recorders Market
Cockpit Voice and Flight Data Recorder Market
Recent activity underscores how quickly the competitive and commercial landscape can shift around a single regulatory or platform milestone. A major connected recorder configuration reached availability for leading narrow-body and wide-body platforms to meet extended voice recording mandates, followed by a distribution collaboration announced at a major MRO event and a separate licensing arrangement covering data download interoperability for a combined cockpit voice and flight data recorder family. These developments are not isolated product launches; they are signals of how compliance deadlines, OEM channel relationships, and data-handling tooling are converging to determine which suppliers capture retrofit volume and new-delivery attach rates during the forecast period.
What the Study Delivers
This report translates market complexity into decision-ready structure. It opens with a full market sizing and forecast model that traces historical performance and forward projections across the 2026 to 2032 window, giving executives a consistent baseline for scenario planning. The analysis decomposes demand by type, application, and region, enabling readers to isolate the segments most relevant to their portfolio, procurement calendar, or investment thesis. Rather than presenting static figures, the study examines the mechanics behind each split, including mandate-driven retrofit timing, fleet delivery momentum, and the interplay between commercial and defense procurement cycles.
The competitive section profiles the leading participants shaping the market, mapping product families, geographic reach, certification footprints, and strategic moves that are likely to influence share dynamics. It evaluates partnership, collaboration, and product-launch activity as indicators of channel access and technology direction, helping readers distinguish between incremental updates and structural shifts in competitive advantage. The regulatory and dynamics component weaves together civil aviation and maritime requirements into a single operational narrative, explaining how standards translate into equipment specifications, installation constraints, and lifecycle support obligations.
Practical modules extend the analysis into actionable territory. Readers gain access to procurement and replacement-cycle considerations, data handling and connectivity trends, and guidance on where certification risk is likely to concentrate as mandates phase in across new-production and in-service fleets. The study also outlines the implications for suppliers, system integrators, MRO providers, and fleet operators, with attention to where value is created in hardware, software, data services, or integrated solution bundles. Throughout, the focus remains on usable intelligence: not just what the market is doing, but why it is doing it, and how that behavior is likely to evolve under different regulatory and commercial scenarios.
Conclusion: From Compliance to Competitive Advantage
The aerospace and marine data recorders market is entering a phase in which regulatory mandates, platform-specific certification progress, and expanding data analytics use cases will jointly determine growth intensity and competitive outcomes. For companies operating in this space, the strategic question is no longer whether demand will persist, but where the highest-value demand will concentrate, which recorder architectures will become the default for new deliveries and retrofits, and how quickly interoperability and data handling capabilities will separate leaders from followers. A market growing at a steady multi-year compound rate toward a 2032 valuation above 3.5 billion dollars offers substantial opportunity, but capturing it requires clarity on segment timing, regional procurement rhythms, and the shifting balance between compliance-driven volume and analytics-enabled upgrades. The full study provides the detailed segmentation, competitive mapping, and forward scenarios needed to translate these dynamics into defensible strategy. For executives preparing 2026 plans and beyond, the report is designed to turn regulatory complexity and market breadth into a clear, actionable roadmap.
For detailed analysis of this topic, please visit the official page: Aerospace and Marine Data Recorders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dental Market Hits $36.9B, 9.25% CAGR to $68.49B by 2032
By pmarketresearch, 2026-09-15
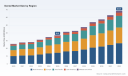
Unlocking Value in a Reshaping Landscape: Strategic Imperatives for the Dental Market Through 2032
The global dental sector is navigating a period of profound transformation. Driven by an aging population, expanding insurance coverage, and rapid technological integration, the market has demonstrated remarkable resilience and growth potential. For enterprise leaders, investors, and strategic planners, understanding the trajectory of this sector is not merely an academic exercise but a critical component of capital allocation and product roadmapping for the coming years.
Our latest comprehensive market research study offers a rigorous examination of the Dental Market, providing a data-rich foundation for decision-making in 2026 and beyond. This article serves as a strategic overview, highlighting the macro trends and competitive dynamics shaping the industry, while outlining the actionable intelligence contained within our full report.
Market Trajectory and Macro Growth Signals
The historical performance of the dental sector provides a robust baseline for forecasting future demand. Our analysis tracks market performance from 2020 through 2025, capturing the recovery patterns and sustained expansion following global economic disruptions. The convergence of post-pandemic oral health awareness, rising disposable incomes in emerging economies, and the aesthetic demands of a digitally native consumer base has created a compelling growth environment.
Looking ahead, the market outlook remains exceptionally strong. Our forecasts project continued double-digit expansion over the next several years, driven by consistent demand across multiple vectors. The compound annual growth rate (CAGR) of 9.25% during the forecast period (2026-2032) underscores the sector's momentum. This growth is not linear; it is punctuated by waves of innovation, shifts in care delivery models, and evolving regulatory frameworks. For organizations strategizing for 2026, these projections offer a clear signal: the market is expanding, and the window for securing competitive advantage is open.
Revenue projections indicate a steady climb toward significant valuation milestones by the early 2030s. The trajectory suggests that cumulative reinvestment in dental infrastructure, technology, and consumables will yield substantial returns for market participants who align their strategies with these growth vectors. Understanding the magnitude of this expansion is essential for capacity planning, R&D budgeting, and M&A evaluation.
Dental Material Market
Macro Dynamics Shaping the 2026 Operating Environment
While top-line growth is attractive, success in 2026 requires a nuanced understanding of the underlying dynamics that influence margin profiles, supply chain stability, and consumer behavior. Our report dissects these forces to provide a clear picture of the operational realities facing dental enterprises.
Dental Market
Economic Pressures and Reimbursement Realities
Financial sustainability remains a central concern for practice owners and dental service organizations (DSOs). Recent data from the ADA Health Policy Institute indicates that while provider reimbursement rates remained stable in late 2025, they have not kept pace with overall inflation and rising practice expenses. This gap creates pressure on profitability, necessitating operational efficiencies and value-based service offerings. Simultaneously, material costs are rising; prices for dental equipment and supplies increased by 5% from the beginning of 2025. Navigating these cost dynamics requires precise procurement strategies and a keen eye on vendor negotiations.
Labor Market Nuances
The workforce landscape is evolving with subtle but significant shifts. As of December 2025, the total number of jobs in dental offices saw a slight monthly contraction of 0.2%, yet the year-over-year trend remained positive with a 1.3% increase. This suggests a tightening labor market where talent retention and specialized skill development are becoming critical differentiators. Organizations must consider how staffing models, training investments, and automation can mitigate labor constraints while maintaining high standards of care.
Regulatory and Ethical Clarity
The regulatory environment continues to mature, adding layers of compliance that demand attention. In May 2025, the Dental Trade Alliance issued a revised U.S. Code of Ethics, providing greater clarity on interactions between manufacturers, distributors, and dental professionals. This update reinforces the importance of transparency and ethical engagement in commercial activities. Companies that proactively align their practices with these standards not only mitigate risk but also enhance their reputation and trustworthiness within the professional community.
Competitive Landscape: Incumbents, Innovators, and Consolidation
The dental market is characterized by a mix of established global leaders, specialized innovators, and robust distribution networks. Market concentration metrics indicate a moderately consolidated environment, with the top three players holding a CR3 of 42.8% and the top five reaching a CR5 of 48.2%. This structure suggests that while scale advantages exist, there is still significant room for differentiation and niche leadership.
Several key players define the competitive arena. Dentsply Sirona Inc., headquartered in Charlotte, North Carolina, stands as a leading global manufacturer of dental equipment, implants, restorative materials, and digital solutions. Their comprehensive portfolio positions them as a central force in both clinical delivery and practice management technology. Straumann Group, based in Basel, Switzerland, remains a global leader in dental implants, prosthetics, and regenerative products, leveraging strong clinical evidence and brand equity in high-value segments.
Innovation in orthodontics and digital workflows is exemplified by Align Technology, Inc. of San Jose, California. As the developer of Invisalign clear aligners and digital orthodontics technology, Align continues to drive shifts in treatment preferences and data-driven care. Ivoclar Vivadent AG, located in Schaan, Liechtenstein, and GC Corporation of Tokyo, Japan, are pivotal players in dental materials, ceramics, and restorative products, serving the essential needs of clinical procedures across diverse geographies. Coltene Group, Kerr Corporation, and 3M Oral Care round out a formidable field of manufacturers focused on consumables, endodontics, rotary instruments, and preventive solutions.
The distribution ecosystem is equally vital. Henry Schein, Inc., Patterson Companies, Inc., and Benco Dental Supply Company form a backbone of supply chain logistics, offering supplies, equipment, and services to a vast network of dental professionals. Henry Schein and Patterson provide full-service solutions that integrate technology and practice management, while Benco serves over 30,000 professionals across the United States with a localized, responsive approach. Additionally, organizations like Yankee Dental Congress facilitate trade and supplier networks, supporting the commercial infrastructure that keeps the market vibrant.
Recent developments highlight the pace of product innovation. In 2025, COLTENE Group launched six new innovations, including HySolate Liquid Dam for advanced gingiva protection and Kenda ShapeGuard for next-generation polishing. Kerr Dental introduced next-generation shaping solutions, pre-sterilized diamond burs, and bioceramic sealers, enhancing procedural efficiency. Dentsply Sirona expanded its digital ecosystem with a new implant product selection guide on its U.S. e-commerce platform featuring the DS OmniTaper Implant. Other players like Parkell and Garrison Dental Solutions also unveiled advanced composites and matrix systems, signaling a continuous stream of incremental improvements that cumulatively raise the bar for performance and patient experience.
Strategic Implications for Enterprise Decision-Makers
For executives preparing for 2026, the interplay of growth, cost pressures, and competitive intensity demands a multifaceted strategy. Our research identifies several critical focus areas:
- Product and Portfolio Alignment: With consumables representing a significant share of revenue and equipment driving long-term value, companies must balance their portfolios to address immediate clinical needs while positioning for digital and precision advancements. Understanding the specific revenue contributions and growth rates of each segment is essential for resource allocation.
- Geographic Diversification and Local Insight: Growth opportunities vary significantly across regions. While mature markets offer stability and high per-capita spend, emerging regions present volume potential and infrastructure development needs. A granular understanding of regional market sizes, maturity levels, and consumer preferences is required to tailor go-to-market strategies effectively.
- Channel and Distribution Optimization: The role of distributors is evolving from mere logistics to value-added partner ecosystems. Leveraging the strengths of major distributors and trade networks can enhance market reach and customer engagement. Decision-makers must evaluate channel partnerships based on service quality, geographic coverage, and alignment with brand positioning.
- Innovation and Time-to-Market: The frequency of product launches among key competitors underscores the need for agile R&D and rapid commercialization. Staying ahead requires not only technological superiority but also a deep understanding of clinical workflows and practitioner pain points.
- Risk Management and Compliance: With reimbursement pressures, cost inflation, and evolving ethical codes, a proactive approach to risk is non-negotiable. Building resilience into supply chains, monitoring reimbursement trends, and adhering to the highest standards of professional conduct are foundational to long-term success.
Inside the Research: What Our Full Report Delivers
This article provides a strategic snapshot, but the depth of insight required for confident decision-making lies in our comprehensive market research report. Designed for senior leadership, strategy teams, and investors, the study offers an exhaustive analysis of the Dental Market, encompassing historical performance, detailed forecasts, and segment-level intelligence.
The report delivers actionable content across multiple dimensions:
- Market Sizing and Forecasting: We provide precise revenue estimates and growth projections spanning the base year through the forecast period of 2032. The analysis captures the full trajectory of market expansion, enabling accurate budgeting and investment planning.
- Segmentation Analysis: The research breaks down the market by region, type, and end-user, revealing the distinct performance characteristics and opportunities within each segment. This granular view allows stakeholders to identify high-growth pockets, assess competitive intensity, and prioritize markets based on revenue potential and strategic fit.
- Competitive Profiling: Detailed company profiles examine the capabilities, market positions, and recent activities of key players. Our analysis goes beyond basic descriptions to evaluate strategic moves, product launches, and positioning tactics, offering a clear map of the competitive landscape.
- Industry Dynamics and Drivers: We explore the macroeconomic, regulatory, and technological factors influencing market behavior. This includes analysis of reimbursement trends, supply chain conditions, labor dynamics, and ethical standards, providing context for interpreting market data and anticipating shifts.
- Strategic Recommendations: Synthesizing data and qualitative insights, the report offers tailored recommendations for navigating the market. Whether the goal is market entry, product development, M&A target evaluation, or operational optimization, our findings provide a structured framework for action.
We deliberately withhold the granular percentage splits and exact monetary values for specific regions, product types, and end-user categories in this public overview. These critical data points are integral to precise financial modeling and strategic planning. Access to the full report ensures that decision-makers have the complete data set needed to build robust business cases and avoid assumptions that could undermine competitive positioning.
Conclusion: Positioning for the 2026 Horizon
The Dental Market is on a robust growth trajectory, supported by favorable demographics, technological advancement, and increasing emphasis on oral health. However, the environment in 2026 presents a complex mix of opportunity and challenge. Rising costs, reimbursement gaps, labor constraints, and a competitive landscape defined by both scale players and agile innovators require a sophisticated approach to strategy.
Our market research equips organizations with the intelligence to navigate this complexity with confidence. By combining macro-level growth signals with micro-level segment analysis, competitive intelligence, and dynamic industry context, the report serves as an indispensable tool for crafting strategies that capture value and sustain advantage. We invite you to explore the full findings to unlock the detailed data and insights necessary for informed decision-making in the year ahead and throughout the forecast horizon.
For detailed analysis of this topic, please visit the official page: Dental Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fuel Cell Electric Vehicles Market to Surge at 26.6% CAGR, Hit $37M by 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Hydrogen Horizon: Navigating the 2026 Fuel Cell Electric Vehicle Landscape
Executive Summary: The Inflection Point of Hydrogen Mobility
The global transition toward sustainable transportation has entered a decisive phase. While battery electric vehicles have dominated early headlines, the Fuel Cell Electric Vehicle (FCEV) market is now demonstrating a distinct and robust growth trajectory, particularly in sectors where energy density and refueling speed are critical. As we move through 2026, industry leaders are shifting from pilot programs to scale-up strategies, driven by tightening decarbonization regulations and advancements in hydrogen infrastructure.
Electric Vehicles and Fuel Cell Vehicles Market
PW Consulting presents this comprehensive market research insight to equip stakeholders with the clarity needed to navigate this evolving landscape. Our analysis covers the period from 2020 through 2032, providing a detailed view of historical performance and future projections. The market, valued at approximately 2.21 billion USD in 2020, has seen accelerating momentum, reaching an estimated 7.08 billion USD by the base year of 2025. This trajectory underscores a compound annual growth rate (CAGR) of 26.6 percent throughout the forecast period extending to 2032. For corporate strategists, investors, and policy advisors, understanding the drivers behind this expansion is not merely an academic exercise but a requisite for capital allocation and product roadmap planning.
This article serves as a high-level overview of the strategic intelligence contained within our full report. It highlights the macroeconomic momentum, competitive dynamics, and regulatory pressures shaping the industry. However, the precise segmentation data, granular regional revenue splits, and specific application-level forecasts are reserved for the complete study. These detailed intelligence assets are critical for precise market entry strategies and are available through our comprehensive dataset.
Market Trajectory: From Niche Technology to Mainstream Adoption
The historical data from 2020 to 2025 reveals a consistent upward curve in market valuation. Starting at 2.21 billion USD, the market grew to 2.78 billion USD in 2021 and 3.46 billion USD in 2022. This growth accelerated through the pandemic recovery period, reaching 4.48 billion USD in 2023 and 5.61 billion USD in 2024. By 2025, the market revenue unit crossed the 7 billion USD threshold, signaling a maturation of the technology stack and supply chain.
Looking ahead, the forecast period from 2026 to 2032 projects aggressive expansion. The market size is anticipated to reach 9.06 billion USD in 2026, climbing to 11.69 billion USD in 2027 and 14.29 billion USD in 2028. By the end of the decade, valuations are expected to approach 23.59 billion USD in 2030, culminating at 37.0 billion USD by 2032. This momentum suggests that FCEVs are transitioning from early adoption to a growth phase driven by commercial viability. The double-digit CAGR indicates that investment flows into hydrogen technology are yielding tangible market returns, though the pace varies significantly by vehicle type and region.
Stakeholders analyzing this growth curve must consider the underlying volume drivers. The revenue growth is not uniform across all vehicle categories. Our deep-dive analysis examines how passenger cars compare against commercial heavy-duty trucks and vans in terms of revenue contribution and unit sales. While specific percentage splits are detailed in the full report, it is clear that commercial applications are generating substantial revenue due to higher unit values and intensive usage patterns. Understanding the balance between passenger and commercial segments is vital for manufacturers deciding where to allocate engineering resources and production capacity in 2026 and beyond.
Competitive Landscape: Key Players and Strategic Maneuvers
The FCEV market is characterized by a mix of automotive giants and specialized technology providers. Market concentration data indicates that the top three players hold a combined market share of 48.0 percent, while the top five control 52.0 percent of the market. This moderate concentration suggests a competitive environment where established leaders must defend their position against emerging challengers and new entrants leveraging patent portfolios or regional advantages. The following key companies are central to the current dynamics:
- Toyota Motor Corporation (Toyota City, Japan) : A pioneer in hydrogen mobility, Toyota continues to push the boundaries of passenger FCEV technology. Their flagship Mirai model integrates advanced fuel cell systems designed for performance and durability. The company's strategy focuses on maintaining technological leadership while expanding partnerships for hydrogen supply chains.
- Hyundai Motor Company (Seoul, South Korea) : Hyundai has aggressively positioned itself in both passenger and heavy-duty segments. With the Nexo passenger vehicle and the Xcient heavy-duty truck, Hyundai addresses diverse use cases. Their recent product debuts highlight a commitment to continuous innovation, leveraging over two decades of FCEV development experience.
- Honda Motor Co., Ltd. (Tokyo, Japan) : Honda complements its passenger offering with the CR-V e:FCEV, which combines fuel cell technology with plug-in battery capabilities. This hybridization strategy aims to maximize flexibility for users. Additionally, Honda supplies fuel cell systems for commercial applications, diversifying its revenue streams beyond vehicle sales.
- BMW Group (Munich, Germany) : Entering the fray with a focus on series production, BMW is targeting market entry around 2028. Their development programs emphasize integrating fuel cell technology into existing platforms while ensuring cost competitiveness. BMW's entry signals growing confidence in the long-term viability of hydrogen for premium automotive segments.
Recent developments during 2025 illustrate the active pace of product launches and strategic announcements. In July 2025, Honda began customer leasing of the CR-V e:FCEV in California, utilizing U.S.-made fuel cell modules. This move demonstrates a shift toward localized production and reduced logistical barriers. In November 2025, Hyundai debuted the all-new NEXO at the Japan Mobility Show, previewing a production model that reinforces their leadership in the passenger segment. Furthermore, the California Air Resources Board released its 2025 Annual Evaluation in December 2025, reporting 14,128 FCEVs registered in California as of April 2025. This data point provides a critical benchmark for regional adoption rates, though a slight year-over-year decline of 291 units highlights the volatility and challenges inherent in scaling infrastructure-dependent technologies.
These corporate actions and regulatory reports are interconnected. For instance, the CARB projection of a maximum of 112 stations enabling up to 16,210 FCEVs by 2028 creates a tangible ceiling for growth in key markets unless infrastructure investment accelerates. Companies are responding by aligning product launches with infrastructure milestones. Our full report analyzes how these timing mismatches between vehicle availability and fueling networks impact market penetration rates and what strategies firms are employing to mitigate risk.
Regulatory and Infrastructure Dynamics: The Dual Engines of Growth
The FCEV market does not exist in a vacuum. It is heavily influenced by policy frameworks and infrastructure readiness. The regulatory environment, particularly in regions with aggressive decarbonization targets, acts as a powerful catalyst. The Fuel Cell and Hydrogen Energy Association (FCHEA) highlighted these dynamics during the 2025 Hydrogen & Fuel Cell Seminar, emphasizing that policy alignment is driving commercialization in heavy-duty sectors. This suggests that while passenger vehicles often garner media attention, the commercial and heavy-duty segments may offer faster pathways to regulatory compliance and economic scale.
Infrastructure remains the critical bottleneck. The CARB 2025 Annual Evaluation underscores the need for hydrogen fueling station network expansion. With the projection of 112 stations supporting a specific capacity by 2028, the gap between current station counts and required coverage is evident. Strategic planners must evaluate not just the total number of stations, but their geographic distribution and reliability. Market participants are increasingly looking at public-private partnerships and government incentives to bridge this gap. Our analysis explores the correlation between station density and vehicle registration rates, revealing insights that are essential for infrastructure investors and fleet operators planning hydrogen procurement strategies.
Moreover, the industry context includes noise from various regulatory signals. Reports indicate that the first recorded decline in FCEV registrations in California, with 14,128 units as of April 2025, serves as a cautionary signal. This decline may reflect temporary factors such as supply chain constraints, vehicle model turnover, or consumer hesitation due to infrastructure anxiety. Understanding the root causes of such fluctuations is key to distinguishing between cyclical noise and structural shifts. The full market research delves into these nuances, providing context for interpreting raw registration data against broader economic and technological trends.
Strategic Implications for 2026 Decision Makers
For executives and analysts operating in 2026, the FCEV market offers both opportunity and complexity. The expansion from 9.06 billion USD in 2026 to over 37.0 billion USD by 2032 represents a significant addressable market. However, capturing value within this growth requires precise execution. Decision makers must balance investments across vehicle types, considering the differing total cost of ownership profiles for passenger versus commercial applications. They must also navigate the competitive landscape where market leaders hold substantial shares but face pressure from new technological iterations and regional players.
Fuel Cell Electric Vehicles Market
Strategic questions that this market research helps answer include: Which vehicle segments offer the highest margin potential in the current regulatory environment? How do geopolitical factors and hydrogen production costs influence regional market attractiveness? What are the timing implications of competitor product launches on market share erosion? While we have outlined the broad strokes of market size and key players here, the specific regional revenue contributions and detailed application breakdowns are provided in our complete study. These details allow for scenario planning and risk assessment that high-level summaries cannot support.
Additionally, the interaction between policy and technology adoption requires continuous monitoring. The FCHEA seminar discussions and CARB reports indicate a dynamic regulatory environment where targets are being set and adjusted based on deployment realities. Companies that can anticipate regulatory shifts and align their product pipelines accordingly will gain a first-mover advantage. Our report includes a timeline of regulatory milestones and policy announcements, helping organizations stay ahead of compliance requirements and incentive programs.
Conclusion and Access to Full Intelligence
The Fuel Cell Electric Vehicle market is at a pivot point. Historical growth from 2020 to 2025 has established a foundation, and the forecast through 2032 points to a transformative decade for hydrogen mobility. The involvement of major automakers like Toyota, Hyundai, Honda, and BMW, combined with active regulatory bodies and industry associations, creates a vibrant ecosystem of innovation and competition. Yet, the path to widespread adoption is fraught with infrastructure challenges and competitive intensity.
PW Consulting's full Fuel Cell Electric Vehicles Market research report offers a deeper layer of analysis required for sophisticated strategic planning. We provide granular segmentation data, including specific regional revenue estimates and application-level breakdowns, which are essential for market entry analysis and competitive benchmarking. Our proprietary datasets cover the sales volume trends, price dynamics, and supply chain vulnerabilities that influence profitability. We also offer comprehensive profiles of key suppliers and technology developers, along with an assessment of the risk factors that could alter the growth trajectory.
To access the complete set of market size projections, competitive intelligence, and actionable recommendations, we invite you to explore the full report. In an environment where data precision can determine investment success, our detailed insights provide the clarity needed to make informed decisions in the rapidly evolving FCEV sector.
For detailed analysis of this topic, please visit the official page: Fuel Cell Electric Vehicles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Relay Market Hits $17.85B in 2025, Projected to Reach $26.71B by 2032 at 6.2% CAGR
By pmarketresearch, 2026-09-15
Navigating the Automotive Relay Market: Strategic Intelligence for 2026 Decision-Makers
The automotive sector stands at a critical inflection point where electrification, lighter materials, and smarter architectures are reshaping every component value chain. Among the seemingly mundane yet operationally essential parts, relays remain indispensable. They bridge control logic and high-current execution, enabling everything from powertrain actuation to safety-critical load switching. For executives planning capital allocation, sourcing strategies, or product roadmaps in 2026, understanding the trajectory of the automotive relay market is not an academic exercise. It is a prerequisite for resilient, cost-aware growth. This article previews the strategic architecture of our latest Automotive Relay Market research and explains why its full intelligence is essential for confident decision-making this year.
The Macro Trajectory: A Market in Sustained Expansion
Drawing on a comprehensive historical baseline spanning 2020 through 2025 and extending across a seven-year forecast window to 2032, the automotive relay sector demonstrates consistent upward momentum. From a base measuring above thirteen thousand million USD, the market has advanced through successive annual increments, surpassing seventeen thousand million USD by 2025 and crossing the eighteen thousand million million milestone in 2026. The trajectory reflects compounding annual growth, driven by vehicle electrification, increased electrical content per platform, and the proliferation of high-current switching requirements in next-generation architectures. Rather than a single-sector surge, the expansion is broad-based: multiple on-road and off-road applications, varied regional manufacturing footprints, and diverse relay form factors are contributing to an aggregate image that rewards strategic clarity over reactive purchasing.
Time Delay Relays Market
Forecast Horizons and Strategic Planning Utility
The forecast period stretches to 2032, giving planning teams a long enough runway to evaluate CAPEX cycles, supplier qualification windows, and platform refresh timelines. The extended horizon is particularly valuable because relay selection is rarely a short-term procurement decision. It embeds into vehicle architecture, service interval planning, and regional compliance pathways. Our research translates this extended time frame into actionable planning matrices, enabling leadership to align sourcing commitments with product lifecycle cadence rather than reacting to spot-market volatility. The full report contains the granular year-by-year projections and scenario layers that allow teams to stress-test assumptions against shifting input costs, regional demand shifts, and competitive pressure.
Growth Catalysts Embedded in System Architecture
The driving force behind the expansion is not isolated to one application category. It is the cumulative effect of higher electrical loads, tighter packaging constraints, and the transition toward architectures that demand compact, high-reliability switching devices. As vehicle platforms evolve, relay specifications are becoming more demanding in terms of current handling, thermal resilience, and miniaturization. Simultaneously, cost discipline remains paramount, creating a tension between performance requirements and unit economics. Our study unpacks where these dynamics intensify, where they moderate, and how they influence total cost of ownership across the value chain. Rather than offering a single read on demand, the report segments the picture so that engineering, procurement, and strategy teams can align on the specific drivers relevant to their product families and target segments.
Segmentation Depth: Reading the Market Beyond the Aggregate
An aggregated headline number is useful for executive briefings, but it is insufficient for operational decision-making. The real value lies in understanding how the market behaves across technology types, application areas, and regional footprints. Our research provides a structured view that lets organizations isolate the demand pools most relevant to their capabilities and ambitions, while remaining mindful of competitive saturation and differentiation opportunities.
Technology Form Factors: Matching Performance to Platform Needs
Relays in modern vehicles are not a uniform product class. The market encompasses printed-circuit-board-mounted relays, plug-in variants, high-voltage solutions, and an additional set of application-specific offerings. Each family serves distinct design constraints and system requirements. PCB-mounted devices align with compact control modules and high-density electronics packaging. Plug-in relays support modular assembly and serviceability in discrete sub-systems. High-voltage categories respond to the shifting load profiles associated with electrification, where switching capability, arc management, and insulation integrity become critical selection criteria. By separating demand across these types, the report helps engineering and sourcing teams evaluate where to invest in qualification, where to consolidate spend, and where to expect price and availability pressure. The full dataset reveals the precise allocation across categories, enabling precise SKU rationalization and supplier negotiation leverage that an aggregated summary cannot provide.
Application Mapping: Where the Demand Actually Resides
From a demand perspective, relays feed into multiple vehicle domains: powertrain systems, body and chassis functions, safety and security subsystems, HVAC and comfort components, and EV battery management functions. Each application carries different performance expectations, volume profiles, and qualification rigor. Powertrain-related switching tends to emphasize durability, current capacity, and thermal resilience. Body and chassis applications often prioritize cost efficiency and integration flexibility. Safety and security functions introduce stricter reliability thresholds and traceability expectations. Comfort and climate systems blend volume scale with moderate performance requirements. EV battery management represents a specialized, fast-evolving domain where switching reliability and voltage handling are paramount. Our segmentation view maps these demand streams so leadership can avoid over-indexing on one vertical while underestimating growth in another. The complete report contains the detailed split that supports portfolio prioritization and resource allocation decisions.
Regional Distribution: Planning Around Localized Demand and Supply
Geography shapes both demand and competitive dynamics. Different regions present distinct vehicle production volumes, regulatory environments, cost structures, and supplier maturity. North American, European, and Asia Pacific markets each contribute meaningfully to total demand, while Latin America and the Middle East and Africa represent additional, often specialized, demand pockets. A regional lens is essential for capacity planning, logistics design, and competitive positioning, particularly when raw material pricing, local content expectations, and certification pathways vary by market. Our research outlines the regional demand structure so organizations can decide where to locate inventory, which suppliers to qualify, and how to hedge against regional supply disruptions. The full report's regional breakdown enables precision in regional strategy without disclosing the exact allocation figures that competitors could exploit if presented in isolation.
Competitive Landscape and Strategic Positioning
The automotive relay market is not dominated by a single winner-takes-all player. Competitive concentration is moderate, which means differentiation, supply chain reliability, and technological readiness still create room for advantage. Our research profiles a broad set of global and regional participants, helping teams understand who competes on performance, who competes on cost, and who competes on integration depth with vehicle manufacturers and Tier 1 suppliers.
Automotive Relay Market
The competitive field includes established multinational firms and capable regional manufacturers. Profiles cover companies such as TE Connectivity, Omron Corporation, Panasonic Corporation, Siemens AG, Phoenix Contact, Schneider Electric, Finder, Cit Relay & Switch, HKE, Xiamen Hongfa Electroacoustic Co., Ltd., Forward Relay, Huaguan, Shenler, Denso Corporation, Robert Bosch GmbH, Eaton Corporation, and Fujitsu Component Limited. These organizations participate across different segments and regions, and their strategic postures diverge based on product breadth, voltage-class readiness, packaging expertise, and proximity to vehicle programs. Rather than treating the landscape as a static list, the report maps how these players are positioned relative to one another in terms of addressable demand, technology emphasis, and regional strength. This framing helps procurement teams benchmark supplier options and helps product teams identify white space for differentiated offerings. The full report delivers the deeper competitive assessment, including positioning nuances that inform partnership selection, negotiation strategy, and risk diversification.
Market Dynamics: Cost Pressure, Innovation, and Regulatory Signals
Market growth does not occur in a vacuum. Cost structures, product launches, and regulatory or compliance considerations all shape the pace and shape of demand. Our research incorporates the dynamic factors that should influence 2026 planning, particularly for teams evaluating supplier stability, margin resilience, and technology roadmaps.
Raw Material and Component Cost Signals
Input cost volatility remains a strategic concern. Recent supplier notices point to material and component price adjustments that can affect relay and associated electromechanical product economics. For example, one major electrical equipment manufacturer announced bulk commodity price-driven increases of up to 40 percent on certain contactor and relay series and related accessories, effective in March 2026. Separately, a major industrial manufacturer announced price increases in the range of 30 percent for glass epoxy multi-layer circuit board materials and 20 percent for prepreg used in relay and electronic component production, effective in April 2026. These developments underscore the importance of forward-looking cost modeling, dual-sourcing strategies, and design-for-cost initiatives. Our study places these signals in context so organizations can anticipate where cost pass-through pressure may emerge and where value engineering can protect margins.
Product Launches That Reshape Performance Expectations
Innovation in the relay category is moving toward higher voltage handling, bidirectional switching, compactness, and improved sustainability profiles. In April 2025, Omron Corporation introduced the G9EK High-Voltage DC Relay, a compact 500 VDC 120 A bidirectional gasless relay designed for next-generation EV charging, battery systems, and power electronics, with carbon neutrality attributes enabled by a gasless plunger-type design that supports 500 VDC 120 A bidirectional switching without gas filling. Around the same period, Durakool introduced the DG86M high-current automotive relay featuring magnetic arc blowout technology for industrial vehicle electrification, delivering 150 A at 72 VDC and 25 A at 250 VDC in a compact lightweight design, with engineering targeted at 15,000 operations with integrated resistor and 5,000 operations with integrated diode. These launches demonstrate that the category is evolving from basic switching toward application-tuned, high-performance solutions. The report translates such developments into implications for design requirements, supplier evaluation, and portfolio planning, while withholding the full competitive benchmarking detail until readers access the complete study.
Regulatory and Sustainability Considerations
Beyond immediate product specifications, sustainability expectations and compliance considerations are increasingly influencing component selection. Gasless design approaches, material efficiency, and lifecycle considerations are becoming part of technical evaluations, especially for programs with stringent environmental targets. At the same time, regulatory expectations around vehicle safety, electrical protection, and component qualification continue to shape acceptance criteria. Our research integrates these considerations into the market dynamics section, helping teams understand where sustainability attributes influence purchase decisions and how compliance burdens differ across applications and regions. The complete report expands on these dynamics with structured analysis that can be aligned to internal sustainability goals and program requirements.
What the Full Report Delivers for 2026 Decision-Making
This preview has outlined the strategic shape of the market: sustained growth, diversified demand across types and applications, a moderately concentrated competitive field, and a backdrop of cost pressure and product innovation. Yet the difference between broad awareness and competitive advantage lies in the specifics. The complete Automotive Relay Market research is built to give decision-makers the precision required to act with confidence.
Inside the full report, readers will find detailed market sizing across the historical and forecast periods, enabling year-by-year resource planning and scenario comparison. The segmentation analysis breaks down demand by technology type, application, and region with sufficient granularity to support SKU strategy, supplier selection, and regional capacity planning. Competitive profiles provide structured insight into the positioning, scope, and strategic emphasis of key players, allowing teams to benchmark their own offering and identify partnership or procurement targets. Market dynamics coverage brings together cost signals, innovation milestones, and regulatory context into a coherent view that supports both short-term sourcing decisions and long-term portfolio planning.
Equally important, the report is organized for practical use rather than passive reading. It is structured to support multiple internal audiences: strategy teams evaluating market entry or expansion, procurement teams managing supplier risk and cost, engineering groups selecting relay specifications for new platforms, and finance teams modeling cost trajectories and margin exposure. By consolidating the analytical layers into one integrated view, the report reduces the time required to align cross-functional stakeholders around a shared market thesis.
For 2026, when planning cycles are increasingly sensitive to input cost variability, electrification-driven specification shifts, and regional supply chain considerations, strategic clarity is a direct enabler of execution quality. Our research is designed to provide that clarity while preserving the competitive sensitivity of the underlying detail. To explore the full segmentation, competitive positioning, and dynamic analysis that underpin this outlook, we invite you to access the complete market study. The detailed intelligence inside will help your organization move from general market awareness to informed, actionable strategy.
Why This Research Matters Now
The automotive relay market is expanding, evolving, and being contested by a diverse group of global and regional players. That combination creates both opportunity and risk. Organizations that understand where demand is concentrated, how technology types differ in value and cost behavior, and which competitive forces are intensifying will be better positioned to protect margins, secure supply, and align product development with real market pull. Those that rely on surface-level summaries risk overcommitting to the wrong segments, underestimating cost pressure, or missing the product innovations that are redefining performance expectations.
Our latest Automotive Relay Market research exists to close that gap. It translates a complex, multi-dimensional market into a structured intelligence asset that supports concrete 2026 decisions. The preview above establishes the professional depth of the analysis and the practical orientation of the content; the complete report delivers the data, segmentation, and competitive assessment needed to turn insight into action. We encourage leadership teams, sourcing professionals, and engineering strategists to review the full study and integrate its findings into their planning cycles this year.
For detailed analysis of this topic, please visit the official page: Automotive Relay Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Optical Fiber Fusion Splicer Market to Hit $344.8M by 2032, Growing at 6.0% CAGR
By pmarketresearch, 2026-09-15
Navigating the Fiber Frontier: Strategic Intelligence for the 2026 Optical Fiber Fusion Splicer Market
The global optical fiber fusion splicer market stands at a pivotal inflection point. As network operators accelerate broadband rollouts, hyperscale data centers push beyond conventional density limits, and public infrastructure programs demand resilient connectivity backbones, equipment procurement decisions carry multi-year operational and financial implications. Our latest market research delivers a decision-ready intelligence package designed specifically for executives navigating 2026 capital allocation, product roadmap planning, and competitive positioning.
This briefing outlines why this analysis matters now, what strategic layers it unravels, and how procurement, R&D, and channel leaders can translate its findings into measurable advantage. Rather than cataloguing incremental shipment figures, the study maps structural forces, capability gaps, and procurement inflection points that will define winner-take dynamics through 2032.
The Trajectory: Why 2026 Is a Strategic Anchor Year
Historical demand patterns reveal a market that has consistently expanded rather than fluctuated with short-cycle technology hype. From 2020 through 2025, global revenue progressed steadily, reflecting sustained deployment cycles in telecommunications, institutional networks, and enterprise infrastructure. The base year of 2025 establishes a clear baseline, and the forward projection through 2032 indicates a compound annual growth rate of approximately 6.0 percent, with market size scaling into the mid-300 million USD range by the end of the forecast window.
This trajectory is not merely a function of incremental device replacements. It reflects compounding pressures: fiber-to-the-x expansions in underserved regions, densification of metro and long-haul routes, and the proliferation of high-capacity fiber arrangements within data center campuses. Organizations that treat the splicer market as a static procurement category risk misaligning budget cycles, inventory strategies, and service-level commitments. By anchoring decisions in a 2026-2032 lens, leaders can evaluate total cost of ownership, technology migration timelines, and supplier reliability under realistic deployment velocity rather than point-in-time pricing snapshots.
Optical Fiber Fusion Splicer Market
The research deliberately frames this growth as a structural shift in how connectivity is engineered, maintained, and scaled. Understanding which demand vectors are accelerating, which are plateauing, and where margin compression is likely allows strategy teams to prioritize investments that compound over the forecast horizon rather than chase short-term volume spikes.
What the Report Delivers: A Decision-Ready Intelligence Architecture
This study is built for operational use, not passive reading. It translates market signal into executable insight across four interconnected layers:
- Demand decomposition across technology categories, application environments, and geographic demand clusters, with emphasis on where capacity utilization, deployment complexity, and service intensity differentiate buyer behavior.
- Product architecture and performance signal analysis, covering core alignment versus ribbon and mass fusion workflows, automation maturity, field-ruggedization requirements, and how feature sets map to installation throughput and OPEX reduction.
- Procurement and policy context, including regulatory classification developments, standardization milestones, and public-sector sourcing activity that influence import costs, compliance risk, and government-adjacent demand pipelines.
- Competitive positioning and capability mapping, tracing how leading manufacturers differentiate through device performance, software connectivity, service ecosystems, and channel control.
Each layer is designed to reduce uncertainty in capital planning and product strategy. Procurement teams can benchmark supplier claims against functional reality, engineering leaders can prioritize feature roadmaps that align with high-growth deployment profiles, and partnership teams can identify where channel strength or after-sales support becomes a decisive differentiator in an increasingly fragmented supply base. The analysis intentionally avoids superficial segmentation summaries and instead focuses on the strategic weightings that determine which demand pockets will command pricing resilience, inventory discipline, and long-term supplier loyalty.
Competitive Landscape: Capability, Momentum, and Positioning Signals
The fusion splicer market is characterized by a relatively concentrated top tier alongside a broad field of regional and application-focused players. The five-firm concentration metric underscores that scale, brand recognition, and ecosystem maturity still command meaningful share, yet the remaining competition remains highly active in niche performance categories, ruggedized field tools, and ribbon or high-density fiber workflows.
Fujikura Ltd. continues to anchor its portfolio around core alignment optical fiber fusion splicers, including models built for telecom and enterprise environments, with increasing emphasis on cloud connectivity and low-loss splicing outcomes. Sumitomo Electric Industries, Ltd. reinforces its field and long-haul credibility through high-speed core alignment platforms that integrate GPS support, automatic cleave checking, and maintenance tooling designed to reduce installation variability. INNO Instrument Inc. has strengthened its positioning around rugged ribbon fiber support platforms, leveraging dual-camera architectures to serve data center and high-density deployment contexts where alignment precision and operational durability matter under demanding site conditions.
OFS Fitel, LLC maintains relevance through single-mode fiber splicing solutions embedded in telecom and enterprise networks, while Furukawa Electric Co., Ltd. extends its footprint across telecom carrier workflows and emergency repair scenarios, pairing core alignment capabilities with advanced ribbon and mass splicing functions. AFL Telecommunications LLC operates a complementary strategy by distributing Fujikura-branded platforms, including mass fusion models with intelligent alignment controls and automatic placement correction, enabling high-volume installation programs to benefit from established device performance with localized service reach.
Recent market momentum illustrates how product launches and institutional procurement activity can alter short-term demand visibility. In May 2026, AFL Telecommunications LLC introduced a Fujikura 100R mass fusion platform featuring automatic placement correction, a development that reduces operator intervention and aligns with high-throughput installation environments. Around the same period, the National Institute of Standards and Technology issued a Sources Sought solicitation to identify potential suppliers and vendors for fiber fusion splicer capabilities, signaling that government-adjacent acquisition planning is actively validating supply options for this equipment class.
Beyond product launches, regulatory and standardization developments are reshaping the market's operational backdrop. A U.S. Customs and Border Protection ruling classified a portable optical fiber fusion splicer under a telecommunications equipment tariff classification, a detail that procurement and import-planning teams must factor into landed-cost modeling and sourcing strategy. Separately, Sumitomo Electric Industries, Ltd. received recognition from Japan's Ministry of Economy, Trade and Industry for contributions to IEC and ISO international standards in optical fiber fusion splicing technology, reinforcing how standards leadership can function as a competitive moat in credibility, interoperability, and export-facing trust. These are not isolated news items; they are signals that connectivity equipment buyers must interpret when evaluating risk, compliance, and long-term supplier durability.
Strategic Implications: Where Decision-Makers Should Focus in 2026
The research translates the market's evolution into actionable priorities for three core functions:
- Procurement and supply chain leaders should stress-test supplier commitments against deployment complexity rather than unit price alone. As installation teams encounter higher fiber densities, tighter site constraints, and greater throughput expectations, device reliability, consumables availability, field-service responsiveness, and diagnostic software maturity become decisive cost drivers.
- Product and R&D teams should evaluate where automation, reduced operator intervention, and cloud-connected diagnostics can create defensible differentiation. In markets where installation labor and rework costs dominate total project expense, splicer platforms that minimize human variability can shift the value conversation from hardware price to operational efficiency.
- Commercial and partnership teams should map channel strength, regional service coverage, and standards-aligned credibility into their go-to-market strategy. In categories where purchase decisions are influenced by long-term support expectations and installer familiarity, ecosystem positioning often outweighs incremental feature announcements.
A critical insight is that the market's growth is not evenly distributed across buyer types or deployment contexts. Telecommunications-dominant demand, data center densification, and varied institutional or specialist applications each impose different performance thresholds, purchasing cycles, and service dependencies. Organizations that generalize their strategy across all segments risk diluting resources where competitive pressure is highest and overlooking pockets where technical specificity or service reliability commands premium positioning. The study isolates where differentiation is durable and where price competition is most likely to compress returns.
Why This Research Matters Now
2026 is not simply another forecast year; it is a calibration point where market momentum, product maturity, and procurement policy intersect. Buyers and suppliers alike are being asked to commit to equipment choices, service agreements, and capacity plans under conditions where installation scale, automation expectations, and public-sector sourcing activity are simultaneously evolving. A decision framework built on retrospective headlines or static segmentation will miss the strategic inflection points that determine margin endurance and market share stability.
Our full report extends well beyond this overview. It provides detailed assessments of demand composition, competitive capability mapping, regulatory and procurement watchpoints, and forward-looking deployment signals that help executives separate structural opportunity from transient noise. The objective is not to overwhelm with volume tables, but to equip teams with a clear lens on where to allocate attention, which supplier traits merit weight in sourcing decisions, and how to anticipate the next wave of installation-driven demand.
For leaders responsible for connectivity infrastructure, network expansion, or equipment portfolio strategy, the message is straightforward: the fusion splicer market is advancing along a definable growth path, but the strategic value lies in understanding which drivers will persist, which capabilities will command premium relevance, and where competitive intensity will reshape buyer expectations. This research is designed to convert that understanding into confident 2026 decisions and a stronger footing for the years that follow.
Worldwide Video Splicer Market
For detailed analysis of this topic, please visit the official page: Optical Fiber Fusion Splicer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Semiconductor Etch Equipment Market Reaches $25.13 Billion in 2025, Projects 7.61% CAGR
By pmarketresearch, 2026-09-15
Strategic Imperatives in the Semiconductor Etch Equipment Market: A 2026 Outlook
The semiconductor manufacturing landscape is entering a decisive phase where equipment capability defines technological leadership. As node sizes shrink and 3D architectures become the standard, the etch process stands as a critical bottleneck and enabler. For executives and investors navigating the 2026 fiscal year, understanding the trajectory of the Semiconductor Etch Equipment Market is not merely an operational concern but a strategic imperative. PW Consulting presents a comprehensive analysis designed to illuminate the path forward, offering clarity amidst volatile demand cycles and tightening regulatory frameworks.
The market has demonstrated remarkable resilience and growth over the past half-decade, evolving from a recovery phase into a sustained expansion period. According to our latest research, the overall market size is projected to reach new heights as we move through the decade. Starting from a base of approximately 25.13 billion USD in 2025, the trajectory indicates a steady climb toward nearly 42 billion USD by 2032. This growth is underpinned by a compound annual growth rate that reflects robust demand across high-performance computing and memory sectors. Such figures represent more than just revenue; they signal a fundamental shift in capital expenditure priorities as manufacturers race to secure supply chain sovereignty and technological edge.
Our report serves as a navigational tool for these complex waters. It dissects the market mechanics without fluff, providing actionable intelligence for strategic planning. Below, we offer a preview of the analytical depth contained within the full study, highlighting why this intelligence is essential for organizational decision-making in 2026.
Market Dynamics and Growth Trajectories
The current valuation of the sector reflects a compound effect of technological adoption and geographic shifts in manufacturing capacity. The progression from 2020 to 2025 shows a clear upward trend, with revenue expanding from 16.0 billion USD to over 25 billion USD. This historical context validates the investment thesis for etch technology but also raises questions about sustainability and concentration risks. The forecast period extending to 2032 suggests that this momentum is not accidental. It is driven by the intensifying requirements for atomic-scale precision in conductor and dielectric processes.
While the aggregate numbers are impressive, the true value for decision-makers lies in understanding the drivers behind the growth. The full report details the segmentation across equipment types, distinguishing between the dominance of dry etch solutions versus wet etch applications. It explores the process-specific demands, analyzing how conductor etch and dielectric etch segments are diverging in terms of growth velocity and technological complexity. Furthermore, the application landscape is scrutinized, revealing how logic chips and memory chips are contributing differently to the revenue pool. Each segment presents unique risk profiles and opportunity sets that require tailored strategic approaches.
Access to the granular data behind these segments is crucial. Organizations need to know not just that the market is growing, but where the growth is concentrated and which technologies are capturing the premium value. The complete analysis provides the necessary breakdown to inform capacity planning, R&D allocation, and partnership strategies without relying on generalized industry assumptions.
Competitive Landscape and Strategic Positioning
The market structure is characterized by a high degree of concentration, where a select few players command the majority of revenue share. Our analysis indicates that the top three companies hold a significant portion of the market, while the top five consolidate even greater dominance. This oligopolistic structure creates a high barrier to entry for newcomers and forces established players to constantly innovate to maintain margins. For stakeholders, this concentration implies that competitor moves must be monitored with extreme precision.
Several key enterprises define the current competitive arena. Applied Materials and Lam Research Corporation remain pivotal forces, each leveraging distinct technological advantages. Tokyo Electron Limited continues to expand its manufacturing footprint to meet demand, while Hitachi High-Tech Corporation and Oxford Instruments plc offer specialized solutions for niche but critical applications. ASML Holding N.V., though often associated with lithography, plays an intertwined role in the broader equipment ecosystem. Other significant contributors include ULVAC, Inc., NAURA Technology Group Co., Ltd., SPTS Technologies Ltd, Plasma-Therm LLC, and SAMCO Inc., each carving out positions based on specific regional strengths or technological niches.
Semiconductor Etch Equipment Market
Recent developments among these key players offer a window into future strategies. Lam Research Corporation, for instance, has been aggressive in both product innovation and ecosystem building. In early 2025, they launched the Akara conductor etch tool, emphasizing atomic-scale precision via DirectDrive plasma control technology. This was followed by a donation of leading-edge multi-chamber etch systems to UC Berkeley for advanced R&D, signaling a commitment to securing the talent pipeline and validating technology in academic settings. Later in the year, collaborations focused on dry resist technology further underscore the industry's shift toward atomic layer etching and deposition.
Tokyo Electron Limited responded to capacity pressures with a facility expansion announcement in Miyagi, aimed at boosting plasma etch systems manufacturing. Meanwhile, Oxford Instruments plc made strides into adjacent emerging sectors, supplying atomic layer etch systems for quantum device fabrication. These moves are not isolated; they are strategic bets on where the next wave of demand will originate beyond traditional logic and memory nodes. Our report analyzes these movements to help clients anticipate competitor capacity expansions and technology pivots.
Regulatory Environment and Geopolitical Risks
No analysis of the semiconductor equipment market in 2026 is complete without a rigorous assessment of the regulatory landscape. The industry is operating under a cloud of evolving export controls and bipartisan legislative actions that directly impact equipment deployment and supply chain logistics. The dynamic nature of these regulations means that compliance is not a one-time checklist but a continuous strategic variable.
Recent actions by the U.S. Department of Commerce Bureau of Industry and Security have tightened constraints significantly. In December 2024, new rules were implemented affecting advanced packaging semiconductor manufacturing equipment, including specific etch tools. This was accompanied by expansions to the foreign direct product rule, extending jurisdiction over foreign-produced equipment destined for certain regions. Additionally, numerous entities were added to the Entity List, and specific types of equipment were added to the Commerce Control List. These measures fundamentally alter the accessible market for major players and require careful navigation for any international supply chain.
Furthermore, legislative moves such as the Bipartisan MATCH Act introduced in April 2026 propose prohibitions on the sale of cryogenic etch tools and deep ultraviolet immersion lithography systems to countries of concern. These regulations create a bifurcated market scenario where technology access is determined by geopolitical alignment rather than purely economic factors. Our report integrates these regulatory variables into the market forecast, helping clients understand the potential impact on revenue streams and market entry strategies in restricted regions. Understanding the nuance of these controls is vital for avoiding compliance pitfalls while optimizing global footprint allocation.
The Strategic Value of Comprehensive Intelligence
In a market defined by high concentration, rapid technological shifts, and stringent regulations, surface-level data is insufficient for robust decision-making. The full PW Consulting report on the Semiconductor Etch Equipment Market goes beyond high-level summaries to provide the depth required for executive strategy. It connects the dots between revenue trends, competitive maneuvers, and regulatory constraints to paint a holistic picture of the operating environment.
The report details the segmentation splits that drive revenue, offering clarity on where capital is flowing. It examines the regional distribution of market value, highlighting the disparities between mature markets and high-growth regions without oversimplifying the complexities of local demand drivers. It provides a thorough examination of the production and consumption dynamics that define the supply-demand equilibrium.
Access to this level of detail allows organizations to:
- Validate internal projections against independent market data.
- Identify potential gaps in product portfolios relative to market demand.
- Assess the risk exposure associated with regulatory changes in key regions.
- Benchmark competitor activities to refine go-to-market strategies.
- Pinpoint emerging opportunities in specialized etch applications beyond standard CMOS manufacturing.
The semiconductor industry rewards those who can anticipate change before it becomes obvious. By leveraging our detailed segmentation data—covering types, processes, applications, and regions—clients can move from reactive planning to proactive strategy. The report includes profiles and strategies for the key companies mentioned, analyzing how their recent developments align with broader market trends. This competitor intelligence is crucial for understanding who is gaining share, who is investing in which technologies, and where the next competitive threats may emerge.
Plasma Etch System Market
Moreover, the analysis considers the macroeconomic context, including the currency valuation and revenue units that frame the financial expectations. The forecast period through 2032 provides a long-term horizon for ROI calculations, allowing stakeholders to justify capital expenditures in equipment development or acquisition. The distinction between dry and wet etch equipment, for example, is not just a technical classification but a financial indicator of where the industry is placing its bets for the next decade. Similarly, the split between conductor and dielectric processes reveals the relative intensity of backend versus frontend manufacturing investments.
Conclusion: Navigating the Next Phase
The Semiconductor Etch Equipment Market is at a crossroads where technological capability and geopolitical reality intersect. The growth trajectory is clear, but the path to capturing value is fraught with complexity. Companies must balance the drive for innovation with the constraints of international regulation. They must watch the few dominant players while keeping an eye on specialists who may disrupt specific segments. They must allocate resources across logic and memory applications without knowing exactly which node will define the next cycle.
PW Consulting's full market research report is designed to equip leadership teams with the intelligence needed to make these judgments with confidence. We invite you to access the complete study to unlock the specific data points, regional breakdowns, and strategic recommendations that will inform your 2026 planning. Do not rely on assumptions when the stakes involve billions in capital and the future of technological sovereignty.
For detailed segmentation data, comprehensive competitor profiles, and in-depth regulatory impact analysis, please visit our dedicated market research portal. The complete intelligence package offers the granularity required to turn market insights into competitive advantage.
For detailed analysis of this topic, please visit the official page: Semiconductor Etch Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Electric Scooters Market Hits $38.23B in 2025, Forecasts 9.81% CAGR to 2032
By pmarketresearch, 2026-09-15
Strategic Horizons for the Electric Scooter Market: Navigating Growth Through 2032
The urban mobility landscape is undergoing a seismic shift, driven by the dual imperatives of decarbonization and last-mile efficiency. Electric scooters, once viewed as niche recreational devices, have matured into integral components of the global transportation ecosystem. For stakeholders operating within this dynamic sector, understanding the trajectory of market expansion is not merely an exercise in forecasting it is a prerequisite for strategic positioning. Our latest comprehensive market research on the Electric Scooter Market offers a granular examination of the forces shaping industry outcomes from 2026 through 2032, providing executives, investors, and policymakers with the intelligence needed to navigate an increasingly complex competitive environment.
Electric Scooters Market
This analysis is built upon a rigorous evaluation of historical performance spanning 2020 to 2025, extending forward through a seven-year forecast period. The data reveals a market characterized by robust structural momentum, with a compound annual growth rate of 9.81 percent projected across the evaluation window. This sustained upward trajectory reflects deepening consumer adoption, expanding commercial deployment, and the convergence of supportive regulatory frameworks with technological maturation. Yet beneath these headline figures lies a far more intricate reality, one defined by regional asymmetries, product segmentation shifts, and intensifying competitive pressures that demand nuanced strategic responses.
Market Trajectory and Core Dynamics
The electric scooter sector has demonstrated remarkable resilience and expansion potential over the past half-decade. Revenue valuations have progressed from a baseline of 24.32 billion USD in 2020, climbing through successive growth phases to reach 38.23 billion USD by 2025. This historical arc establishes a credible foundation for near-term projections, with valuations anticipated to breach 41.58 billion USD in 2026 and continue their ascent toward 73.5 billion USD by 2032. Such growth is neither accidental nor uniform. It emerges from the interplay of urbanization pressures, infrastructural investments, evolving consumer preferences, and the strategic maneuvering of manufacturers seeking to capture share within an increasingly crowded arena.
Several macro force are propelling this expansion. Urban congestion in megacities has accelerated demand for compact, zero-emission alternatives to traditional motorized transport. Municipalities worldwide are integrating micromobility into broader transit networks, recognizing the role that electric scooters play in bridging gaps between mass transit hubs and final destinations. Simultaneously, advancements in battery chemistry, motor efficiency, and connected vehicle technologies have elevated product reliability and user experience, addressing earlier adoption barriers related to range anxiety and maintenance complexity.
However, growth is not without friction. Regulatory interventions have introduced new layers of complexity for market participants. Trade policy adjustments, including the imposition of significant tariffs on electric scooters imported from China, have reshaped supply chain considerations and prompted manufacturers to reevaluate sourcing strategies and regional production footprints. Concurrently, evolving standards governing lithium-ion battery transport, storage, and recycling impose compliance obligations that influence product design, logistics, and total cost structures. These dynamics underscore the necessity of proactive regulatory intelligence as a core competency for organizations operating in this space.
Segmentation Architectures and Demand Drivers
A superficial glance at aggregate market figures obscures the divergent growth patterns unfolding across product categories, end-use verticals, and geographic corridors. Understanding these sub-market dynamics is essential for allocating capital efficiently, tailoring product roadmaps, and identifying white-space opportunities that remain underserved by current competitive offerings.
Product architecture continues to bifurcate between foldable and non-foldable designs, each addressing distinct user requirements and deployment contexts. Foldable configurations prioritize portability and multi-modal integration, appealing to commuters who combine scooter usage with public transit. Non-foldable variants, by contrast, emphasize structural robustness, payload capacity, and extended range, catering to applications where stability and durability outweigh portability concerns. The relative performance of these segments reflects broader shifts in consumer lifestyle patterns and commercial fleet requirements, with implications for manufacturing specialization and inventory strategy.
Application-wise, the market divides between personal use and commercial deployment, each following distinct adoption curves and value propositions. Personal use remains anchored in consumer preference for convenient, low-cost, environmentally conscious mobility solutions. Commercial applications, spanning last-mile delivery fleets, shared micromobility programs operated by municipal authorities or private operators, and corporate campus transportation, introduce additional dimensions of scale, utilization efficiency, and total cost of ownership. The interplay between these application verticals shapes demand volatility, pricing architecture, and the extent to which manufacturers can pursue differentiated value chains.
Geographically, market performance varies substantially, reflecting differences in urban density, regulatory environments, infrastructure maturity, and cultural acceptance of micromobility. Certain regions exhibit accelerated penetration rates driven by aggressive public-sector support and dense urban form, while others progress more incrementally as infrastructure catch-up and consumer education remain ongoing processes. These spatial divergences create heterogeneous opportunity landscapes, requiring market entrants and incumbents alike to calibrate their regional strategies with precision rather than relying on one-size-fits-all expansion models.
Competitive Landscape: Navigating an Increasingly Crowded Field
The electric scooter market is defined by a concentration of established players alongside a steady influx of new entrants, each leveraging distinct technological capabilities, brand positioning, and operational models to capture share. Our research maps this competitive terrain in detail, examining the strategic postures of leading manufacturers and shared mobility operators whose actions collectively shape market direction.
Among the prominent hardware manufacturers, several Chinese-based companies have built formidable portfolios emphasizing range, connectivity, and performance versatility. Segway-Ninebot continues to expand its E-series and Max series offerings, with recent product introductions at CES 2026 highlighting updated battery technologies and cross-platform integration between e-bikes and e-scooters. NIU International has reinforced its position through the KQi series and lightweight variants that blend integrated connectivity with extended range options tailored for urban environments. Yadea Technology Group broadens its footprint by spanning electric two-wheeler scooters and motorcycles, leveraging advanced battery and motor systems that serve both personal and commercial end markets. Kaabo has carved a niche in the heavy-duty off-road segment, deploying high-capacity batteries and high-output motors that appeal to enthusiasts and specialized commercial users alike.
The Indian market has emerged as a particularly dynamic theater of innovation and scale. TVS Motor Company has continued to refine its Orbiter and Star Series e-scooters, with the 2026 release of the TVS X model introducing ABS options and updated powertrain configurations aimed at mainstream commuting segments. Ather Energy has pursued a differentiated strategy centered on AI-optimized performance, swappable battery architectures, and telematics integration, positioning its Rizta and 450X models as technology-forward solutions for urban and last-mile transport. Ola Electric has scaled rapidly with its S1 Pro and S1 X scooters, emphasizing high-efficiency motors and fast-charging infrastructure designed to support both personal ownership and fleet applications. These Indian players benefit from a confluence of domestic demand, manufacturing scale, and aggressive product iteration that collectively intensifies competitive pressure across the broader market.
In North America, a diverse set of manufacturers and operators addresses varying consumer and institutional requirements. Apollo Scooters and Gotrax serve commuter segments with solid-tire designs, extended battery life, and foldable configurations that balance affordability with reliability. Navee and VMAX have targeted higher-performance use cases, emphasizing 48V systems, hub-motor configurations, and range specifications that support daily transport and off-road capabilities. InMotion focuses on rugged terrain and payload capacity through high-peak-power models. LexGo has introduced dual-motor options that extend range and performance envelopes for urban and highway commuting contexts. These regional players operate within a regulatory environment shaped by evolving customs policies and battery transport standards, making supply chain agility and compliance readiness critical differentiators.
The shared mobility segment introduces an additional competitive dimension, with operators such as Lime, Bird, Spin, Veo, and Gogoro deploying dockless or fleet-based models tailored to citywide micromobility programs and municipal partnerships. These companies emphasize utilization efficiency, battery-swapping ecosystems, and customized fleet solutions that align with urban transportation authority requirements. Their competitive calculus differs from hardware manufacturers, prioritizing operational economics, regulatory relationships, and user acquisition over unit sales volume.
Market concentration data indicates that a relatively small number of firms command a substantial share of aggregate revenue, with CR3 and CR5 metrics reflecting meaningful consolidation at the top of the competitive pyramid. This concentration does not eliminate opportunities for specialized entrants, particularly those that can differentiate through technology, regional focus, or niche application expertise, but it does raise the stakes for market participants seeking to achieve scale and defend margins.
Regulatory and Supply-Side Currents
Strategic decision-making in the electric scooter market must account for a broad array of externalities that influence costs, product design, market access, and competitive dynamics. Regulatory frameworks are evolving rapidly across jurisdictions, and the implications extend far beyond compliance checklists.
Trade policy has emerged as a particularly salient factor. Recent tariff measures imposed on electric scooters imported from China, coupled with duties on lithium-ion battery components, have compelled manufacturers and distributors to reassess sourcing strategies, pricing architecture, and regional assembly considerations. Organizations that have developed flexible supply chain models, localized production capabilities, or diversified sourcing portfolios are better positioned to absorb policy-driven cost pressures while maintaining competitive pricing.
Battery-related regulations introduce additional complexity. Updated guidance on lithium battery marking, watt-hour rating requirements, and quantity limits for batteries packed with equipment impose new documentation and packaging obligations that influence logistics, warehousing, and cross-border movement. In parallel, recycling mandates in certain jurisdictions require elevated material recovery rates for battery components used in shared fleets, affecting total lifecycle costs and incentivizing investments in closed-loop material management.
Raw material dynamics further complicate the supply-side picture. Surging export volumes and values for lithium batteries reflect robust global demand for energy storage and electrified mobility, but they also introduce volatility considerations related to commodity pricing, capacity allocation, and geopolitical factors. Manufacturers that have secured long-term supply agreements, invested in battery technology differentiation, or developed partnerships with experienced component suppliers gain relative advantage in navigating these fluctuations.
Trip data collection and urban mobility monitoring efforts by transportation authorities provide increasingly granular visibility into usage patterns, trip lengths, and modal substitution effects. Access to such data, whether through public reporting or proprietary partnerships, enables operators and manufacturers to refine product specifications, optimize fleet deployment, and tailor marketing strategies to evidence-based usage insights rather than assumption-driven planning.
What the Research Delivers: Actionable Intelligence for 2026 Decision-Making
This market research report is designed to translate complex market signals into structured, actionable intelligence. Beyond high-level sizing and growth projections, the analysis provides a detailed operational framework that supports strategic planning across multiple functional domains.
The report examines historical performance and forward-looking forecasts across the full evaluation period, grounding projections in transparent methodology while identifying inflection points, risk factors, and catalyst events that could alter trajectory. Segmentation analysis disaggregates demand by product architecture and application vertical, revealing where growth is accelerating, where saturation may emerge, and where unmet needs create openings for informed market entry. Geographic analysis maps regional performance differentials without reducing them to simplistic rankings, instead exploring the structural drivers that underpin divergent outcomes and the strategic implications for market access, partnership selection, and capacity deployment.
Hoverboard Scooters Market
Competitive profiling extends beyond descriptive summaries to assess strategic positioning, product portfolio coherence, recent launch activity, and the manner in which leading firms are responding to regulatory and supply-side pressures. Recent developments, including product introductions at major trade exhibitions, model refreshes targeting specific performance or range thresholds, and the expansion of model lineups by emerging brands, are contextualized within broader competitive dynamics to illustrate how incumbents and challengers are contesting market share.
Regulatory and supply-chain analysis is integrated throughout rather than treated as a standalone appendix, ensuring that decision-makers understand how policy developments, battery standards, recycling mandates, and trade measures interact with pricing, product design, and market entry timing. This integrated approach enables organizations to evaluate not only what the market is likely to do, but also where constraints and enablers will shape the feasible set of strategic choices.
For corporate strategists, the research supports scenarios around capacity investment, product portfolio optimization, and geographic prioritization. For investors, it provides a framework for assessing market attractiveness, competitive durability, and the risk-adjusted return profiles associated with different segments and regions. For policy-oriented readers, it illuminates the relationship between regulatory design, infrastructure development, and market outcomes, offering evidence that can inform program design and stakeholder coordination.
Conclusion: Prioritizing Precision in a High-Growth Market
The electric scooter market presents a compelling growth narrative, but growth alone does not guarantee competitive success. Organizations that thrive in this environment will be those that combine macro-level appreciation of market momentum with micro-level understanding of segmentation dynamics, competitive behavior, regulatory exposure, and supply-chain resilience. Aggregate figures provide necessary context, but they do not substitute for the granular intelligence required to allocate resources efficiently, position products effectively, and anticipate shifts before they become industry consensus.
This report offers that depth. It is structured to equip decision-makers with a comprehensive view of where the market stands, how it is evolving, and what strategic options are most likely to yield durable advantage through 2032. To access the full dataset, detailed segmentation breakdowns, regional performance analysis, competitive benchmarking, and the complete set of forecasts underpinning this analysis, we invite you to explore the full report on our platform. The complete intelligence package provides the precision necessary to convert market opportunity into executable strategy.
For detailed analysis of this topic, please visit the official page: Electric Scooters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wind Turbine Blade Market Hits $29.34B in 2025, Projected 6.53% CAGR to 2032
By pmarketresearch, 2026-09-15
Navigating the Wind Turbine Blade Market: Strategic Imperatives for 2026 and Beyond
The global energy transition is no longer a speculative narrative; it is a capital-intensive reality reshaping infrastructure portfolios worldwide. At the heart of this transformation lies the wind turbine blade, a critical component that dictates efficiency, longevity, and ultimately the levelized cost of energy. As we move through 2026, industry stakeholders face a complex matrix of technological innovation, regulatory pressure, and shifting geographic demand. This article serves as an executive overview of our latest comprehensive market research, designed to equip strategic decision-makers with the intelligence required to navigate this evolving landscape.
Our analysis indicates that the market has sustained a robust growth trajectory over the past half-decade. Valued at approximately 21.38 billion USD in 2020, the sector expanded steadily to reach 29.34 billion USD by 2025. This historical performance underscores the resilience of wind energy investments despite macroeconomic fluctuations. Looking forward, the forecast period from 2026 to 2032 projects continued expansion, with the market expected to surpass 45 billion USD by the end of the decade. This growth is underpinned by a compound annual growth rate that reflects sustained demand for both onshore and offshore capacity, driven by national renewable targets and corporate procurement strategies.
However, top-line figures only tell part of the story. The strategic value for enterprise leaders in 2026 lies in understanding the underlying dynamics propelling this growth. Our report dissects the market into critical dimensions, offering a granular view of where value is being created and where risks are consolidating. For instance, the shift towards larger rotor diameters and higher capacity turbines is altering material requirements and supply chain logistics. Similarly, the geographic redistribution of manufacturing hubs is responding to trade policies and localization mandates. Decision-makers must recognize that the market is not monolithic; it is a collection of distinct segments, each with its own profit pools and competitive intensities.
Competitive Landscape and Strategic Positioning
The competitive environment is characterized by a mix of integrated turbine manufacturers and specialized blade suppliers. Our research identifies key players who are defining the standards for performance and sustainability. Companies such as LM Wind Power and Siemens Gamesa Renewable Energy remain pivotal, leveraging vertical integration and technological proprietary advantages to maintain market share. Vestas Wind Systems A/S continues to strengthen its position through strategic acquisitions, such as the recent expansion of its European manufacturing footprint, signaling a commitment to supply chain security and regional capacity.
Independent manufacturers like TPI Composites Inc. play a crucial role in the ecosystem, supporting multiple original equipment manufacturers across global facilities. Their ability to scale production, evidenced by significant production milestones reached in early 2025, highlights the importance of flexible manufacturing capabilities. Meanwhile, regional players in Asia and Europe, including Nordex SE, Enercon GmbH, and specialized Chinese manufacturers, are increasingly influential in shaping local market dynamics. The report provides detailed profiles of these entities, analyzing their strategic moves, capacity expansions, and partnership networks.
Market concentration remains a key metric for assessing competitive risk. The data suggests a moderately concentrated landscape where a handful of firms control a significant portion of revenue. Understanding the balance between integrated OEMs and independent suppliers is essential for procurement strategies and partnership evaluations. Our analysis explores how these relationships are evolving, particularly in the context of technology licensing and manufacturing alliances.
Technology and Sustainability: The New Battleground
Sustainability is transitioning from a corporate social responsibility initiative to a core operational requirement. The European wind industry has implemented a self-imposed landfill ban on decommissioned wind turbine blades effective January 2026. This regulatory milestone mandates that 100% of blades must be reused, recovered, or recycled. This shift places immense pressure on material science and end-of-life management strategies. Vestas has been proactive in this arena, aiming for full blade circularity by 2030 through initiatives like the CETEC project, which focuses on chemical disassembly processes for epoxy-infused blades.
Technological innovation is also accelerating in manufacturing processes. Advances such as additive manufacturing for blade molds, demonstrated through collaborations between industry leaders and national laboratories, are reducing production times and enabling more complex geometries. These developments offer potential efficiencies in cost and lead time, which are critical for meeting the aggressive installation targets set by governments globally. Siemens Gamesa's introduction of new offshore platforms exemplifies the push towards larger, more efficient turbines that can capitalize on offshore wind resources.
The report delves deep into these technological trajectories, evaluating their commercial viability and impact on cost structures. We assess the readiness levels of various recycling technologies and the potential for material redesign. For investors and product planners, understanding the timeline for these technologies to reach commercial scale is vital for long-term asset planning.
Market Dynamics and Regulatory Environment
The regulatory landscape is becoming increasingly complex, influencing both market entry and operational compliance. Beyond the European landfill ban, there are growing calls for Europe-wide regulations affecting large composite nacelle components. These regulations aim to standardize disposal practices and encourage circular economy principles across the industry. Companies operating in or exporting to these regions must align their product lifecycles with these emerging standards to avoid compliance risks and reputational damage.
Worldwide Wind Turbine Blade Anti-Corrosion Coating Market
Supply chain resilience is another critical dynamic. Geopolitical tensions and trade policies are prompting a reassessment of manufacturing locations. The data shows significant variation in regional market sizes, with Asia Pacific representing a substantial portion of global revenue, followed by Europe and North America. Each region presents unique challenges regarding logistics, labor costs, and local content requirements. Our study provides a comparative analysis of these regions, helping stakeholders optimize their geographic footprint without exposing sensitive strategic details prematurely.
Furthermore, the interaction between policy incentives and market demand creates volatility that requires agile strategic planning. Government subsidies, tax credits, and renewable portfolio standards vary significantly by jurisdiction. The report maps these policy frameworks against market growth projections to identify high-potential markets and potential bottlenecks.
What This Report Delivers for Your Organization
This market research is not merely a data compilation; it is a strategic toolkit designed for C-suite executives, investment managers, and product strategists. The full report offers detailed segmentation analysis across multiple dimensions, allowing you to isolate specific growth vectors relevant to your business unit. We provide historical data series that establish a reliable baseline for forecasting, alongside forward-looking estimates that account for scenario variations.
Readers will gain access to comprehensive profiles of key market participants, including their strategic focus, recent developments, and competitive positioning. This intelligence is crucial for benchmarking, merger and acquisition due diligence, and partnership identification. The analysis of recent industry events, such as major production milestones and facility acquisitions, provides context for understanding current market momentum.
Importantly, the report addresses the operational implications of sustainability mandates. We evaluate the cost implications of recycling technologies and the potential for new revenue streams from blade repurposing. This perspective is essential for companies looking to turn regulatory compliance into a competitive advantage. The insights provided are intended to support capital allocation decisions, R&D prioritization, and supply chain optimization.
Conclusion: The Path Forward
As the wind turbine blade market matures, the window for strategic advantage narrows. Success in 2026 and beyond will depend on the ability to anticipate technological shifts, navigate regulatory complexities, and optimize global operations. The data indicates a clear upward trend in market value, but realizing this potential requires nuanced understanding and precise execution.
Wind Turbine Blade Market
Our full market research report provides the depth and granularity needed to make informed decisions. It moves beyond general trends to offer specific, actionable intelligence tailored to the needs of industry leaders. We invite you to access the complete study to unlock the detailed segmentation data, comprehensive competitor analysis, and strategic recommendations that will define your approach in this critical sector. The insights contained within are designed to empower your organization to lead rather than follow in the renewable energy transition.
For detailed analysis of this topic, please visit the official page: Wind Turbine Blade Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com