

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Optical Fiber Fusion Splicer Market to Hit $344.8M by 2032, Growing at 6.0% CAGR

Navigating the Fiber Frontier: Strategic Intelligence for the 2026 Optical Fiber Fusion Splicer Market
The global optical fiber fusion splicer market stands at a pivotal inflection point. As network operators accelerate broadband rollouts, hyperscale data centers push beyond conventional density limits, and public infrastructure programs demand resilient connectivity backbones, equipment procurement decisions carry multi-year operational and financial implications. Our latest market research delivers a decision-ready intelligence package designed specifically for executives navigating 2026 capital allocation, product roadmap planning, and competitive positioning.
This briefing outlines why this analysis matters now, what strategic layers it unravels, and how procurement, R&D, and channel leaders can translate its findings into measurable advantage. Rather than cataloguing incremental shipment figures, the study maps structural forces, capability gaps, and procurement inflection points that will define winner-take dynamics through 2032.
The Trajectory: Why 2026 Is a Strategic Anchor Year
Historical demand patterns reveal a market that has consistently expanded rather than fluctuated with short-cycle technology hype. From 2020 through 2025, global revenue progressed steadily, reflecting sustained deployment cycles in telecommunications, institutional networks, and enterprise infrastructure. The base year of 2025 establishes a clear baseline, and the forward projection through 2032 indicates a compound annual growth rate of approximately 6.0 percent, with market size scaling into the mid-300 million USD range by the end of the forecast window.
This trajectory is not merely a function of incremental device replacements. It reflects compounding pressures: fiber-to-the-x expansions in underserved regions, densification of metro and long-haul routes, and the proliferation of high-capacity fiber arrangements within data center campuses. Organizations that treat the splicer market as a static procurement category risk misaligning budget cycles, inventory strategies, and service-level commitments. By anchoring decisions in a 2026-2032 lens, leaders can evaluate total cost of ownership, technology migration timelines, and supplier reliability under realistic deployment velocity rather than point-in-time pricing snapshots.
Optical Fiber Fusion Splicer Market
The research deliberately frames this growth as a structural shift in how connectivity is engineered, maintained, and scaled. Understanding which demand vectors are accelerating, which are plateauing, and where margin compression is likely allows strategy teams to prioritize investments that compound over the forecast horizon rather than chase short-term volume spikes.
What the Report Delivers: A Decision-Ready Intelligence Architecture
This study is built for operational use, not passive reading. It translates market signal into executable insight across four interconnected layers:
- Demand decomposition across technology categories, application environments, and geographic demand clusters, with emphasis on where capacity utilization, deployment complexity, and service intensity differentiate buyer behavior.
- Product architecture and performance signal analysis, covering core alignment versus ribbon and mass fusion workflows, automation maturity, field-ruggedization requirements, and how feature sets map to installation throughput and OPEX reduction.
- Procurement and policy context, including regulatory classification developments, standardization milestones, and public-sector sourcing activity that influence import costs, compliance risk, and government-adjacent demand pipelines.
- Competitive positioning and capability mapping, tracing how leading manufacturers differentiate through device performance, software connectivity, service ecosystems, and channel control.
Each layer is designed to reduce uncertainty in capital planning and product strategy. Procurement teams can benchmark supplier claims against functional reality, engineering leaders can prioritize feature roadmaps that align with high-growth deployment profiles, and partnership teams can identify where channel strength or after-sales support becomes a decisive differentiator in an increasingly fragmented supply base. The analysis intentionally avoids superficial segmentation summaries and instead focuses on the strategic weightings that determine which demand pockets will command pricing resilience, inventory discipline, and long-term supplier loyalty.
Competitive Landscape: Capability, Momentum, and Positioning Signals
The fusion splicer market is characterized by a relatively concentrated top tier alongside a broad field of regional and application-focused players. The five-firm concentration metric underscores that scale, brand recognition, and ecosystem maturity still command meaningful share, yet the remaining competition remains highly active in niche performance categories, ruggedized field tools, and ribbon or high-density fiber workflows.
Fujikura Ltd. continues to anchor its portfolio around core alignment optical fiber fusion splicers, including models built for telecom and enterprise environments, with increasing emphasis on cloud connectivity and low-loss splicing outcomes. Sumitomo Electric Industries, Ltd. reinforces its field and long-haul credibility through high-speed core alignment platforms that integrate GPS support, automatic cleave checking, and maintenance tooling designed to reduce installation variability. INNO Instrument Inc. has strengthened its positioning around rugged ribbon fiber support platforms, leveraging dual-camera architectures to serve data center and high-density deployment contexts where alignment precision and operational durability matter under demanding site conditions.
OFS Fitel, LLC maintains relevance through single-mode fiber splicing solutions embedded in telecom and enterprise networks, while Furukawa Electric Co., Ltd. extends its footprint across telecom carrier workflows and emergency repair scenarios, pairing core alignment capabilities with advanced ribbon and mass splicing functions. AFL Telecommunications LLC operates a complementary strategy by distributing Fujikura-branded platforms, including mass fusion models with intelligent alignment controls and automatic placement correction, enabling high-volume installation programs to benefit from established device performance with localized service reach.
Recent market momentum illustrates how product launches and institutional procurement activity can alter short-term demand visibility. In May 2026, AFL Telecommunications LLC introduced a Fujikura 100R mass fusion platform featuring automatic placement correction, a development that reduces operator intervention and aligns with high-throughput installation environments. Around the same period, the National Institute of Standards and Technology issued a Sources Sought solicitation to identify potential suppliers and vendors for fiber fusion splicer capabilities, signaling that government-adjacent acquisition planning is actively validating supply options for this equipment class.
Beyond product launches, regulatory and standardization developments are reshaping the market's operational backdrop. A U.S. Customs and Border Protection ruling classified a portable optical fiber fusion splicer under a telecommunications equipment tariff classification, a detail that procurement and import-planning teams must factor into landed-cost modeling and sourcing strategy. Separately, Sumitomo Electric Industries, Ltd. received recognition from Japan's Ministry of Economy, Trade and Industry for contributions to IEC and ISO international standards in optical fiber fusion splicing technology, reinforcing how standards leadership can function as a competitive moat in credibility, interoperability, and export-facing trust. These are not isolated news items; they are signals that connectivity equipment buyers must interpret when evaluating risk, compliance, and long-term supplier durability.
Strategic Implications: Where Decision-Makers Should Focus in 2026
The research translates the market's evolution into actionable priorities for three core functions:
- Procurement and supply chain leaders should stress-test supplier commitments against deployment complexity rather than unit price alone. As installation teams encounter higher fiber densities, tighter site constraints, and greater throughput expectations, device reliability, consumables availability, field-service responsiveness, and diagnostic software maturity become decisive cost drivers.
- Product and R&D teams should evaluate where automation, reduced operator intervention, and cloud-connected diagnostics can create defensible differentiation. In markets where installation labor and rework costs dominate total project expense, splicer platforms that minimize human variability can shift the value conversation from hardware price to operational efficiency.
- Commercial and partnership teams should map channel strength, regional service coverage, and standards-aligned credibility into their go-to-market strategy. In categories where purchase decisions are influenced by long-term support expectations and installer familiarity, ecosystem positioning often outweighs incremental feature announcements.
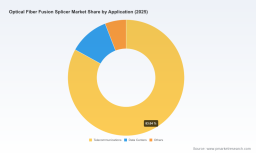
A critical insight is that the market's growth is not evenly distributed across buyer types or deployment contexts. Telecommunications-dominant demand, data center densification, and varied institutional or specialist applications each impose different performance thresholds, purchasing cycles, and service dependencies. Organizations that generalize their strategy across all segments risk diluting resources where competitive pressure is highest and overlooking pockets where technical specificity or service reliability commands premium positioning. The study isolates where differentiation is durable and where price competition is most likely to compress returns.
Why This Research Matters Now
2026 is not simply another forecast year; it is a calibration point where market momentum, product maturity, and procurement policy intersect. Buyers and suppliers alike are being asked to commit to equipment choices, service agreements, and capacity plans under conditions where installation scale, automation expectations, and public-sector sourcing activity are simultaneously evolving. A decision framework built on retrospective headlines or static segmentation will miss the strategic inflection points that determine margin endurance and market share stability.
Our full report extends well beyond this overview. It provides detailed assessments of demand composition, competitive capability mapping, regulatory and procurement watchpoints, and forward-looking deployment signals that help executives separate structural opportunity from transient noise. The objective is not to overwhelm with volume tables, but to equip teams with a clear lens on where to allocate attention, which supplier traits merit weight in sourcing decisions, and how to anticipate the next wave of installation-driven demand.
For leaders responsible for connectivity infrastructure, network expansion, or equipment portfolio strategy, the message is straightforward: the fusion splicer market is advancing along a definable growth path, but the strategic value lies in understanding which drivers will persist, which capabilities will command premium relevance, and where competitive intensity will reshape buyer expectations. This research is designed to convert that understanding into confident 2026 decisions and a stronger footing for the years that follow.
Worldwide Video Splicer Market
For detailed analysis of this topic, please visit the official page: Optical Fiber Fusion Splicer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com