

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Fuel Cell Electric Vehicles Market to Surge at 26.6% CAGR, Hit $37M by 2032

Strategic Intelligence for the Hydrogen Horizon: Navigating the 2026 Fuel Cell Electric Vehicle Landscape
Executive Summary: The Inflection Point of Hydrogen Mobility
The global transition toward sustainable transportation has entered a decisive phase. While battery electric vehicles have dominated early headlines, the Fuel Cell Electric Vehicle (FCEV) market is now demonstrating a distinct and robust growth trajectory, particularly in sectors where energy density and refueling speed are critical. As we move through 2026, industry leaders are shifting from pilot programs to scale-up strategies, driven by tightening decarbonization regulations and advancements in hydrogen infrastructure.
Electric Vehicles and Fuel Cell Vehicles Market
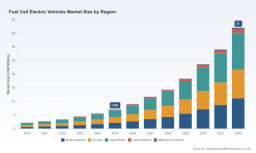
PW Consulting presents this comprehensive market research insight to equip stakeholders with the clarity needed to navigate this evolving landscape. Our analysis covers the period from 2020 through 2032, providing a detailed view of historical performance and future projections. The market, valued at approximately 2.21 billion USD in 2020, has seen accelerating momentum, reaching an estimated 7.08 billion USD by the base year of 2025. This trajectory underscores a compound annual growth rate (CAGR) of 26.6 percent throughout the forecast period extending to 2032. For corporate strategists, investors, and policy advisors, understanding the drivers behind this expansion is not merely an academic exercise but a requisite for capital allocation and product roadmap planning.
This article serves as a high-level overview of the strategic intelligence contained within our full report. It highlights the macroeconomic momentum, competitive dynamics, and regulatory pressures shaping the industry. However, the precise segmentation data, granular regional revenue splits, and specific application-level forecasts are reserved for the complete study. These detailed intelligence assets are critical for precise market entry strategies and are available through our comprehensive dataset.
Market Trajectory: From Niche Technology to Mainstream Adoption
The historical data from 2020 to 2025 reveals a consistent upward curve in market valuation. Starting at 2.21 billion USD, the market grew to 2.78 billion USD in 2021 and 3.46 billion USD in 2022. This growth accelerated through the pandemic recovery period, reaching 4.48 billion USD in 2023 and 5.61 billion USD in 2024. By 2025, the market revenue unit crossed the 7 billion USD threshold, signaling a maturation of the technology stack and supply chain.
Looking ahead, the forecast period from 2026 to 2032 projects aggressive expansion. The market size is anticipated to reach 9.06 billion USD in 2026, climbing to 11.69 billion USD in 2027 and 14.29 billion USD in 2028. By the end of the decade, valuations are expected to approach 23.59 billion USD in 2030, culminating at 37.0 billion USD by 2032. This momentum suggests that FCEVs are transitioning from early adoption to a growth phase driven by commercial viability. The double-digit CAGR indicates that investment flows into hydrogen technology are yielding tangible market returns, though the pace varies significantly by vehicle type and region.
Stakeholders analyzing this growth curve must consider the underlying volume drivers. The revenue growth is not uniform across all vehicle categories. Our deep-dive analysis examines how passenger cars compare against commercial heavy-duty trucks and vans in terms of revenue contribution and unit sales. While specific percentage splits are detailed in the full report, it is clear that commercial applications are generating substantial revenue due to higher unit values and intensive usage patterns. Understanding the balance between passenger and commercial segments is vital for manufacturers deciding where to allocate engineering resources and production capacity in 2026 and beyond.
Competitive Landscape: Key Players and Strategic Maneuvers
The FCEV market is characterized by a mix of automotive giants and specialized technology providers. Market concentration data indicates that the top three players hold a combined market share of 48.0 percent, while the top five control 52.0 percent of the market. This moderate concentration suggests a competitive environment where established leaders must defend their position against emerging challengers and new entrants leveraging patent portfolios or regional advantages. The following key companies are central to the current dynamics:
- Toyota Motor Corporation (Toyota City, Japan) : A pioneer in hydrogen mobility, Toyota continues to push the boundaries of passenger FCEV technology. Their flagship Mirai model integrates advanced fuel cell systems designed for performance and durability. The company's strategy focuses on maintaining technological leadership while expanding partnerships for hydrogen supply chains.
- Hyundai Motor Company (Seoul, South Korea) : Hyundai has aggressively positioned itself in both passenger and heavy-duty segments. With the Nexo passenger vehicle and the Xcient heavy-duty truck, Hyundai addresses diverse use cases. Their recent product debuts highlight a commitment to continuous innovation, leveraging over two decades of FCEV development experience.
- Honda Motor Co., Ltd. (Tokyo, Japan) : Honda complements its passenger offering with the CR-V e:FCEV, which combines fuel cell technology with plug-in battery capabilities. This hybridization strategy aims to maximize flexibility for users. Additionally, Honda supplies fuel cell systems for commercial applications, diversifying its revenue streams beyond vehicle sales.
- BMW Group (Munich, Germany) : Entering the fray with a focus on series production, BMW is targeting market entry around 2028. Their development programs emphasize integrating fuel cell technology into existing platforms while ensuring cost competitiveness. BMW's entry signals growing confidence in the long-term viability of hydrogen for premium automotive segments.
Recent developments during 2025 illustrate the active pace of product launches and strategic announcements. In July 2025, Honda began customer leasing of the CR-V e:FCEV in California, utilizing U.S.-made fuel cell modules. This move demonstrates a shift toward localized production and reduced logistical barriers. In November 2025, Hyundai debuted the all-new NEXO at the Japan Mobility Show, previewing a production model that reinforces their leadership in the passenger segment. Furthermore, the California Air Resources Board released its 2025 Annual Evaluation in December 2025, reporting 14,128 FCEVs registered in California as of April 2025. This data point provides a critical benchmark for regional adoption rates, though a slight year-over-year decline of 291 units highlights the volatility and challenges inherent in scaling infrastructure-dependent technologies.
These corporate actions and regulatory reports are interconnected. For instance, the CARB projection of a maximum of 112 stations enabling up to 16,210 FCEVs by 2028 creates a tangible ceiling for growth in key markets unless infrastructure investment accelerates. Companies are responding by aligning product launches with infrastructure milestones. Our full report analyzes how these timing mismatches between vehicle availability and fueling networks impact market penetration rates and what strategies firms are employing to mitigate risk.
Regulatory and Infrastructure Dynamics: The Dual Engines of Growth
The FCEV market does not exist in a vacuum. It is heavily influenced by policy frameworks and infrastructure readiness. The regulatory environment, particularly in regions with aggressive decarbonization targets, acts as a powerful catalyst. The Fuel Cell and Hydrogen Energy Association (FCHEA) highlighted these dynamics during the 2025 Hydrogen & Fuel Cell Seminar, emphasizing that policy alignment is driving commercialization in heavy-duty sectors. This suggests that while passenger vehicles often garner media attention, the commercial and heavy-duty segments may offer faster pathways to regulatory compliance and economic scale.
Infrastructure remains the critical bottleneck. The CARB 2025 Annual Evaluation underscores the need for hydrogen fueling station network expansion. With the projection of 112 stations supporting a specific capacity by 2028, the gap between current station counts and required coverage is evident. Strategic planners must evaluate not just the total number of stations, but their geographic distribution and reliability. Market participants are increasingly looking at public-private partnerships and government incentives to bridge this gap. Our analysis explores the correlation between station density and vehicle registration rates, revealing insights that are essential for infrastructure investors and fleet operators planning hydrogen procurement strategies.
Moreover, the industry context includes noise from various regulatory signals. Reports indicate that the first recorded decline in FCEV registrations in California, with 14,128 units as of April 2025, serves as a cautionary signal. This decline may reflect temporary factors such as supply chain constraints, vehicle model turnover, or consumer hesitation due to infrastructure anxiety. Understanding the root causes of such fluctuations is key to distinguishing between cyclical noise and structural shifts. The full market research delves into these nuances, providing context for interpreting raw registration data against broader economic and technological trends.
Strategic Implications for 2026 Decision Makers
For executives and analysts operating in 2026, the FCEV market offers both opportunity and complexity. The expansion from 9.06 billion USD in 2026 to over 37.0 billion USD by 2032 represents a significant addressable market. However, capturing value within this growth requires precise execution. Decision makers must balance investments across vehicle types, considering the differing total cost of ownership profiles for passenger versus commercial applications. They must also navigate the competitive landscape where market leaders hold substantial shares but face pressure from new technological iterations and regional players.
Fuel Cell Electric Vehicles Market
Strategic questions that this market research helps answer include: Which vehicle segments offer the highest margin potential in the current regulatory environment? How do geopolitical factors and hydrogen production costs influence regional market attractiveness? What are the timing implications of competitor product launches on market share erosion? While we have outlined the broad strokes of market size and key players here, the specific regional revenue contributions and detailed application breakdowns are provided in our complete study. These details allow for scenario planning and risk assessment that high-level summaries cannot support.
Additionally, the interaction between policy and technology adoption requires continuous monitoring. The FCHEA seminar discussions and CARB reports indicate a dynamic regulatory environment where targets are being set and adjusted based on deployment realities. Companies that can anticipate regulatory shifts and align their product pipelines accordingly will gain a first-mover advantage. Our report includes a timeline of regulatory milestones and policy announcements, helping organizations stay ahead of compliance requirements and incentive programs.
Conclusion and Access to Full Intelligence
The Fuel Cell Electric Vehicle market is at a pivot point. Historical growth from 2020 to 2025 has established a foundation, and the forecast through 2032 points to a transformative decade for hydrogen mobility. The involvement of major automakers like Toyota, Hyundai, Honda, and BMW, combined with active regulatory bodies and industry associations, creates a vibrant ecosystem of innovation and competition. Yet, the path to widespread adoption is fraught with infrastructure challenges and competitive intensity.
PW Consulting's full Fuel Cell Electric Vehicles Market research report offers a deeper layer of analysis required for sophisticated strategic planning. We provide granular segmentation data, including specific regional revenue estimates and application-level breakdowns, which are essential for market entry analysis and competitive benchmarking. Our proprietary datasets cover the sales volume trends, price dynamics, and supply chain vulnerabilities that influence profitability. We also offer comprehensive profiles of key suppliers and technology developers, along with an assessment of the risk factors that could alter the growth trajectory.
To access the complete set of market size projections, competitive intelligence, and actionable recommendations, we invite you to explore the full report. In an environment where data precision can determine investment success, our detailed insights provide the clarity needed to make informed decisions in the rapidly evolving FCEV sector.
For detailed analysis of this topic, please visit the official page: Fuel Cell Electric Vehicles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com