

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Aerospace & Marine Data Recorders Market to Hit $3,512.35 Million by 2032, 5.85% CAGR

The Unblinking Eye: Strategic Intelligence in the Aerospace and Marine Data Recorders Market Through 2032
In an era where data integrity defines operational resilience, the aerospace and marine data recorders market stands as a critical infrastructure layer for global transportation safety, regulatory compliance, and fleet optimization. As aviation and maritime operators navigate tightening certification frameworks, expanding voyage logging mandates, and the steady digitization of legacy monitoring systems, the ability to anticipiate demand shifts, technology migration paths, and competitive positioning has moved from optional to indispensable. Our latest market intelligence study, spanning historical performance from 2020 through 2025 and a forward-looking forecast window from 2026 to 2032, provides decision-makers with a rigorous, scenario-tested foundation for capital allocation, procurement strategy, and partnership development. This briefing outlines the structural drivers, competitive architecture, and regulatory tailwinds shaping the sector, while highlighting the analytical depth available in the full report.
The market has demonstrated steady, compounding growth over the past half-decade, reflecting both replacement-cycle maturity and incremental adoption of advanced recording architectures across commercial fleets, military platforms, and merchant marine operations. By 2025, the global market reached a baseline valuation that anchors our six-year projection period, with the trajectory pointing toward a compound annual growth rate of 5.85 percent through 2032. That growth is not merely a function of fleet expansion; it is increasingly driven by mandate-driven retrofits, higher-duration recording requirements, solid-state crash-survival standards, and the convergence of flight and voyage data into unified analytics pipelines. For executives planning multi-year programs, understanding where growth concentrates, which product families are gaining traction, and how regional procurement cycles align with certification timelines is essential for de-risking investment and capturing share in a moderately concentrated landscape.
Market Trajectory and Structural Dynamics
The historical record from 2020 to 2025 reveals a market that has consistently expanded beyond the pace of general transportation GDP, underscoring the regulatory and safety-driven nature of demand. The transition from older magnetic-tape and low-capacity solid-state units toward higher-density, networked, and longer-duration recording platforms has accelerated replacement cycles across both aerospace and marine end markets. Over the forecast horizon, the market is projected to climb steadily, crossing the mid-2020s threshold and advancing toward a valuation exceeding 3.5 billion dollars by 2032. This path is supported by durable demand for flight data recorders and cockpit voice recorders in commercial aviation, complemented by voyage data recorders and simplified voyage data recorders in maritime applications, alongside specialized quick access recorders that serve maintenance, engineering, and flight-safety analytics workflows.
Several structural forces underpin this trajectory. First, regulatory milestones are reshaping minimum equipment lists. In commercial aviation, federal and European certification authorities have moved to require cockpit voice recorders capable of at least 25 hours of continuous audio recording on new aircraft, with solid-state, crash-survivable designs becoming the norm. Parallel international civil aviation standards continue to specify minimum recording parameters and survivability thresholds for flight data recorders, effectively locking in baseline demand for upgraded units across narrow-body, wide-body, and freighter fleets. In the maritime domain, international maritime organization performance standards and associated classification society interpretations mandate voyage data recording on passenger ships and cargo vessels above defined tonnages, while simplified voyage data recorder requirements extend coverage to a broader segment of the merchant fleet. These requirements create a non-discretionary demand floor that sustains volume even when cyclical procurement budgets tighten.
Second, the operational value proposition of data recorders is expanding beyond accident investigation and compliance. Airlines, cargo operators, business jet fleets, and naval programs increasingly treat recorded data as an input to predictive maintenance, pilot training analytics, route optimization, and fleet reliability programs. Quick access recorders and data acquisition units have gained relevance as intermediaries that feed ground-side analytics platforms, enabling operators to extract actionable insights without waiting for post-incident retrieval. This functional expansion supports higher attachment rates for advanced recorder configurations and encourages vendors to bundle hardware with data handling software, download tools, and integration services. Third, supply chain normalization and component availability have improved the feasibility of large-scale retrofit programs, allowing operators to phase in 25-hour recording architectures and solid-state survivability upgrades across in-service fleets rather than deferring until next-generation deliveries.
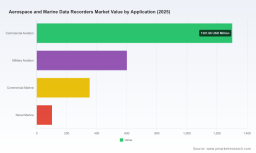
Geography and application mix further shape the growth pattern. Demand in North America remains anchored by mature commercial aviation fleets, active business aviation channels, and sustained defense-related procurement, while European markets benefit from stringent certification alignment and strong MRO networks. Asia Pacific reflects a combination of airline capacity growth, new aircraft deliveries, and expanding maritime trade infrastructure, creating incremental recorder demand across commercial and naval use cases. Latin America and the Middle East and Africa contribute more specialized but strategically important volumes tied to regional airline development, offshore marine activity, and government procurement cycles. Across applications, commercial aviation represents the largest demand pool, supported by recurring fleet refreshes and mandate-driven upgrades, while military aviation, commercial marine, and naval marine segments each present distinct purchasing rhythms, performance requirements, and integration constraints.
Regulatory Catalysts and Technology Migration
Regulation is the single most reliable demand catalyst in this market, and the current cycle introduces requirements that are reshaping both product design and lifecycle economics. The move to 25-hour cockpit voice recording mandates on new aircraft platforms compels operators and manufacturers to adopt recorder configurations that can sustain longer continuous capture without compromising crash survivability or retrieval reliability. Solid-state architectures have become the default expectation, offering greater resilience, faster data access, and improved compatibility with ground-side download and analysis workflows. These design shifts are not cosmetic; they influence bill-of-materials costs, qualification timelines, and the competitive positioning of incumbent suppliers versus newer entrants offering integrated connected-recorder solutions.
In the maritime sector, voyage data recorder mandates under international maritime organization performance standards and related code requirements continue to expand the addressable base across passenger vessels and cargo ships. The availability of simplified voyage data recorder options has broadened compliance pathways for smaller tonnage segments, while classification society expectations and port-state control scrutiny elevate the importance of certified, maintainable recording equipment. The practical effect is a market where compliance hardware must also satisfy operational durability, environmental hardening, and integration with bridge monitoring and ship performance systems. This dual mandate—regulatory conformity plus operational utility—favors suppliers that can deliver certified recorders alongside dependable data retrieval and performance monitoring capabilities.
Technology migration is also evident in the growing emphasis on connectivity and standardized data handling. Connected recorder platforms designed for extended voice and flight data capture are increasingly expected to interface cleanly with airline maintenance ecosystems and aircraft manufacturer distribution channels. Recent platform-specific availability announcements for major narrow-body and wide-body programs illustrate how recorder upgrades are being slotted into existing OEM and MRO pipelines, reducing installation friction and accelerating fleet-wide adoption. At the same time, data download tooling and interoperability arrangements are becoming strategic differentiators, as operators seek to streamline post-flight data extraction, minimize ground-time penalties, and integrate recorder outputs into broader flight data management environments.
Competitive Landscape and Strategic Positioning
The market exhibits a moderately concentrated structure, with a leading cohort of specialized aerospace and marine instrumentation providers commanding a significant share of qualified demand. This concentration reflects the certification-heavy nature of the sector, where qualification timelines, type-certification alignment, and long-term support commitments create meaningful barriers to entry. Incumbents with deep black-box heritage, established relationships with airframe and ship-equipment programs, and proven crash-survival pedigrees retain a durable advantage, while selective partnerships and licensing arrangements are reshaping how data handling features are commercialized.
Honeywell International remains a defining presence in the aerospace recording segment, drawing on more than sixty years of black-box technology experience to supply flight recorders for commercial aviation platforms. Its connected recorder series for extended cockpit voice and flight data recording has become particularly relevant as operators prepare for 25-hour voice mandates, and recent platform-specific availability for major airframer programs signals how recorder upgrades are being integrated into established delivery and service channels. Curtiss-Wright Defense Solutions complements this ecosystem with its own flight recorder portfolio and collaboration on extended-duration CVR/FDR systems for commercial, cargo, and business jet applications, reinforcing the trend toward shared architectures that reduce qualification duplication and broaden installation options.
Acron Aviation, formerly known in the commercial aviation solutions space, contributes cockpit voice and flight data recorder configurations tailored to commercial and specialized aircraft applications, with combined recording units that simplify installation and data management for operators seeking compact, reliable solutions. HR Smith Group addresses adjacent aerospace needs through combined position indicators with memory modules for recorder data storage and emergency locator beacons, illustrating how complementary subsystems increasingly intersect with the broader data recording value chain. Teledyne Controls rounds out the aerospace-focused cohort with data acquisition units, flight data management systems, and support for recorder data handling across aerospace platforms, positioning the company to benefit from the growing emphasis on post-recording analytics and ground-side data workflows.
On the marine side, Danelec Marine and Furuno Electric anchor a strong maritime recording segment, with Danelec emphasizing voyage data recorders and ship performance monitoring systems, while Furuno delivers voyage data recorder and simplified voyage data recorder product lines aligned with international maritime organization standards for merchant marine vessels. AMI Marine and Consilium further expand the maritime roster, offering voyage data recorder and simplified voyage data recorder systems for a range of vessel types and emphasizing compliance with international maritime organization and international electrodotechnical commission standards. Together, these providers reflect a competitive field in which certification readiness, environmental durability, and integration with vessel monitoring architectures are decisive differentiators.
Aerospace and Marine Data Recorders Market
Cockpit Voice and Flight Data Recorder Market
Recent activity underscores how quickly the competitive and commercial landscape can shift around a single regulatory or platform milestone. A major connected recorder configuration reached availability for leading narrow-body and wide-body platforms to meet extended voice recording mandates, followed by a distribution collaboration announced at a major MRO event and a separate licensing arrangement covering data download interoperability for a combined cockpit voice and flight data recorder family. These developments are not isolated product launches; they are signals of how compliance deadlines, OEM channel relationships, and data-handling tooling are converging to determine which suppliers capture retrofit volume and new-delivery attach rates during the forecast period.
What the Study Delivers
This report translates market complexity into decision-ready structure. It opens with a full market sizing and forecast model that traces historical performance and forward projections across the 2026 to 2032 window, giving executives a consistent baseline for scenario planning. The analysis decomposes demand by type, application, and region, enabling readers to isolate the segments most relevant to their portfolio, procurement calendar, or investment thesis. Rather than presenting static figures, the study examines the mechanics behind each split, including mandate-driven retrofit timing, fleet delivery momentum, and the interplay between commercial and defense procurement cycles.
The competitive section profiles the leading participants shaping the market, mapping product families, geographic reach, certification footprints, and strategic moves that are likely to influence share dynamics. It evaluates partnership, collaboration, and product-launch activity as indicators of channel access and technology direction, helping readers distinguish between incremental updates and structural shifts in competitive advantage. The regulatory and dynamics component weaves together civil aviation and maritime requirements into a single operational narrative, explaining how standards translate into equipment specifications, installation constraints, and lifecycle support obligations.
Practical modules extend the analysis into actionable territory. Readers gain access to procurement and replacement-cycle considerations, data handling and connectivity trends, and guidance on where certification risk is likely to concentrate as mandates phase in across new-production and in-service fleets. The study also outlines the implications for suppliers, system integrators, MRO providers, and fleet operators, with attention to where value is created in hardware, software, data services, or integrated solution bundles. Throughout, the focus remains on usable intelligence: not just what the market is doing, but why it is doing it, and how that behavior is likely to evolve under different regulatory and commercial scenarios.
Conclusion: From Compliance to Competitive Advantage
The aerospace and marine data recorders market is entering a phase in which regulatory mandates, platform-specific certification progress, and expanding data analytics use cases will jointly determine growth intensity and competitive outcomes. For companies operating in this space, the strategic question is no longer whether demand will persist, but where the highest-value demand will concentrate, which recorder architectures will become the default for new deliveries and retrofits, and how quickly interoperability and data handling capabilities will separate leaders from followers. A market growing at a steady multi-year compound rate toward a 2032 valuation above 3.5 billion dollars offers substantial opportunity, but capturing it requires clarity on segment timing, regional procurement rhythms, and the shifting balance between compliance-driven volume and analytics-enabled upgrades. The full study provides the detailed segmentation, competitive mapping, and forward scenarios needed to translate these dynamics into defensible strategy. For executives preparing 2026 plans and beyond, the report is designed to turn regulatory complexity and market breadth into a clear, actionable roadmap.
For detailed analysis of this topic, please visit the official page: Aerospace and Marine Data Recorders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com