

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Machinery & Automotive
PW Consulting: Digital Inclinometer Market Poised to Surge at 6.3% CAGR — From USD 342.7 Million in 2025 to USD 525.58 Million by 2032
By pmarketresearch, 2026-07-06
Digital Inclinometer Market 2026: Strategic Imperatives for Executive Decision‑Makers
Executive summary
As infrastructure renewal, renewable energy deployment, and industrial automation intersect, digital inclinometers have moved from niche sensing components to strategic enabling technologies. PW Consulting’s latest market study—anchored on a 2025 base year and a 2020–2025 historical review, with a 2026–2032 forecast horizon—shows a resilient market trajectory underpinned by MEMS adoption, diversified industrial demand, and rising requirements for structural health monitoring.
Digital Inclinometer Market
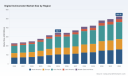
Key macro findings: the global digital inclinometer market reached approximately USD 342.7 Million (revenue, USD Million) in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of 6.3% through 2032, reaching an estimated USD 525.6 Million by 2032. Market concentration remains meaningful: the top three players account for roughly 38.5% of revenue, while the top five collectively control just over half of the market.
Digital Inclinometer Market
Why this report matters for 2026 strategic planning
- Actionable foresight for capital allocation: Our forecast and scenario analysis translate sensor-level trends into revenue and margin outcomes for adjacent systems integrators, OEMs, and infrastructure owners.
- Technology roadmap alignment: Understanding MEMS maturation and interface standardization is essential for R&D prioritization and supplier selection.
- M&A and partnership signaling: With moderate market concentration and differentiated product portfolios, targeted acquisitions and alliances can rapidly improve route-to-market, particularly for firms seeking entry into geotechnical or solar-tracking segments.
- Regulatory and quality assurance implications: Quality management certifications and evolving monitoring standards materially affect procurement cycles; timing investments to align with these triggers is a core recommendation.
Market trajectory and dynamics (what the numbers tell us)
The market’s progression from USD 228.5 Million in 2020 to USD 342.7 Million in 2025 demonstrates sustained demand growth driven by a mix of retrofit projects, new infrastructure builds, and expanded sensorization across industrial assets. The relatively stable near‑term forecast for 2026 (approximately USD 344.0 Million) masks divergent drivers beneath the surface: while traditional construction and heavy equipment use-cases continue to grow steadily, accelerated adoption in renewable energy and digital twin initiatives explains much of the medium‑term upside captured in the 6.3% CAGR to 2032.
Digital Inclinometer Market
From a competition perspective, mid-sized incumbents and specialized niche vendors coexist with large connectors and sensor conglomerates. The resulting market structure produces attractive windows for focused entrants: disciplined product differentiation or deep channel partnerships can yield disproportionate returns. Our concentration metrics (CR3 ≈ 38.5%, CR5 ≈ 52.7%) imply that while a handful of vendors dominate, there remains substantial room for regional specialists and OEM-focused suppliers to expand.
Competitive landscape: what strategic leaders need to know
Our vendor analysis synthesizes company positioning, product breadth, and go‑to‑market orientation. Below are condensed strategic profiles of several market movers we cover in the full report:
- Jewell Instruments (Manchester, NH, USA) — Offers a broad portfolio across single-, dual- and tri-axis MEMS and force-balance inclinometers with flexible analog and digital outputs. Strengths: product diversity and proven performance in harsh environments. Strategic implication: Ideal partner for integrators requiring flexible interfacing and ruggedized designs.
- GEOKON (Lebanon, NH, USA) — Focuses on geotechnical inclinometer systems for slope stability and structural monitoring. Strengths: domain-specific instrumentation and long-standing adoption among geotechnical consultancies. Strategic implication: High value for infrastructure monitoring programs and long-term service contracts.
- US Digital (Vancouver, WA, USA) — Specializes in absolute optical and networked inclinometers with full 360° capability and high resolution. Strengths: precision, networkability, and suitability for solar and dredging applications. Strategic implication: Attractive for players targeting precision applications and networked asset management.
- Level Developments Ltd (Croydon, UK) — Produces tilt sensors and OEM modules tailored for machinery and solar tracking. Strengths: OEM partnerships and temperature-compensated product lines. Strategic implication: Potential acquisition target for firms seeking European OEM channels.
- Rieker Inc (Aston, PA, USA) — Offers vehicular and industrial tilt monitoring solutions. Strengths: focus on vehicle safety and boom angle systems. Strategic implication: Strong OEM relationships in mobile equipment sectors.
- Fredericks Company (Huntingdon Valley, PA, USA) — Precision analog and digital sensors for industrial and environmental applications. Strengths: wide range of angular ranges and industrial-grade interfaces. Strategic implication: Suited for precision retrofit projects.
- TE Connectivity (Schaffhausen, Switzerland) — Brings high-volume manufacturing and platform-level solutions with CAN interfaces and rugged designs. Strengths: scale, systems integration capability, and automotive-grade practices. Strategic implication: Competitive pressure in any application requiring platform-level certification and high-volume supply chains.
Recent developments and regulatory context
Key industry events in the recent 12–18 months reinforce the strategic themes above. Notably, a prominent sensor manufacturer successfully completed an ISO 9001:2015 follow‑up audit in early 2026, signaling consistent quality governance—an increasingly important procurement filter for infrastructure and energy clients. Product introductions and catalog expansions from several vendors in 2025 highlighted incremental performance improvements (resolution and response times) and application-specific packages for solar tracking and industrial machinery.
These developments are consistent with two macro dynamics we analyze in depth: first, the rising importance of structural health monitoring for public and private infrastructure, which favors MEMS-based inclinometers for their precision and compactness; second, the role of interface standardization and network protocols in enabling scale deployments across energy and industrial sectors.
Report contents — practical, decision‑oriented deliverables
PW Consulting’s Digital Inclinometer Market report is designed as a practical playbook for 2026 decision-making. The report includes:
- Market sizing and forecast models (2020–2025 historical, 2026–2032 forecast) with scenario and sensitivity analyses to stress-test strategic options;
- Go‑to‑market frameworks and buyer decision matrices tailored to OEMs, system integrators, and end‑users;
- Detailed vendor scorecards, product capability maps, and channel evaluations to guide supplier selection and partnership prioritization;
- Technology roadmaps showing MEMS performance curves, interface trends (serial, CAN, Modbus, etc.), and power consumption profiles with suggested R&D focus areas;
- Regulatory impact analysis and procurement triggers, including quality management certifications and standards that affect adoption cycles;
- M&A screening tools: candidate profiles, rationale templates, and valuation heuristics to accelerate deal evaluation;
- Operational tools: deployment cost models, ROI calculators, and pilot-to-scale playbooks for fast-track rollouts.
In keeping with our “trailer” approach, this release intentionally highlights the analytical depth and practical outputs without reproducing the full segment-level tables and proprietary splits contained in the report. Those granular insights—critical for tactical execution—are available in the full report and accompanying data pack.
Strategic recommendations for 2026
- Prioritize MEMS-led product lines for volume and low‑power applications: MEMS continues to dominate due to precision, compactness, and cost-efficiency—allocate R&D and sourcing resources accordingly.
- Invest in interface and systems compatibility: Support for standardized interfaces and network protocols reduces integration friction and shortens sales cycles for platform customers.
- Target verticalized solutions: Focus on a small set of high-value verticals (infrastructure monitoring, solar tracking, heavy equipment) where sensor selection is driven by domain-specific requirements rather than general-purpose price competition.
- Use certification and quality programs as differentiators: Attesting to manufacturing and quality standards can be a decisive procurement criterion, especially for public infrastructure projects and international tenders.
- Consider bolt-on M&A or distribution partnerships to broaden channel reach in underpenetrated regions: With a mid-level concentration profile, targeted acquisitions can rapidly improve market access and product portfolio depth.
How executives should use this report
Procurement leaders can use our vendor scorecards and procurement templates to compress tender cycles and reduce integration risk. Product and R&D executives will find the technology roadmaps and interface analysis useful for prioritizing next-generation sensor designs. Strategy and corporate development teams can leverage our M&A screening and valuation heuristics to build a pipeline of targets matched to specific capability gaps.
Conclusion and next steps
The digital inclinometer market in 2026 is a balance of steady, demand-driven growth and selective disruption driven by MEMS improvements, interface standardization, and expanding structural monitoring use-cases. The market’s medium-term upside—captured in a 6.3% CAGR through 2032—creates attractive strategic entry points for product innovators, integrators, and financial sponsors.
PW Consulting’s full Digital Inclinometer Market report provides the complete dataset, segment-level analyses, and executable playbooks required to convert insight into strategy. For organizations preparing capital budgets, launching new sensor lines, or evaluating M&A in 2026, the report delivers the granular intelligence and practical tools to shorten time-to-decision and increase execution certainty.
To access the full report, detailed company matrices, and interactive modeling assets, please visit the PW Consulting publications page or contact our research team for an executive briefing.
For detailed analysis of this topic, please visit the official page: Digital Inclinometer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Floor-Standing Aircraft Weighing Scales Market to Rise from USD 521.09 Million in 2025 to USD 836.75 Million by 2032 (7.0% CAGR)
By pmarketresearch, 2026-07-06
Floor Standing Aircraft Weighing Scales Market: Strategic Preview for 2026 Decision-Makers
Executive snapshot
PW Consulting’s latest market study on Floor Standing Aircraft Weighing Scales delivers a focused, actionable intelligence package geared to inform capital allocation, product roadmaps, procurement choices, and M&A prioritization for 2026. Our analysis traces developments across 2020–2025, anchors decision-making to a 2025 base year, and projects through 2032. The global market, which reached a material scale in 2025, is expected to expand at a steady compound annual growth rate (CAGR) of approximately 7.0% over the forecast window, underpinning both organic investment cases and inorganic consolidation scenarios for incumbent and new entrants alike.
Floor Standing Aircraft Weighing Scales Market
Why this market matters in 2026
Aircraft weighing is a mission-critical activity for airlines, manufacturers, MROs, and military operators: accurate weight and balance data are prerequisites for safety, regulatory compliance, fuel optimization, and payload planning. As airline networks rebound and fleets renew, and as regulatory scrutiny around traceability and measurement uncertainty tightens, the modest-size but technically demanding market for floor standing aircraft weighing scales occupies a strategic niche. For 2026 planning cycles, this market presents three converging forces that will drive decisions:
Floor Standing Aircraft Weighing Scales Market
- Regulatory tightening and traceability expectations that increase demand for certified, NIST-traceable systems and documented calibration chains;
- Technology-driven shifts toward digital, wireless, and data-integrated weighing solutions that reduce operational friction and enable lifecycle service revenues;
- Consolidation and platform differentiation as a small number of high-capability suppliers capture an outsized share of high-value contracts.
Market trajectory and its strategic implications
From a strategic standpoint, market momentum matters more than headline absolute value. Our study finds that after a recovery phase in the early 2020s, the market scaled meaningfully into 2025 and is forecast to continue expanding through 2032. This growth profile supports multi-year investment plays—product development for digitized scales, expansion of calibration and service networks, and targeted acquisitions that add technological or geographic capabilities. Importantly, the market exhibits moderate concentration; the top three players account for a substantial share, and the top five even more so, creating both barriers and opportunities for challengers. For executives planning 2026 budgets, this combination implies that selective investment in differentiated product features and channel partnerships can deliver outsized returns.
Floor Standing Aircraft Weighing Scales Market
Practical, non-negotiable levers for success in 2026
Our research identifies a short list of operational levers that will separate winners from laggards in the coming year:
- Compliance-first product engineering: Systems that demonstrate traceability to recognized standards and meet the ±0.1% accuracy expectations demanded by certification authorities will remain table stakes.
- Data-enabled service models: Wireless telemetry, secure cloud integration, and standardized data exchange formats increase the lifetime value of each installed base and create cross-sell levers for calibration and digital maintenance offerings.
- Lightweight, durable materials: The continued use of aircraft-grade aluminum and optimized low-profile designs reduces handling friction and broadens applicability across aircraft classes without adding complexity to regulatory compliance.
- Channel and aftersales footprint: Quick-response calibration services and regional presence are decisive for airlines and military operators who prioritize operational continuity.
What the PW Consulting report delivers — operational content for 2026
This is not a desk-summary. The report is constructed as an operational toolkit for corporate strategy, procurement, and product teams. Key deliverables include:
- Market sizing and growth scenarios: A clear base-case and alternative trajectories through 2032, with modeled sensitivities to fleet growth, regulation, and technology adoption.
- Competitive benchmarking: A structured scorecard approach evaluating capability across performance (accuracy, capacity), form factor (low-profile vs. platform), digital integration (wireless, APIs), and service nodes (calibration, spare parts).
- Procurement playbook: RFP templates, evaluation matrices, and total cost of ownership (TCO) models tailored to airlines, MROs, and military procurement cycles.
- Product and R&D roadmap guidance: Prioritized feature investments (e.g., Bluetooth and secure telemetry stacks, ruggedized low-profile platforms) with estimated development timelines and break-even analyses.
- M&A and partnership framework: A tiered target map and valuation heuristics for tuck-in acquisitions or technology partnerships that accelerate entry or close feature gaps.
- Compliance checklist and calibration traceability protocol: Practical, auditable steps to maintain NIST-traceable measurement chains and meet advisory circulars and industry standards.
Competitive landscape — who to watch
The market is technologically specialized and served by a small set of highly capable vendors. Our competitive analysis synthesizes public product capabilities, recent commercial developments, and positioning strategies:
- Intercomp Company (Medina, Minnesota) — A recognized leader in platform scales and top-of-jack systems, their product evolution toward wireless and low-profile high-capacity models, combined with NIST-traceable calibration offerings, reinforces a premium, service-centric positioning. Recent product introductions that emphasize Bluetooth-enabled real-time data transfer underscore their focus on digitizing the installed base.
- General Electrodynamics Corporation (Arlington, Texas) — Known for portable, wireless, and low-profile systems, with patented technologies and global adoption. Their product set targets operational flexibility and rapid deployment, attributes that resonate with airlines and OEMs seeking plug-and-play capability.
- Teknoscale Oy (Vantaa, Finland) — A specialist in high-capacity EVOPLANE and EVOJET platforms, Teknoscale competes on engineering depth for heavier commercial and fighter aircraft requirements, emphasizing ruggedness and precision.
- Langa Industrial S.A. (Spain), FEMA AIRPORT (France), Henk Maas Weegschalen B.V. (Netherlands), Jackson Aircraft Weighing Systems LLC (USA) — These providers differentiate through vertical integration into ground support equipment (GSE), certification credentials tied to OEM assembly lines, and regional service footprints.
Notably, recent corporate moves—product launches, customer adoptions, and OEM certifications—illustrate how vendors are shifting to capture higher-margin recurring services alongside hardware sales. Intercomp’s late-2025 launch of a Bluetooth-enabled Expert Weigh platform and a major airline’s move to low-profile high-capacity models are cases in point. Likewise, homologation wins that support final assembly operations remain critical differentiators for suppliers targeting OEM supply chains.
Regulation, standards, and materials — operational realities
Regulatory compliance is a practical constraint that shapes procurement and product design. Advisory circulars and industry standards require calibrated systems with documented traceability for certified aircraft operations. Practitioners must plan around mandated accuracy tolerances and maintain auditable calibration chains; this drives demand for certified calibration providers and for supplier capabilities that can deliver and log evidence of measurement integrity.
On the engineering side, lightweight, aircraft-grade aluminum remains the material of choice for low-profile platform construction; it enables high load capacity while maintaining portability and corrosion resistance. Vendors that optimize structural design to balance stiffness and weight while preserving calibration stability will secure competitive advantage.
Strategic moves for executives in 2026
For leadership teams allocating 2026 resources, our report prescribes a pragmatic set of moves:
- Prioritize features that unlock recurring revenue: wireless telemetry, secure over-the-air firmware, and cloud-based calibration logs convert capital purchases into streams of service revenue.
- Build or secure calibration capacity: either through partnerships with accredited calibration labs or targeted acquisitions, since proximity and turnaround time influence procurement decisions.
- Pursue targeted product line extensions: low-profile, high-capacity pads and lightweight modular platforms open up OEM retrofit and fleet modernization opportunities without requiring full product platform reinvestment.
- Consider bolt-on acquisitions for technology gaps: acquiring a specialist wireless-stack provider or a regional service network can accelerate time-to-market at a lower risk than greenfield expansion.
How to use this preview and next steps
This article is a preview of the full strategic package. PW Consulting’s complete report includes detailed scenario outputs, vendor scorecards, procurement templates, and an investable target map designed to accelerate decision-making during 2026 budgeting and strategy cycles. We intentionally preserve granular segmentation and contract-level detail for the full report to ensure proprietary value for subscribers and clients.
If you are preparing capital plans, evaluating product roadmaps, or assessing M&A targets for 2026, our research team can deliver a tailored briefing that maps the report’s findings to your specific operational and financial KPIs. Our clients use these briefings to adjust procurement cadence, refine R&D priorities, and model acquisition synergies with confidence.
Closing note
The Floor Standing Aircraft Weighing Scales market is compact but consequential: accuracy requirements, regulatory oversight, and a push toward digitization make it strategically important for aviation operators and equipment providers alike. With a steady growth trajectory and concentrated vendor landscape, 2026 offers a window for disciplined investment and consolidation. PW Consulting’s report equips executives with the empirical models and field-tested tools necessary to convert market visibility into actionable strategy—without exposing proprietary segmentation data in a public summary. For the complete breakdown, granular segmentation, and bespoke briefings, visit our full report page or contact PW Consulting’s aviation practice.
For detailed analysis of this topic, please visit the official page: Floor Standing Aircraft Weighing Scales Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Automotive Occupant Sensing Systems (OSS) and Whiplash Protection Systems (WPS) Market to Expand at 8.75% CAGR During 2026–2032
By pmarketresearch, 2026-07-06
Automotive Occupant Sensing Systems & Whiplash Protection Systems (OSS & WPS): Strategic Imperatives for 2026
Executive preview
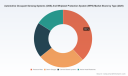
As original equipment manufacturers (OEMs), Tier-1 suppliers, and private equity investors orient strategy for 2026, the occupant sensing and whiplash protection market has moved from niche safety add-ons to a structural line item in vehicle platform roadmaps. Our latest PW Consulting market study — covering historical performance (2020–2025) and forecasting through 2026–2032 — shows a clear, data-backed trajectory: the OSS & WPS market expanded from approximately USD 3,124.65 Million in 2020 to USD 5,200.0 Million in 2025, and is projected to reach roughly USD 9,356.0 Million by 2032, representing a compound annual growth rate (CAGR) of 8.75% over the forecast window. This growth is being driven by converging forces: stricter safety regulation and test protocols, faster adoption of interior sensing technologies, and OEM platform strategies that treat occupant sensing as both a safety and comfort enabler.
Automotive Occupant Sensing Systems Oss And Whiplash Protection System Wps Market
Why 2026 is a decisive year
Two inflection points crystallize the urgency for near-term decisions. First, regulatory and test-body updates enacted in late 2025 and early 2026 (notably Euro NCAP protocol enhancements and refreshed IIHS whiplash evaluation methods) materially raise the bar on restraint performance, forcing OEMs and suppliers to accelerate development and validation cycles. Second, interior sensing requirements tied to driver-monitoring, child presence detection and adaptive restraint deployment are becoming standard items on safety checklists rather than optional features — converting latent demand into procurement mandates across multiple vehicle segments.
Automotive Occupant Sensing Systems Oss And Whiplash Protection System Wps Market
Market dynamics at a glance
- Strong historical expansion: The market nearly doubled in scale within the past five years, validating investment hypotheses for sensing hardware, embedded software, and integrated restraint modules.
- Durable mid-single-digit-plus CAGR: An 8.75% CAGR through 2032 reflects sustained replacement cycles, retrofit and aftermarket opportunities, and feature migration from premium to mainstream models.
- Moderate concentration: The market exhibits meaningful concentration amongst top OEM suppliers (CR3 ≈ 48.5%; CR5 ≈ 62.3%), indicating both opportunities for independent innovators and entry barriers for new full-system suppliers.
Competitive landscape — practical reading for decision-makers
Our competitive analysis profiles incumbent global players and emerging specialists. The ecosystem is led by well-capitalized Tier-1s that combine sensing, restraint actuation, and certification experience, along with seat manufacturers and electronic systems houses that integrate sensing into vehicle architecture. Selected company insights we highlight include:
Automotive Occupant Sensing Systems Oss And Whiplash Protection System Wps Market
- Autoliv Inc.: Broad occupant protection portfolio with holistic concepts for integrated pelvic and head restraint innovations; continues to position itself as a safety systems integrator across airbag and restraint domains.
- Robert Bosch GmbH: Deep competency in occupant electronics and multi-modal interior sensing (camera, radar) and in control-unit integration for classification and deployment logic.
- Continental AG: Focuses on cabin sensing stacks and camera/radar-based occupant monitoring as part of its passenger-safety roadmap.
- Magna International: Recent program wins demonstrate industrialization capability for multi-modal sensing systems across OEM programs, including child presence detection.
- ZF Friedrichshafen, Lear Corporation, Hyundai Mobis, Joyson Safety Systems, Grammer AG: Each plays a differentiated role across seating, sensing, and restraint subsystems, from sensor hardware and algorithms to mechanically integrated whiplash mitigation.
Recent public developments — from Magna’s announced program deployments to Autoliv’s trade-show innovations and IIHS’s updated whiplash test protocols — are analyzed in the report to expose where product roadmaps, certification timelines, and procurement cycles intersect.
Technology and product evolution
Occupant sensing today is a multi-technology problem set: pressure-based systems, strain sensors, camera and radar imaging, and active head restraint mechanics each bring distinct cost-performance trade-offs. But the strategic story is less about individual sensor types and more about system orchestration — sensor fusion, real-world validation across occupant postures and clothing, and resilient algorithms that deliver deterministic safety outcomes in regulatory testbeds. Suppliers that excel will be those that marry validated sensing stacks with scalable electronic control units, cybersecurity-hardened software, and industrialized seat integration.
Regulation & testing: the new de facto procurement driver
Regulatory change is simultaneously a market facilitator and a risk accelerator. Euro NCAP’s 2026 protocols and IIHS’s December 2025 whiplash evaluation impose new, measurable performance targets; compliance is becoming a non-negotiable pass/fail for many OEM programs. Our report provides a regulation-to-product map that links each test requirement to supplier capabilities, validation steps, and recommended contingency timelines. For procurement teams, this map translates into a prioritized supplier audit checklist and a realistic time-to-compliance ladder for 2026 launch schedules.
What the PW Consulting report delivers (practical contents)
We designed the study as an actionable playbook for commercial and product leaders. Key inclusions:
- End-to-end market model (historical 2020–2025; base year 2025; forecast 2026–2032) with scenario sensitivity and upside/downside case workstreams.
- Technology deep dives and sensor fusion performance matrices that link capability to OEM use-cases and test outcomes.
- Regulatory impact assessment and a compliance runway that aligns IIHS/Euro NCAP/EU requirements with development and validation milestones.
- Supplier scorecards and competitive positioning tools (strengths, weaknesses, industrial scale, certification experience).
- Commercial playbooks for OEM sourcing teams (RFI/RFP templates, integration checkpoints, validation protocols) and for suppliers (go-to-market templates, pricing levers, program win strategies).
- M&A and partnership candidacy matrix highlighting where vertical integration or capability buy-in de-risks time-to-market.
Important: the report contains the granular segmentation by region, application, and sensor type, plus detailed unit/revenue splits and price curve assumptions. Those subsegment tables are purposefully omitted from this release to preserve strategic value and are available in the full report.
Implications for corporate strategy in 2026
For OEMs:
- Prioritize supplier shortlists based on integrated validation experience, not only sensor performance. Certification history and IIHS/Euro NCAP track record matter for program risk reduction.
- Lock-in upgrade paths on platform architectures that allow sensor and software swaps across model years; retrofitting logic must be feasible for aftermarket safety mandates.
For Tier-1 suppliers:
- Invest in sensor fusion IP, deterministic algorithms, and verification labs that simulate the new test pulses and occupant variability scenarios. This is a superior defense against margin erosions from sensor commoditization.
- Consider partnerships with seat manufacturers and software houses to offer fully integrated subsystems rather than component kits.
For investors and M&A teams:
- Target assets with proven validation pipelines and OEM program footprints. Smaller firms with differentiated algorithms or child-presence detection IP command a premium when paired with system integrators.
- Use the market’s concentration profile to assess consolidation opportunities where three-to-five vendor dominance leaves adjacent niches for bolt-on acquisitions.
Five pragmatic actions to take in the next 12 months
- Complete a compliance gap analysis against IIHS and Euro NCAP updates and map the shortest path to “test-ready” status for next-generation platforms.
- Re-baseline cost models to reflect accelerated sensor adoption and software lifecycle costs; include cybersecurity and over-the-air update provisions.
- Run supplier stress-tests: validate claims against third-party labs and demand full-program references that include certification documentation.
- Establish a carrier-grade integration roadmap for human-machine interface (HMI) and occupant comfort features that leverage sensing data — turning a safety line item into a multi-revenue stream opportunity.
- Build a two-track partnership strategy: fast-follower arrangements for immediate compliance, and strategic co-development for longer-term differentiation.
Closing — how this intelligence translates into competitive advantage
By 2026, occupant sensing and whiplash protection will no longer be optional engineering checkboxes; they will be program-level determinants of vehicle launch viability and brand safety positioning. PW Consulting’s OSS & WPS study equips leaders with the market sizing, scenario analyses, regulatory mapping, and supplier playbooks needed to make de-risked, time-sensitive decisions. We present enough insight here to inform strategic intent while reserving the granular segment tables, regional breakdowns, and supplier financials for purchasers of the full report — the source of the exact metrics required to operationalize tactics and commitments.
Next step
For teams preparing 2026 budget cycles and platform commitments, schedule a briefing with our Automotive Practice to review the full dataset, supplier scorecards, and scenario-specific action plans. The path to compliance and commercial advantage is measurable; the question is whether you want the public synopsis or the full playbook that converts insight into executed advantage.
For detailed analysis of this topic, please visit the official page: Automotive Occupant Sensing Systems Oss And Whiplash Protection System Wps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial Centrifuge Machines Market to Reach USD 13.47 Billion by 2032, Growing at a 5.12% CAGR—North America Leads with USD 3.54B (2025)
By pmarketresearch, 2026-07-06
Industrial Centrifuge Machines Market: Strategic Preview for 2026 Decision-Making
PW Consulting’s new Industrial Centrifuge Machines Market brief crystallizes the high-level trends and decision levers that will shape procurement, product strategy, and M&A activity in 2026. Our analysis shows a mature market that continues to expand steadily — estimated at USD 9.53 Billion in the 2025 base year with a compound annual growth rate of 5.12% across the 2026–2032 forecast window (our horizon projects market growth toward the mid-teens in cumulative value by 2032). These headline figures frame an environment of moderate growth, measurable consolidation, and acute cost pressure that executives must navigate with precision.
Industrial Centrifuge Machines Market
Why this preview matters to executives in 2026
-
Timing capital investment: A steady mid-single-digit CAGR signals that now is a tactical moment to prioritize modernization and service-led differentiation rather than pursue broad capacity expansion. Companies that sequence investments to capture premium segments (high-throughput, high-integrity separations) will outpace peers on margin expansion.
Industrial Centrifuge Machines Market -
Supplier and partner selection: Market concentration metrics reveal a landscape where top suppliers hold meaningful scale but do not dominate outright — creating room for regional specialists and innovative challengers to win business through speed-to-application and lifecycle services.
Industrial Centrifuge Machines Market -
Cost and supply risk mitigation: Sustained raw-material pressures and trade-policy dynamics mean manufacturers and end-users must re-evaluate sourcing, design-to-cost, and hedging strategies to protect margins in 2026.
What the report delivers — practical, executable intelligence
Our full market study is built for executives who need to convert market intelligence into concrete actions within 6–18 months. Key deliverables include:
-
Executive playbook — a prioritized list of six strategic moves (e.g., service-first product roadmaps, targeted bolt-on acquisition criteria, and aftermarket monetization pathways) aligned to different corporate objectives: growth, margin protection, and defensibility.
-
Proprietary Total Cost of Ownership (TCO) models — scenario-ready tools that quantify CapEx and OpEx trade-offs across equipment classes, lifecycle services, and energy regimes to inform procurement and retrofit decisions.
-
Go-to-market frameworks for product differentiation — templates for positioning high-speed separators, decanters, and filtration-focused units to win in food & beverage, bioprocessing, wastewater, and heavy industrial segments.
-
Supplier & technology scorecards — standardized evaluation matrices that combine performance, service capability, footprint, and digital maturity so buyers can accelerate supplier selection without the ambiguity of disparate vendor data.
-
Regulatory and raw-material impact maps — decision matrices that translate tariffs, specialty-steel volatility, and local content rules into procurement and inventory responses to protect project economics.
-
Scenario-driven demand forecasts — short-, medium-, and long-term scenarios that stress-test investment plans under variations in feedstock, energy costs, and end-market demand for circular-processing solutions.
Competitive landscape: how incumbents and challengers are positioning in 2026
The market is characterized by a mix of large multinational OEMs, regionally focused specialists, and century-old firms that have carved niche capabilities. Three- and five-firm concentration numbers indicate a market where scale matters but innovation and service differentiation can carve outsized value. Against that backdrop, companies are pursuing distinct strategic levers:
-
Product-led differentiation: Global OEMs continue to launch high-value separators and decanters optimized for growth verticals. Recent launches that exemplify this move include high-speed units designed for dense fermentation and hermetically sealed separators for biopharma processes — reflecting targeted investment toward higher-margin, technology-intensive applications.
-
M&A and capability aggregation: Select players have broadened portfolios via bolt-on acquisitions that add sensorization, chemical dosing or complementary water-treatment technologies — a trend that accelerates integrated solution offerings in municipal and industrial wastewater accounts.
-
Service and processization: New process centers and expanded application labs are being opened to accelerate customer adoption through onsite trials, performance guarantees, and outcome-based contracting — blurring the line between equipment vendor and process partner.
-
Regional manufacturing and aftermarket emphasis: To address tariff dynamics and steel-cost headwinds, some manufacturers are doubling down on regionalization of assembly and parts distribution while expanding aftermarket teams to convert one-time sales into recurring revenue streams.
Representative players illustrate these dynamics. Major incumbents are refreshing portfolios with high-speed and hermetic designs optimized for biotech and alternative-protein processing. Others are expanding sensors and digital monitoring capabilities through targeted acquisitions, while specialist manufacturers continue to win by offering tailored solutions and strong service networks. This mix creates both consolidation opportunities and niches for well-positioned challengers.
Cost, supply chain, and regulatory dynamics that will drive 2026 priorities
-
Raw-material pressures: Steel and specialty alloy volatility is directly impacting equipment costs. Executives should assume persistent elevated input prices in near-term supplier negotiations and model procurement windows accordingly.
-
Trade and tariff risks: Continued elevated trade measures in key markets mean import-dependent sourcing exposes buyers to margin erosion. Nearshoring or regional assembly can be decisive hedges for contract competitiveness.
-
Serviceability and uptime: As process partners push for stricter SLAs in critical applications (pharma, waste treatment), investments in remote-monitoring, spare-part strategies, and predictive maintenance are becoming non-negotiable cost-avoidance levers.
Strategic playbook for 2026 — five actions for executives
-
Re-prioritize capex: Move from broad capacity builds to selective modernization of high-throughput and high-integrity assets. Use our TCO templates to identify retrofit opportunities that deliver faster payback with lower incremental risk.
-
Design to availability: Shift procurement evaluation from sticker price to availability and lifecycle cost. Shorten lead times by qualifying multiple regional suppliers and locking in critical components with staggered contracts.
-
Pursue service-led growth: Create bundled offers combining equipment, monitoring, and outcome-based maintenance. The path to recurring revenue now runs through performance guarantees and digital service delivery.
-
Hedge material exposure: Implement multi-year material contracts, strategic inventory buffers for critical alloys, and engineering reviews to substitute where life-cycle risk allows.
-
Use M&A tactically: Target acquisitions that add sensorization, process engineering expertise, or local footprint. Smaller-scale deals that bring application know-how often yield quicker returns than broad transformative transactions.
How to use this analysis in 2026 planning cycles
-
Board-level capital allocation: Apply our scenario tools to test CapEx requests under three market trajectories (conservative, baseline, accelerated) and require breakpoints for retrofit vs. new-build investments.
-
Procurement scorecards: Replace traditional shortlists with our supplier scorecards that weight lifecycle cost, digital readiness, and regional manufacturing exposure to tariffs.
-
R&D and product roadmap: Prioritize designs that reduce material intensity, enable rapid serviceability, and integrate predictive diagnostics to capture aftermarket margins.
What we are intentionally holding back — and why
In this preview we have focused on the strategic implications and actionable playbook that will matter to decision-makers in 2026. To preserve the value of the full study as a strategic asset, detailed segmentation tables, granular regional and application splits, and vendor-by-vendor revenue benchmarks are reserved for the full report and the interactive data portal. These granular datasets power procurement shortlists, investment memos, and M&A valuations — and are provided in the complete package so practitioners can run vendor selection and deal due diligence with primary-source rigor.
Next steps
For leaders preparing budgets and strategy for 2026, PW Consulting’s full Industrial Centrifuge Machines Market report converts the directional intelligence presented here into executable tactics: calibrated investment timing, supplier negotiation templates, and prioritized M&A targets. Contact our industry team to access the full dataset, the customizable TCO models, and a tailored briefing that maps our insights to your business objectives.
For detailed analysis of this topic, please visit the official page: Industrial Centrifuge Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Handheld Devices Command 58.41% of Portable Keratometer Market as Industry Eyes 6.75% CAGR Through 2032
By pmarketresearch, 2026-07-06
Portable Keratometer Market: Strategic Imperatives for 2026 — PW Consulting Release
PW Consulting today publishes a strategic preview of our latest Portable Keratometer Market study, designed for C-suite decision makers, corporate strategy teams, product leaders and investors who need an evidence-led playbook for 2026. Grounded in a rigorous historical review (2020–2025) and a seven-year forecast (2026–2032), the report synthesizes commercial, clinical and regulatory dynamics that will determine winners in an evolving portable ophthalmic diagnostics ecosystem.
Portable Keratometer Market
Why this report matters for 2026 planning
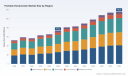
Portable keratometers have moved from niche field tools to core assets within hybrid eye-care delivery models — from outreach missions and mobile clinics to integrated point-of-care workflows in ambulatory surgery centers. Our analysis shows a resilient market that expanded through 2025, reaching an estimated market size of USD 73.15 Million in the base year, and is projected to continue expanding at a steady compound annual growth rate of approximately 6.75% over the forecast period. Underlying that headline growth is a mix of accelerating adoption in non-traditional care settings, incremental product innovation (miniaturization, sensor fusion, and app-based analytics), and tighter integration with biometry and refractive platforms.
Portable Keratometer Market
For executives preparing 2026 budgets and three- to five-year roadmaps, the practical implications are clear: invest selectively in portable keratometry if your strategy depends on mobility, cost-optimized refractive screening, or bundle offerings around mobile surgical services. However, the financial upside is best realized by pairing device capability with service models — training, tele-interpretation, and deployment logistics — rather than relying solely on unit sales.
Portable Keratometer Market
What the report delivers — actionable, decision-focused content
- Market sizing and trend narrative: A reconciled historical dataset (2020–2025) and scenario-based forecasts to 2032 that reflect demand elasticity under differing adoption and reimbursement assumptions.
- Go-to-market playbooks: Practical routes to scale in low-resource and premium settings, including channel mix, pricing approaches, and partnership architectures that reduce time-to-adoption.
- Product and technology roadmap guidance: Comparative evaluation of key design trade-offs (handheld ergonomics vs. tabletop-dock versatility; sensor accuracy vs. throughput; local processing vs. cloud analytics) to inform R&D prioritization and M&A screening.
- Regulatory and standards checklist: Mileposts for 510(k) strategies, EU MDR conformity, and ISO standards compliance to avoid time-consuming rework during product commercialization.
- Procurement model templates: Cost-of-ownership frameworks tailored for hospital buyers, NGO procurement teams, and mobile clinic operators — including sample KPIs for uptime, calibration cadence, and operator training requirements.
- Risk heatmaps and mitigation strategies: Operational, regulatory and competitive risks prioritized by likelihood and impact, with recommended mitigations that can be executed within six to 18 months.
The report is deliberately structured to be operational from day one — with executive checklists, an investment decision matrix, and templated vendor evaluation criteria. To preserve strategic value for paying subscribers, detailed segment-by-segment revenue tables and unit-level pricing schedules are available in the full report.
Competitive landscape — concentration and strategic profiles
The portable keratometer market exhibits moderate concentration: the top three vendors account for a meaningful share of the market, and the top five consolidate an even larger portion of available revenues. This concentration presents both risks and opportunities. Established suppliers benefit from brand trust and distribution scale, while agile entrants can capture share by addressing unserved niches — particularly in mobile outreach and low-cost screening.
- Micro Medical Devices (United States) — Micro Medical Devices has positioned its PalmScan PRO and K2000 portable keratometer probe as a field-deployable solution tightly integrated with biometry systems. Their recent mission deployments demonstrate the commercial and reputational benefits of proving devices in real-world outreach programs. Website: https://micromedinc.com/
- PlenOptika (United States) — PlenOptika’s QuickSee Free Pro leverages wavefront aberrometry to deliver clinical-grade refraction and keratometry in a handheld form factor. The company’s platform emphasis is on software and mobile integration; a mid-2025 app update underscores the competitive importance of a robust companion software ecosystem. Website: https://plenoptika.com/
- NIDEK (Japan) — NIDEK’s HandyRef-K demonstrates how incumbent ophthalmic OEMs are adapting core technologies for portable use, addressing both clinic overflow and supine/mobile patient workflows. Website: https://www.nidek-intl.com/
- Marco (United States) — Marco competes with portable ARK devices intended for anytime/anywhere refraction and keratometry, leveraging service networks to support clinicians. Website: https://marco.com/
- Devine Meditech (India) — Focused on cost-effective handheld auto-keratometers, Devine Meditech is an example of regional players filling affordability gaps, especially in emerging markets. Website: https://devinemeditech.com/
- Reichert (AMETEK) (United States) — Reichert offers portable-capable keratometry within a broader ophthalmic diagnostics portfolio, an approach that supports cross-selling into existing installed bases. Website: https://www.reichert.com/
- Huvitz (South Korea) — Huvitz brings portable-compatible ref/keratometers to market, emphasizing ergonomic design and compatibility across refraction workflows. Website: https://www.huvitz.com/
Recent vendor activity highlights how competition is shifting from hardware-only differentiation to software-enabled clinical workflows and field validation. Notable examples include PlenOptika’s February 2025 companion app upgrade and Micro Medical Devices’ documented mission deployment in late 2025. These moves signal that clinical integration and proof-of-field efficacy are decisive purchase triggers.
Regulatory, standards and reimbursement dynamics
Understanding the regulatory and standards environment is critical to getting to market quickly and sustaining commercial traction. Key considerations covered in the report include:
- Regulatory classification: In the United States, auto-keratometers are regulated as Class II devices under FDA 21 CFR Part 886.1500 and typically require 510(k) premarket notification. This drives specific evidence requirements around performance and equivalence.
- European market access: Devices fall under EU MDR 2017/745 classifications that necessitate conformity assessment and ongoing post-market surveillance — a material cost and timeline factor for international launches.
- Standards compliance: ISO 15004-1:2020 establishes test methods and fundamental requirements for non-invasive ophthalmic instruments; alignment with recognized consensus standards can streamline regulatory submissions and reduce review risk.
The report includes a practical timeline for regulatory filings, a prioritized list of performance tests to commission (bench and clinical), and templates for post-market surveillance plans that meet MDR expectations while minimizing surveillance overhead.
Strategic takeaways for 2026 decision cycles
- Prioritize integration over replacement: Buyers increasingly favor keratometers that integrate with biometry and refraction ecosystems. Providers should demonstrate interoperability and data portability as primary value drivers.
- Segment go-to-market by use-case economics: High-throughput ambulatory centers have different payback horizons than mission-driven NGOs or primary-care screening programs. Tailor commercial models — service bundles, device-as-a-service, and volume discounts — to the economics of each buyer segment.
- Invest in software and clinical evidence: App ecosystems, cloud analytics and validated clinical workflows yield disproportionate returns versus marginal hardware improvements. Clinical validation in target use environments (e.g., supine, low-light, pediatric) is a competitive moat.
- Plan regulatory pathways early: For entrants eyeing international scale, prepare parallel regulatory strategies and designate engineering resources to meet MDR and ISO requirements to avoid staggered launches.
- Use procurement KPIs to win long-term contracts: Vendors that commit to measurable uptime, calibration turn-around, and operator training can shorten procurement cycles and secure bundled service contracts.
How to use this preview — and where to find the full intelligence
This release is a strategic preview intended to help leadership teams prioritize initiatives for 2026. PW Consulting’s full Portable Keratometer Market report contains the granular segmentation tables, scenario-model outputs, vendor benchmarking matrices and downloadable procurement templates that buyers and investors rely on when committing capital or entering partnerships.
If your 2026 strategy depends on portable keratometry — whether to scale mobile eye-care programs, defend share in ambulatory settings, or evaluate acquisition candidates — the full report equips you with the data and executable frameworks needed to act confidently. Detailed segment revenue breakdowns, unit economics, and modeled sensitivity analyses are available in the complete study.
To request an executive briefing or access the full report, please contact your PW Consulting account representative or visit our website for subscription options and licensing details.
For detailed analysis of this topic, please visit the official page: Portable Keratometer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Superconducting Magnetometer Market Forecast (2026–2032) — Set to Reach USD 40.68 Million by 2032, Growing at a 7.7% CAGR
By pmarketresearch, 2026-07-06
Superconducting Magnetometer Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting’s latest industry briefing previews our full Superconducting Magnetometer Market research report, offering senior executives a forward-looking playbook to inform decisions across product strategy, customer segmentation, and capital allocation in 2026. This preview explains why the market’s trajectory — and the structural forces behind it — make next-year planning a watershed moment for vendors, integrators, and strategic investors. For reasons of competitive sensitivity we deliberately withhold detailed regional and application-level splits in this release; the full dataset and growth scenarios are available in the complete report.
Superconducting Magnetometer Market
Market trajectory at a glance
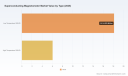
The superconducting magnetometer market has experienced steady expansion through the early 2020s and is projected to continue on a healthy growth path over the 2026–2032 forecast window. Using 2025 as our base year, PW Consulting’s model projects the market will grow from USD 24.2 Million (revenue unit: Million USD) to approximately USD 40.68 Million by 2032, reflecting a compound annual growth rate (CAGR) of 7.7% over the forecast period. This growth is supported by converging demand drivers in research, industrial sensing, and exploration, alongside selective policy tailwinds for quantum-technology adoption.
Superconducting Magnetometer Market
Why 2026 matters: three strategic inflection points
-
Technology convergence: Cryogenics, HTS material advances, and compact readout electronics are lowering system-level barriers for differentiated, application-specific magnetometer products. Vendors that translate subsystem innovations into reliable, serviceable systems will be positioned to capture disproportionate value in 2026–2028.
Superconducting Magnetometer Market -
Market structure and competitive dynamics: The market displays moderate concentration — PW Consulting’s competitive analysis shows a top-three concentration that approaches mid‑range levels and a top‑five concentration that indicates a clear leader cohort. This structure creates room for agile challengers with specialized product offerings (portable systems, integrated sensors) while preserving premium margins for incumbents that can offer integrated service and lifecycle guarantees.
-
Policy and funding inflection: Public funding programs and industrial modernization incentives (notably multi‑billion euro commitments in European quantum programs and targeted national incentives in North America) are accelerating institutional purchases for advanced sensing and quantum-enabled measurement platforms. Vendors that map these public funding cycles into targeted sales pipelines will gain a measurable first-mover advantage.
Report practicalities — what PW Consulting delivers
Our full report is built for executives who must convert market insight into operational plans in 2026. Deliverables include:
-
Market sizing and scenario models (historical 2020–2025; forecast 2026–2032) with baseline, upside, and downside scenarios reflecting supply shocks, policy acceleration, and adoption curves.
-
Vendor benchmarking and value‑chain maps: product portfolios, core component suppliers, margin pools, and service opportunities.
-
Technology heatmaps assessing Low‑Temperature (LTS) and High‑Temperature (HTS) SQUID developments, readout electronics, and system integration tradeoffs for differing applications.
-
Commercial playbooks: go‑to‑market segmentation, channel strategies, pricing sensitivity analyses, and tender play templates for institutional and industrial buyers.
-
Supply‑chain risk register, including materials, labor skills, and manufacturing scalability assessments with mitigation actions and cost impact estimates.
-
M&A and partnership diagnostics: transaction targets, valuation heuristics, and integration checklists tailored to strategic buyers and private equity.
Competitive landscape — who matters and why
The vendor field combines established precision-instrument firms, niche specialist sensor builders, and systems integrators. PW Consulting’s qualitative and quantitative work highlights several strategic archetypes:
-
Full-system incumbents — firms that pair magnetically shielded measurement platforms with superconducting magnets and multi‑mode measurement capability. These players retain strong institutional relationships with research labs and advanced industrial customers due to proven reliability and integrated service offerings.
-
Sensor and electronics specialists — companies focusing on low‑noise SQUID sensors and readout electronics, enabling third‑party system builders to compress product development timelines and differentiate on portability and cost.
-
Application-focused innovators — small, nimble companies delivering fit‑for‑purpose solutions for field exploration, portable diagnostics, and modular research instruments. These firms accelerate market penetration where compactness and ease of deployment are decisive.
Representative companies we profile in the full report include established names and specialized innovators. For example:
-
Quantum Design Inc. (San Diego, USA) — known for high‑sensitivity magnetometer systems that support multiple measurement modes and high‑field capabilities, positioning the firm strongly in laboratory and materials R&D use cases.
-
STAR Cryoelectronics LLC (Santa Fe, USA) — a supplier of both LTS and HTS SQUID sensors and integrated readout electronics, serving research and applied geophysics markets.
-
Tristan Technologies Inc. (San Diego, USA) — a specialist in custom systems for rock magnetometry and geophysical exploration with practical liquid‑nitrogen cooled HTS offerings.
-
Supracon AG (Jena, Germany) — active in geophysical surveys and quantum sensing; recent deployments with exploration partners demonstrate commercialization pathways for ultrasensitive sensors.
-
Cryogenic Limited (London, UK) and Magnicon GmbH (Hamburg, Germany) — companies focused on integrating superconducting magnets with cryogen‑free systems and low‑noise electronics respectively, enabling broader application adoption.
-
ez SQUID (Netherlands) — an emerging entrant delivering compact SQUID sensors for portable applications, a trend that accelerates field deployment and lowers entry friction for new buyers.
Recent vendor activity we analyze includes product launches and partnership deployments that validate both technological readiness and market demand (for instance, compact sensor lines introduced by agile entrants and deployment partnerships for mineral exploration). PW Consulting’s vendor heatmap identifies which firms are investing in modular platforms, which are prioritizing high‑field laboratory systems, and which are pursuing channel partnerships to access industrial users.
Opportunities, risks and operational levers
-
Opportunities: Rising demand for precision magnetic sensing across medical imaging research, geophysical exploration, and quantum R&D creates differentiated niches for premium and portable offerings. Vendors with aftermarket service, remote diagnostics, and modular upgrade paths can expand lifetime value per system.
-
Risks: Input cost pressure from specialized superconducting materials and a constrained pool of cryogenics expertise create supply-side bottlenecks. Regulatory and standards uncertainty in new application domains can slow procurement cycles for system-level buyers.
-
Operational levers: Near-term moves that materially change 2026 outcomes include: securing long‑lead material contracts, investing in remote calibration and service infrastructure, and aligning product roadmaps to public funding cycles that finance institutional procurement.
Policy and ecosystem nudges
Policy accelerators are nontrivial. Public funding initiatives targeting quantum technologies, notably significant allocations in European programs, are indirectly subsidizing adoption of SQUID‑based systems in research and strategic industrial projects. Complementary incentives under North American modernization and energy‑storage policies are also creating procurement pockets for superconducting technologies. PW Consulting models multiple policy uptake scenarios to help clients prioritize market entry and partnership timing.
2026 decision checklist — five recommended actions
-
Prioritize product roadmaps that reduce total cost of ownership (serviceability, cryogen‑free operation, modular upgrades).
-
Lock early supply agreements for specialty superconducting materials and critical readout components to avoid margin erosion from spot shortages.
-
Build go‑to‑market plays aligned with institutional funding cycles and proof‑of‑value deployments in prioritized verticals (research labs, exploration, industrial sensing).
-
Evaluate bolt‑on M&A targets that complement core strengths — e.g., sensor electronics firms for incumbents, or systems integrators for smaller technology players seeking scale.
-
Invest in service capabilities and remote diagnostics to de‑risk field deployments and capture aftermarket revenue.
Conclusion — where PW Consulting adds strategic value
Our analysis shows a market that is both growing and maturing: structurally attractive for firms that can combine deep technical capability with pragmatic commercial execution. PW Consulting’s full report translates the headline CAGR and market trajectory into executable initiatives — from procurement and supply‑chain playbooks to M&A heatmaps and pricing battlegrounds — enabling clients to convert 2026 choices into multi‑year competitive advantage.
To access the full dataset, granular segmentation, and the vendor scorecards that we intentionally omitted from this preview, please consult the complete Superconducting Magnetometer Market report on the PW Consulting website. The full report contains the granular regional and application breakdowns, detailed financial modeling (Million USD unit), and step‑by‑step implementation playbooks tailored for 2026 action.
For detailed analysis of this topic, please visit the official page: Superconducting Magnetometer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Automatic Spray Guns Market to Grow at 5.85% CAGR — From USD 1,025.6 Million in 2025 to USD 1,527.35 Million by 2032, Led by HVLP and Europe
By pmarketresearch, 2026-07-06
Automotive Automatic Spray Guns Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive summary
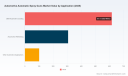
As original equipment manufacturers, refinishers, system integrators and Tier‑1 suppliers prepare their 2026 capital plans, the Automotive Automatic Spray Guns market presents a clear but nuanced growth story. Our latest PW Consulting market study establishes that the market reached USD 1,025.6 Million (base year 2025) and is forecast to expand at a compound annual growth rate (CAGR) of 5.85% over the 2026–2032 horizon, exceeding the USD 1.5 Billion threshold by the end of the forecast period. That topline momentum is being driven by regulatory tightening, increased adoption of high‑transfer technologies, and intensifying automation in vehicle paint shops — but the path forward is punctuated by supply‑side constraints, material cost pressure and a selectively consolidating competitive landscape.
Automotive Automatic Spray Guns Market
Why this report matters for 2026 corporate decisions
-
Timing of investment: manufacturers face a narrow window to commit to automation and electrostatic solutions aligned with phased VOC and NESHAP compliance deadlines through 2028. The report translates regulatory timelines into purchase and retrofit milestones so procurement and plant engineering teams can de‑risk capex.
Automotive Automatic Spray Guns Market -
Procurement and supplier strategy: escalating nozzle and component alloy costs are squeezing margins on premium guns. Our analysis provides procurement playbooks to balance price, service levels and technology upgrades — providing concrete levers to protect EBITDA while upgrading performance.
Automotive Automatic Spray Guns Market -
M&A and partnership prioritization: with a moderate level of market concentration (CR3 ≈ 38.5%, CR5 ≈ 52.7%), strategic buyers and investors must identify targets offering technological complementarity or channel access rather than volume alone. The report highlights the types of assets most likely to unlock near‑term synergies.
-
Operational readiness: systems integrators and OEM paint shops can use the report’s scenario models to plan robot cell redesigns and paint line sequencing to maximize transfer efficiency and throughput without excessive paint waste.
Market trajectory and growth drivers
The mechanical and regulatory drivers are reinforcing one another. On the demand side, vehicle electrification and changing body architectures are altering paint system footprints and increasing the premium on transfer efficiency and atomization control. On the regulatory side, requirements such as EPA NESHAP 6H, South Coast AQMD Rule 1151 and the EU VOC Directive are accelerating shifts toward HVLP‑equivalent and electrostatic technologies in both OEM and refinishing channels. Supply dynamics are equally important: higher stainless steel and specialty alloy costs for critical nozzle components are influencing manufacturer pricing, design decisions and aftermarket strategies.
These forces underpin the mid‑single‑digit CAGR we project through 2032 — steady growth, but concentrated around technology transitions, replacement cycles and regulatory compliance windows rather than a uniform expansion across all product tiers.
Competitive landscape — what to watch in 2026
-
Graco Inc. (Minneapolis, USA) — Strengths: broad product portfolio that spans high‑transfer electrostatic and robotic integration; reputation for durability and service. Strategic implication: Graco’s emphasis on robotic compatibility makes it a natural incumbent for greenfield automotive lines and for OEMs upgrading automation standards.
-
SATA GmbH & Co. KG (Kornwestheim, Germany) — Strengths: precision atomization and ergonomic design; strong presence in vehicle manufacturing and refinish arenas. Strategic implication: SATA’s premium positioning and recent product previews signal opportunities for refinisher networks and premium OEM tiers seeking consistency and finish quality.
-
Anest Iwata (Yokohama, Japan) — Strengths: advanced atomization tech and continual product refresh (e.g., 2026 catalogue rollouts). Strategic implication: buyers focused on finish fidelity and consistent color matching should consider Anest Iwata in supplier evaluations, especially where cross‑line standardization matters.
-
Nordson Corporation (Westlake, USA) — Strengths: electrostatic and powder coating systems optimized for high‑volume lines. Strategic implication: where throughput and material savings are prioritized, Nordson’s systems provide scalable solutions; consider total cost of ownership (TCO) models that capture material savings over multiple years.
-
EXEL Industries / Sames (Épernay, France) — Strengths: diversified technology mix (Airspray, Airmix, electrostatic) and assembly‑line experience. Strategic implication: strong candidate for integrators seeking an array of technologies under a single vendor umbrella, facilitating lifecycle support and spare parts commonality.
-
Carlisle Fluid Technologies (DeVilbiss, Binks) (Scottsdale, USA) — Strengths: legacy brands focused on transfer efficiency and industrial finishes. Strategic implication: attractive for aftermarket service contracts and for plants balancing cost and performance with established supplier relationships.
-
Selected Chinese OEMs (e.g., Ningbo Lis, Zhejiang Rongpeng) — Strengths: cost‑competitive, customizable offerings. Strategic implication: strong contenders in volume retrofit projects and price‑sensitive markets; quality and long‑term service support should be validated in pilot deployments prior to large rollouts.
Recent market moves underscore these trends: a 2026 educational partnership with a major technical training institute, product previews from legacy premium vendors and refreshed catalogs from established Japanese manufacturers all point to simultaneous demand for training, premiumization and product renewal. These are signals that the market is not only growing, but also maturing in procurement complexity.
Report contents — practical tools inside
This is not a high‑level narrative. PW Consulting’s report is operationally focused and designed for immediate use by procurement, engineering, product and strategy teams. Key deliverables include:
-
A decision matrix aligning technology choices (HVLP, airless, electrostatic) with plant objectives: yield, throughput, regulatory compliance and TCO.
-
Investment timing playbooks that map regulatory deadlines and replacement cycles to capex windows and pilot program schedules.
-
Supplier scorecards and negotiation scripts — assessing service coverage, spare parts lead times, retrofit compatibility and aftermarket economics.
-
Scenario financial models (best case / mid / downside) to stress‑test ROI for line upgrades, including sensitivity to raw‑material cost inflation and labor rates.
-
Implementation checklists for automation integrators covering robot head compatibility, control protocols and paint booth ergonomics.
-
Compliance and risk register that translates regulatory language into plant‑level obligations and audit readiness steps.
Strategic playbook for 2026
-
Prioritize regulatory alignment: convert compliance deadlines into actionable retrofit or replacement milestones. Early pilots on electrostatic/HVLP solutions reduce rework and avoid last‑minute premium procurement.
-
Hedge material cost pressure: renegotiate multi‑year contracts with nozzle and component suppliers; evaluate alternative alloys and surface treatments that preserve performance at lower cost.
-
Build selective redundancy: given the market’s mid‑level concentration, cultivate primary and secondary suppliers to avoid single‑source risk for critical spare parts and robot interfaces.
-
Leverage TCO, not sticker price: capture savings from reduced paint consumption and improved throughput in procurement evaluations. Our TCO templates show how small efficiency gains compound over typical equipment lifecycles.
-
Invest in workforce upskilling: partnerships between vendors and technical institutes (as seen in recent industry announcements) are becoming a differentiator — integrate training clauses into supplier contracts.
-
Monitor consolidation opportunities: given CR3/CR5 dynamics, M&A targets that close functional gaps (robotic software, nozzle tech, local service networks) deliver greater value than pure volume plays.
How to use the PW Consulting study in practice
We recommend a three‑step adoption plan for 2026:
-
Phase 1 — Rapid diagnostic (30 days): use our supplier scorecards and regulatory checklists to triage immediate compliance and spare‑parts vulnerabilities across your plants.
-
Phase 2 — Pilot and validate (3–9 months): deploy a pilot cell using recommended technologies and run TCO scenarios against baseline operations, incorporating paint savings and labor impacts.
-
Phase 3 — Scale and contract (9–24 months): negotiate framework agreements with primary and secondary suppliers, lock in pricing collars for critical components, and roll out upgrades aligned with planned production downtime.
Conclusion — the strategic payoff
For companies facing 2026 budget cycles, the choice is not simply which spray gun to buy — it is about orchestrating technology, procurement, compliance and operations to deliver measurable margin improvement and regulatory resilience. With the market at USD 1,025.6 Million in 2025 and a clear growth path (5.85% CAGR to 2032), the opportunity cost of delayed action is real: missed paint savings, compressed lifecycles and exposure to regulatory penalties. PW Consulting’s Automotive Automatic Spray Guns Market study is structured to convert market intelligence into executable steps — a concise playbook that turns regulatory pressure and material headwinds into competitive advantage.
Contact PW Consulting for access to the full report, proprietary models and a tailored briefing for your organization’s 2026 strategy session.
For detailed analysis of this topic, please visit the official page: Automotive Automatic Spray Guns Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Refrigerated Food Vending Machine Market Set to Expand at a 7.5% CAGR, Revolutionizing On‑the‑Go Fresh Food Retail
By pmarketresearch, 2026-07-06
Refrigerated Food Vending Machine Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
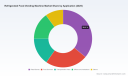
As organizations plan capital allocation and go-to-market moves for 2026, the refrigerated food vending machine market presents a window of accelerated opportunity and regulatory-driven disruption. Our new PW Consulting market study shows the industry growing from an estimated USD 6.9 billion in 2025 at a compound annual growth rate of 7.5% through the 2026–2032 forecast horizon, reaching roughly USD 11.45 billion by 2032. These headline metrics underline a robust demand trajectory—but behind the aggregate figures sits a set of operational, regulatory and technological inflection points that will determine winners and losers over the next 18–36 months.
Refrigerated Food Vending Machine Market
Why 2026 Is a Pivotal Year for Buyers and Providers
-
Regulatory dead zones and compliance cliffs are creating mandatory reset points for fleets. In North America, the EPA AIM Act’s phase-out schedule for high‑GWP refrigerants culminates in sales restrictions that came into force for manufacturers/importers and for most machine sales as of early 2026. In parallel, European energy labeling and performance standards are raising the bar on permissible energy consumption and mechanical efficiency. The practical effect is twofold: legacy machines using non‑compliant refrigerants or poor energy performance will face enforced retirement or costly retrofit, and buyers who delay will confront compressed supplier capacity as operators accelerate fleet refreshes.
Refrigerated Food Vending Machine Market -
Convergence of smart hardware and services is accelerating adoption. Smart vending coolers, RFID‑enabled inventory tracking, AI‑assisted merchandising and integrated micro‑market solutions showcased at trade events in 2026 are redefining uptime economics and the operator value proposition. Early adopters are already demonstrating higher fill efficiencies, lower shrink and improved average ticket via personalization and real‑time assortment optimization.
Refrigerated Food Vending Machine Market -
Supply chain and material dynamics matter. Structural components remain dominated by steel in food vending construction due to durability and thermal performance—an important input constraint for procurement and lifecycle costing.
What the PW Consulting Report Delivers (Practical, Execution‑Oriented)
Our full study is designed as an operational playbook for buyers, OEMs, investors and foodservice chains evaluating refrigerated vending strategies in 2026. Key deliverables include:
-
Proven market sizing and forecast methodology with scenario sensitivity to refrigerant regulation timelines, energy regulation adoption and macro demand drivers.
-
Demand‑driver analysis and adoption curves for smart features (telemetry, RFID, AI merchandising), with use‑case payback models that let you stress‑test assumptions by site type and footfall profile.
-
Regulatory compliance playbook: a step‑by‑step checklist for retrofits vs. replacement, procurement language for refrigerant compliance, and energy label testing protocols aligned to current EU and U.S. standards.
-
Competitive benchmarking and vendor scorecards covering refrigeration technology, service models, software ecosystem, reliability data and commercial terms—built to inform RFPs and supplier selection.
-
Operational toolkits for operators: deployment planning templates, KPI dashboards, maintenance SOWs, spare‑parts strategies and capex/opex optimization guidance.
-
Commercial playbooks for manufacturers and channel partners: product roadmaps, aftermarket services strategies, subscription and leasing models, and prioritized feature investments by ROI impact.
-
Case studies and build‑to‑bench ROI calculators for pilots in four archetypal channel environments—retail, transportation hubs, foodservice and workplace—so executives can size pilots and scale with confidence.
Competitive Landscape: Who’s Moving the Needle
The vendor field combines legacy vending OEMs and nimble systems integrators. Market concentration is moderate—the top three companies account for less than one‑third of market revenue while the top five capture a bit over two‑fifths—indicating substantial room for regional leaders, technology specialists and new entrants to gain share through differentiation and aggressive go‑to‑market moves.
-
Established OEMs with integrated cold‑chain expertise are leveraging brand reliability and distribution reach to protect installed base economics. Their strengths lie in proven refrigeration platforms, nationwide service networks and scale procurement for components and compressors. These providers are prioritizing compliance upgrades and energy efficiency improvements to secure renewal contracts and large channel partnerships.
-
Technology‑first entrants and systems integrators are attacking value streams above the cabinet—software, telemetry, inventory automation and consumer experience. RFID‑enabled smart fridges and AI merchandising systems are being piloted and deployed in high‑visibility sites; these platforms reduce labor cost per sale and enable dynamic assortment decisions that measurably lift per‑site revenue.
-
Regional manufacturers—particularly those from high‑volume production centers—are competing on price, modularity and adjustable cooling ranges to serve emerging markets and non‑traditional placement opportunities. Their product portfolios often include flexible temperature zones and touchscreen UX that appeal to operators seeking low‑cost reliability.
-
Recent market signals: RFID smart‑fridge deployments by innovators in 2025–2026 and broad exposure of AI‑enabled refrigerated coolers at trade events indicate the next wave of differentiation will be software‑centric offerings backed by service contracts rather than pure hardware sales.
Technology, Regulation and Cost Dynamics: What Keeps CFOs Awake
-
Refrigerant transition is a capital‑intensive pivot. Moving from high‑GWP HFCs to compliant low‑GWP alternatives (or to alternative refrigeration architectures) affects BOM cost, reliability profiles and maintenance skillsets. Procurement teams must model retrofit vs. replacement under multiple regulatory scenarios to avoid stranded assets.
-
Energy efficiency is now a sales and operating cost driver. Energy labeling regimes will increasingly influence procurement decisions and operator economics—machines with superior energy ratings command lower lifetime operating costs and easier approvals for placement in regulated facilities.
-
Connected features change the monetization math. Telemetry, inventory sensors and data aggregation allow operators to reduce replenishment frequency, lower shrink and test price/assortment strategies fast. Software monetization (SaaS and data services) is emerging as a high‑margin aftermarket stream for OEMs and platform providers.
-
Materials and supply chain: the prevalence of steel in structural components drives procurement exposure to commodity cycles; smart hedging and multi‑source strategies are practical levers for cost certainty.
Commercial Models and Route‑to‑Scale
Successful scaling patterns are converging on a few repeatable models:
-
Lease + Managed Services: lowers client upfront cost and creates recurring revenue for providers while aligning incentives on uptime and fill performance.
-
Platform + Marketplace: combining refrigeration hardware with proprietary merchandising algorithms and content/display partnerships to increase average transaction value.
-
Micro‑market integration: blending unattended refrigerated cabinets into larger micro‑retail ecosystems—this increases basket size and extends revenue per square foot for landlords and operators.
Top Strategic Recommendations for 2026 Decision‑Makers
-
Prioritize compliance and energy performance in shortlists. Regulatory non‑compliance now has defined cut‑off dates; prioritize suppliers with validated low‑GWP refrigerant solutions and strong energy labeling performance.
-
Design pilots to validate commercial software ROI first. Test telemetry, dynamic assortment and price sensitivity in a small number of high‑quality sites before committing to a national roll‑out.
-
Move from transactional procurement to partnership contracts. Seek supplier terms that bundle hardware, software upgrades and parts exchange to protect against technology obsolescence and refrigerant transitions.
-
Diversify component sourcing and hedge steel exposure. Locking favorable terms with multiple compress or cabinet suppliers reduces the risk of price spikes and lead‑time shocks.
-
Plan for M&A and consolidation options. Moderate market concentration suggests buy‑and‑build strategies can unlock scale advantages—keep deal teams active and model bolt‑on economics for adjacent services such as telemetry platforms and managed operations.
How to Use the Full Report
This press brief highlights the strategic contours and immediate action levers for 2026, but it is intentionally a teaser. The full PW Consulting Refrigerated Food Vending Machine Market report provides the granular competitive scorecards, channel‑level demand curves, RFP templates, scenario P&L models and vendor‑by‑feature matrices required to execute with confidence. For operators and manufacturers preparing capex and product roadmaps in 2026, those detailed data and decision tools shorten the timeline from strategy to profitable execution.
To obtain the complete set of operational templates, vendor benchmarks, and site‑level ROI calculators—plus our consultants’ recommended implementation sequences—please consult the PW Consulting report download page. The full analysis contains the confidential split‑level intelligence and deployment playbooks that support fast, low‑risk scaling decisions.
About the Author
Prepared by PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, this brief synthesizes primary market research, vendor interviews and regulatory analysis completed through mid‑2026. Our advisory practice helps clients convert market insight into executable programs that reduce risk and accelerate value capture in capital‑intensive equipment markets.
For detailed analysis of this topic, please visit the official page: Refrigerated Food Vending Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aircraft Composite Enclosures Market to Expand at a 7.12% CAGR Through 2032
By pmarketresearch, 2026-07-06
Aircraft Composite Enclosures Market: Strategic Imperatives for 2026 — A PW Consulting Perspective
As aerospace platforms continue to push the envelope on weight reduction, electromagnetic compatibility, and packaging density, composite enclosures for aircraft electronics have shifted from niche innovation to core systems enabler. PW Consulting’s latest market study—anchored on a 2025 base year and a 2026–2032 forecast horizon—shows the global aircraft composite enclosures market expanding at a compound annual growth rate (CAGR) of 7.12%. The market has accelerated from an early-decade base to a materially larger addressable pool by 2025, and our modeling anticipates continued momentum through 2032.
Aircraft Composite Enclosures Market
Why 2026 Is a Pivotal Year for Decision‑Makers
2026 is the inflection point when several converging forces change the economic calculus for OEMs, tier‑one suppliers, and strategic investors. First, the technology-to-cost trajectory for carbon and advanced resin systems is reaching thresholds that make composites competitive not only on weight but on lifecycle cost. Second, supply‑side consolidation and long‑term feedstock agreements are maturing, reducing the volatility that has historically discouraged large-scale program transitions. Third, regulators and certification frameworks are clarifying allowable practices for composite structural and enclosure elements, which materially shortens time-to-certification for new designs.
Aircraft Composite Enclosures Market
- Momentum and scale: The market has grown substantially in the 2020–2025 period and is projected to continue appreciating through 2032, providing a runway for investment-backed growth strategies.
- De-risking through supply agreements: Recent long-term carbon fiber and resin agreements are reducing price and availability tail risks—an enabler for multi-year program commitments in 2026 and beyond.
- Regulatory clarity: Updated advisory guidance on composite design and testing reduces certification uncertainty, accelerating program schedules.
Report Highlights: Actionable Components for Executives
PW Consulting’s report is structured to support decision-making at three levels: strategic portfolio decisions, program-level execution, and procurement/supply‑chain optimization. Rather than a purely descriptive market taxonomy, the study delivers implementable tools and a playbook for 2026 priorities.
Aircraft Composite Enclosures Market
- Investment and portfolio diagnostics: A decision matrix that aligns product portfolios (e.g., enclosure design variants, material choices, integration complexity) with program types (commercial narrowbody, widebody, military, rotorcraft, and aftermarket/MRO).
- Commercial models and pricing sensitivity: A cost‑model framework that maps material, manufacturing, and certification cost drivers to bill-of-material outcomes—enabling “what‑if” scenario planning under varying raw material price paths and production volumes.
- Supplier scorecards and risk heatmaps: Objective evaluations of tier‑one and tier‑two suppliers across technology capability, certification track record, program capacity, and financial resilience—designed for sourcing and partnership decisions.
- Go‑to‑market playbook for OEMs and new entrants: Pre-validated pathways for co-development, licensing, captive manufacturing, or contract manufacturing strategies, including suggested KPIs and prototype-to-certification timelines.
- M&A and J‑V advisory filters: A prioritization framework for acquisition targets and joint-venture structures—aligned with synergies in materials, processing know‑how, and geographic access to final assembly lines.
- Regulatory and test program roadmap: End-to-end guidance for leveraging current advisory circulars and regulatory updates to shorten time-to-approval for enclosure designs.
Competitive Landscape: How the Leaders Are Positioning in 2026
The market demonstrates mid-to-high concentration among established aerospace suppliers, with a pronounced role for diversified electronics and systems integrators that combine materials expertise with certification and supply-chain capabilities. Across the competitive set we profiled, distinct strategies emerge:
- TE Connectivity (Switzerland, with major U.S. operations) is leveraging its strength in connector and shielding technology to offer composite enclosures that integrate high-performance EMI shielding and holistic cable-interconnect considerations. Their proposition centers on system-level weight reduction without sacrificing electromagnetic compatibility—appealing to avionics integrators seeking plug-and-play replacements for legacy metal housings.
- Collins Aerospace (United States) leverages deep platform relationships with airframers and defense primes to deploy advanced composite enclosures across both commercial and military programs. Their competitive edge is program intimacy—early involvement in system partitioning and packaging that locks in long-term derivatives and retrofit opportunities.
- Carlisle Interconnect Technologies (Amphenol CIT) (United States) combines interconnect expertise with composite enclosure manufacturing to address high-voltage and high-density power-electronics packaging. Their value proposition centers on electro-mechanical integration and qualification for demanding aerospace operating envelopes.
- GE Aerospace (United States) illustrates cross-domain technology transfer—applying composite enclosure expertise from marine gas turbines into naval and aerospace markets. Recent contracts demonstrate capability in shock and vibration qualification and serve as a springboard into defense platforms.
- Automated Dynamics (Trelleborg) and specialist composites firms (e.g., AIM Aerospace, RAMPF Group, Kaman/Vermont Composites) differentiate through customization and niche engineering for sensitive electronics, emphasizing dielectric and shielding performance alongside mechanical robustness.
For new entrants and component suppliers, the competitive lesson is clear: success requires either deep systems integration capabilities, privileged material supply, or a narrowly defensible technical niche. The market rewards integrated value propositions that reduce OEM integration risk.
Recent Developments That Matter to 2026 Strategy
- Supply-side agreements continue to reshape sourcing risk. A notable long-term carbon fiber supply agreement announced in early 2026 underscores industry efforts to stabilize feedstock availability—an important signal for firms budgeting multi‑year programs.
- Major program awards that include composite enclosure scopes demonstrate buyer confidence in composite solutions. High‑visibility contracts in adjacent domains (e.g., marine gas turbines with composite housings) validate crossover opportunities and the transferability of qualification data.
- Raw material price dynamics remain relevant. For example, epoxy resin pricing has seen notable near-term increases, creating short-term cost pressure for resin-intensive layups and low-volume programs. At the same time, aerospace-grade carbon fiber pricing varies across a broad band—making procurement strategy and long-term supply commitments decisive for unit economics.
- Regulatory guidance on composite structure design and testing continues to advance. Firms that align early with advisory frameworks and invest in shared test artifacts will shorten certification timelines and capture first-mover advantages on new platforms.
Strategic Recommendations — Practical Moves for 2026
2026 should be the year companies convert strategic intent into executable programs. PW Consulting recommends a coordinated set of actions across product, procurement, and partnership domains:
- Lock in feedstock through tiered contracts: Negotiate a mix of fixed-price and indexed contracts for carbon fiber and key resins to balance price predictability and upside flexibility. Prioritize suppliers with demonstrable commitment to aerospace-grade continuity.
- De-risk certification early: Invest in pre‑qualification test programs and cross‑platform data packages that can be reused across programs. Leverage advisory circulars and engage certification authorities in pilot programs to reduce surprises in full-scale certification routes.
- Integrate system-level design thinking: Move beyond component replacement to system co-optimization—combining enclosure design with thermal management, EMI control, and ease-of-installation to increase total system value capture.
- Pursue strategic partnerships: Consider J‑Vs with material suppliers or joint development agreements with avionics integrators to share development costs and secure preferential supply access.
- Prepare manufacturing scalability plans: For firms expecting volume, develop investment roadmaps that migrate from hand-layup prototyping to automated tape-lay and out-of-autoclave processes, with explicit ROI gates tied to orderbook milestones.
What PW Consulting’s Report Will Do for Your 2026 Plan
Our report is designed to be a working tool for leaders who must make tangible 2026 commitments—whether that is to include composite enclosures in an OEM’s next-generation platform, to greenlight capital spending for manufacturing upgrades, or to pursue M&A opportunities in the supplier base. It delivers the intelligence you need to:
- Quantify program-level economics under alternative material and volume scenarios;
- Prioritize suppliers and partnership targets with an evidence‑based scoring methodology;
- Map certification pathways and estimate realistic timeline and cost buffers;
- Define procurement hedging strategies that align with your risk appetite;
- Benchmark your capabilities against leading providers to identify capability gaps and targeted investments.
Conclusion — From Insight to Action
Composite enclosures are no longer a marginal choice; they are central to the next wave of avionics and systems packaging innovation. With the market growing at a mid-single-digit-plus CAGR and accelerating toward a larger addressable base over the next decade, 2026 is the moment to translate strategy into contracts, partnerships, and factory floors. PW Consulting’s report equips leaders with the scenarios, cost models, supplier intelligence, and certification roadmaps necessary to make those decisions with confidence—while preserving the full set of segmented market data and program-level analyses for stakeholders who require the detailed export package.
To access the full report, including proprietary segment-level models and the supplier scorecards, please visit the PW Consulting report portal or contact our advisory team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Aircraft Composite Enclosures Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Digital Inclinometer Market to Rise from USD 342.7 Million (Base Year 2025) to USD 525.58 Million by 2032 at 6.3% CAGR — Asia‑Pacific Leads with USD 122.54M, Construction the Top Application
By pmarketresearch, 2026-07-06
Digital Inclinometer Market 2026: Strategic Intelligence Brief — A PW Consulting Special Release
As infrastructure resilience, renewable energy deployment, and industrial automation accelerate into 2026, digital inclinometers have shifted from niche instrumentation to strategic enablers of operational safety and performance. PW Consulting’s latest market research on the Digital Inclinometer Market (base year 2025; forecast 2026–2032) synthesizes proprietary market-sizing, vendor benchmarking, technology deep dives, and scenario-based forecasting to deliver the one-page strategic blueprint enterprises need to prioritize investments and shape go-to-market strategies in 2026.
Digital Inclinometer Market
Market snapshot: validated growth and forward momentum
Our macro analysis confirms a sustained expansion in the global digital inclinometer market. After a period of steady historical growth from 2020 through 2025 — when the market reached approximately USD 342.7 Million (base year 2025) — the report’s forward-looking model projects continuation of this trajectory through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 6.3%. The PW Consulting model maps demand drivers tied to infrastructure monitoring, solar and renewable asset optimization, and the industrialization of sensor-enabled safety systems, producing a market value that rises materially by the end of the forecast period.
Digital Inclinometer Market
Two macro takeaways for 2026 decision-makers: (1) the market is large enough to support differentiated product and channel strategies while (2) adoption is driven more by systems-level value (reduced maintenance cost, risk mitigation, uptime) than by component-level price competition. Our concentration analysis reinforces this: market share is clustered among a handful of global and regional specialists, with mid-level concentration that still leaves space for focused challengers and adjacent-industry entrants.
Digital Inclinometer Market
What the PW Consulting report delivers — operational intelligence, not just data
- Robust market-sizing and demand-scenario modeling (base 2025; forecast 2026–2032) built from primary interviews, field sampling, and proprietary shipment-to-revenue translation models.
- Technology deep-dive comparing MEMS, optical, and force-balance architectures, including trade-offs for precision, power, form-factor, and total cost of ownership across typical industrial deployments.
- Vendor benchmarking and capability matrices covering product families, interfaces (serial, CAN, networked protocols), ruggedization, field calibration practices, and OEM/aftermarket positioning.
- Practical go-to-market playbooks for OEMs, channel partners, and service providers: pricing band guidelines, bundling options (sensor + cloud analytics), and specification checklists for procurement teams.
- Risk and compliance heatmaps addressing manufacturing quality, supply continuity, and certification readiness — including examples of ISO-driven manufacturing practices that matter to large infrastructure buyers.
- Field validation protocols and sample dashboard templates that shorten time-to-value for pilot projects and accelerated rollouts.
- An interactive financial model (delivered with the report) that allows executives to stress-test demand, margin, and investment scenarios for 2026 planning cycles.
Note: while this brief shares high-level market facts and strategic direction, the report contains granular regional and application-level segmentation, pricing benchmarking data, and vendor share-breakdowns that are available exclusively in the full publication.
Strategic implications for 2026 corporate decisions
- R&D prioritization: Invest in MEMS-based platforms for most mainstream industrial and infrastructure use cases where size, power, and cost deliver the best ROI. Reserve force-balance and optical solutions for ultra-high-precision or mission-critical geotechnical monitoring where lifetime performance outweighs unit cost.
- Productization and system offers: Move up the value chain with sensor-to-analytics bundles. Customers increasingly buy outcomes (reduced downtime, predictive maintenance alerts, compliance reporting) rather than raw sensor units.
- Channel and partnership strategy: Build strategic partnerships with system integrators and asset managers who control specification in brownfield and greenfield projects. For OEMs, modular tilt-sensor OEM kits with standardized digital interfaces reduce time-to-integration.
- M&A and investment screening: Prioritize targets that offer unique system integrations, firmware differentiation (on-device edge processing), or certificated quality systems that lower procurement friction for public-sector infrastructure projects.
- Supply-chain resilience: Seek suppliers with quality certifications and diversified component sourcing; certification continuity is increasingly a procurement gate for infrastructure contracts.
Competitive landscape — who matters now and why
The market’s supplier ecosystem is a mix of specialist sensor manufacturers, industrial OEMs, and niche engineering firms. PW Consulting’s competitive assessment focuses on capability sets that matter for 2026 buyers — precision envelope, interface flexibility, ruggedization, and system-level support.
- Jewell Instruments (Manchester, NH, USA) — Strong product breadth across single-, dual-, and tri-axis MEMS and force-balance inclinometers with multiple interface options. Their combination of industrial-grade outputs and field-proven ruggedization makes them a go-to for mixed-use portfolios.
- GEOKON (Lebanon, NH, USA) — Market-recognized specialist for geotechnical monitoring systems. Their in-place inclinometer (IPI) and spiral probe offerings cater to slope stability and long-term civil instrumentation programs, where integrated system design and data continuity are prioritized.
- US Digital (Vancouver, WA, USA) — Offers absolute optical and networked digital inclinometers with full 360° measurement and high resolution. Their networked architectures target distributed sensing use cases — e.g., solar arrays and dredging operations — where remote diagnostics matter.
- Level Developments Ltd (Croydon, UK) — OEM-focused supplier with strong footholds in solar tracking and industrial tilt sensing. Their catalogue demonstrates how temperature compensation and interface standardization reduce integration risk for system buyers.
- Rieker Inc (Aston, PA, USA) — Focused on vehicle and mobile-equipment tilt monitoring (boom angle, tip-over protection), representing the niche where application-specific ruggedness and certification are decisive.
- Fredericks Company (Huntingdon Valley, PA, USA) — Known for precision analog/digital inclinometers across wide angular ranges; their depth in specification-level products makes them a preferred partner for calibration-sensitive industrial use.
- TE Connectivity (Schaffhausen, Switzerland) — Global OEM with the AXISENSE series and embedded interfaces like CAN J1939, positioning them strongly for heavy equipment and platform-level safety systems.
From a market structure perspective, the top three suppliers account for a meaningful share of industry revenue, with the top five representing a majority position — a configuration that favors both established global suppliers and well-positioned regional specialists. This concentration level creates opportunities for focused players to win by specialization (e.g., power-optimized MEMS modules, certified geotechnical suites) and for larger players to pursue inorganic consolidation where scale accelerates platform adoption.
Industry dynamics: standards, quality, and the dominance of MEMS
Three persistent dynamics will influence procurement and product strategy in 2026:
- Standards and quality assurance: Certification continuity — exemplified by recent ISO 9001 follow-up audits in the industry — increasingly functions as a procurement filter for infrastructure and public procurement. Buyers value vendors who can demonstrate consistent manufacturing controls and quality processes.
- Technology convergence: MEMS technology has emerged as the dominant technical approach for mainstream digital inclinometers thanks to its favorable precision-to-cost ratio, compactness, and low power consumption. That creates a baseline expectation for many applications, while optical and force-balance technologies retain niches requiring extreme resolution or environmental robustness.
- Systems-level adoption: Demand is shifting from sensor procurement to integrated monitoring systems. Use cases like structural health monitoring, solar tracker optimization, and industrial safety are driving procurement toward sensors embedded in data platforms and service contracts.
Recent vendor moves illustrate these dynamics: certification updates that reassure large buyers, product introductions that push MEMS resolution and response times, and catalog refreshes that target solar and industrial segments with temperature-compensated, interface-rich devices. PW Consulting’s fieldwork shows that these micro-events materially change procurement conversations and selection criteria in 2026.
Recommended playbook: three immediate actions for 2026
- For manufacturers: tighten firmware and interface ecosystems to enable sensor-as-a-service models; invest in edge analytics and standardized connectivity to shorten integration cycles.
- For system integrators and asset owners: run pilot programs that bundle sensors with analytics and SLA commitments; use PW Consulting’s field validation templates to quantify the operational ROI within three to six months.
- For investors and corporate development teams: prioritize targets that deliver either clear system integration advantages (software + sensor) or that hold certification/quality processes minimizing procurement friction in public projects.
Conclusion and access to full intelligence
As organizations finalize 2026 investment plans, the Digital Inclinometer Market presents both clear growth opportunities and nuanced supplier-selection challenges. PW Consulting’s report equips executives with a decision-grade toolkit: validated market sizing (base year 2025, forecast 2026–2032, CAGR 6.3%), actionable vendor intelligence, and practical deployment playbooks. The full report contains the granular segmentation, pricing bands, and vendor-share tables that procurement teams and product strategists rely upon; those detailed elements are reserved for the complete document.
To obtain the full report, interactive model, and vendor benchmark appendices, visit our Digital Inclinometer Market page or contact PW Consulting’s industry practice. Use the intelligence to convert 2026 uncertainty into competitive advantage.
For detailed analysis of this topic, please visit the official page: Digital Inclinometer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com