

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Aircraft Composite Enclosures Market to Expand at a 7.12% CAGR Through 2032

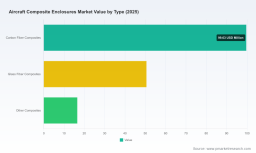
Aircraft Composite Enclosures Market: Strategic Imperatives for 2026 — A PW Consulting Perspective
As aerospace platforms continue to push the envelope on weight reduction, electromagnetic compatibility, and packaging density, composite enclosures for aircraft electronics have shifted from niche innovation to core systems enabler. PW Consulting’s latest market study—anchored on a 2025 base year and a 2026–2032 forecast horizon—shows the global aircraft composite enclosures market expanding at a compound annual growth rate (CAGR) of 7.12%. The market has accelerated from an early-decade base to a materially larger addressable pool by 2025, and our modeling anticipates continued momentum through 2032.
Aircraft Composite Enclosures Market
Why 2026 Is a Pivotal Year for Decision‑Makers
2026 is the inflection point when several converging forces change the economic calculus for OEMs, tier‑one suppliers, and strategic investors. First, the technology-to-cost trajectory for carbon and advanced resin systems is reaching thresholds that make composites competitive not only on weight but on lifecycle cost. Second, supply‑side consolidation and long‑term feedstock agreements are maturing, reducing the volatility that has historically discouraged large-scale program transitions. Third, regulators and certification frameworks are clarifying allowable practices for composite structural and enclosure elements, which materially shortens time-to-certification for new designs.
Aircraft Composite Enclosures Market
- Momentum and scale: The market has grown substantially in the 2020–2025 period and is projected to continue appreciating through 2032, providing a runway for investment-backed growth strategies.
- De-risking through supply agreements: Recent long-term carbon fiber and resin agreements are reducing price and availability tail risks—an enabler for multi-year program commitments in 2026 and beyond.
- Regulatory clarity: Updated advisory guidance on composite design and testing reduces certification uncertainty, accelerating program schedules.
Report Highlights: Actionable Components for Executives
PW Consulting’s report is structured to support decision-making at three levels: strategic portfolio decisions, program-level execution, and procurement/supply‑chain optimization. Rather than a purely descriptive market taxonomy, the study delivers implementable tools and a playbook for 2026 priorities.
Aircraft Composite Enclosures Market
- Investment and portfolio diagnostics: A decision matrix that aligns product portfolios (e.g., enclosure design variants, material choices, integration complexity) with program types (commercial narrowbody, widebody, military, rotorcraft, and aftermarket/MRO).
- Commercial models and pricing sensitivity: A cost‑model framework that maps material, manufacturing, and certification cost drivers to bill-of-material outcomes—enabling “what‑if” scenario planning under varying raw material price paths and production volumes.
- Supplier scorecards and risk heatmaps: Objective evaluations of tier‑one and tier‑two suppliers across technology capability, certification track record, program capacity, and financial resilience—designed for sourcing and partnership decisions.
- Go‑to‑market playbook for OEMs and new entrants: Pre-validated pathways for co-development, licensing, captive manufacturing, or contract manufacturing strategies, including suggested KPIs and prototype-to-certification timelines.
- M&A and J‑V advisory filters: A prioritization framework for acquisition targets and joint-venture structures—aligned with synergies in materials, processing know‑how, and geographic access to final assembly lines.
- Regulatory and test program roadmap: End-to-end guidance for leveraging current advisory circulars and regulatory updates to shorten time-to-approval for enclosure designs.
Competitive Landscape: How the Leaders Are Positioning in 2026
The market demonstrates mid-to-high concentration among established aerospace suppliers, with a pronounced role for diversified electronics and systems integrators that combine materials expertise with certification and supply-chain capabilities. Across the competitive set we profiled, distinct strategies emerge:
- TE Connectivity (Switzerland, with major U.S. operations) is leveraging its strength in connector and shielding technology to offer composite enclosures that integrate high-performance EMI shielding and holistic cable-interconnect considerations. Their proposition centers on system-level weight reduction without sacrificing electromagnetic compatibility—appealing to avionics integrators seeking plug-and-play replacements for legacy metal housings.
- Collins Aerospace (United States) leverages deep platform relationships with airframers and defense primes to deploy advanced composite enclosures across both commercial and military programs. Their competitive edge is program intimacy—early involvement in system partitioning and packaging that locks in long-term derivatives and retrofit opportunities.
- Carlisle Interconnect Technologies (Amphenol CIT) (United States) combines interconnect expertise with composite enclosure manufacturing to address high-voltage and high-density power-electronics packaging. Their value proposition centers on electro-mechanical integration and qualification for demanding aerospace operating envelopes.
- GE Aerospace (United States) illustrates cross-domain technology transfer—applying composite enclosure expertise from marine gas turbines into naval and aerospace markets. Recent contracts demonstrate capability in shock and vibration qualification and serve as a springboard into defense platforms.
- Automated Dynamics (Trelleborg) and specialist composites firms (e.g., AIM Aerospace, RAMPF Group, Kaman/Vermont Composites) differentiate through customization and niche engineering for sensitive electronics, emphasizing dielectric and shielding performance alongside mechanical robustness.
For new entrants and component suppliers, the competitive lesson is clear: success requires either deep systems integration capabilities, privileged material supply, or a narrowly defensible technical niche. The market rewards integrated value propositions that reduce OEM integration risk.
Recent Developments That Matter to 2026 Strategy
- Supply-side agreements continue to reshape sourcing risk. A notable long-term carbon fiber supply agreement announced in early 2026 underscores industry efforts to stabilize feedstock availability—an important signal for firms budgeting multi‑year programs.
- Major program awards that include composite enclosure scopes demonstrate buyer confidence in composite solutions. High‑visibility contracts in adjacent domains (e.g., marine gas turbines with composite housings) validate crossover opportunities and the transferability of qualification data.
- Raw material price dynamics remain relevant. For example, epoxy resin pricing has seen notable near-term increases, creating short-term cost pressure for resin-intensive layups and low-volume programs. At the same time, aerospace-grade carbon fiber pricing varies across a broad band—making procurement strategy and long-term supply commitments decisive for unit economics.
- Regulatory guidance on composite structure design and testing continues to advance. Firms that align early with advisory frameworks and invest in shared test artifacts will shorten certification timelines and capture first-mover advantages on new platforms.
Strategic Recommendations — Practical Moves for 2026
2026 should be the year companies convert strategic intent into executable programs. PW Consulting recommends a coordinated set of actions across product, procurement, and partnership domains:
- Lock in feedstock through tiered contracts: Negotiate a mix of fixed-price and indexed contracts for carbon fiber and key resins to balance price predictability and upside flexibility. Prioritize suppliers with demonstrable commitment to aerospace-grade continuity.
- De-risk certification early: Invest in pre‑qualification test programs and cross‑platform data packages that can be reused across programs. Leverage advisory circulars and engage certification authorities in pilot programs to reduce surprises in full-scale certification routes.
- Integrate system-level design thinking: Move beyond component replacement to system co-optimization—combining enclosure design with thermal management, EMI control, and ease-of-installation to increase total system value capture.
- Pursue strategic partnerships: Consider J‑Vs with material suppliers or joint development agreements with avionics integrators to share development costs and secure preferential supply access.
- Prepare manufacturing scalability plans: For firms expecting volume, develop investment roadmaps that migrate from hand-layup prototyping to automated tape-lay and out-of-autoclave processes, with explicit ROI gates tied to orderbook milestones.
What PW Consulting’s Report Will Do for Your 2026 Plan
Our report is designed to be a working tool for leaders who must make tangible 2026 commitments—whether that is to include composite enclosures in an OEM’s next-generation platform, to greenlight capital spending for manufacturing upgrades, or to pursue M&A opportunities in the supplier base. It delivers the intelligence you need to:
- Quantify program-level economics under alternative material and volume scenarios;
- Prioritize suppliers and partnership targets with an evidence‑based scoring methodology;
- Map certification pathways and estimate realistic timeline and cost buffers;
- Define procurement hedging strategies that align with your risk appetite;
- Benchmark your capabilities against leading providers to identify capability gaps and targeted investments.
Conclusion — From Insight to Action
Composite enclosures are no longer a marginal choice; they are central to the next wave of avionics and systems packaging innovation. With the market growing at a mid-single-digit-plus CAGR and accelerating toward a larger addressable base over the next decade, 2026 is the moment to translate strategy into contracts, partnerships, and factory floors. PW Consulting’s report equips leaders with the scenarios, cost models, supplier intelligence, and certification roadmaps necessary to make those decisions with confidence—while preserving the full set of segmented market data and program-level analyses for stakeholders who require the detailed export package.
To access the full report, including proprietary segment-level models and the supplier scorecards, please visit the PW Consulting report portal or contact our advisory team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Aircraft Composite Enclosures Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com