

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Industrial Centrifuge Machines Market to Reach USD 13.47 Billion by 2032, Growing at a 5.12% CAGR—North America Leads with USD 3.54B (2025)

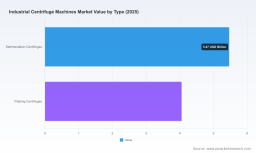
Industrial Centrifuge Machines Market: Strategic Preview for 2026 Decision-Making
PW Consulting’s new Industrial Centrifuge Machines Market brief crystallizes the high-level trends and decision levers that will shape procurement, product strategy, and M&A activity in 2026. Our analysis shows a mature market that continues to expand steadily — estimated at USD 9.53 Billion in the 2025 base year with a compound annual growth rate of 5.12% across the 2026–2032 forecast window (our horizon projects market growth toward the mid-teens in cumulative value by 2032). These headline figures frame an environment of moderate growth, measurable consolidation, and acute cost pressure that executives must navigate with precision.
Industrial Centrifuge Machines Market
Why this preview matters to executives in 2026
-
Timing capital investment: A steady mid-single-digit CAGR signals that now is a tactical moment to prioritize modernization and service-led differentiation rather than pursue broad capacity expansion. Companies that sequence investments to capture premium segments (high-throughput, high-integrity separations) will outpace peers on margin expansion.
Industrial Centrifuge Machines Market -
Supplier and partner selection: Market concentration metrics reveal a landscape where top suppliers hold meaningful scale but do not dominate outright — creating room for regional specialists and innovative challengers to win business through speed-to-application and lifecycle services.
Industrial Centrifuge Machines Market -
Cost and supply risk mitigation: Sustained raw-material pressures and trade-policy dynamics mean manufacturers and end-users must re-evaluate sourcing, design-to-cost, and hedging strategies to protect margins in 2026.
What the report delivers — practical, executable intelligence
Our full market study is built for executives who need to convert market intelligence into concrete actions within 6–18 months. Key deliverables include:
-
Executive playbook — a prioritized list of six strategic moves (e.g., service-first product roadmaps, targeted bolt-on acquisition criteria, and aftermarket monetization pathways) aligned to different corporate objectives: growth, margin protection, and defensibility.
-
Proprietary Total Cost of Ownership (TCO) models — scenario-ready tools that quantify CapEx and OpEx trade-offs across equipment classes, lifecycle services, and energy regimes to inform procurement and retrofit decisions.
-
Go-to-market frameworks for product differentiation — templates for positioning high-speed separators, decanters, and filtration-focused units to win in food & beverage, bioprocessing, wastewater, and heavy industrial segments.
-
Supplier & technology scorecards — standardized evaluation matrices that combine performance, service capability, footprint, and digital maturity so buyers can accelerate supplier selection without the ambiguity of disparate vendor data.
-
Regulatory and raw-material impact maps — decision matrices that translate tariffs, specialty-steel volatility, and local content rules into procurement and inventory responses to protect project economics.
-
Scenario-driven demand forecasts — short-, medium-, and long-term scenarios that stress-test investment plans under variations in feedstock, energy costs, and end-market demand for circular-processing solutions.
Competitive landscape: how incumbents and challengers are positioning in 2026
The market is characterized by a mix of large multinational OEMs, regionally focused specialists, and century-old firms that have carved niche capabilities. Three- and five-firm concentration numbers indicate a market where scale matters but innovation and service differentiation can carve outsized value. Against that backdrop, companies are pursuing distinct strategic levers:
-
Product-led differentiation: Global OEMs continue to launch high-value separators and decanters optimized for growth verticals. Recent launches that exemplify this move include high-speed units designed for dense fermentation and hermetically sealed separators for biopharma processes — reflecting targeted investment toward higher-margin, technology-intensive applications.
-
M&A and capability aggregation: Select players have broadened portfolios via bolt-on acquisitions that add sensorization, chemical dosing or complementary water-treatment technologies — a trend that accelerates integrated solution offerings in municipal and industrial wastewater accounts.
-
Service and processization: New process centers and expanded application labs are being opened to accelerate customer adoption through onsite trials, performance guarantees, and outcome-based contracting — blurring the line between equipment vendor and process partner.
-
Regional manufacturing and aftermarket emphasis: To address tariff dynamics and steel-cost headwinds, some manufacturers are doubling down on regionalization of assembly and parts distribution while expanding aftermarket teams to convert one-time sales into recurring revenue streams.
Representative players illustrate these dynamics. Major incumbents are refreshing portfolios with high-speed and hermetic designs optimized for biotech and alternative-protein processing. Others are expanding sensors and digital monitoring capabilities through targeted acquisitions, while specialist manufacturers continue to win by offering tailored solutions and strong service networks. This mix creates both consolidation opportunities and niches for well-positioned challengers.
Cost, supply chain, and regulatory dynamics that will drive 2026 priorities
-
Raw-material pressures: Steel and specialty alloy volatility is directly impacting equipment costs. Executives should assume persistent elevated input prices in near-term supplier negotiations and model procurement windows accordingly.
-
Trade and tariff risks: Continued elevated trade measures in key markets mean import-dependent sourcing exposes buyers to margin erosion. Nearshoring or regional assembly can be decisive hedges for contract competitiveness.
-
Serviceability and uptime: As process partners push for stricter SLAs in critical applications (pharma, waste treatment), investments in remote-monitoring, spare-part strategies, and predictive maintenance are becoming non-negotiable cost-avoidance levers.
Strategic playbook for 2026 — five actions for executives
-
Re-prioritize capex: Move from broad capacity builds to selective modernization of high-throughput and high-integrity assets. Use our TCO templates to identify retrofit opportunities that deliver faster payback with lower incremental risk.
-
Design to availability: Shift procurement evaluation from sticker price to availability and lifecycle cost. Shorten lead times by qualifying multiple regional suppliers and locking in critical components with staggered contracts.
-
Pursue service-led growth: Create bundled offers combining equipment, monitoring, and outcome-based maintenance. The path to recurring revenue now runs through performance guarantees and digital service delivery.
-
Hedge material exposure: Implement multi-year material contracts, strategic inventory buffers for critical alloys, and engineering reviews to substitute where life-cycle risk allows.
-
Use M&A tactically: Target acquisitions that add sensorization, process engineering expertise, or local footprint. Smaller-scale deals that bring application know-how often yield quicker returns than broad transformative transactions.
How to use this analysis in 2026 planning cycles
-
Board-level capital allocation: Apply our scenario tools to test CapEx requests under three market trajectories (conservative, baseline, accelerated) and require breakpoints for retrofit vs. new-build investments.
-
Procurement scorecards: Replace traditional shortlists with our supplier scorecards that weight lifecycle cost, digital readiness, and regional manufacturing exposure to tariffs.
-
R&D and product roadmap: Prioritize designs that reduce material intensity, enable rapid serviceability, and integrate predictive diagnostics to capture aftermarket margins.
What we are intentionally holding back — and why
In this preview we have focused on the strategic implications and actionable playbook that will matter to decision-makers in 2026. To preserve the value of the full study as a strategic asset, detailed segmentation tables, granular regional and application splits, and vendor-by-vendor revenue benchmarks are reserved for the full report and the interactive data portal. These granular datasets power procurement shortlists, investment memos, and M&A valuations — and are provided in the complete package so practitioners can run vendor selection and deal due diligence with primary-source rigor.
Next steps
For leaders preparing budgets and strategy for 2026, PW Consulting’s full Industrial Centrifuge Machines Market report converts the directional intelligence presented here into executable tactics: calibrated investment timing, supplier negotiation templates, and prioritized M&A targets. Contact our industry team to access the full dataset, the customizable TCO models, and a tailored briefing that maps our insights to your business objectives.
For detailed analysis of this topic, please visit the official page: Industrial Centrifuge Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com