

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automotive Automatic Spray Guns Market to Grow at 5.85% CAGR — From USD 1,025.6 Million in 2025 to USD 1,527.35 Million by 2032, Led by HVLP and Europe

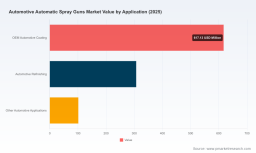
Automotive Automatic Spray Guns Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive summary
As original equipment manufacturers, refinishers, system integrators and Tier‑1 suppliers prepare their 2026 capital plans, the Automotive Automatic Spray Guns market presents a clear but nuanced growth story. Our latest PW Consulting market study establishes that the market reached USD 1,025.6 Million (base year 2025) and is forecast to expand at a compound annual growth rate (CAGR) of 5.85% over the 2026–2032 horizon, exceeding the USD 1.5 Billion threshold by the end of the forecast period. That topline momentum is being driven by regulatory tightening, increased adoption of high‑transfer technologies, and intensifying automation in vehicle paint shops — but the path forward is punctuated by supply‑side constraints, material cost pressure and a selectively consolidating competitive landscape.
Automotive Automatic Spray Guns Market
Why this report matters for 2026 corporate decisions
-
Timing of investment: manufacturers face a narrow window to commit to automation and electrostatic solutions aligned with phased VOC and NESHAP compliance deadlines through 2028. The report translates regulatory timelines into purchase and retrofit milestones so procurement and plant engineering teams can de‑risk capex.
Automotive Automatic Spray Guns Market -
Procurement and supplier strategy: escalating nozzle and component alloy costs are squeezing margins on premium guns. Our analysis provides procurement playbooks to balance price, service levels and technology upgrades — providing concrete levers to protect EBITDA while upgrading performance.
Automotive Automatic Spray Guns Market -
M&A and partnership prioritization: with a moderate level of market concentration (CR3 ≈ 38.5%, CR5 ≈ 52.7%), strategic buyers and investors must identify targets offering technological complementarity or channel access rather than volume alone. The report highlights the types of assets most likely to unlock near‑term synergies.
-
Operational readiness: systems integrators and OEM paint shops can use the report’s scenario models to plan robot cell redesigns and paint line sequencing to maximize transfer efficiency and throughput without excessive paint waste.
Market trajectory and growth drivers
The mechanical and regulatory drivers are reinforcing one another. On the demand side, vehicle electrification and changing body architectures are altering paint system footprints and increasing the premium on transfer efficiency and atomization control. On the regulatory side, requirements such as EPA NESHAP 6H, South Coast AQMD Rule 1151 and the EU VOC Directive are accelerating shifts toward HVLP‑equivalent and electrostatic technologies in both OEM and refinishing channels. Supply dynamics are equally important: higher stainless steel and specialty alloy costs for critical nozzle components are influencing manufacturer pricing, design decisions and aftermarket strategies.
These forces underpin the mid‑single‑digit CAGR we project through 2032 — steady growth, but concentrated around technology transitions, replacement cycles and regulatory compliance windows rather than a uniform expansion across all product tiers.
Competitive landscape — what to watch in 2026
-
Graco Inc. (Minneapolis, USA) — Strengths: broad product portfolio that spans high‑transfer electrostatic and robotic integration; reputation for durability and service. Strategic implication: Graco’s emphasis on robotic compatibility makes it a natural incumbent for greenfield automotive lines and for OEMs upgrading automation standards.
-
SATA GmbH & Co. KG (Kornwestheim, Germany) — Strengths: precision atomization and ergonomic design; strong presence in vehicle manufacturing and refinish arenas. Strategic implication: SATA’s premium positioning and recent product previews signal opportunities for refinisher networks and premium OEM tiers seeking consistency and finish quality.
-
Anest Iwata (Yokohama, Japan) — Strengths: advanced atomization tech and continual product refresh (e.g., 2026 catalogue rollouts). Strategic implication: buyers focused on finish fidelity and consistent color matching should consider Anest Iwata in supplier evaluations, especially where cross‑line standardization matters.
-
Nordson Corporation (Westlake, USA) — Strengths: electrostatic and powder coating systems optimized for high‑volume lines. Strategic implication: where throughput and material savings are prioritized, Nordson’s systems provide scalable solutions; consider total cost of ownership (TCO) models that capture material savings over multiple years.
-
EXEL Industries / Sames (Épernay, France) — Strengths: diversified technology mix (Airspray, Airmix, electrostatic) and assembly‑line experience. Strategic implication: strong candidate for integrators seeking an array of technologies under a single vendor umbrella, facilitating lifecycle support and spare parts commonality.
-
Carlisle Fluid Technologies (DeVilbiss, Binks) (Scottsdale, USA) — Strengths: legacy brands focused on transfer efficiency and industrial finishes. Strategic implication: attractive for aftermarket service contracts and for plants balancing cost and performance with established supplier relationships.
-
Selected Chinese OEMs (e.g., Ningbo Lis, Zhejiang Rongpeng) — Strengths: cost‑competitive, customizable offerings. Strategic implication: strong contenders in volume retrofit projects and price‑sensitive markets; quality and long‑term service support should be validated in pilot deployments prior to large rollouts.
Recent market moves underscore these trends: a 2026 educational partnership with a major technical training institute, product previews from legacy premium vendors and refreshed catalogs from established Japanese manufacturers all point to simultaneous demand for training, premiumization and product renewal. These are signals that the market is not only growing, but also maturing in procurement complexity.
Report contents — practical tools inside
This is not a high‑level narrative. PW Consulting’s report is operationally focused and designed for immediate use by procurement, engineering, product and strategy teams. Key deliverables include:
-
A decision matrix aligning technology choices (HVLP, airless, electrostatic) with plant objectives: yield, throughput, regulatory compliance and TCO.
-
Investment timing playbooks that map regulatory deadlines and replacement cycles to capex windows and pilot program schedules.
-
Supplier scorecards and negotiation scripts — assessing service coverage, spare parts lead times, retrofit compatibility and aftermarket economics.
-
Scenario financial models (best case / mid / downside) to stress‑test ROI for line upgrades, including sensitivity to raw‑material cost inflation and labor rates.
-
Implementation checklists for automation integrators covering robot head compatibility, control protocols and paint booth ergonomics.
-
Compliance and risk register that translates regulatory language into plant‑level obligations and audit readiness steps.
Strategic playbook for 2026
-
Prioritize regulatory alignment: convert compliance deadlines into actionable retrofit or replacement milestones. Early pilots on electrostatic/HVLP solutions reduce rework and avoid last‑minute premium procurement.
-
Hedge material cost pressure: renegotiate multi‑year contracts with nozzle and component suppliers; evaluate alternative alloys and surface treatments that preserve performance at lower cost.
-
Build selective redundancy: given the market’s mid‑level concentration, cultivate primary and secondary suppliers to avoid single‑source risk for critical spare parts and robot interfaces.
-
Leverage TCO, not sticker price: capture savings from reduced paint consumption and improved throughput in procurement evaluations. Our TCO templates show how small efficiency gains compound over typical equipment lifecycles.
-
Invest in workforce upskilling: partnerships between vendors and technical institutes (as seen in recent industry announcements) are becoming a differentiator — integrate training clauses into supplier contracts.
-
Monitor consolidation opportunities: given CR3/CR5 dynamics, M&A targets that close functional gaps (robotic software, nozzle tech, local service networks) deliver greater value than pure volume plays.
How to use the PW Consulting study in practice
We recommend a three‑step adoption plan for 2026:
-
Phase 1 — Rapid diagnostic (30 days): use our supplier scorecards and regulatory checklists to triage immediate compliance and spare‑parts vulnerabilities across your plants.
-
Phase 2 — Pilot and validate (3–9 months): deploy a pilot cell using recommended technologies and run TCO scenarios against baseline operations, incorporating paint savings and labor impacts.
-
Phase 3 — Scale and contract (9–24 months): negotiate framework agreements with primary and secondary suppliers, lock in pricing collars for critical components, and roll out upgrades aligned with planned production downtime.
Conclusion — the strategic payoff
For companies facing 2026 budget cycles, the choice is not simply which spray gun to buy — it is about orchestrating technology, procurement, compliance and operations to deliver measurable margin improvement and regulatory resilience. With the market at USD 1,025.6 Million in 2025 and a clear growth path (5.85% CAGR to 2032), the opportunity cost of delayed action is real: missed paint savings, compressed lifecycles and exposure to regulatory penalties. PW Consulting’s Automotive Automatic Spray Guns Market study is structured to convert market intelligence into executable steps — a concise playbook that turns regulatory pressure and material headwinds into competitive advantage.
Contact PW Consulting for access to the full report, proprietary models and a tailored briefing for your organization’s 2026 strategy session.
For detailed analysis of this topic, please visit the official page: Automotive Automatic Spray Guns Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com