

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Handheld Devices Command 58.41% of Portable Keratometer Market as Industry Eyes 6.75% CAGR Through 2032

Portable Keratometer Market: Strategic Imperatives for 2026 — PW Consulting Release
PW Consulting today publishes a strategic preview of our latest Portable Keratometer Market study, designed for C-suite decision makers, corporate strategy teams, product leaders and investors who need an evidence-led playbook for 2026. Grounded in a rigorous historical review (2020–2025) and a seven-year forecast (2026–2032), the report synthesizes commercial, clinical and regulatory dynamics that will determine winners in an evolving portable ophthalmic diagnostics ecosystem.
Portable Keratometer Market
Why this report matters for 2026 planning
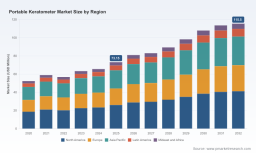
Portable keratometers have moved from niche field tools to core assets within hybrid eye-care delivery models — from outreach missions and mobile clinics to integrated point-of-care workflows in ambulatory surgery centers. Our analysis shows a resilient market that expanded through 2025, reaching an estimated market size of USD 73.15 Million in the base year, and is projected to continue expanding at a steady compound annual growth rate of approximately 6.75% over the forecast period. Underlying that headline growth is a mix of accelerating adoption in non-traditional care settings, incremental product innovation (miniaturization, sensor fusion, and app-based analytics), and tighter integration with biometry and refractive platforms.
Portable Keratometer Market
For executives preparing 2026 budgets and three- to five-year roadmaps, the practical implications are clear: invest selectively in portable keratometry if your strategy depends on mobility, cost-optimized refractive screening, or bundle offerings around mobile surgical services. However, the financial upside is best realized by pairing device capability with service models — training, tele-interpretation, and deployment logistics — rather than relying solely on unit sales.
Portable Keratometer Market
What the report delivers — actionable, decision-focused content
- Market sizing and trend narrative: A reconciled historical dataset (2020–2025) and scenario-based forecasts to 2032 that reflect demand elasticity under differing adoption and reimbursement assumptions.
- Go-to-market playbooks: Practical routes to scale in low-resource and premium settings, including channel mix, pricing approaches, and partnership architectures that reduce time-to-adoption.
- Product and technology roadmap guidance: Comparative evaluation of key design trade-offs (handheld ergonomics vs. tabletop-dock versatility; sensor accuracy vs. throughput; local processing vs. cloud analytics) to inform R&D prioritization and M&A screening.
- Regulatory and standards checklist: Mileposts for 510(k) strategies, EU MDR conformity, and ISO standards compliance to avoid time-consuming rework during product commercialization.
- Procurement model templates: Cost-of-ownership frameworks tailored for hospital buyers, NGO procurement teams, and mobile clinic operators — including sample KPIs for uptime, calibration cadence, and operator training requirements.
- Risk heatmaps and mitigation strategies: Operational, regulatory and competitive risks prioritized by likelihood and impact, with recommended mitigations that can be executed within six to 18 months.
The report is deliberately structured to be operational from day one — with executive checklists, an investment decision matrix, and templated vendor evaluation criteria. To preserve strategic value for paying subscribers, detailed segment-by-segment revenue tables and unit-level pricing schedules are available in the full report.
Competitive landscape — concentration and strategic profiles
The portable keratometer market exhibits moderate concentration: the top three vendors account for a meaningful share of the market, and the top five consolidate an even larger portion of available revenues. This concentration presents both risks and opportunities. Established suppliers benefit from brand trust and distribution scale, while agile entrants can capture share by addressing unserved niches — particularly in mobile outreach and low-cost screening.
- Micro Medical Devices (United States) — Micro Medical Devices has positioned its PalmScan PRO and K2000 portable keratometer probe as a field-deployable solution tightly integrated with biometry systems. Their recent mission deployments demonstrate the commercial and reputational benefits of proving devices in real-world outreach programs. Website: https://micromedinc.com/
- PlenOptika (United States) — PlenOptika’s QuickSee Free Pro leverages wavefront aberrometry to deliver clinical-grade refraction and keratometry in a handheld form factor. The company’s platform emphasis is on software and mobile integration; a mid-2025 app update underscores the competitive importance of a robust companion software ecosystem. Website: https://plenoptika.com/
- NIDEK (Japan) — NIDEK’s HandyRef-K demonstrates how incumbent ophthalmic OEMs are adapting core technologies for portable use, addressing both clinic overflow and supine/mobile patient workflows. Website: https://www.nidek-intl.com/
- Marco (United States) — Marco competes with portable ARK devices intended for anytime/anywhere refraction and keratometry, leveraging service networks to support clinicians. Website: https://marco.com/
- Devine Meditech (India) — Focused on cost-effective handheld auto-keratometers, Devine Meditech is an example of regional players filling affordability gaps, especially in emerging markets. Website: https://devinemeditech.com/
- Reichert (AMETEK) (United States) — Reichert offers portable-capable keratometry within a broader ophthalmic diagnostics portfolio, an approach that supports cross-selling into existing installed bases. Website: https://www.reichert.com/
- Huvitz (South Korea) — Huvitz brings portable-compatible ref/keratometers to market, emphasizing ergonomic design and compatibility across refraction workflows. Website: https://www.huvitz.com/
Recent vendor activity highlights how competition is shifting from hardware-only differentiation to software-enabled clinical workflows and field validation. Notable examples include PlenOptika’s February 2025 companion app upgrade and Micro Medical Devices’ documented mission deployment in late 2025. These moves signal that clinical integration and proof-of-field efficacy are decisive purchase triggers.
Regulatory, standards and reimbursement dynamics
Understanding the regulatory and standards environment is critical to getting to market quickly and sustaining commercial traction. Key considerations covered in the report include:
- Regulatory classification: In the United States, auto-keratometers are regulated as Class II devices under FDA 21 CFR Part 886.1500 and typically require 510(k) premarket notification. This drives specific evidence requirements around performance and equivalence.
- European market access: Devices fall under EU MDR 2017/745 classifications that necessitate conformity assessment and ongoing post-market surveillance — a material cost and timeline factor for international launches.
- Standards compliance: ISO 15004-1:2020 establishes test methods and fundamental requirements for non-invasive ophthalmic instruments; alignment with recognized consensus standards can streamline regulatory submissions and reduce review risk.
The report includes a practical timeline for regulatory filings, a prioritized list of performance tests to commission (bench and clinical), and templates for post-market surveillance plans that meet MDR expectations while minimizing surveillance overhead.
Strategic takeaways for 2026 decision cycles
- Prioritize integration over replacement: Buyers increasingly favor keratometers that integrate with biometry and refraction ecosystems. Providers should demonstrate interoperability and data portability as primary value drivers.
- Segment go-to-market by use-case economics: High-throughput ambulatory centers have different payback horizons than mission-driven NGOs or primary-care screening programs. Tailor commercial models — service bundles, device-as-a-service, and volume discounts — to the economics of each buyer segment.
- Invest in software and clinical evidence: App ecosystems, cloud analytics and validated clinical workflows yield disproportionate returns versus marginal hardware improvements. Clinical validation in target use environments (e.g., supine, low-light, pediatric) is a competitive moat.
- Plan regulatory pathways early: For entrants eyeing international scale, prepare parallel regulatory strategies and designate engineering resources to meet MDR and ISO requirements to avoid staggered launches.
- Use procurement KPIs to win long-term contracts: Vendors that commit to measurable uptime, calibration turn-around, and operator training can shorten procurement cycles and secure bundled service contracts.
How to use this preview — and where to find the full intelligence
This release is a strategic preview intended to help leadership teams prioritize initiatives for 2026. PW Consulting’s full Portable Keratometer Market report contains the granular segmentation tables, scenario-model outputs, vendor benchmarking matrices and downloadable procurement templates that buyers and investors rely on when committing capital or entering partnerships.
If your 2026 strategy depends on portable keratometry — whether to scale mobile eye-care programs, defend share in ambulatory settings, or evaluate acquisition candidates — the full report equips you with the data and executable frameworks needed to act confidently. Detailed segment revenue breakdowns, unit economics, and modeled sensitivity analyses are available in the complete study.
To request an executive briefing or access the full report, please contact your PW Consulting account representative or visit our website for subscription options and licensing details.
For detailed analysis of this topic, please visit the official page: Portable Keratometer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com