

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Refrigerated Food Vending Machine Market Set to Expand at a 7.5% CAGR, Revolutionizing On‑the‑Go Fresh Food Retail

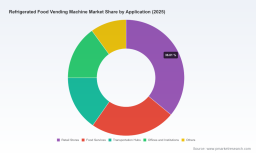
Refrigerated Food Vending Machine Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
As organizations plan capital allocation and go-to-market moves for 2026, the refrigerated food vending machine market presents a window of accelerated opportunity and regulatory-driven disruption. Our new PW Consulting market study shows the industry growing from an estimated USD 6.9 billion in 2025 at a compound annual growth rate of 7.5% through the 2026–2032 forecast horizon, reaching roughly USD 11.45 billion by 2032. These headline metrics underline a robust demand trajectory—but behind the aggregate figures sits a set of operational, regulatory and technological inflection points that will determine winners and losers over the next 18–36 months.
Refrigerated Food Vending Machine Market
Why 2026 Is a Pivotal Year for Buyers and Providers
-
Regulatory dead zones and compliance cliffs are creating mandatory reset points for fleets. In North America, the EPA AIM Act’s phase-out schedule for high‑GWP refrigerants culminates in sales restrictions that came into force for manufacturers/importers and for most machine sales as of early 2026. In parallel, European energy labeling and performance standards are raising the bar on permissible energy consumption and mechanical efficiency. The practical effect is twofold: legacy machines using non‑compliant refrigerants or poor energy performance will face enforced retirement or costly retrofit, and buyers who delay will confront compressed supplier capacity as operators accelerate fleet refreshes.
Refrigerated Food Vending Machine Market -
Convergence of smart hardware and services is accelerating adoption. Smart vending coolers, RFID‑enabled inventory tracking, AI‑assisted merchandising and integrated micro‑market solutions showcased at trade events in 2026 are redefining uptime economics and the operator value proposition. Early adopters are already demonstrating higher fill efficiencies, lower shrink and improved average ticket via personalization and real‑time assortment optimization.
Refrigerated Food Vending Machine Market -
Supply chain and material dynamics matter. Structural components remain dominated by steel in food vending construction due to durability and thermal performance—an important input constraint for procurement and lifecycle costing.
What the PW Consulting Report Delivers (Practical, Execution‑Oriented)
Our full study is designed as an operational playbook for buyers, OEMs, investors and foodservice chains evaluating refrigerated vending strategies in 2026. Key deliverables include:
-
Proven market sizing and forecast methodology with scenario sensitivity to refrigerant regulation timelines, energy regulation adoption and macro demand drivers.
-
Demand‑driver analysis and adoption curves for smart features (telemetry, RFID, AI merchandising), with use‑case payback models that let you stress‑test assumptions by site type and footfall profile.
-
Regulatory compliance playbook: a step‑by‑step checklist for retrofits vs. replacement, procurement language for refrigerant compliance, and energy label testing protocols aligned to current EU and U.S. standards.
-
Competitive benchmarking and vendor scorecards covering refrigeration technology, service models, software ecosystem, reliability data and commercial terms—built to inform RFPs and supplier selection.
-
Operational toolkits for operators: deployment planning templates, KPI dashboards, maintenance SOWs, spare‑parts strategies and capex/opex optimization guidance.
-
Commercial playbooks for manufacturers and channel partners: product roadmaps, aftermarket services strategies, subscription and leasing models, and prioritized feature investments by ROI impact.
-
Case studies and build‑to‑bench ROI calculators for pilots in four archetypal channel environments—retail, transportation hubs, foodservice and workplace—so executives can size pilots and scale with confidence.
Competitive Landscape: Who’s Moving the Needle
The vendor field combines legacy vending OEMs and nimble systems integrators. Market concentration is moderate—the top three companies account for less than one‑third of market revenue while the top five capture a bit over two‑fifths—indicating substantial room for regional leaders, technology specialists and new entrants to gain share through differentiation and aggressive go‑to‑market moves.
-
Established OEMs with integrated cold‑chain expertise are leveraging brand reliability and distribution reach to protect installed base economics. Their strengths lie in proven refrigeration platforms, nationwide service networks and scale procurement for components and compressors. These providers are prioritizing compliance upgrades and energy efficiency improvements to secure renewal contracts and large channel partnerships.
-
Technology‑first entrants and systems integrators are attacking value streams above the cabinet—software, telemetry, inventory automation and consumer experience. RFID‑enabled smart fridges and AI merchandising systems are being piloted and deployed in high‑visibility sites; these platforms reduce labor cost per sale and enable dynamic assortment decisions that measurably lift per‑site revenue.
-
Regional manufacturers—particularly those from high‑volume production centers—are competing on price, modularity and adjustable cooling ranges to serve emerging markets and non‑traditional placement opportunities. Their product portfolios often include flexible temperature zones and touchscreen UX that appeal to operators seeking low‑cost reliability.
-
Recent market signals: RFID smart‑fridge deployments by innovators in 2025–2026 and broad exposure of AI‑enabled refrigerated coolers at trade events indicate the next wave of differentiation will be software‑centric offerings backed by service contracts rather than pure hardware sales.
Technology, Regulation and Cost Dynamics: What Keeps CFOs Awake
-
Refrigerant transition is a capital‑intensive pivot. Moving from high‑GWP HFCs to compliant low‑GWP alternatives (or to alternative refrigeration architectures) affects BOM cost, reliability profiles and maintenance skillsets. Procurement teams must model retrofit vs. replacement under multiple regulatory scenarios to avoid stranded assets.
-
Energy efficiency is now a sales and operating cost driver. Energy labeling regimes will increasingly influence procurement decisions and operator economics—machines with superior energy ratings command lower lifetime operating costs and easier approvals for placement in regulated facilities.
-
Connected features change the monetization math. Telemetry, inventory sensors and data aggregation allow operators to reduce replenishment frequency, lower shrink and test price/assortment strategies fast. Software monetization (SaaS and data services) is emerging as a high‑margin aftermarket stream for OEMs and platform providers.
-
Materials and supply chain: the prevalence of steel in structural components drives procurement exposure to commodity cycles; smart hedging and multi‑source strategies are practical levers for cost certainty.
Commercial Models and Route‑to‑Scale
Successful scaling patterns are converging on a few repeatable models:
-
Lease + Managed Services: lowers client upfront cost and creates recurring revenue for providers while aligning incentives on uptime and fill performance.
-
Platform + Marketplace: combining refrigeration hardware with proprietary merchandising algorithms and content/display partnerships to increase average transaction value.
-
Micro‑market integration: blending unattended refrigerated cabinets into larger micro‑retail ecosystems—this increases basket size and extends revenue per square foot for landlords and operators.
Top Strategic Recommendations for 2026 Decision‑Makers
-
Prioritize compliance and energy performance in shortlists. Regulatory non‑compliance now has defined cut‑off dates; prioritize suppliers with validated low‑GWP refrigerant solutions and strong energy labeling performance.
-
Design pilots to validate commercial software ROI first. Test telemetry, dynamic assortment and price sensitivity in a small number of high‑quality sites before committing to a national roll‑out.
-
Move from transactional procurement to partnership contracts. Seek supplier terms that bundle hardware, software upgrades and parts exchange to protect against technology obsolescence and refrigerant transitions.
-
Diversify component sourcing and hedge steel exposure. Locking favorable terms with multiple compress or cabinet suppliers reduces the risk of price spikes and lead‑time shocks.
-
Plan for M&A and consolidation options. Moderate market concentration suggests buy‑and‑build strategies can unlock scale advantages—keep deal teams active and model bolt‑on economics for adjacent services such as telemetry platforms and managed operations.
How to Use the Full Report
This press brief highlights the strategic contours and immediate action levers for 2026, but it is intentionally a teaser. The full PW Consulting Refrigerated Food Vending Machine Market report provides the granular competitive scorecards, channel‑level demand curves, RFP templates, scenario P&L models and vendor‑by‑feature matrices required to execute with confidence. For operators and manufacturers preparing capex and product roadmaps in 2026, those detailed data and decision tools shorten the timeline from strategy to profitable execution.
To obtain the complete set of operational templates, vendor benchmarks, and site‑level ROI calculators—plus our consultants’ recommended implementation sequences—please consult the PW Consulting report download page. The full analysis contains the confidential split‑level intelligence and deployment playbooks that support fast, low‑risk scaling decisions.
About the Author
Prepared by PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, this brief synthesizes primary market research, vendor interviews and regulatory analysis completed through mid‑2026. Our advisory practice helps clients convert market insight into executable programs that reduce risk and accelerate value capture in capital‑intensive equipment markets.
For detailed analysis of this topic, please visit the official page: Refrigerated Food Vending Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com