

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Digital Inclinometer Market to Rise from USD 342.7 Million (Base Year 2025) to USD 525.58 Million by 2032 at 6.3% CAGR — Asia‑Pacific Leads with USD 122.54M, Construction the Top Application

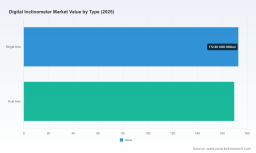
Digital Inclinometer Market 2026: Strategic Intelligence Brief — A PW Consulting Special Release
As infrastructure resilience, renewable energy deployment, and industrial automation accelerate into 2026, digital inclinometers have shifted from niche instrumentation to strategic enablers of operational safety and performance. PW Consulting’s latest market research on the Digital Inclinometer Market (base year 2025; forecast 2026–2032) synthesizes proprietary market-sizing, vendor benchmarking, technology deep dives, and scenario-based forecasting to deliver the one-page strategic blueprint enterprises need to prioritize investments and shape go-to-market strategies in 2026.
Digital Inclinometer Market
Market snapshot: validated growth and forward momentum
Our macro analysis confirms a sustained expansion in the global digital inclinometer market. After a period of steady historical growth from 2020 through 2025 — when the market reached approximately USD 342.7 Million (base year 2025) — the report’s forward-looking model projects continuation of this trajectory through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 6.3%. The PW Consulting model maps demand drivers tied to infrastructure monitoring, solar and renewable asset optimization, and the industrialization of sensor-enabled safety systems, producing a market value that rises materially by the end of the forecast period.
Digital Inclinometer Market
Two macro takeaways for 2026 decision-makers: (1) the market is large enough to support differentiated product and channel strategies while (2) adoption is driven more by systems-level value (reduced maintenance cost, risk mitigation, uptime) than by component-level price competition. Our concentration analysis reinforces this: market share is clustered among a handful of global and regional specialists, with mid-level concentration that still leaves space for focused challengers and adjacent-industry entrants.
Digital Inclinometer Market
What the PW Consulting report delivers — operational intelligence, not just data
- Robust market-sizing and demand-scenario modeling (base 2025; forecast 2026–2032) built from primary interviews, field sampling, and proprietary shipment-to-revenue translation models.
- Technology deep-dive comparing MEMS, optical, and force-balance architectures, including trade-offs for precision, power, form-factor, and total cost of ownership across typical industrial deployments.
- Vendor benchmarking and capability matrices covering product families, interfaces (serial, CAN, networked protocols), ruggedization, field calibration practices, and OEM/aftermarket positioning.
- Practical go-to-market playbooks for OEMs, channel partners, and service providers: pricing band guidelines, bundling options (sensor + cloud analytics), and specification checklists for procurement teams.
- Risk and compliance heatmaps addressing manufacturing quality, supply continuity, and certification readiness — including examples of ISO-driven manufacturing practices that matter to large infrastructure buyers.
- Field validation protocols and sample dashboard templates that shorten time-to-value for pilot projects and accelerated rollouts.
- An interactive financial model (delivered with the report) that allows executives to stress-test demand, margin, and investment scenarios for 2026 planning cycles.
Note: while this brief shares high-level market facts and strategic direction, the report contains granular regional and application-level segmentation, pricing benchmarking data, and vendor share-breakdowns that are available exclusively in the full publication.
Strategic implications for 2026 corporate decisions
- R&D prioritization: Invest in MEMS-based platforms for most mainstream industrial and infrastructure use cases where size, power, and cost deliver the best ROI. Reserve force-balance and optical solutions for ultra-high-precision or mission-critical geotechnical monitoring where lifetime performance outweighs unit cost.
- Productization and system offers: Move up the value chain with sensor-to-analytics bundles. Customers increasingly buy outcomes (reduced downtime, predictive maintenance alerts, compliance reporting) rather than raw sensor units.
- Channel and partnership strategy: Build strategic partnerships with system integrators and asset managers who control specification in brownfield and greenfield projects. For OEMs, modular tilt-sensor OEM kits with standardized digital interfaces reduce time-to-integration.
- M&A and investment screening: Prioritize targets that offer unique system integrations, firmware differentiation (on-device edge processing), or certificated quality systems that lower procurement friction for public-sector infrastructure projects.
- Supply-chain resilience: Seek suppliers with quality certifications and diversified component sourcing; certification continuity is increasingly a procurement gate for infrastructure contracts.
Competitive landscape — who matters now and why
The market’s supplier ecosystem is a mix of specialist sensor manufacturers, industrial OEMs, and niche engineering firms. PW Consulting’s competitive assessment focuses on capability sets that matter for 2026 buyers — precision envelope, interface flexibility, ruggedization, and system-level support.
- Jewell Instruments (Manchester, NH, USA) — Strong product breadth across single-, dual-, and tri-axis MEMS and force-balance inclinometers with multiple interface options. Their combination of industrial-grade outputs and field-proven ruggedization makes them a go-to for mixed-use portfolios.
- GEOKON (Lebanon, NH, USA) — Market-recognized specialist for geotechnical monitoring systems. Their in-place inclinometer (IPI) and spiral probe offerings cater to slope stability and long-term civil instrumentation programs, where integrated system design and data continuity are prioritized.
- US Digital (Vancouver, WA, USA) — Offers absolute optical and networked digital inclinometers with full 360° measurement and high resolution. Their networked architectures target distributed sensing use cases — e.g., solar arrays and dredging operations — where remote diagnostics matter.
- Level Developments Ltd (Croydon, UK) — OEM-focused supplier with strong footholds in solar tracking and industrial tilt sensing. Their catalogue demonstrates how temperature compensation and interface standardization reduce integration risk for system buyers.
- Rieker Inc (Aston, PA, USA) — Focused on vehicle and mobile-equipment tilt monitoring (boom angle, tip-over protection), representing the niche where application-specific ruggedness and certification are decisive.
- Fredericks Company (Huntingdon Valley, PA, USA) — Known for precision analog/digital inclinometers across wide angular ranges; their depth in specification-level products makes them a preferred partner for calibration-sensitive industrial use.
- TE Connectivity (Schaffhausen, Switzerland) — Global OEM with the AXISENSE series and embedded interfaces like CAN J1939, positioning them strongly for heavy equipment and platform-level safety systems.
From a market structure perspective, the top three suppliers account for a meaningful share of industry revenue, with the top five representing a majority position — a configuration that favors both established global suppliers and well-positioned regional specialists. This concentration level creates opportunities for focused players to win by specialization (e.g., power-optimized MEMS modules, certified geotechnical suites) and for larger players to pursue inorganic consolidation where scale accelerates platform adoption.
Industry dynamics: standards, quality, and the dominance of MEMS
Three persistent dynamics will influence procurement and product strategy in 2026:
- Standards and quality assurance: Certification continuity — exemplified by recent ISO 9001 follow-up audits in the industry — increasingly functions as a procurement filter for infrastructure and public procurement. Buyers value vendors who can demonstrate consistent manufacturing controls and quality processes.
- Technology convergence: MEMS technology has emerged as the dominant technical approach for mainstream digital inclinometers thanks to its favorable precision-to-cost ratio, compactness, and low power consumption. That creates a baseline expectation for many applications, while optical and force-balance technologies retain niches requiring extreme resolution or environmental robustness.
- Systems-level adoption: Demand is shifting from sensor procurement to integrated monitoring systems. Use cases like structural health monitoring, solar tracker optimization, and industrial safety are driving procurement toward sensors embedded in data platforms and service contracts.
Recent vendor moves illustrate these dynamics: certification updates that reassure large buyers, product introductions that push MEMS resolution and response times, and catalog refreshes that target solar and industrial segments with temperature-compensated, interface-rich devices. PW Consulting’s fieldwork shows that these micro-events materially change procurement conversations and selection criteria in 2026.
Recommended playbook: three immediate actions for 2026
- For manufacturers: tighten firmware and interface ecosystems to enable sensor-as-a-service models; invest in edge analytics and standardized connectivity to shorten integration cycles.
- For system integrators and asset owners: run pilot programs that bundle sensors with analytics and SLA commitments; use PW Consulting’s field validation templates to quantify the operational ROI within three to six months.
- For investors and corporate development teams: prioritize targets that deliver either clear system integration advantages (software + sensor) or that hold certification/quality processes minimizing procurement friction in public projects.
Conclusion and access to full intelligence
As organizations finalize 2026 investment plans, the Digital Inclinometer Market presents both clear growth opportunities and nuanced supplier-selection challenges. PW Consulting’s report equips executives with a decision-grade toolkit: validated market sizing (base year 2025, forecast 2026–2032, CAGR 6.3%), actionable vendor intelligence, and practical deployment playbooks. The full report contains the granular segmentation, pricing bands, and vendor-share tables that procurement teams and product strategists rely upon; those detailed elements are reserved for the complete document.
To obtain the full report, interactive model, and vendor benchmark appendices, visit our Digital Inclinometer Market page or contact PW Consulting’s industry practice. Use the intelligence to convert 2026 uncertainty into competitive advantage.
For detailed analysis of this topic, please visit the official page: Digital Inclinometer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com