

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: IT & Electronics
PW Consulting Forecast: DDR5 RDIMM Memory Interface Chip Market Set to Reach USD 7,930.15 Million by 2032, Growing at a 20.45% CAGR
By pmarketresearch, 2026-07-02
DDR5 RDIMM Memory Interface Chip Market: Strategic Intelligence for 2026 Decision-Making
Executive summary
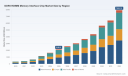
PW Consulting's new market study on the DDR5 RDIMM Memory Interface Chip market provides actionable intelligence tailored for technology leaders, procurement heads, and corporate strategists preparing for 2026 and beyond. The market has moved from niche adoption to rapid commercialization: total industry revenue expanded from USD 350.0 Million in 2020 to USD 2,150.5 Million in 2025, and our forecast shows an acceleration toward USD 7,930.15 Million by 2032. The market's structural trajectory through the 2026–2032 forecast window implies a compounded annual growth rate (CAGR) of 20.45%, underpinning significant strategic implications for suppliers, OEMs, hyperscalers and system integrators.
DDR5 RDIMM Memory Interface Chip Market
Why this report matters for 2026 strategic choices
-
Timing and investment prioritization: With an inflection point between 2025 and 2026, organizations must decide whether to accelerate investments in DDR5-enabled server architectures or adopt a wait-and-see posture. Our study isolates the timing risk and reward profiles across product, supply-chain, and go-to-market moves.
DDR5 RDIMM Memory Interface Chip Market -
Sourcing and supplier risk mitigation: The memory interface chip layer is rapidly consolidating—top-three vendors control over 85% of the market concentration, and the top-five exceed 96%—making single-supplier dependency a material operational risk. The report provides sourcing playbooks to diversify exposure without sacrificing integration performance.
DDR5 RDIMM Memory Interface Chip Market -
Cost-to-performance optimization for AI and cloud workloads: As DDR5 RCD and PMIC innovations drive module performance and power profiles, procurement and platform engineering teams must reassess TCO assumptions. Our analysis translates chipset-level performance upgrades into platform-level cost impacts across typical enterprise deployment scenarios.
Market dynamics and structural drivers
Several concurrent forces are shaping the DDR5 RDIMM interface market as it moves into mainstream server adoption. Demand drivers include sustained AI training and inference deployments, hyperscale cloud expansions, and the upgrade cycle from DDR4 to DDR5 in enterprise data centers. On the supply side, innovation in registered clock drivers (RCDs), data buffers, and power management ICs (PMICs) is enabling higher speeds and better thermal profiles, accelerating module-level adoption.
From a macro perspective, the market grew more than sixfold between 2020 and 2025, reflecting rapid product maturation, and our bottom-up forecast points to a multi-billion-dollar opportunity by the end of the decade. This growth coexists with short-term noise—tariff adjustments introduced in 2025 that shifted sourcing patterns and near-term pricing volatility for DRAM and modules driven by AI demand—which collectively create both tactical risks and strategic windows for incumbents and new entrants.
Competitive landscape: who matters and why
The market is highly concentrated, with a few specialized players dominating the memory interface chipset layer. Key vendors combine chipset depth, IP portfolios, and supply-chain scale to win design cycles with server and module manufacturers. Our research highlights several strategic archetypes among market leaders:
-
Platform integrators focused on end-to-end module solutions: These firms provide integrated RDIMM chipset stacks—registered clock drivers, PMICs, SPD hubs and sensors—positioning themselves as turnkey partners for module houses and OEMs. Their value proposition centers on validated performance at higher data rates and accelerated time-to-market for RDIMM designs.
-
Component specialists with thermal and power differentiation: PMIC-focused companies emphasize energy efficiency and thermal integration, an increasingly important attribute as module densities climb and AI workloads stress power envelopes.
-
Regional-scale production players: A mix of firms are targeting volume scaling and cost-competitive mass production for Gen4 implementations to capture share during the mainstreaming phase of DDR5 adoption.
Representative companies covered in the study include Rambus, Renesas Electronics, Montage Technology, Texas Instruments, Analog Devices and Infineon Technologies. The report examines each firm’s strategic positioning, product roadmap focus (RCD, DB, PMIC, SPD hubs), go-to-market motions, and recent milestones—such as product launches, mass production ramp-ups, and industry recognition—that materially affect competitive dynamics.
Recent vendor developments with strategic implications
-
Rambus: Recognized in April 2026 with an industry award for its DDR5 RDIMM 8000 chipset, signaling strong validation of its high-bandwidth product strategy for AI and data center applications.
-
Renesas Electronics: In November 2025, introduced what it describes as an industry-first Gen6 DDR5 registered clock driver targeting next-generation server RDIMMs—an important leap for customers planning multi-generation roadmaps.
-
Montage Technology: Announced mass production of Gen4 RCD silicon in late 2025, reflecting the industry’s move from early adopter volumes to broader production-scale deployments.
Practical contents of the PW Consulting report (what’s inside)
Our market report is structured to be operationally useful to business leaders and technical decision-makers. It includes:
-
Market size and forecast model: A transparent, bottoms-up revenue model covering historical performance (2020–2025) and a detailed forecast (2026–2032) with sensitivity scenarios. The report documents our core assumptions and provides scenario outputs calibrated to demand, pricing, and adoption curve variables.
-
Technology and product taxonomy: Detailed mapping of the DDR5 RDIMM interface stack—RCDs, data buffers, PMICs, SPD hubs—and the functional and thermal trade-offs relevant for server and AI module designs.
-
Vendor scorecards and strategic playbooks: Comparative assessments of incumbents and challengers across product performance, roadmap breadth, integration support, manufacturing footprint, and go-to-market capabilities. Each scorecard is paired with a recommended playbook for purchasers and a partnering checklist for suppliers.
-
Supply-chain and tariff impact analysis: An examination of recent regulatory moves, tariff adjustments and sourcing shifts, showing how procurement strategies and geography of supply may alter cost and lead-time dynamics.
-
Use-case-driven TCO models: Module- and system-level examples that translate chipset choices into total cost of ownership for representative cloud and enterprise workloads.
-
Market concentration and competitive scenarios: Analysis of consolidation risk, barriers to entry, and likely competitive outcomes under high- and low-growth scenarios.
How to apply the findings in 2026 planning cycles
-
Procurement: Use the vendor scorecards and TCO models to revise supplier qualification criteria—prioritize proven high-speed RCD performance and robust PMIC thermal integration when negotiating multi-year contracts.
-
R&D and platform roadmaps: Align module validation timelines with the product roadmaps of primary RCD and PMIC vendors; accelerate lab validation for Gen4/Gen6 silicon if your workloads require sub-8000 MT/s performance in 2026 deployments.
-
M&A and partnership scouting: The high concentration suggests attractive bolt-on targets for system suppliers seeking vertical integration; our report identifies capability gaps where acquisitions or JV structures could create differentiated module offers.
-
Risk management: Model single-source exposure scenarios and execute contingency plans—second-source validation and phased adoption pathways are included in our pragmatic checklist.
Methodology and data integrity
The study combines primary interviews with module OEMs, chipset vendors and hyperscale IT architects, with secondary triangulation using shipment and pricing data, public filings, and regulatory disclosures. Our forecast employs a bottom-up approach, building revenues from device-level adoption curves and validated bill-of-material assumptions. All major assumptions are documented and sensitivity-tested to provide transparent decision levers for corporate planning teams.
Limitations and the PW Consulting “preview” approach
Consistent with the report’s intent to be a strategic decision tool, this announcement highlights the major market trajectories, competitive dynamics, and practical frameworks. To preserve the tactical exclusivity that many clients require, the detailed segment-by-segment revenue tables, regional breakouts, and full vendor share matrices are provided only in the full report. This “preview” is designed to answer the question of “why it matters” while prompting deeper examination of “where specifically” to allocate capital and engineering resources.
Key takeaways for executive teams
-
The DDR5 RDIMM interface market is at a rapid scale-up phase; total industry revenue reached USD 2,150.5 Million in 2025 and is projected to approach USD 7,930.15 Million by 2032 under our base case.
-
Market concentration is high—the top three and top five vendors dominate—so vendor selection and multi-sourcing strategies will materially affect cost, lead times, and design flexibility.
-
Recent product launches and mass-production ramps indicate both performance headroom (Gen6 roadmaps) and production readiness (Gen4 volumes), which require synchronized platform validation plans.
-
Tariff shifts and DRAM pricing volatility create immediate operational noise; however, medium-term demand from AI and hyperscale workloads supports sustained market expansion.
Next steps and how to get the full analysis
For executive teams and technical leaders who need the granular revenue matrices, regional and application breakdowns, detailed vendor market-share tables, and downloadable financial models, PW Consulting makes the complete DDR5 RDIMM Memory Interface Chip Market report available through our research portal. The full report contains the tables, charts, and step-by-step playbooks required to translate market intelligence into 2026 investment and procurement decisions.
Contact PW Consulting’s Market Intelligence team to schedule a briefing and obtain the complete dataset and actionable recommendations.
For detailed analysis of this topic, please visit the official page: DDR5 RDIMM Memory Interface Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Embedded Storage (eMMC & UFS) Market to Surge at 15.02% CAGR, Hitting USD 10.9B by 2032
By pmarketresearch, 2026-07-02
Automotive Embedded Storage (eMMC & UFS) Market: Strategic Imperatives for 2026
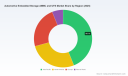
As vehicles continue their transformation into data-centers-on-wheels, embedded storage has moved from a component line-item to a strategic enabler of user experience, safety and software-defined value capture. PW Consulting’s latest Automotive Embedded Storage (eMMC & UFS) Market report — built on a 2025 base year and a 2026–2032 forecast horizon — quantifies that transition. The market expanded from roughly USD 3.15 billion in 2023 to USD 4.10 billion in 2025 and is projected to reach approximately USD 10.91 billion by 2032, reflecting a compound annual growth rate (CAGR) of ~15.02% across the forecast period. For executive teams planning 2026 investments, procurement cycles, qualification roadmaps and M&A activity, these macro dynamics create both urgency and optionality.
Automotive Embedded Storage (eMMC and UFS) Market
What the report delivers — practical, decision-ready content
- Forward-looking market sizing and scenario-based forecasts (2026–2032) with sensitivity to NAND supply, pricing and adoption curves for eMMC and UFS.
- Buyer playbooks for procurement and qualification: realistic timelines, contract structures, inventory strategies and sample/qualification pathways for automotive OEMs and Tier-1 suppliers.
- Vendor benchmarking and scorecards: multidimensional profiles covering product maturity, automotive-grade qualification status, performance-per-watt, functional-safety support and aftermarket reliability evidence.
- Supply-chain and risk maps: concentrated production footprints, geopolitical exposure analysis, tariff and export-control scenarios, and contingency sourcing templates.
- Technical guidance for systems architects: design trade-offs between eMMC and UFS (cost, throughput, power, lifecycle), recommended interfaces for IVI, ADAS and telematics modules, and memory-stack optimization patterns.
- Hands-on commercial tools: pricing sensitivity models, contract negotiation levers (price collars, allocation commitments, volume-flex clauses), and an M&A/partnering framework targeting controller and NAND specialists.
Market dynamics shaping 2026 decisions
- Rapid market growth with elevated supply-side risk — The double-digit CAGR illustrates structural demand from richer infotainment stacks, data-logging for autonomy, and in-vehicle AI workloads. That demand is colliding with persistent NAND supply tightness and strategic production shifts by major suppliers, creating near-term allocation pressure for automotive-qualified eMMC and UFS parts.
- Price and allocation volatility — Contract and spot NAND prices rose into early 2026, increasing component costs for embedded storage. Procurement teams must model both price risk and delivery risk simultaneously; doing so will change how procurement prioritizes capacity reservations versus spot buys.
- Qualification cadence is a gating factor — Automotive qualification cycles for eMMC/UFS typically span 18–24 months. This creates durable demand lock-in for suppliers that achieve early qualification and implies that design and sourcing decisions made in 2026 will influence product roadmaps and supplier relationships well into 2028.
- Functional safety and regulatory overlay — AEC-Q100 and ISO 26262/ASIL requirements remain non-negotiable for ADAS and safety-adjacent storage. Suppliers with demonstrable ASIL-compliant solutions and long-tailed reliability data will command pricing and allocation advantages.
- Concentration and supplier power — The embedded storage market shows high concentration, with the top three suppliers accounting for a substantial majority of market share and the top five covering nearly nine-in-ten of the market. This structure amplifies supplier negotiating power, but also concentrates systemic risk if one node experiences capacity or trade disruptions.
- Geopolitical and supply-chain exposure — Global NAND production is heavily concentrated in Asia. That concentration introduces geopolitical risk vectors — export controls, tariffs and localized disruptions — which must be part of any sourcing or contingency planning exercise.
Competitive landscape — who matters and why
The competitive set combines large, vertically integrated memory manufacturers, controller specialists and regional players that focus on automotive-grade reliability. Key strategic considerations by supplier type include:
Automotive Embedded Storage (eMMC and UFS) Market
- Vertically integrated NAND leaders (e.g., major memory houses): offer depth in manufacturing scale, advanced process nodes and broad automotive-focused portfolios. Their strengths are supply stability (when capacity is allocated) and early access to high-density NAND generations.
- Controller specialists and system integrators: provide the firmware, controller IP and validation necessary to optimize UFS/eMMC in complex cockpit and ADAS platforms. Their validation on major vehicle SoCs creates a practical adoption pathway for OEMs.
- Regional and niche suppliers: focus on endurance, extended temperature ranges and automotive qualifications. These players are critical fallback partners for niche programs and aftermarket support.
Recent product and validation developments underscore technology momentum and competitive moves into automotive: a leading memory supplier began shipping qualification samples of an automotive UFS 4.1 solution built on G9 NAND and touting ASIL-B compliance; other players introduced UFS 4.1 samples and early UFS 5.0 evaluations; and controller vendors completed compatibility validation on prominent cockpit-class SoC platforms. These events accelerate OEMs’ ability to architect higher-performance storage stacks but also compress windows for supplier selection.
Automotive Embedded Storage (eMMC and UFS) Market
Strategic implications and recommended 2026 actions
Based on our analysis, PW Consulting recommends a multi-track approach that balances near-term risk mitigation with medium-term capability capture:
- Procurement: Move from annual spot buys to multi-year allocation agreements with clarity on volume, performance classes and price adjustment mechanisms. Negotiate explicit allocation guarantees for automotive-qualified parts and include reciprocal technical support commitments (e.g., co-engineering and failure-analysis SLAs).
- Qualification & Design: Start or accelerate qualification programs in H1 2026 for any platforms targeting 2028–2029 production. Treat qualification as a strategic barrier — securing early-qualified suppliers locks-in supply and reduces rework risk. Design teams should standardize interfaces to allow late-stage downgrades/upgrades (e.g., UFS-capable controllers that can operate with eMMC during shortage scenarios).
- Technology choices: Align storage architecture to product tiers. For high-performance IVI and ADAS domains, favor UFS generations that provide the necessary throughput and power efficiency. For cost-sensitive telematics or entry-level modules, validated eMMC solutions still offer compelling TCO. However, avoid rigid bifurcation: build BOM flexibility that anticipates rapid UFS adoption.
- Inventory & hedging: Consider strategic buffer stocks for critical SKUs and negotiate price-collar or index-linked contracts to mitigate spot price swings. Where capacity is tight, allocate a portion of your spend to upstream partners to secure wafer or die-level allocations as part of a vertical sourcing strategy.
- Supplier portfolio and partnerships: Diversify across vertically integrated NAND leaders and specialized controller vendors. Prioritize suppliers with proven automotive qualifications, ASIL support and demonstrated validation on target SoC platforms. For OEMs pursuing cockpit differentiation, early co-development agreements with controller/IP vendors can be a competitive advantage.
- M&A & innovation plays: For companies looking to enter or scale in this space, target assets that shorten qualification cycles (e.g., controller IP, firmware teams) or provide unique value-add (secure storage, endurance-enhancing firmware). Smaller acquisitions can be effective bolt-ons to accelerate time-to-market without incurring the long lead-time of in-house development.
- Risk & compliance: Embed scenario planning for geopolitical shock, export-control changes and supplier outages into 2026 budgeting cycles. Build dual-source and near-shore options for critical programs where feasible.
Decision roadmap and timing for 2026
- Immediate (Q1–Q2 2026): Freeze qualification roadmaps for 2028-bound platforms; initiate allocation negotiations with primary suppliers; conduct BOM flexibility audits.
- Near term (Q3–Q4 2026): Execute multi-year contracts with allocation and price mechanics; begin co-validation with chosen controller partners; formalize inventory hedging where justified.
- Medium term (2027): Operationalize supplier partnerships in production-intent runs; reassess portfolio by product tier and transition modules to higher-performance UFS where ROI and supply permit.
What we are deliberately withholding — and why
In keeping with the “trailer” principle that guides PW Consulting’s release strategy, this public summary intentionally highlights macro sizing, concentration metrics and strategic implications while withholding granular subsegment tables and raw numerical worksheets (e.g., detailed regional splits, application-specific revenue lines and per-supplier volumetric allocations). Those detailed datasets and interactive models are essential for program-level procurement negotiations and engineering BOM decisions; they are available exclusively in the full report and accompanying data workbook. The intent is to provide enough diagnostic clarity to inform executive strategy while preserving the detailed intelligence that operational teams require to execute supplier selection and contractual arrangements.
Final note — why 2026 matters
Decisions made in 2026 will disproportionately shape supplier relationships, product architectures and cost curves through the late-2020s. With a market expanding at roughly 15% annually and facing persistent supply-side stressors, OEMs and Tier-1s who coordinate procurement, qualification and design strategy now will gain preferential access to capacity, protect margins and accelerate time-to-market for differentiated cockpit and ADAS experiences. PW Consulting’s full Automotive Embedded Storage (eMMC & UFS) Market report provides the granular forecasting, supplier scorecards and commercial tools needed to operationalize these strategic recommendations. For teams preparing 2026 budgets and sourcing plans, the question is not whether to act — but how quickly and with which partners.
For detailed analysis of this topic, please visit the official page: Automotive Embedded Storage (eMMC and UFS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Display Driver IC Wafer Foundry Market Set to Expand at a 6.55% CAGR Through 2032
By pmarketresearch, 2026-07-02
DDIC Wafer Foundry Services Market: A 2026 Strategic Playbook for Executives
As demand patterns in displays continue to bifurcate between high-volume mobile and large-area panels, and as foundry capacity is reallocated across adjacent semiconductor priorities, Display Driver IC (DDIC) wafer foundry services have risen to a strategic inflection point. PW Consulting’s latest market research — anchored on a 2025 base year and projecting through 2032 — quantifies this transition and translates it into executable guidance for 2026 decision-making. This release is a preview: we reveal the analytical framing, directional market architecture and practical implications for corporate strategy, while preserving the granular segment tables and proprietary model outputs for subscribers of the full report.
Display Driver IC (DDIC) Wafer Foundry Services Market
Market trajectory: what the numbers tell us
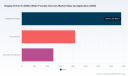
Our top-line modelling traces a clear and durable expansion of the DDIC wafer foundry services market. The market rose from an estimated USD 5,120 Million in 2020 to roughly USD 7,250 Million in 2025 (base year), and is forecast to reach approximately USD 7,928 Million in 2026. Under the central-case assumptions embedded in the report, the market expands at a compound annual growth rate (CAGR) of 6.55% over the 2026–2032 forecast window, culminating in a projected market size north of USD 11,300 Million by 2032.
Display Driver IC (DDIC) Wafer Foundry Services Market
Two quantitative takeaways frame the strategic context for 2026: first, momentum is steady rather than explosive — the market is entering an expansionary but competitive phase; second, market concentration is material, with the top three and top five foundries together controlling a substantial majority of wafer supply. These concentration dynamics create both negotiating leverage for leading foundries and procurement vulnerabilities for OEMs and IDMs that rely on single-source or single-region supply.
Display Driver IC (DDIC) Wafer Foundry Services Market
Why this matters to 2026 corporate strategy
- Procurement and cost management: With foundries signaling price adjustments for mature nodes and OSAT costs trending higher, 2026 will be a year when firms must decide whether to accept short-term cost inflation, renegotiate supply terms, or accelerate qualification of alternative suppliers.
- Capacity and node allocation: Reallocation of capacity in Taiwan and South Korea toward high-priority PMIC and advanced-node logic impacts DDIC lead times. Firms will need scenario plans that align product roadmaps with available node capacity and qualification timelines.
- Risk and resilience: Geopolitical controls and equipment restrictions targeting specific geographies introduce asymmetric risk. Supply diversification and contingency sourcing are no longer optional defensive measures.
- M&A and partnership timing: Market concentration and the rise of specialist foundries create windows for strategic investments, minority stakes, JV structures or long-term offtake agreements that secure capacity and technology access.
What’s inside the full PW Consulting report (practical deliverables)
The full report is built for immediate operational use by procurement, product strategy, and corporate development teams. Core deliverables include:
- Proprietary demand-supply model with scenario-based outputs (fast-growth, baseline, downside) so teams can stress-test product launch timelines against likely wafer availability and price paths.
- Foundry scorecards and qualification roadmaps for mature (90nm and above), mid-range (40–65nm) and advanced mature (sub-40nm) DDIC process options, including cycle-time, yield sensitivity and tooling constraints.
- Price-pass-through and margin impact simulations calibrated to observed wafer price adjustments and raw material trends since 2025, enabling finance teams to model gross margin and ASP sensitivity under multiple market scenarios.
- Negotiation playbook and term-sheet templates for securing mid- to long-term wafer commitments, with clauses designed for capacity shifts, technology upgrades and force majeure covering export-control disruptions.
- M&A heatmaps, partnership match-making matrices and a prioritized target list for strategic investment, including runnable valuation corridors that reflect DDIC-specific economics and concentration risk.
- Regional risk assessment and contingency maps that translate geopolitical and export-control exposure into actionable sourcing shifts and certification plans.
Note: this preview omits the detailed region-by-region and application-by-application allocation tables. Those segment-level splits are available exclusively in the subscription release, which includes downloadable model workbooks for client-specific stress-testing.
Competitive landscape — who matters and why
The DDIC foundry ecosystem is a mix of global integrated leaders, large pure-play foundries, and regionally specialized providers. The competitive set we profile in the report includes leading incumbent foundries and rising regional players. High-level implications:
- TSMC (Hsinchu, Taiwan): The global lead in volume and node breadth. TSMC’s ability to supply both mature and select advanced processes for DDIC, combined with its scale, gives it leverage in shaping pricing and allocation in 2026.
- Samsung Foundry (Suwon, South Korea): Offers high-voltage platforms and benefits from an integrated display ecosystem. Its premium-tier capabilities make it a go-to for AMOLED-focused DDICs.
- UMC (Hsinchu, Taiwan): Strength in specialty and high-voltage processes; important for customers needing targeted analog/high-voltage solutions in mature nodes.
- GlobalFoundries (Malta, NY): Competes on stable, proven high-voltage platforms in mature nodes — a predictable partner where yield and reliability trump bleeding-edge scaling.
- Vis/Hua Hong/SMIC/Nexchip/Vanguard: A group of regional and specialist foundries that collectively reshape supply dynamics. Chinese players in particular have accelerated expansion in large-area DDIC production.
Market concentration metrics underline the strategic calculus: the top three and top five foundries together control a dominant share of capacity. For buyers, this means negotiating power is uneven; for investors, scale and process breadth remain differentiators.
Recent market moves and near-term catalysts
Several events in early 2026 crystallize the environment in which 2026 decisions must be made:
- Capacity reallocation and price moves: Taiwanese and South Korean foundries have shifted allocation toward PMICs and advanced logic, creating tighter supply for large-area DDIC wafers. Multiple foundries signaled price adjustments for mature nodes in H2 2026, creating immediate procurement implications.
- Regional expansion and capital raises: Chinese specialists have moved aggressively to expand mature-node fabs. Strategic capital actions — including listing applications to fund expansions — are reshaping the geographic distribution of DDIC capacity.
- Input-cost inflation: Rising OSAT, wafer and precious-metal costs (e.g., bumping materials) are exerting margin pressure and raising the odds of cost pass-through to OEMs.
- Policy and export controls: U.S. export restrictions and tighter equipment shipments to some Chinese foundries create asymmetric growth constraints and an acceleration of localization strategies by affected suppliers.
Actionable strategic recommendations for 2026
- Dual-track supplier strategies: Implement primary-secondary foundry relationships structured by product tier and node class. For new product introductions, reserve qualification cycles across at least two geographies.
- Lock and layer pricing: Use a combination of short-term fixed-price tranches and longer-term index-linked agreements to manage inflationary spikes while preserving supplier commitment.
- Prioritize node-fit over headline node numbers: For display drivers, maturity of analog/high-voltage process and yield experience often matter more than the nominal nm label. Allocate engineering resources to validation of process variants rather than chasing node hierarchy.
- Commodity and OSAT hedging: Establish procurement hedges for key bumping and substrate materials; explore preferred supplier agreements with OSAT partners to secure downstream assembly capacity.
- Strategic finance moves: Consider minority investments or prepayment capacity agreements with regional foundries that can materially reduce lead times and lock in expansion priority.
- Prepare export-control playbooks: Map critical supply chains that intersect with restricted equipment or materials and create pre-approved alternate flows and qualification paths.
How to convert this insight into 90‑day and 12‑month plans
Within 90 days: run the report’s scenario model against your SKU-level demand; identify top three wafers by spend and initiate secondary-qualification programs where single-sourced. Negotiate a short-term price-and-capacity tranche with critical foundries to cover Q3–Q4 2026 exposure.
Within 12 months: finalize bilateral or JV capacity agreements for critical mature-node DDIC production, restructure supplier scorecards to include export-control exposure and materials-risk indices, and incorporate the report’s margin-sensitivity outputs into product-pricing decisions and investor disclosures.
Next steps and access to the full intelligence
This executive preview is designed to surface the market dynamics and operational levers that will shape pragmatic decision-making in 2026. The full PW Consulting DDIC Wafer Foundry Services Market report contains the complete segmentation matrices, downloadable forecast models, supplier playbooks and a confidential appendix with contract language and recommended term structures.
For procurement leaders, product and manufacturing executives, and corporate development teams preparing 2026 roadmaps, the report is an immediately actionable toolset. Access to the full dataset, granular regional/application splits, and bespoke modelling support is available through PW Consulting’s client portal — detailed instructions and subscription options are provided on the report landing page.
Contact PW Consulting to schedule a briefing and modelling workshop that tailors the report’s outputs to your enterprise’s product portfolio and sourcing footprint.
For detailed analysis of this topic, please visit the official page: Display Driver IC (DDIC) Wafer Foundry Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Hydrocarbon & PTFE Resin High-Speed Digital CCL Market Poised to Grow at a 9.2% CAGR Through 2026–2032
By pmarketresearch, 2026-07-02
Hydrocarbon and PTFE Resin High‑Speed Digital CCL Market: Strategic Imperatives for 2026 Decision‑Making
As PW Consulting publishes its latest market study on Hydrocarbon and PTFE Resin High‑Speed Digital Copper Clad Laminates (CCL), this briefing highlights the strategic value the report delivers to executives preparing to make critical choices in 2026. Grounded in rigorous historical analysis (2020–2025) and forward looking to 2026–2032, our research synthesizes commercial, technical and regulatory forces shaping a market that is re‑rating for performance, supply resilience and regulatory volatility.
Hydrocarbon and PTFE Resin High-Speed Digital Copper Clad Laminate (CCL) Market
Why this report matters for 2026
-
A rapidly expanding market: Our analysis shows the addressable market rose sharply through the 2020–2025 period and, based on base‑year 2025 calibration, is projected to accelerate through the 2026–2032 forecast horizon at a compound annual growth rate of approximately 9.2%. This trajectory reflects structural demand from hyperscale data centers, 5G infrastructure, automotive radar/ADAS and aerospace/defense segments.
Hydrocarbon and PTFE Resin High-Speed Digital Copper Clad Laminate (CCL) Market -
Decision time for capex and vertical integration: Supply‑side moves in 2024–2026 (capacity expansions, targeted product launches and raw‑material driven margin squeeze) mean that 2026 is a pivot year for manufacturing investments, strategic partnerships and M&A to secure throughput and technology differentiation.
Hydrocarbon and PTFE Resin High-Speed Digital Copper Clad Laminate (CCL) Market -
Concentration and competitive dynamics: The market shows meaningful concentration at the top end (CR3 and CR5 are material, indicating mid‑to‑high consolidation among leading specialist producers). For firms deciding where and how to compete, our report provides the quantitative and qualitative context to choose the right battles.
Market sizing headline (what we disclose here)
-
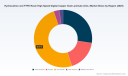
Historical momentum: The global Hydrocarbon and PTFE CCL market expanded from a mid‑three‑hundred million USD base in 2020 to an approximate half‑billion USD level in the base year 2025.
-
Forecast path: Under our central scenario, the market continues to scale through 2032 and approaches the high‑single‑digit hundreds of millions USD threshold by the end of the forecast window, consistent with the 9.2% CAGR cited above.
-
Concentration metrics: Market concentration is significant — our analysis indicates the top three suppliers account for the majority share of specialized high‑frequency/high‑speed products, and the top five further extend that dominance. These dynamics drive bargaining power, supplier selection risk and acquisition rationale.
What the PW Consulting report contains (practical, executable content)
-
Validated market model: A transparent, auditable model covering 2020–2025 historicals and 2026–2032 forecasts. The model is built bottom‑up from demand drivers by application and technology and stress‑tested with scenario overlays reflecting raw material shocks and regulatory outcomes.
-
Segmentation framework (methodology, not just numbers): We break the market into technology buckets (PTFE‑based, hydrocarbon‑based, ceramic‑filled hybrids), applications and regions, with demand drivers and elasticity assumptions for each. To preserve the value of the full dataset — and to avoid disintermediating subscribers — we withhold granular segment tables in this release; full segment detail is accessible via the report portal.
-
Supply chain and cost curve analysis: Mapped supplier footprint, lead times, capex schedules and a marginal cost curve that quantifies sensitivity to PTFE and hydrocarbon resin pricing. This includes hedging considerations and a supplier risk heatmap.
-
Competitive benchmarking and value‑chain positioning: Objective scorecards for incumbents and challengers across product breadth, capacity, price positioning, service, certification and technology roadmap.
-
Regulatory and raw‑material impact assessment: A compliance cost matrix evaluating proposed chemical regulations, trade measures and raw material concentration risk on BOM and margins.
-
Commercial playbooks and go‑to‑market guidance: Practical routes for premiumization, cost‑leadership and channel expansion tailored to different company profiles — OEM suppliers, captive producers, and pure‑play laminate manufacturers.
-
M&A and partnership pipeline: Prioritized targets (by capability and geography), valuation heuristics and integration risks for buyers seeking inorganic growth to acquire scale or specialized tech.
-
Scenarios for 2026 tactical planning: Three actionable scenarios (Base, High‑Growth, Disruption) with trigger points, KPIs and contingency playbooks for procurement, manufacturing and commercial teams.
Competitive landscape — who matters and why
Our report profiles incumbents and fast movers, capturing capability, recent investments and the strategic posture that will determine winners through 2026 and beyond. Highlights include:
-
Rogers Corporation (Chandler, AZ) — a leader in hydrocarbon‑ceramic laminates and PTFE offerings. Recent capacity additions in Europe strengthen its position for defense and automotive radar markets. Their product range and manufacturing flexibility make them a natural supplier to high‑margin, low‑volume segments.
-
AGC Inc. (Tokyo) and Taconic (part of AGC) — AGC’s HF series and PTFE resin systems position it strongly across sub‑6 GHz and mmWave applications. Taconic brings specialized PTFE expertise in North America, enhancing AGC’s global technology stack.
-
Isola Group (Chandler, AZ) — well positioned with a diversified laminate portfolio and an emphasis on manufacturability for high‑speed digital and RF PCBs, focusing on scalable solutions for server and telecom OEMs.
-
Taiwan Union Technology (TUC) and ITEQ (Taiwan) — specialist Taiwanese players with deep ties into the server and telecom supply chains; they are critical for customers prioritizing lead‑time reliability in the Asia supply base.
-
Shengyi Technology (China) — a major regional producer expanding capacity specifically for 5G and data‑center demand. New plant announcements underscore China’s role in meeting volume growth.
-
Panasonic (Japan) — through the MEGTRON line, Panasonic is pushing into ultra‑low loss laminate territory for high‑speed digital servers and network gear, supported by new product introductions aimed at >112 Gbps signaling.
Each of the above profile entries in the full report is accompanied by a supplier scorecard, plant‑level capacity, and an assessment of strategic fit for different customer archetypes. Recent industry moves such as Shengyi’s facility expansion, Panasonic’s MEGTRON product launch, and Rogers’ European capacity increase are interpreted not as isolated events but as portents of a market bifurcation between scale and specialty.
Raw materials, regulation and cost volatility — the near‑term risks
-
PTFE supply concentration and price volatility: High‑purity PTFE is supplied by a small set of global producers, contributing to episodic price swings. Historical pricing and supply observations indicate volatility bands that materially affect margin sensitivity for PTFE‑heavy laminates.
-
Hydrocarbon resin cost pressures: Vendors have announced price increases to offset feedstock and operating cost inflation, which compresses spreads unless passed through to customers via contractual mechanisms.
-
Regulatory uncertainty (PFAS/REACH): Proposed restrictions in major markets introduce compliance and reformulation risk for PTFE‑based systems. The timeline for regulatory impact is asymmetric and could force incremental capex or reformulation costs for manufacturers and OEMs.
What to do in 2026 — five concrete strategic priorities
-
Lock in supplier diversity and early capacity options: Prioritize multi‑source qualification and short‑term offtake agreements to mitigate PTFE supply shocks.
-
Adopt a product tiering approach: Separate commoditized hydrocarbon laminates from premium PTFE‑based offerings in pricing, sales coverage and R&D investment decisions.
-
Embed regulatory watch‑flows into NPI: Ensure product roadmaps include alternative resin formulations and a regulatory impact cost line item to avoid last‑minute redesigns.
-
Prepare conditional M&A and partnership playbooks: Have triggers defined for acquiring scale (to contest commodity tiers) versus acquiring technology (to capture premium mmWave/server segments).
-
Stress‑test margins against raw‑material scenarios: Use the report’s cost curve to run sensitivity analyses that inform pricing strategies and contract structures for 2026 negotiations.
How PW Consulting helps
Our report is designed as a decision‑support toolkit for executives who need to convert market intelligence into capital allocation and commercial action plans in 2026. It blends a transparent market model, supplier‑level due diligence, regulatory scenario planning and executable GTM playbooks. To preserve the commercial utility of the dataset for subscribers, we are intentionally reserving detailed segment tables, regional breakdowns and application‑level monetization maps for the full report.
Next steps
Executives and strategy teams preparing 2026 budgets or M&A roadmaps should request the full report and model to access the complete segmented data and supplier scorecards. PW Consulting can also run tailored workshops to map the report’s scenarios to your capex timeline, procurement strategy and product roadmaps.
For immediate questions or to schedule a briefing with our lead analyst team, please contact PW Consulting. The full dataset, including downloadable models and supplier scorecards, is available to subscribers and licensed purchasers through our report portal.
For detailed analysis of this topic, please visit the official page: Hydrocarbon and PTFE Resin High-Speed Digital Copper Clad Laminate (CCL) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: EV Charging App Market to Soar from USD 2,500.00 Million in 2025 to USD 11,591.11 Million by 2032, Expanding at a 24.5% CAGR
By pmarketresearch, 2026-07-02
PW Consulting Releases Strategic Brief: Electric Vehicle Charging App Market — Essential Intelligence for 2026 Decision-Makers
As electric mobility accelerates into its commercial phase, the software layer that connects drivers, charging infrastructure, utilities and fleet operators is moving from convenience to competitive necessity. PW Consulting’s new market research brief on the Electric Vehicle (EV) Charging App Market synthesizes five years of historical performance with a multi-scenario forecast to 2032 — providing the strategic context executives and product leaders need to make high-stakes choices in 2026.
Electric Vehicle Charging App Market
Market Trajectory at a Glance
The market for EV charging applications has demonstrated steep adoption over the past half-decade, rising from a modest base in 2020 to a robust market size in 2025. Our base-year assessment (2025) places the market at USD 2,500 Million, with a 2026 opening-year projection above USD 3.1 Billion. Under the central scenario, the market expands at a compound annual growth rate (CAGR) of 24.5% across the 2026–2032 forecast window, culminating in a market size that exceeds USD 11.5 Billion by 2032.
Electric Vehicle Charging App Market
Those headline numbers capture more than growth for its own sake. They reflect a structural shift: apps are becoming a primary interface for monetization, energy optimization, regulatory compliance, and customer retention. For companies that control the software stack, the opportunity is substantial; for those that do not, the risk is losing control of pricing, data flows and customer relationships.
Electric Vehicle Charging App Market
Why This Report Matters for 2026 Strategy
- Time-sensitive regulatory inflection points: Policy changes enacted in 2026 — including US NEVI requirements (minimum DC fast-charging configurations, uptime reporting, and payment interoperability) and EU AFIR mandates for real-time data transparency and ISO 15118 compatibility — materially alter product requirements and commercial contracts. Our brief translates these requirements into concrete product and procurement criteria.
- Capital allocation and ROI clarity: With DC fast chargers and Level 2 hardware costs remaining a material portion of deployment budgets, app-level revenue and utilization levers become decisive for project returns. The report connects app monetization models to site-level economics so CFOs can stress-test investment cases in 2026.
- Platform and partnership choices: In a high-growth market, first-mover advantages in integration (open APIs, OCPP, ISO 15118) and marketplace liquidity can lock in long-term value. Our analysis shows which integration capabilities deliver the largest delta in commercial outcomes.
What the PW Consulting Brief Contains (Operational and Strategic Tools)
The report is designed as a decision-support toolkit rather than an academic exercise. Key, practitioner-focused deliverables include:
- Executive dashboards showing historical baseline (2020–2025), opening-year metrics for 2026, and scenario-driven forecasts through 2032.
- Product-market fit matrices for different operator types (public network operators, fleets, workplace/retail hosts, OEMs), with prioritized feature roadmaps tied to regulatory timelines.
- Commercial model templates — freemium, paid subscription, transaction-based and hybrid structures — with sensitivity analyses on take rates and lifetime value under multiple utilization scenarios.
- Procurement checklists and technical specifications that map NEVI/AFIR/UK smart-charging requirements to app capabilities (reliability SLAs, open API endpoints, payment interoperability, and ISO 15118/V2G readiness).
- Vendor evaluation framework and scoring rubric for software platforms and white-label app providers, enabling procurement teams to compare OCPP compliance, integration effort, uptime guarantees, and data ownership terms.
- Implementation playbooks for staged rollouts, including pilot sizing, A/B testing for pricing and reservation features, and safeguards for uptime and payment reconciliation.
- Scenario planning and stress tests for energy constraints, dynamic pricing adoption, and hardware failure modes — with prescriptive mitigations for each.
Competitive Landscape: Who’s Shaping the App Layer
The app layer today is a mix of network operators, pure-play software firms, OEM platforms and aggregator communities. PW Consulting’s competitive chapter profiles the incumbents and innovators that matter most to strategic planners in 2026, including their positioning and go-to-market strengths:
- ChargePoint (Campbell, CA) — A broad public and private charging network with mature mobile capabilities for locating, initiating and paying for sessions across a large footprint. Their app strategy is centered on network scale and enterprise integrations. ( https://www.chargepoint.com)
- EVgo (Los Angeles, CA) — Operator of a leading US fast-charging network with app-based reservation and session management features, positioning on speed and convenience for long-haul drivers. ( https://www.evgo.com)
- PlugShare (part of EVgo; El Segundo, CA) — The dominant aggregator and community-driven mapping platform for charging points, frequently cited for its comprehensive data and trip-planning utility. ( https://www.plugshare.com)
- EV Connect (USA) — Focused on charging management software with an enterprise-grade driver app; recently expanded with a Software+ management console that tightens controls on pricing and utilization analytics.
- Tesla (Austin, TX) — Its Supercharger network and integrated app remain influential, and broadening access to non-Tesla EVs is changing expectations around reservation, authentication and throughput management. ( https://www.tesla.com)
- Blink Charging (USA) — Hardware-to-software provider pairing stations with apps and network services, often competing on bundled solutions. ( https://blinkcharging.com)
- AMPECO (Bulgaria) — Hardware-agnostic, white-label software that appeals to operators seeking rapid launch with brand control and global integrations. ( https://www.ampeco.com)
- ChargeLab (Canada) — A platform focused on flexible integrations (including OCPP support) and operator tools for managing mixed portfolios of chargers. ( https://chargelab.co)
Recent industry movements underscore an acceleration of product innovation and a shift toward utility-grade operations. Notable developments covered in the brief include EV Connect’s 2026 Software+ launch, market commentary from platform specialists predicting broader AI adoption for dynamic pricing and predictive maintenance, and recognition of aggregator platforms for their role in discovery and consumer trust.
Regulatory and Cost Dynamics that Drive Product Requirements
Two converging forces shape app design and commercial viability in 2026:
- Regulation as product constraint: NEVI (US) and AFIR (EU) introduced operational and data transparency requirements in 2026 that elevate technical compliance into a competitive differentiator. Requirements such as minimum fast-charger configurations, uptime reporting and open APIs mean apps must bake compliance into their architecture rather than bolt it on.
- Hardware economics and deployment trade-offs: With DC fast charger installed unit costs remaining in a high range and Level 2 installs materially less expensive, app revenue models and energy management features become key levers to justify higher capital intensity. The report maps how app-enabled features (reservation systems, demand-response, dynamic pricing) alter site-level cash flows and payback periods.
For procurement teams and product owners, this means prioritizing integration standards (OCPP, ISO 15118) and data models that support real-time telemetry, payments and energy management. Our templates translate regulatory text into product acceptance criteria and test cases.
Strategic Recommendations for 2026
PW Consulting’s strategic guidance frames near-term actions that produce the greatest optionality over the forecast horizon:
- Prioritize open APIs and standards compliance: Make OCPP and ISO 15118 support non-negotiable for any partner. This reduces lock-in risk and enables V2G and smart charging monetization.
- Design for regulatory resilience: Build data pipelines and uptime monitoring that satisfy NEVI/AFIR reporting requirements from day one to avoid costly retrofits.
- Deploy layered commercial models: Test freemium entry points while piloting transaction-based premium features (reservations, priority sessions, dynamic pricing) to discover willingness-to-pay without sacrificing scale.
- Use pilots to validate energy strategies: Integrate demand-side management and simple predictive-maintenance telemetry early to demonstrate immediate operating-cost benefits to hosts and site owners.
- Defend customer relationships: For OEMs and infrastructure owners, own the driver experience or secure exclusive data-sharing rights; otherwise, aggregators will capture the touchpoint and influence pricing and loyalty.
Accessing the Full Intelligence
This insight brief is a strategic preview. PW Consulting’s full report contains the granular segmentation, country- and channel-level analyses, vendor scorecards, and downloadable financial models that executives will need to operationalize 2026 plans. In keeping with our “teaser” approach, we have summarized the implications and provided actionable frameworks here while reserving the detailed numerical segment tables and proprietary scoring outputs for the full publication.
For leaders structuring budgets, negotiating vendor agreements, or designing product roadmaps in 2026, the difference between an incremental and a transformative outcome will be shaped by choices documented in this report. Reach out to PW Consulting to obtain the complete research package and the interactive tools that accompany it.
PW Consulting — Strategic clarity for the electric transition.
For detailed analysis of this topic, please visit the official page: Electric Vehicle Charging App Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: HSMT SerDes Chip Market Set to Jump from USD 3,200 Million in 2025 to USD 7,764.6 Million by 2032 on 13.5% CAGR
By pmarketresearch, 2026-07-02
HSMT SerDes Chip Market — Strategic Playbook for 2026
PW Consulting’s new HSMT SerDes Chip Market report provides a timely, decision-ready framework for CIOs, product leaders, supply-chain strategists and investors navigating a market that has more than doubled in size since 2020. Our analysis shows the global HSMT SerDes market expanding from USD 1,720 million in 2020 to USD 3,200 million in the 2025 base year, with a continued trajectory that reaches approximately USD 7,765 million by 2032 under a 13.5% CAGR (2026–2032). For executives planning resource allocation and go-to-market moves in 2026, the implications are clear: the window to solidify platform positions, secure resilient supply chains and capture premium mobility and data-transmission segments is now.
HSMT SerDes Chip Market
Why this report matters for 2026 decision cycles
- Actionable foresight, not forecasts alone. Beyond headline growth, the report decodes the business levers that will determine winners in 2026 — from protocol strategy and PAM4 adoption to tiered sourcing and qualification cycles for automotive-grade silicon.
- Tactical timing for procurement and product roadmap teams. Lead-time dynamics and capacity expansions in 2026 materially affect component allocation for automotive Tier-1s and hyperscale data-center OEMs; our timeline guidance converts market growth into concrete buy/qualify windows.
- Risk-to-reward mapping for investment and M&A. The HSMT SerDes market shows higher concentration among the top manufacturers, underscoring how selective acquisitions or strategic JV stakes can accelerate route-to-market while reducing integration risk.
High-level market dynamics you can trust
- Structural growth driven by automotive and high-bandwidth display needs. Demand for in-vehicle lossless video and sensor aggregation is a primary growth engine. Coupled with expansion in telecommunications and edge networking, this is what sustains a 13.5% compound annual growth through the forecast period.
- Market concentration signals strategic choke points. The competitive landscape demonstrates a relatively concentrated supplier base among top vendors — a dynamic that enables leading suppliers to influence pricing, protocol adoption rates and qualification roadmaps.
- Regulatory and geopolitical tailwinds for localized ecosystems. HSMT’s status as a recommended standard by the China Automotive Standardization Administration, combined with continued U.S. export controls and tariff structures, is accelerating domestic ecosystem development in China and influencing vendor selection and cross-border sourcing decisions.
What the report delivers — practical, executable outputs
PW Consulting’s report is designed for rapid translation into 2026 strategy. It includes:
HSMT SerDes Chip Market
- Market model and sensitivity scenarios that translate macro growth into addressable opportunity by customer class and protocol strategy (full data tables and model inputs are included in the full report).
- Supplier benchmark dossiers with capability matrices, qualification readiness, and commercialization timelines for primary vendors.
- Procurement playbooks: component qualification checklists, sample lead-time hedging strategies and a supplier scorecard adaptable to different risk appetites.
- Regulatory impact analysis: scenario planning for trade-control regimes and standardization milestones that affect certification and market access.
- Go-to-market frameworks for OEMs and Tier-1s: feature-pricing maps, differentiation opportunities around dual-protocol support, PAM4 implementation, and software-enabled value capture.
Competitive landscape — incumbent moves and fast followers
The report profiles the active vendor ecosystem, illustrating how product roadmaps and partnerships are shaping 2026 battlegrounds. Notable themes include rapid productization among Chinese vendors, dual-protocol strategies, and early moves toward higher-rate link products for cockpit and ADAS applications.
HSMT SerDes Chip Market
- Norelsys (China) — Positioned as a leader in automotive HSMT SerDes chipsets, with mass-produced 12G/12.8Gbps products targeting camera and display applications. Norelsys’ broad HSMT portfolio and production maturity make it a key reference for OEM qualification timelines.
- Rsemi (Nanjing Rsemi Technology, China) — Recently showcased a 32Gbps display SerDes (Auto China 2026 debut), signaling a push into high-bandwidth cockpit architectures and revealing where next-generation requirements will concentrate.
- Nanochip (China) — Early mover with 6.4G HSMT solutions positioned as a benchmark for in-vehicle link performance; useful for benchmark and legacy-replacement strategies.
- Ruifa Technology (China) — Demonstrated breadth at major industry exhibitions with mass-produced variants across a broad rate spectrum, underscoring domestic supply-chain depth.
- Velinktech (Venlinktech Microelectronics, China) — Noteworthy for dual-protocol offerings (MIPI A-PHY and HSMT) and a launched PAM4 12.8Gb/s product in mass production with a leading OEM — a model for commercial adoption pathways.
- Naxin Micro & Shouchuan Micro (China) — Represent the wave of firms delivering automotive-grade HSMT implementations that leverage domestic manufacturing and supply-chain integration.
Recent product and commercial milestones (selected)
- Early 2025–2026 product debuts and mass-production announcements have validated the technical feasibility and manufacturability of HSMT SerDes at multiple bandwidth points, reducing technical uncertainty for OEM adoption.
- Automotive OEM engagements and initial model integrations demonstrate that qualification cycles are compressing for established vendors who can deliver automotive-grade quality and supply assurances.
- Exhibitions and partnerships in 2025–2026 have accelerated ecosystem validation, making 2026 a critical junction for vendors and customers to commit to specific protocol roadmaps.
Supply chain, cost and regulatory implications for 2026
Executives must balance multiple, sometimes opposing forces in 2026:
- Lead-time improvements vs. persistent tightness. While industry reports show lead-time improvements for relevant mature nodes (moving into a 16–26 week range amid capacity expansions), adequate inventory strategies remain essential during peak qualification and ramp phases.
- Pricing pressure from adjacent demand. Memory and analog component pricing pressures — driven by AI-related demand spillover — can elevate BOM costs for SerDes solutions and compress OEM margins unless mitigated via long-term procurement or design consolidation.
- Geopolitical risk. Ongoing export controls and tariffs encourage localization in certain markets while elevating transaction costs for cross-border suppliers — a strategic consideration for global OEMs that must balance compliance with performance and cost.
Strategic recommendations for 2026 (prioritized, executable)
- Adopt a dual-path protocol strategy. For OEMs serving multiple geographies, prioritize suppliers that can support both HSMT and alternative standards (e.g., dual-protocol silicon) to minimize regional lock-in and maintain optionality.
- Fast-track qualification with tiered commitments. Use staged volume commitments tied to performance milestones to secure capacity from leading vendors while preserving flexibility to pivot as protocol adoption clarifies.
- Hedge critical BOM components. Negotiate medium-term purchase agreements for analog and memory items and maintain strategic buffer inventories to avoid margin erosion from short-term price spikes.
- Pursue targeted partnerships and minority investments. Use commercial alliances or minority equity in strategically positioned suppliers to accelerate roadmap access and de-risk supply without full integration overhead.
- Embed regulatory scenario planning into product roadmaps. Map alternative sourcing and certification playbooks for the most probable trade-control scenarios and align R&D timelines to the slowest majority path for multiregion launches.
What we deliberately withhold — why you need the full report
In line with PW Consulting’s “trailer” approach, this release highlights the strategic contours and actionable priorities emerging from our analysis but intentionally omits granular subsegment tables, region-by-application revenue splits and model-level company shares. Those datasets — including our detailed market-model workbook, segmented demand curves and supplier-specific revenue scenarios — are proprietary and available through the full report package. These detailed cells are the decision-grade inputs your procurement, product and M&A teams will use to build 90–180 day execution plans.
Next steps for executive teams
- Download the full report to access the interactive market model and supplier dossiers for qualification scheduling and sourcing optimization.
- Request a tailored briefing with PW Consulting to align your 2026 procurement calendar, product milestones and potential investment targets to the scenarios most relevant to your business footprint.
- Leverage our supplier scorecard template to run rapid, comparable assessments across your incumbent and potential HSMT SerDes partners.
PW Consulting’s HSMT SerDes Chip Market report translates growth forecasts (from USD 1,720 million in 2020 to USD 3,200 million in 2025 and toward USD 7,765 million by 2032 at a 13.5% CAGR) into executable 2026 actions. If your 2026 planning cycle includes decisions on product architecture, supply-chain commitments, or strategic investment in SerDes technology, this report is designed to be the playbook that turns market momentum into competitive advantage.
For detailed analysis of this topic, please visit the official page: HSMT SerDes Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Semiconductor Part Refurbishment Repairs Market to Reach USD 8.23 Billion by 2032 on 7.85% CAGR, Asia Pacific Holds USD 2.45 Billion Share
By pmarketresearch, 2026-07-02
Semiconductor Part Refurbishment & Repairs: Strategic Imperatives for 2026 — PW Consulting Market Brief
PW Consulting’s new market study on the Semiconductor Part Refurbishment & Repairs market synthesizes multi-year historical tracking and a robust forward-looking model to give senior leaders the actionable intelligence they need to navigate supply-chain stress, regulatory friction, and accelerating fab investment. This briefing frames the report’s strategic value for decisions to be made in 2026 while intentionally preserving the granular segment tables and proprietary assumptions for subscribers.
Semiconductor Part Refurbishment Repairs Market
Executive summary
After tracking the market through a detailed 2020–2025 historical calibration, our baseline shows the global Semiconductor Part Refurbishment & Repairs market at approximately USD 4.85 billion in the base year (2025). Under a set of conservative-to-base assumptions, the market is projected to grow at a compound annual growth rate (CAGR) of 7.85% over the 2026–2032 forecast horizon, reaching roughly USD 8.23 billion by 2032. This trajectory is driven by three structural forces: continued fab expansion and capital intensity, constrained new-part availability and extended lead times, and an industry-wide cost optimization push that increases the attractiveness of refurbishment and parts-reuse strategies.
Semiconductor Part Refurbishment Repairs Market
Why this report matters for 2026 corporate decisions
- Strategic procurement and inventory planning: The combination of extended lead times and periodic price uplifts in core semiconductor components means organizations must reassess inventory policies and total landed-cost models. Our analysis links repair/refurbishment economics directly to procurement KPIs and TCO thresholds most relevant in 2026.
- CapEx vs. Opex trade-offs: As fabs scale and diversify, decisions about investing in in-house refurbishment capability versus outsourcing will hinge on utilization scenarios. We provide a financial framework and scenario outputs that show the breakpoints where in‑house capability becomes accretive.
- Regulatory and geopolitical decisioning: With evolving export controls and new tariff structures effective in early 2026, maintenance and repair strategies are being recast — particularly where cross-border transfers, licensing, and domestic exceptions apply. The report maps the practical contours of these rules and their operational impacts.
- M&A and partnership targeting: The market’s moderate concentration profile and specialized service footprints create distinct windows for bolt-on acquisitions and strategic partnerships. Our competitive lens surfaces acquisition targets and illustrative valuation multiples (available in the full report) aligned to 2026 exit and growth plans.
Market trajectory and what the numbers tell us
Using a data-led approach that triangulates supplier financials, end-user fab buildouts, and observed replacement/repair cycles, the report establishes a clear mid-term growth path: from roughly USD 4.50 billion in 2024 to USD 4.85 billion in 2025, then continuing toward an estimated USD 5.23 billion in 2026 and into the high single-digit billions by the early 2030s. The 7.85% CAGR reflects recurring service demand for legacy and current-generation tools, rising refurbishment economics as a response to supply constraints, and steady aftermarket penetration within new fab projects.
Semiconductor Part Refurbishment Repairs Market
Report contents — practical and operational deliverables
Designed for operating executives, procurement leads, and corporate development teams, the full report contains:
- Detailed market-sizing and 2026–2032 forecast models (with sensitivity scenarios and downloadable spreadsheet templates).
- Service- and equipment-level playbooks that translate market demand into operational KPIs: lead-time-to-repair, mean-time-to-return, warranty exposure, and parts obsolescence curves.
- Regulatory impact matrix that maps recent policy changes to practical operating responses (including how certain tariff exclusions apply to repair activities in the United States).
- A prioritized list of opportunities for cost reduction, near-term revenue capture, and margin expansion for aftermarket service providers.
- Deal-sourcing guidance and a shortlist of target profiles for M&A and strategic JV activity, with integration risk checklists.
Competitive landscape — what incumbents and specialists bring to the table
The aftermarket for semiconductor parts is populated by a mix of highly specialized repair houses, regional distributors with service offerings, and engineering-focused refurbishers. PW Consulting’s competitive analysis spotlights capabilities and strategic postures of market participants to help acquirers and partners align to 2026 objectives:
- IES Semiconductor Parts (Bristol, UK) — A specialist in repair and testing for a broad range of manufacturing parts. Their emphasis on extending legacy equipment life and offering warranty-backed services makes them attractive to fabs preserving long-lived tool assets, especially in markets where OEM obsolescence is accelerating.
- PSI Semicon Services (Livonia, MI, USA) — A full-service provider whose breadth across robotics, controllers, power systems, and vacuum components positions them as a one-stop shop for North American fabs seeking to rationalize supplier count while maintaining legacy support.
- SemiGroup (Dallas, TX, USA) — Focused on refurbishing to OEM-grade specifications with installation and maintenance support. Their model is aligned to customers that require turnkey refurbish-install-warranty solutions to minimize downtime risk.
- Capitol Area Technology (Austin, TX, USA) — Combining distribution and repair, CAT offers transactional flexibility that appeals to smaller fabs and contractors balancing capital constraints with uptime requirements.
- Ichor Systems (Fremont, CA, USA) — Noted for engineering-led refurbishments of processing equipment with deep tool integration capability; they serve customers that need design engineering tied to refurbishment for performance restoration.
- Semiconductor Support Services Co. (SSSco) (Austin, TX, USA) — Provides repairs, upgrades, and parts across major OEM tool families, an advantage where multi‑vendor homogeneity is low and cross-platform expertise reduces mean time to recovery.
- Conation Technologies (USA) — A niche provider focused on equipment from specific test and inspection OEMs, useful for fabs where inspection tool uptime is mission-critical.
Collectively, the competitive field shows a mix of complementary strengths: engineering depth, warranty-backed offerings, regional service networks, and logistics capabilities. For corporate strategy teams, the question is not whether to interact with these providers, but how to structure relationships (preferred-supplier, JV, or full acquisition) to lock in capacity and expertise as fabs scale in 2026.
Market dynamics and external shocks shaping 2026 strategies
- Price volatility: Recent supplier price actions (industry reports in early 2026 indicate increases in semi component pricing of 15–35% in some lines) create a renewed ROI case for refurbishment and parts reuse versus sourcing new components.
- Lead-time pressures: Select device categories have trended toward protracted delivery windows (observed trending into the high tens of weeks for some SKUs), reinforcing the strategic value of repair networks and validated refurbished inventories.
- Regulatory shifts: The U.S. Section 232 proclamation effective January 2026 introduces tariffs on certain advanced semiconductors, but crucially includes carve-outs for repair, replacement, and R&D performed domestically — a structural tailwind for U.S.-based refurbishers and for onshore maintenance strategies.
- Geopolitical controls: Export controls and licensing requirements remain a central operational complexity for cross-border maintenance activities. The report provides a decision matrix that ties asset-class risk to licensing pathways.
- Fab investment: With projected global fab spending exceeding USD 1.5 trillion across a multi-year window, sustained capex supports long-term demand for aftermarket services and creates opportunities to embed refurbishment options into factory build contracts.
- Notable developments: Recent facility and investment moves — for example, the launch of a new eco-focused refurbishment facility in Singapore (early 2025) and the wave of U.S. fab project announcements since the CHIPS Act — are changing the geography of aftermarket services and the economics of material recovery.
Opportunities, risks, and recommended 2026 actions
For corporate leaders, the practical decision agenda for 2026 should include the following prioritized actions:
- Recalculate spare-parts policy thresholds using the report’s scenario module — adjust reorder points to reflect new lead-time distributions and price volatility shocks.
- Establish or expand “shop-in-shop” refurbishment capacity where utilization and mix justify fixed-cost investment; otherwise, consolidate outsourcing with 2–3 strategic partners under long-term SLAs that include capacity guarantees and performance penalties.
- Leverage regulatory carve-outs: structure certain maintenance and R&D activities domestically to mitigate tariff exposure and expedite licensing for controlled repairs.
- Pursue selective M&A to acquire engineering capabilities or regional footprint quickly — target profiles include niche engineering refurbishers, warranty-capable installers, and parts-diagnostic specialists.
- Integrate sustainability KPIs into refurbishment contracts to capture material-recovery and circular‑economy benefits that increasingly matter to customers and regulators.
Conclusion & next steps
Our analysis confirms that the Semiconductor Part Refurbishment & Repairs market is neither marginal nor purely tactical — it is a strategic lever for resilience, cost control, and competitive differentiation in 2026 and beyond. With market size rising from the mid‑single billions in the mid‑2020s to the high single‑digit billions by the early 2030s at a 7.85% CAGR, organizations that treat aftermarket strategy as a core pillar of supply‑chain and asset management will materially outperform peers on uptime and cost metrics.
To access the full dataset, segmented forecasts, scenario spreadsheets, and the detailed company benchmarking that informed these conclusions, please visit the PW Consulting report page. The full report contains the granular tables, regional and service splits, and the proprietary sensitivity tests that strategic teams will need to operationalize action plans for 2026.
For detailed analysis of this topic, please visit the official page: Semiconductor Part Refurbishment Repairs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Cloud Backup System Market to Expand at 11.25% CAGR Through 2032
By pmarketresearch, 2026-07-01
Cloud Backup System Market: A 2026 Strategic Preview from PW Consulting
As organizations enter 2026 with cloud-first strategies maturing into cloud-native operations, backup and recovery have moved from IT hygiene to board-level strategic priorities. PW Consulting’s latest Cloud Backup System Market study — with a 2025 base year and a 2026–2032 forecast horizon — provides the evidence-based, decision-grade guidance executives need to navigate supplier selection, architecture trade-offs, and regulatory risk. The market we modelled reached approximately USD 7.15 billion in 2025 and is projected to more than double by 2032, reaching roughly USD 15.08 billion at a compound annual growth rate (CAGR) of 11.25% over the forecast period. This release is intended as a tactical “preview trailer”: it demonstrates the depth of our analysis and the practical tools available to clients while steering readers to the full report for granular segment-level intelligence and proprietary datasets.
Cloud Backup System Market
Why this report matters for 2026 decisions
-
Encryption, immutability, and recoverability are now competitive differentiators. With ransomware sophistication rising, backup solutions are not merely storage targets but active components of cyber resilience strategies.
Cloud Backup System Market -
Regulatory drivers are reshaping deployment patterns. Data sovereignty rules and energy-efficiency mandates (e.g., EU EED requirements for PUE/WUE reporting) are raising the operational bar for where and how backups are stored and managed.
Cloud Backup System Market -
Economic pressures — particularly rising data center construction and energy costs — are changing the calculus between capex-heavy on-prem architectures and opex-centric cloud backup models. Our modelling explicitly incorporates projected increases in data center construction costs and electricity consumption trends to stress-test TCO scenarios.
-
Vendor strategies are diverging: hyperscalers push integrated cloud-native backup services, incumbent enterprise vendors emphasize cyber-resilience and platform unification, while specialist SaaS-first players focus on endpoints and SaaS-app protection. Understanding these trajectories is critical when negotiating multi-year contracts and defining integration roadmaps.
What the PW Consulting report delivers — practical, actionable outputs
-
Market sizing and scenarios: our base-case and two alternate scenarios illuminate demand sensitivity to energy pricing, regulatory tightening, and enterprise cloud adoption curves.
-
Vendor landscape and decision framework: comparative vendor scorecards, differentiated by capability (e.g., ransomware detection and recovery, air-gapped architectures, cross-cloud mobility), with pragmatic selection criteria tailored to enterprise archetypes.
-
TCO and procurement playbooks: modular financial models that translate technology choices, data gravity, ingress/egress economics, and expected growth into five-year cost profiles.
-
Cyber-resilience blueprints: recovery time and point objectives (RTO/RPO) matrices aligned with business-criticality tiers, plus architecture patterns that balance immutability, automation, and testability.
-
Regulatory & sustainability heatmaps: guidance on aligning backup deployments with local data sovereignty, energy-efficiency reporting, and emerging incentives — enabling compliance by design.
-
Executive action checklist: prioritized initiatives for CIOs, CISOs, and procurement leads to implement within the next 12–18 months.
Competitive landscape — positioning and near-term dynamics
The market shows a moderate level of concentration: the top three vendors account for a meaningful share of market revenue, and the top five capture slightly more than half — an environment that combines scale advantages with opportunities for targeted competition. This translates into three practical observations for 2026 planning:
-
Hyperscalers (AWS, Microsoft Azure, Google Cloud) continue to push integrated backup-as-a-service propositions that favor customers seeking native integration, global vaulting options, and operational simplicity. Expect feature expansion around multi-region vaulting and more aggressive SLAs for cloud-native workloads.
-
Enterprise platform vendors (e.g., Commvault, Veritas) and data-protection specialists (Veeam, Rubrik, Cohesity) emphasize unified control planes, cyber-resilience, and hybrid-cloud orchestration. Their value proposition centers on managing heterogenous estates, migrating legacy backups, and offering vendor-neutral recovery paths.
-
SaaS-first and niche players (Druva, Backblaze, Barracuda, Acronis) are sharpening offers for endpoint and SaaS-app protection, as well as simplified pricing models that attract mid-market and distributed workforces.
Recent product and partnership moves are already re-pricing differentiation vectors in 2026. Notable examples include Veeam’s early-year platform releases and expanded scanner coverage, Google Cloud’s multi-region backup vault and higher-frequency backup options for Compute Engine, and strengthened alliances between cloud platforms and independent data-protection vendors. These actions signal an acceleration in both feature parity and ecosystem collaboration — making vendor roadmaps an essential input to any multi-year procurement decision.
Regulatory, cost, and sustainability headwinds that shape strategy
-
Energy footprint and data center demand: U.S. data center electricity consumption was material in recent years and is projected to rise further; for high-scale backup strategies this translates into greater scrutiny of where replication occurs and growing interest in energy-optimized storage tiers.
-
Construction and infrastructure inflation: rising per-MW data center build costs means enterprises must treat locality and egress economics as first-order variables when selecting backup topologies.
-
Compliance complexity: regional data sovereignty regimes increase the operational burden for global organizations; expect an uptick in local/edge vault deployments and contractual clauses around data residency.
-
Regulatory incentives and local policy (e.g., state-level electricity rate programs) will influence site selection and the attractiveness of hybrid or edge strategies for backup retention.
Strategic playbook for 2026 — six prioritized actions
-
Elevate backup to a board-level resilience KPI: translate RTO/RPO into business outcomes and price them into insurance and continuity plans.
-
Adopt a hybrid resilience posture: combine immutable, air-gapped cloud vaulting with localized rapid-recovery points to meet both operational and regulatory requirements.
-
Negotiate contract levers beyond price: ensure egress predictability, testable recovery SLAs, portfolio-level indemnities for ransomware events, and roadmap commitments for feature parity or integration.
-
Embed sustainability and cost stress tests: include energy-price and construction-cost scenarios in TCO runs and favor architectures that mitigate data movement and storage hot-paths.
-
Prioritize vendor features that matter now: automated ransomware scanning and recovery playbooks, multi-region vaulting with tested failover, and SaaS-application protection for increasingly cloud-native estates.
-
Run supplier consolidation experiments: use controlled pilot programs to assess whether consolidation delivers operational leverage without increasing systemic risk.
How enterprise teams should use this preview
This article is a curated overview intended to orient executive priority-setting in 2026. The full PW Consulting Cloud Backup System Market report contains the proprietary breakdowns, vendor scorecards, downloadable TCO models, and scenario data that enterprise procurement, security, and IT architecture teams will need to convert strategy into implementation. For teams preparing RFPs, building migration roadmaps, or refining cyber-resilience budgets, the report’s modular frameworks are ready to be adapted to specific enterprise risk tolerances and regulatory footprints.
Closing perspective
Backup in 2026 is no longer a commodity checkbox; it is a strategic lever that intersects cybersecurity, regulatory compliance, sustainability, and cloud economics. PW Consulting’s study gives leaders the market context, vendor intelligence, and operational playbooks to make confident decisions in an environment where costs, rules, and threats are evolving rapidly. This release is a synthesis of our best thinking — a “trailer” that demonstrates the analytical rigor and practical tooling available in the full report. Organizations ready to sharpen their 2026 data protection strategy should consult the complete study to access the segment-level data, interactive models, and vendor matrices that underpin these recommendations.
For access to the full dataset, vendor scorecards, and downloadable TCO models, visit PW Consulting’s Cloud Backup System Market report page or contact our advisory team for a briefing tailored to your enterprise profile.
For detailed analysis of this topic, please visit the official page: Cloud Backup System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Closeouts Market Poised to Grow at a 6.85% CAGR in 2026–2032 Forecast
By pmarketresearch, 2026-07-01
Closeouts Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
Executive preview
As companies prepare their 2026 playbooks, the closeouts market is moving from a niche recapture channel to a strategic lever for revenue, margin recovery, and inventory optimization. PW Consulting’s latest Closeouts Market study (base year 2025, historical window 2020–2025, forecast 2026–2032) synthesizes market-scale modeling, competitive mapping, regulatory tailwinds and headwinds, and operator-level playbooks that together translate macro trajectories into boardroom decisions. Our analysis shows the market expanding meaningfully — from USD 285.5 Billion in 2025 to an anticipated USD 454.0 Billion by 2032 — reflecting a compound annual growth rate (CAGR) of 6.85%. This press release previews the report’s strategic value while reserving the granular segment-level tables and proprietary model outputs for the full report.
Closeouts Market
Why 2026 is an inflection year
Several converging dynamics elevate closeouts from tactical afterthought to strategic priority in 2026. Post-pandemic consumption patterns, retailer balance-sheet stress and a cautious consumer posture have increased supply of overstock and returned goods. Simultaneously, digital platforms and sophisticated secondary retail channels are professionalizing flows and improving recoveries for sellers. The result is both scale and volatility: more inventory moving through secondary channels, but higher dispersion in realized prices and buyer mix. For executives, this means that closeouts can be engineered as a controllable margin-recovery engine — if managed with data, process, and channel discipline.
Closeouts Market
Macro picture: scale, growth and concentration
-
Market scale: Our base-year market model pegs global closeouts at USD 285.5 Billion in 2025, rising to USD 454.0 Billion by 2032 under the central forecast.
Closeouts Market -
Growth trajectory: The market’s 6.85% CAGR through 2032 embeds both structural drivers (increased product churn, retail overcapacity) and tactical accelerants (platform-driven access to buyers, cross-border trade in secondary goods).
-
Competitive structure: The market remains fragmented — the top three players account for under a fifth of total activity and the top five capture roughly a quarter — creating both scale opportunities for platform leaders and attractive niches for specialist resellers and local distributors.
Regulatory and market noise impacting 2026 decisions
-
Tariff pressure: Ongoing U.S. tariffs on imported consumer goods continue to distort supply-chain economics. Our synthesis of public research indicates pass-through to consumer prices varies materially by category — a factor that directly shifts liquidation price floors and buyer willingness-to-pay across product lines.
-
Supply-side surplus: A wave of retailer restructuring and more conservative inventory policies have increased the flow of closeout and return inventory. This abundance can depress near-term realizations but creates scale advantages for operators who can sort, grade, and route inventory efficiently.
Key strategic implications for corporate leaders
Below are actionable decisions PW Consulting recommends companies prioritize in 2026. Each is grounded in our quantitative model, scenario stress-tests, and operator interviews captured in the full report.
-
Recast closeouts as an operational margin center, not just a cost-center disposal mechanism. By integrating reverse-logistics, pricing analytics and buyer-segmentation, retailers can improve net recovery per unit materially. Leading practices include dynamic reserve pricing, automated buyer-matching algorithms, and product-grade-driven routing to differentiated channels.
-
Segment channel strategies by product flow and recovery profile. Not all secondary inventory should take the same path: some requires curated auction exposure to maximize bids; others are better monetized via direct secondary retail partnerships or palletized wholesale. Our report outlines decision trees to determine optimal routing by cost-to-serve and expected recovery.
-
Invest in digital phasing to capture price transparency gains. Platforms that expose liquidations to broader buyer sets are compressing time-to-discovery and widening price realization ranges. For incumbents, a minimum viable data stack (barcode-level provenance + condition scoring + API-enabled lot listings) is a near-term differentiator.
-
Hedge tariff and supply volatility via diversified channel mixes and contractual protections. Given the asymmetric pass-through of tariffs across categories, firms should include tariff-sensitivity in lot-pricing models and pursue contractual clauses with suppliers to allocate risk of policy shifts.
-
Make targeted M&A and partnership plays to secure scale in specific flows. The fragmented market structure creates opportunities to consolidate regional networks, acquire digital marketplaces, or form exclusive supply agreements with distressed retailers. Our valuation appendix provides precedent multiples and diligence checklists for these transactions.
-
Embed sustainability and circularity into monetization. Closeout channels are naturally aligned with circular-economy objectives. Corporations that can demonstrate environmentally preferable disposition (repair/refurbish, certified resale partners) often access premium buyer segments and avoid reputational costs.
Competitive landscape — who matters and why
Our competitive mapping highlights platform leaders, B2B specialists, and bulk wholesalers. A handful of U.S.-based operators have emerged repeatedly in our supplier and buyer interviews:
-
Direct Liquidation (directliquidation.com) — An industry leader that partners with national retailers and manufacturers to channel name-brand overstock, closeouts, returns and surplus goods through auctions and wholesale lots. The firm’s scale in multi-category flows and national account relationships makes it a bellwether for pricing trends.
-
B-Stock (bstock.com) — A digital marketplace that aggregates liquidation inventory from major retailers and provides a marketplace layer connecting institutional buyers with overstock and returns. B-Stock’s marketplace model lowers transaction friction and increases price discovery velocity.
-
Liquidation.com (liquidation.com) — Known for auction-based disposition, the platform specializes in surplus inventory from large retailers and manufacturers. Their auction mechanics and buyer base provide reliable benchmarks for realized recoveries at scale.
-
Wholesale and pallet specialists — BULQ (bulq.com), Overstock Trader (overstocktrader.com), UpLiquidation (upliquidation.com), Kole Imports (koleimports.com), and several B2B wholesalers demonstrate how logistics, lot-mix, and curation differentiate returns. These firms tend to capture local reseller segments and provide granular sorting value.
-
Smaller-scale niche players — Total Surplus Solutions, Countryside Closeouts, Global Distributors and others occupy attractive high-return niches where curation, category expertise or specialized logistics create defensibility.
Our analysis in the full report compares these players on sourcing depth, technology stack, buyer network, unit economics and international reach. We also provide playbooks for engaging each operator type — when to partner, when to compete, and when to co-invest.
What the PW Consulting Closeouts Market report contains
Designed as an executive tool kit for 2026 planning, the full study combines proprietary market-sizing, scenario models, and practical deliverables:
-
Top-line market model with historical (2020–2025) calibration and forecast (2026–2032) scenarios — central, downside, and accelerated adoption pathways.
-
Operator-level competitive profiles and strategic positioning maps covering platform providers, auction houses, pallet wholesalers and specialty resellers.
-
Decision frameworks and decision trees for lot routing, pricing reserve setting, and channel selection by product flow and condition grade.
-
Due diligence checklists, valuation guidance, and precedent transaction summaries for M&A and strategic partnerships.
-
Implementation playbooks addressing systems requirements (minimum viable reverse-logistics stack), operational KPIs, and a 12–24 month transformation roadmap.
-
Risk matrix including regulatory exposures (tariff sensitivity), market shocks from retail insolvencies, and reputational risks tied to disposition practices.
To preserve competitive confidentiality and to adhere to our “trailer” approach, the report teaser above deliberately omits the proprietary subsegment tables and granular regional/product/distribution breakdowns that form the actionable core. Those detailed tables — including lot-level recovery curves, buyer elasticity by category, and channel-level margins — are available only in the full report.
Recommended next steps for executive teams
-
Run an internal rapid-assessment: map your 2025 inventory exits and simulate alternative routing outcomes using the decision trees in our appendix.
-
Pilot a data-driven channel test: select a representative product flow, instrument real-time grading and listing, and measure recovery lifts over a 90-day sprint.
-
Revisit supplier contracts: introduce clauses to share upside from improved recoveries and allocate tariff risks aligned with commercial realities.
-
Assess strategic consolidation targets: prioritize platforms or regional wholesalers that unlock either feedstock security or buyer-network access.
Conclusion — the strategic payoff
Closeouts are no longer just a downstream accounting problem. For firms willing to invest in analytics, platform connectivity, and disciplined channel management, the closeouts market offers a growing pool of recoverable value. With the market projected to grow from USD 285.5 Billion in 2025 to USD 454.0 Billion by 2032 at a 6.85% CAGR, executives who treat closeouts as a strategic channel can materially improve margins, reduce waste, and unlock new revenue streams. PW Consulting’s full Closeouts Market report converts these macro realities into executable initiatives — from the tactical (pricing mechanics, lot-routing) to the strategic (M&A, platform partnerships). For access to the full dataset, segment-level models, and operator scorecards, please consult the PW Consulting report portal.
For detailed analysis of this topic, please visit the official page: Closeouts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Off-Grid Solar Street Light Market Poised for Robust Expansion with 7.95% CAGR Through 2032
By pmarketresearch, 2026-07-01
Off‑Grid Solar Street Light Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
PW Consulting’s new Off‑Grid Solar Street Light Market report (base year 2025; historical coverage 2020–2025; forecast 2026–2032) synthesizes commercial, technical and policy intelligence into a single decision‑grade resource for companies and investors preparing strategy in 2026. The market, having grown from approximately USD 1,671.3 Million in 2020 to USD 2,450.0 Million in 2025, is forecast to expand to roughly USD 4,185.43 Million by 2032 at a compound annual growth rate (CAGR) of 7.95% over the 2026–2032 period. This brief highlights how the full report delivers immediate, operationally relevant insights while withholding segment‑level line‑items to preserve the report’s role as the authoritative, purchasable dataset.
Off-Grid Solar Street Light Market
Why this report matters for 2026 decision‑makers
-
Transition from pilot to scale: 2026 is the inflection year for many organizations moving from demonstration projects to formal procurement and deployment programs. Our report translates market momentum into pragmatic risk/return guidance tailored for that shift.
Off-Grid Solar Street Light Market -
Procurement and product strategy alignment: declining module costs, shifting battery chemistry economics and changing incentives make supplier selection, specification and contract structure high‑impact choices in 2026.
Off-Grid Solar Street Light Market -
Capital planning and revenue models: public tenders, private concession models and service‑based offers require different CAPEX/OPEX and financing profiles — the report’s financial models make these comparisons tangible.
What the report delivers (practical contents)
-
Methodology and 360° market sizing: reproducible approach linking demand drivers to installed base and replacement cycles across the 2020–2032 timeline.
-
Macro and component economics: forward curves and sensitivity analyses for PV modules, LiFePO4 batteries and related balance‑of‑system components, and the resulting impact on unit economics.
-
Vendor intelligence and benchmarking: strategic profiles, capability maps and procurement scorecards for the sector’s active suppliers, enabling apples‑to‑apples RFP design.
-
Technology archetypes and spec playbooks: decision trees for choosing integrated (all‑in‑one) vs. split architectures, energy‑management strategies and maintenance regimes.
-
Policy and incentives navigator: timeline‑anchored implications for corporate procurement and project finance under current regulatory trajectories.
-
Commercial tools: TCO calculators, scenario planners (including upside/downside demand cases), contract clause templates and risk heatmaps that convert insight into action.
-
Case studies and deployment lessons: real world implementations and procurement outcomes that accelerate learning curves and lower execution risk.
Competitive landscape — what we observed
The market exhibits a mix of specialized manufacturers and vertically integrated suppliers. Notable vendors featured in our competitive analysis include:
-
Fonroche Lighting America (USA) — known for resilient all‑in‑one systems and AI‑driven power management designed for off‑grid reliability.
-
SEPCO Solar Electric Power Company (USA) — a long‑standing provider of high‑power off‑grid LED solutions targeting remote and municipal applications.
-
Greenshine New Energy (USA) — a commercial‑grade systems manufacturer; its business continuity was materially affected by an acquisition of assets and operations in January 2026.
-
Solar Lighting International (USA) — concentrates on high‑lumen commercial solar LED products optimized for parking and roadway use.
-
Sunna Design (France) — European design focus with advanced energy management for industrial and commercial deployments.
-
EnGoPlanet, Streetleaf, ClearWorld and Solar Street Lights USA (primarily USA) — a cluster of firms offering full off‑grid solutions with varying emphasis on manufacturing origin, after‑sales service and system intelligence.
-
HeiSolar (China) — large‑scale manufacturer with strong cost competitiveness and a broad product portfolio for international markets.
Recent industry activity underlines two competing dynamics: product innovation and selective consolidation. Product launches such as SRESKY’s March 2026 “Tracker” all‑in‑one series point to continued differentiation on performance and urban use cases, while the January 2026 acquisition involving Greenshine signals that asset consolidation and scale pursuits are accelerating. Project deployments (for example, Cmoonlight’s Palm Series in the Philippines) demonstrate that implementation risk is falling for many standard applications when paired with proven specification and service models.
Key market dynamics and 2026 implications
-
Component cost trajectories matter. Polysilicon softness in Northeast Asia (reported at ~USD 5.35/kg in April 2026) and adjustments in LiFePO4 cathode prices are compressing module and battery cost tails — altering supplier margins and shortening payback windows for high‑quality systems.
-
Battery chemistry choices are strategic. LiFePO4 price movements (noted adjustments of USD 150–300 per tonne in late 2025–early 2026) make chemistry selection and lifecycle costing a procurement lever rather than a technical footnote.
-
Unit price dispersion is wide. Commercial‑grade off‑grid street lights are transacted in the market across a broad range (approximately USD 800 to USD 3,500 per unit in 2026 depending on specification). Buyers must enforce strict specification and test protocols to avoid cost overruns tied to premature failure.
-
Regulatory timing is a near‑term constraint. Changes to U.S. residential and commercial tax treatments (including expiration of the Section 25D residential credit and critical dates for commercial ITC eligibility) create timing incentives for project starts and influence financing structures.
-
Market structure: buyers should expect a moderately fragmented supplier landscape in which leading vendors offer scale and value‑added services, but opportunity exists for niche or vertically integrated entrants to capture regional contracts.
Actionable recommendations for 2026 (6–18 month horizon)
-
Lock short windows of preferential financing and tax‑driven benefits by initiating construction‑ready projects or binding supply agreements where regulatory deadlines apply.
-
Conduct component hedging or multi‑source procurement for batteries and PV modules to blunt single‑supplier exposure and benefit from falling commodity prices.
-
Specify performance and warranty metrics tied to measured lumen maintenance, battery cycles and remote telemetry; insist on service level agreements with penalty ladders.
-
Pilot integrated systems with clear KPIs for energy management intelligence — deploy telemetry to build operating datasets that inform scaled procurements.
-
Reassess product portfolio priorities: prioritize integrated, energy‑management capable offerings where OPEX savings are material; retain split systems where modularity enables lower initial CAPEX.
-
Embed supplier contingency and transition clauses in contracts to account for raw material price volatility and supply chain disruptions.
-
Monitor M&A and asset transactions (the Greenshine acquisition is an example) to identify consolidation partners or acquisition targets that accelerate scale and market access.
-
Use the report’s TCO models to compare contracting options — purchase, lease, pay‑per‑light — and to structure offers to municipalities and private owners that are financeable under local rules.
How PW Consulting supports execution
PW Consulting’s full Off‑Grid Solar Street Light Market report pairs the high‑level growth trajectory and scenario forecasts with executable tools: supplier due‑diligence templates, procurement scorecards, project financial models, and customizable scenario planners that translate the market’s ~7.95% forecast CAGR into project‑level cashflows. For clients that require implementation support, we provide vendor selection facilitation, contract negotiation support, and localized deployment playbooks.
Our approach preserves the usefully granular intelligence that underpins confident decisions while reserving the raw segment‑level tables and supplier revenue line‑items for the full report package. That structure—expert interpretation up front, complete primary data behind a controlled access layer—ensures executive teams make informed, defensible choices and procurement teams get the templates needed to operationalize them.
To move from insight to impact in 2026, corporate leaders should combine three moves: (1) translate the macro trajectory into a 12‑ to 24‑month procurement and pilot roadmap, (2) lock supplier and financing arrangements mindful of component price shifts and incentive deadlines, and (3) instrument pilots to generate the operating data needed for scaled rollouts. PW Consulting’s report and advisory services are designed to accelerate that sequence while limiting execution risk.
For institutions and teams preparing tenders, bids, investment memoranda or rollout plans in 2026, PW Consulting’s Off‑Grid Solar Street Light Market report is a decision‑grade toolkit. Visit our website to request the full report and proprietary datasets that support procurement, product and capital allocation decisions.
For detailed analysis of this topic, please visit the official page: Off-Grid Solar Street Light Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com