

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Closeouts Market Poised to Grow at a 6.85% CAGR in 2026–2032 Forecast

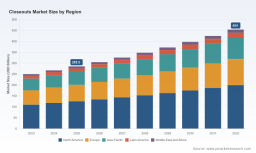
Closeouts Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
Executive preview
As companies prepare their 2026 playbooks, the closeouts market is moving from a niche recapture channel to a strategic lever for revenue, margin recovery, and inventory optimization. PW Consulting’s latest Closeouts Market study (base year 2025, historical window 2020–2025, forecast 2026–2032) synthesizes market-scale modeling, competitive mapping, regulatory tailwinds and headwinds, and operator-level playbooks that together translate macro trajectories into boardroom decisions. Our analysis shows the market expanding meaningfully — from USD 285.5 Billion in 2025 to an anticipated USD 454.0 Billion by 2032 — reflecting a compound annual growth rate (CAGR) of 6.85%. This press release previews the report’s strategic value while reserving the granular segment-level tables and proprietary model outputs for the full report.
Closeouts Market
Why 2026 is an inflection year
Several converging dynamics elevate closeouts from tactical afterthought to strategic priority in 2026. Post-pandemic consumption patterns, retailer balance-sheet stress and a cautious consumer posture have increased supply of overstock and returned goods. Simultaneously, digital platforms and sophisticated secondary retail channels are professionalizing flows and improving recoveries for sellers. The result is both scale and volatility: more inventory moving through secondary channels, but higher dispersion in realized prices and buyer mix. For executives, this means that closeouts can be engineered as a controllable margin-recovery engine — if managed with data, process, and channel discipline.
Closeouts Market
Macro picture: scale, growth and concentration
-
Market scale: Our base-year market model pegs global closeouts at USD 285.5 Billion in 2025, rising to USD 454.0 Billion by 2032 under the central forecast.
Closeouts Market -
Growth trajectory: The market’s 6.85% CAGR through 2032 embeds both structural drivers (increased product churn, retail overcapacity) and tactical accelerants (platform-driven access to buyers, cross-border trade in secondary goods).
-
Competitive structure: The market remains fragmented — the top three players account for under a fifth of total activity and the top five capture roughly a quarter — creating both scale opportunities for platform leaders and attractive niches for specialist resellers and local distributors.
Regulatory and market noise impacting 2026 decisions
-
Tariff pressure: Ongoing U.S. tariffs on imported consumer goods continue to distort supply-chain economics. Our synthesis of public research indicates pass-through to consumer prices varies materially by category — a factor that directly shifts liquidation price floors and buyer willingness-to-pay across product lines.
-
Supply-side surplus: A wave of retailer restructuring and more conservative inventory policies have increased the flow of closeout and return inventory. This abundance can depress near-term realizations but creates scale advantages for operators who can sort, grade, and route inventory efficiently.
Key strategic implications for corporate leaders
Below are actionable decisions PW Consulting recommends companies prioritize in 2026. Each is grounded in our quantitative model, scenario stress-tests, and operator interviews captured in the full report.
-
Recast closeouts as an operational margin center, not just a cost-center disposal mechanism. By integrating reverse-logistics, pricing analytics and buyer-segmentation, retailers can improve net recovery per unit materially. Leading practices include dynamic reserve pricing, automated buyer-matching algorithms, and product-grade-driven routing to differentiated channels.
-
Segment channel strategies by product flow and recovery profile. Not all secondary inventory should take the same path: some requires curated auction exposure to maximize bids; others are better monetized via direct secondary retail partnerships or palletized wholesale. Our report outlines decision trees to determine optimal routing by cost-to-serve and expected recovery.
-
Invest in digital phasing to capture price transparency gains. Platforms that expose liquidations to broader buyer sets are compressing time-to-discovery and widening price realization ranges. For incumbents, a minimum viable data stack (barcode-level provenance + condition scoring + API-enabled lot listings) is a near-term differentiator.
-
Hedge tariff and supply volatility via diversified channel mixes and contractual protections. Given the asymmetric pass-through of tariffs across categories, firms should include tariff-sensitivity in lot-pricing models and pursue contractual clauses with suppliers to allocate risk of policy shifts.
-
Make targeted M&A and partnership plays to secure scale in specific flows. The fragmented market structure creates opportunities to consolidate regional networks, acquire digital marketplaces, or form exclusive supply agreements with distressed retailers. Our valuation appendix provides precedent multiples and diligence checklists for these transactions.
-
Embed sustainability and circularity into monetization. Closeout channels are naturally aligned with circular-economy objectives. Corporations that can demonstrate environmentally preferable disposition (repair/refurbish, certified resale partners) often access premium buyer segments and avoid reputational costs.
Competitive landscape — who matters and why
Our competitive mapping highlights platform leaders, B2B specialists, and bulk wholesalers. A handful of U.S.-based operators have emerged repeatedly in our supplier and buyer interviews:
-
Direct Liquidation (directliquidation.com) — An industry leader that partners with national retailers and manufacturers to channel name-brand overstock, closeouts, returns and surplus goods through auctions and wholesale lots. The firm’s scale in multi-category flows and national account relationships makes it a bellwether for pricing trends.
-
B-Stock (bstock.com) — A digital marketplace that aggregates liquidation inventory from major retailers and provides a marketplace layer connecting institutional buyers with overstock and returns. B-Stock’s marketplace model lowers transaction friction and increases price discovery velocity.
-
Liquidation.com (liquidation.com) — Known for auction-based disposition, the platform specializes in surplus inventory from large retailers and manufacturers. Their auction mechanics and buyer base provide reliable benchmarks for realized recoveries at scale.
-
Wholesale and pallet specialists — BULQ (bulq.com), Overstock Trader (overstocktrader.com), UpLiquidation (upliquidation.com), Kole Imports (koleimports.com), and several B2B wholesalers demonstrate how logistics, lot-mix, and curation differentiate returns. These firms tend to capture local reseller segments and provide granular sorting value.
-
Smaller-scale niche players — Total Surplus Solutions, Countryside Closeouts, Global Distributors and others occupy attractive high-return niches where curation, category expertise or specialized logistics create defensibility.
Our analysis in the full report compares these players on sourcing depth, technology stack, buyer network, unit economics and international reach. We also provide playbooks for engaging each operator type — when to partner, when to compete, and when to co-invest.
What the PW Consulting Closeouts Market report contains
Designed as an executive tool kit for 2026 planning, the full study combines proprietary market-sizing, scenario models, and practical deliverables:
-
Top-line market model with historical (2020–2025) calibration and forecast (2026–2032) scenarios — central, downside, and accelerated adoption pathways.
-
Operator-level competitive profiles and strategic positioning maps covering platform providers, auction houses, pallet wholesalers and specialty resellers.
-
Decision frameworks and decision trees for lot routing, pricing reserve setting, and channel selection by product flow and condition grade.
-
Due diligence checklists, valuation guidance, and precedent transaction summaries for M&A and strategic partnerships.
-
Implementation playbooks addressing systems requirements (minimum viable reverse-logistics stack), operational KPIs, and a 12–24 month transformation roadmap.
-
Risk matrix including regulatory exposures (tariff sensitivity), market shocks from retail insolvencies, and reputational risks tied to disposition practices.
To preserve competitive confidentiality and to adhere to our “trailer” approach, the report teaser above deliberately omits the proprietary subsegment tables and granular regional/product/distribution breakdowns that form the actionable core. Those detailed tables — including lot-level recovery curves, buyer elasticity by category, and channel-level margins — are available only in the full report.
Recommended next steps for executive teams
-
Run an internal rapid-assessment: map your 2025 inventory exits and simulate alternative routing outcomes using the decision trees in our appendix.
-
Pilot a data-driven channel test: select a representative product flow, instrument real-time grading and listing, and measure recovery lifts over a 90-day sprint.
-
Revisit supplier contracts: introduce clauses to share upside from improved recoveries and allocate tariff risks aligned with commercial realities.
-
Assess strategic consolidation targets: prioritize platforms or regional wholesalers that unlock either feedstock security or buyer-network access.
Conclusion — the strategic payoff
Closeouts are no longer just a downstream accounting problem. For firms willing to invest in analytics, platform connectivity, and disciplined channel management, the closeouts market offers a growing pool of recoverable value. With the market projected to grow from USD 285.5 Billion in 2025 to USD 454.0 Billion by 2032 at a 6.85% CAGR, executives who treat closeouts as a strategic channel can materially improve margins, reduce waste, and unlock new revenue streams. PW Consulting’s full Closeouts Market report converts these macro realities into executable initiatives — from the tactical (pricing mechanics, lot-routing) to the strategic (M&A, platform partnerships). For access to the full dataset, segment-level models, and operator scorecards, please consult the PW Consulting report portal.
For detailed analysis of this topic, please visit the official page: Closeouts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com