

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Off-Grid Solar Street Light Market Poised for Robust Expansion with 7.95% CAGR Through 2032

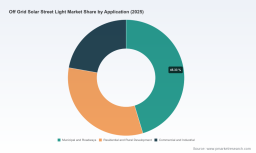
Off‑Grid Solar Street Light Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
PW Consulting’s new Off‑Grid Solar Street Light Market report (base year 2025; historical coverage 2020–2025; forecast 2026–2032) synthesizes commercial, technical and policy intelligence into a single decision‑grade resource for companies and investors preparing strategy in 2026. The market, having grown from approximately USD 1,671.3 Million in 2020 to USD 2,450.0 Million in 2025, is forecast to expand to roughly USD 4,185.43 Million by 2032 at a compound annual growth rate (CAGR) of 7.95% over the 2026–2032 period. This brief highlights how the full report delivers immediate, operationally relevant insights while withholding segment‑level line‑items to preserve the report’s role as the authoritative, purchasable dataset.
Off-Grid Solar Street Light Market
Why this report matters for 2026 decision‑makers
-
Transition from pilot to scale: 2026 is the inflection year for many organizations moving from demonstration projects to formal procurement and deployment programs. Our report translates market momentum into pragmatic risk/return guidance tailored for that shift.
Off-Grid Solar Street Light Market -
Procurement and product strategy alignment: declining module costs, shifting battery chemistry economics and changing incentives make supplier selection, specification and contract structure high‑impact choices in 2026.
Off-Grid Solar Street Light Market -
Capital planning and revenue models: public tenders, private concession models and service‑based offers require different CAPEX/OPEX and financing profiles — the report’s financial models make these comparisons tangible.
What the report delivers (practical contents)
-
Methodology and 360° market sizing: reproducible approach linking demand drivers to installed base and replacement cycles across the 2020–2032 timeline.
-
Macro and component economics: forward curves and sensitivity analyses for PV modules, LiFePO4 batteries and related balance‑of‑system components, and the resulting impact on unit economics.
-
Vendor intelligence and benchmarking: strategic profiles, capability maps and procurement scorecards for the sector’s active suppliers, enabling apples‑to‑apples RFP design.
-
Technology archetypes and spec playbooks: decision trees for choosing integrated (all‑in‑one) vs. split architectures, energy‑management strategies and maintenance regimes.
-
Policy and incentives navigator: timeline‑anchored implications for corporate procurement and project finance under current regulatory trajectories.
-
Commercial tools: TCO calculators, scenario planners (including upside/downside demand cases), contract clause templates and risk heatmaps that convert insight into action.
-
Case studies and deployment lessons: real world implementations and procurement outcomes that accelerate learning curves and lower execution risk.
Competitive landscape — what we observed
The market exhibits a mix of specialized manufacturers and vertically integrated suppliers. Notable vendors featured in our competitive analysis include:
-
Fonroche Lighting America (USA) — known for resilient all‑in‑one systems and AI‑driven power management designed for off‑grid reliability.
-
SEPCO Solar Electric Power Company (USA) — a long‑standing provider of high‑power off‑grid LED solutions targeting remote and municipal applications.
-
Greenshine New Energy (USA) — a commercial‑grade systems manufacturer; its business continuity was materially affected by an acquisition of assets and operations in January 2026.
-
Solar Lighting International (USA) — concentrates on high‑lumen commercial solar LED products optimized for parking and roadway use.
-
Sunna Design (France) — European design focus with advanced energy management for industrial and commercial deployments.
-
EnGoPlanet, Streetleaf, ClearWorld and Solar Street Lights USA (primarily USA) — a cluster of firms offering full off‑grid solutions with varying emphasis on manufacturing origin, after‑sales service and system intelligence.
-
HeiSolar (China) — large‑scale manufacturer with strong cost competitiveness and a broad product portfolio for international markets.
Recent industry activity underlines two competing dynamics: product innovation and selective consolidation. Product launches such as SRESKY’s March 2026 “Tracker” all‑in‑one series point to continued differentiation on performance and urban use cases, while the January 2026 acquisition involving Greenshine signals that asset consolidation and scale pursuits are accelerating. Project deployments (for example, Cmoonlight’s Palm Series in the Philippines) demonstrate that implementation risk is falling for many standard applications when paired with proven specification and service models.
Key market dynamics and 2026 implications
-
Component cost trajectories matter. Polysilicon softness in Northeast Asia (reported at ~USD 5.35/kg in April 2026) and adjustments in LiFePO4 cathode prices are compressing module and battery cost tails — altering supplier margins and shortening payback windows for high‑quality systems.
-
Battery chemistry choices are strategic. LiFePO4 price movements (noted adjustments of USD 150–300 per tonne in late 2025–early 2026) make chemistry selection and lifecycle costing a procurement lever rather than a technical footnote.
-
Unit price dispersion is wide. Commercial‑grade off‑grid street lights are transacted in the market across a broad range (approximately USD 800 to USD 3,500 per unit in 2026 depending on specification). Buyers must enforce strict specification and test protocols to avoid cost overruns tied to premature failure.
-
Regulatory timing is a near‑term constraint. Changes to U.S. residential and commercial tax treatments (including expiration of the Section 25D residential credit and critical dates for commercial ITC eligibility) create timing incentives for project starts and influence financing structures.
-
Market structure: buyers should expect a moderately fragmented supplier landscape in which leading vendors offer scale and value‑added services, but opportunity exists for niche or vertically integrated entrants to capture regional contracts.
Actionable recommendations for 2026 (6–18 month horizon)
-
Lock short windows of preferential financing and tax‑driven benefits by initiating construction‑ready projects or binding supply agreements where regulatory deadlines apply.
-
Conduct component hedging or multi‑source procurement for batteries and PV modules to blunt single‑supplier exposure and benefit from falling commodity prices.
-
Specify performance and warranty metrics tied to measured lumen maintenance, battery cycles and remote telemetry; insist on service level agreements with penalty ladders.
-
Pilot integrated systems with clear KPIs for energy management intelligence — deploy telemetry to build operating datasets that inform scaled procurements.
-
Reassess product portfolio priorities: prioritize integrated, energy‑management capable offerings where OPEX savings are material; retain split systems where modularity enables lower initial CAPEX.
-
Embed supplier contingency and transition clauses in contracts to account for raw material price volatility and supply chain disruptions.
-
Monitor M&A and asset transactions (the Greenshine acquisition is an example) to identify consolidation partners or acquisition targets that accelerate scale and market access.
-
Use the report’s TCO models to compare contracting options — purchase, lease, pay‑per‑light — and to structure offers to municipalities and private owners that are financeable under local rules.
How PW Consulting supports execution
PW Consulting’s full Off‑Grid Solar Street Light Market report pairs the high‑level growth trajectory and scenario forecasts with executable tools: supplier due‑diligence templates, procurement scorecards, project financial models, and customizable scenario planners that translate the market’s ~7.95% forecast CAGR into project‑level cashflows. For clients that require implementation support, we provide vendor selection facilitation, contract negotiation support, and localized deployment playbooks.
Our approach preserves the usefully granular intelligence that underpins confident decisions while reserving the raw segment‑level tables and supplier revenue line‑items for the full report package. That structure—expert interpretation up front, complete primary data behind a controlled access layer—ensures executive teams make informed, defensible choices and procurement teams get the templates needed to operationalize them.
To move from insight to impact in 2026, corporate leaders should combine three moves: (1) translate the macro trajectory into a 12‑ to 24‑month procurement and pilot roadmap, (2) lock supplier and financing arrangements mindful of component price shifts and incentive deadlines, and (3) instrument pilots to generate the operating data needed for scaled rollouts. PW Consulting’s report and advisory services are designed to accelerate that sequence while limiting execution risk.
For institutions and teams preparing tenders, bids, investment memoranda or rollout plans in 2026, PW Consulting’s Off‑Grid Solar Street Light Market report is a decision‑grade toolkit. Visit our website to request the full report and proprietary datasets that support procurement, product and capital allocation decisions.
For detailed analysis of this topic, please visit the official page: Off-Grid Solar Street Light Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com