

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Display Driver IC Wafer Foundry Market Set to Expand at a 6.55% CAGR Through 2032

DDIC Wafer Foundry Services Market: A 2026 Strategic Playbook for Executives
As demand patterns in displays continue to bifurcate between high-volume mobile and large-area panels, and as foundry capacity is reallocated across adjacent semiconductor priorities, Display Driver IC (DDIC) wafer foundry services have risen to a strategic inflection point. PW Consulting’s latest market research — anchored on a 2025 base year and projecting through 2032 — quantifies this transition and translates it into executable guidance for 2026 decision-making. This release is a preview: we reveal the analytical framing, directional market architecture and practical implications for corporate strategy, while preserving the granular segment tables and proprietary model outputs for subscribers of the full report.
Display Driver IC (DDIC) Wafer Foundry Services Market
Market trajectory: what the numbers tell us
Our top-line modelling traces a clear and durable expansion of the DDIC wafer foundry services market. The market rose from an estimated USD 5,120 Million in 2020 to roughly USD 7,250 Million in 2025 (base year), and is forecast to reach approximately USD 7,928 Million in 2026. Under the central-case assumptions embedded in the report, the market expands at a compound annual growth rate (CAGR) of 6.55% over the 2026–2032 forecast window, culminating in a projected market size north of USD 11,300 Million by 2032.
Display Driver IC (DDIC) Wafer Foundry Services Market
Two quantitative takeaways frame the strategic context for 2026: first, momentum is steady rather than explosive — the market is entering an expansionary but competitive phase; second, market concentration is material, with the top three and top five foundries together controlling a substantial majority of wafer supply. These concentration dynamics create both negotiating leverage for leading foundries and procurement vulnerabilities for OEMs and IDMs that rely on single-source or single-region supply.
Display Driver IC (DDIC) Wafer Foundry Services Market
Why this matters to 2026 corporate strategy
- Procurement and cost management: With foundries signaling price adjustments for mature nodes and OSAT costs trending higher, 2026 will be a year when firms must decide whether to accept short-term cost inflation, renegotiate supply terms, or accelerate qualification of alternative suppliers.
- Capacity and node allocation: Reallocation of capacity in Taiwan and South Korea toward high-priority PMIC and advanced-node logic impacts DDIC lead times. Firms will need scenario plans that align product roadmaps with available node capacity and qualification timelines.
- Risk and resilience: Geopolitical controls and equipment restrictions targeting specific geographies introduce asymmetric risk. Supply diversification and contingency sourcing are no longer optional defensive measures.
- M&A and partnership timing: Market concentration and the rise of specialist foundries create windows for strategic investments, minority stakes, JV structures or long-term offtake agreements that secure capacity and technology access.
What’s inside the full PW Consulting report (practical deliverables)
The full report is built for immediate operational use by procurement, product strategy, and corporate development teams. Core deliverables include:
- Proprietary demand-supply model with scenario-based outputs (fast-growth, baseline, downside) so teams can stress-test product launch timelines against likely wafer availability and price paths.
- Foundry scorecards and qualification roadmaps for mature (90nm and above), mid-range (40–65nm) and advanced mature (sub-40nm) DDIC process options, including cycle-time, yield sensitivity and tooling constraints.
- Price-pass-through and margin impact simulations calibrated to observed wafer price adjustments and raw material trends since 2025, enabling finance teams to model gross margin and ASP sensitivity under multiple market scenarios.
- Negotiation playbook and term-sheet templates for securing mid- to long-term wafer commitments, with clauses designed for capacity shifts, technology upgrades and force majeure covering export-control disruptions.
- M&A heatmaps, partnership match-making matrices and a prioritized target list for strategic investment, including runnable valuation corridors that reflect DDIC-specific economics and concentration risk.
- Regional risk assessment and contingency maps that translate geopolitical and export-control exposure into actionable sourcing shifts and certification plans.
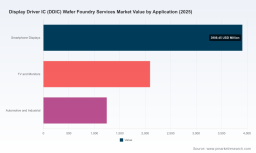
Note: this preview omits the detailed region-by-region and application-by-application allocation tables. Those segment-level splits are available exclusively in the subscription release, which includes downloadable model workbooks for client-specific stress-testing.
Competitive landscape — who matters and why
The DDIC foundry ecosystem is a mix of global integrated leaders, large pure-play foundries, and regionally specialized providers. The competitive set we profile in the report includes leading incumbent foundries and rising regional players. High-level implications:
- TSMC (Hsinchu, Taiwan): The global lead in volume and node breadth. TSMC’s ability to supply both mature and select advanced processes for DDIC, combined with its scale, gives it leverage in shaping pricing and allocation in 2026.
- Samsung Foundry (Suwon, South Korea): Offers high-voltage platforms and benefits from an integrated display ecosystem. Its premium-tier capabilities make it a go-to for AMOLED-focused DDICs.
- UMC (Hsinchu, Taiwan): Strength in specialty and high-voltage processes; important for customers needing targeted analog/high-voltage solutions in mature nodes.
- GlobalFoundries (Malta, NY): Competes on stable, proven high-voltage platforms in mature nodes — a predictable partner where yield and reliability trump bleeding-edge scaling.
- Vis/Hua Hong/SMIC/Nexchip/Vanguard: A group of regional and specialist foundries that collectively reshape supply dynamics. Chinese players in particular have accelerated expansion in large-area DDIC production.
Market concentration metrics underline the strategic calculus: the top three and top five foundries together control a dominant share of capacity. For buyers, this means negotiating power is uneven; for investors, scale and process breadth remain differentiators.
Recent market moves and near-term catalysts
Several events in early 2026 crystallize the environment in which 2026 decisions must be made:
- Capacity reallocation and price moves: Taiwanese and South Korean foundries have shifted allocation toward PMICs and advanced logic, creating tighter supply for large-area DDIC wafers. Multiple foundries signaled price adjustments for mature nodes in H2 2026, creating immediate procurement implications.
- Regional expansion and capital raises: Chinese specialists have moved aggressively to expand mature-node fabs. Strategic capital actions — including listing applications to fund expansions — are reshaping the geographic distribution of DDIC capacity.
- Input-cost inflation: Rising OSAT, wafer and precious-metal costs (e.g., bumping materials) are exerting margin pressure and raising the odds of cost pass-through to OEMs.
- Policy and export controls: U.S. export restrictions and tighter equipment shipments to some Chinese foundries create asymmetric growth constraints and an acceleration of localization strategies by affected suppliers.
Actionable strategic recommendations for 2026
- Dual-track supplier strategies: Implement primary-secondary foundry relationships structured by product tier and node class. For new product introductions, reserve qualification cycles across at least two geographies.
- Lock and layer pricing: Use a combination of short-term fixed-price tranches and longer-term index-linked agreements to manage inflationary spikes while preserving supplier commitment.
- Prioritize node-fit over headline node numbers: For display drivers, maturity of analog/high-voltage process and yield experience often matter more than the nominal nm label. Allocate engineering resources to validation of process variants rather than chasing node hierarchy.
- Commodity and OSAT hedging: Establish procurement hedges for key bumping and substrate materials; explore preferred supplier agreements with OSAT partners to secure downstream assembly capacity.
- Strategic finance moves: Consider minority investments or prepayment capacity agreements with regional foundries that can materially reduce lead times and lock in expansion priority.
- Prepare export-control playbooks: Map critical supply chains that intersect with restricted equipment or materials and create pre-approved alternate flows and qualification paths.
How to convert this insight into 90‑day and 12‑month plans
Within 90 days: run the report’s scenario model against your SKU-level demand; identify top three wafers by spend and initiate secondary-qualification programs where single-sourced. Negotiate a short-term price-and-capacity tranche with critical foundries to cover Q3–Q4 2026 exposure.
Within 12 months: finalize bilateral or JV capacity agreements for critical mature-node DDIC production, restructure supplier scorecards to include export-control exposure and materials-risk indices, and incorporate the report’s margin-sensitivity outputs into product-pricing decisions and investor disclosures.
Next steps and access to the full intelligence
This executive preview is designed to surface the market dynamics and operational levers that will shape pragmatic decision-making in 2026. The full PW Consulting DDIC Wafer Foundry Services Market report contains the complete segmentation matrices, downloadable forecast models, supplier playbooks and a confidential appendix with contract language and recommended term structures.
For procurement leaders, product and manufacturing executives, and corporate development teams preparing 2026 roadmaps, the report is an immediately actionable toolset. Access to the full dataset, granular regional/application splits, and bespoke modelling support is available through PW Consulting’s client portal — detailed instructions and subscription options are provided on the report landing page.
Contact PW Consulting to schedule a briefing and modelling workshop that tailors the report’s outputs to your enterprise’s product portfolio and sourcing footprint.
For detailed analysis of this topic, please visit the official page: Display Driver IC (DDIC) Wafer Foundry Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com