

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automotive Embedded Storage (eMMC & UFS) Market to Surge at 15.02% CAGR, Hitting USD 10.9B by 2032

Automotive Embedded Storage (eMMC & UFS) Market: Strategic Imperatives for 2026
As vehicles continue their transformation into data-centers-on-wheels, embedded storage has moved from a component line-item to a strategic enabler of user experience, safety and software-defined value capture. PW Consulting’s latest Automotive Embedded Storage (eMMC & UFS) Market report — built on a 2025 base year and a 2026–2032 forecast horizon — quantifies that transition. The market expanded from roughly USD 3.15 billion in 2023 to USD 4.10 billion in 2025 and is projected to reach approximately USD 10.91 billion by 2032, reflecting a compound annual growth rate (CAGR) of ~15.02% across the forecast period. For executive teams planning 2026 investments, procurement cycles, qualification roadmaps and M&A activity, these macro dynamics create both urgency and optionality.
Automotive Embedded Storage (eMMC and UFS) Market
What the report delivers — practical, decision-ready content
- Forward-looking market sizing and scenario-based forecasts (2026–2032) with sensitivity to NAND supply, pricing and adoption curves for eMMC and UFS.
- Buyer playbooks for procurement and qualification: realistic timelines, contract structures, inventory strategies and sample/qualification pathways for automotive OEMs and Tier-1 suppliers.
- Vendor benchmarking and scorecards: multidimensional profiles covering product maturity, automotive-grade qualification status, performance-per-watt, functional-safety support and aftermarket reliability evidence.
- Supply-chain and risk maps: concentrated production footprints, geopolitical exposure analysis, tariff and export-control scenarios, and contingency sourcing templates.
- Technical guidance for systems architects: design trade-offs between eMMC and UFS (cost, throughput, power, lifecycle), recommended interfaces for IVI, ADAS and telematics modules, and memory-stack optimization patterns.
- Hands-on commercial tools: pricing sensitivity models, contract negotiation levers (price collars, allocation commitments, volume-flex clauses), and an M&A/partnering framework targeting controller and NAND specialists.
Market dynamics shaping 2026 decisions
- Rapid market growth with elevated supply-side risk — The double-digit CAGR illustrates structural demand from richer infotainment stacks, data-logging for autonomy, and in-vehicle AI workloads. That demand is colliding with persistent NAND supply tightness and strategic production shifts by major suppliers, creating near-term allocation pressure for automotive-qualified eMMC and UFS parts.
- Price and allocation volatility — Contract and spot NAND prices rose into early 2026, increasing component costs for embedded storage. Procurement teams must model both price risk and delivery risk simultaneously; doing so will change how procurement prioritizes capacity reservations versus spot buys.
- Qualification cadence is a gating factor — Automotive qualification cycles for eMMC/UFS typically span 18–24 months. This creates durable demand lock-in for suppliers that achieve early qualification and implies that design and sourcing decisions made in 2026 will influence product roadmaps and supplier relationships well into 2028.
- Functional safety and regulatory overlay — AEC-Q100 and ISO 26262/ASIL requirements remain non-negotiable for ADAS and safety-adjacent storage. Suppliers with demonstrable ASIL-compliant solutions and long-tailed reliability data will command pricing and allocation advantages.
- Concentration and supplier power — The embedded storage market shows high concentration, with the top three suppliers accounting for a substantial majority of market share and the top five covering nearly nine-in-ten of the market. This structure amplifies supplier negotiating power, but also concentrates systemic risk if one node experiences capacity or trade disruptions.
- Geopolitical and supply-chain exposure — Global NAND production is heavily concentrated in Asia. That concentration introduces geopolitical risk vectors — export controls, tariffs and localized disruptions — which must be part of any sourcing or contingency planning exercise.
Competitive landscape — who matters and why
The competitive set combines large, vertically integrated memory manufacturers, controller specialists and regional players that focus on automotive-grade reliability. Key strategic considerations by supplier type include:
Automotive Embedded Storage (eMMC and UFS) Market
- Vertically integrated NAND leaders (e.g., major memory houses): offer depth in manufacturing scale, advanced process nodes and broad automotive-focused portfolios. Their strengths are supply stability (when capacity is allocated) and early access to high-density NAND generations.
- Controller specialists and system integrators: provide the firmware, controller IP and validation necessary to optimize UFS/eMMC in complex cockpit and ADAS platforms. Their validation on major vehicle SoCs creates a practical adoption pathway for OEMs.
- Regional and niche suppliers: focus on endurance, extended temperature ranges and automotive qualifications. These players are critical fallback partners for niche programs and aftermarket support.
Recent product and validation developments underscore technology momentum and competitive moves into automotive: a leading memory supplier began shipping qualification samples of an automotive UFS 4.1 solution built on G9 NAND and touting ASIL-B compliance; other players introduced UFS 4.1 samples and early UFS 5.0 evaluations; and controller vendors completed compatibility validation on prominent cockpit-class SoC platforms. These events accelerate OEMs’ ability to architect higher-performance storage stacks but also compress windows for supplier selection.
Automotive Embedded Storage (eMMC and UFS) Market
Strategic implications and recommended 2026 actions
Based on our analysis, PW Consulting recommends a multi-track approach that balances near-term risk mitigation with medium-term capability capture:
- Procurement: Move from annual spot buys to multi-year allocation agreements with clarity on volume, performance classes and price adjustment mechanisms. Negotiate explicit allocation guarantees for automotive-qualified parts and include reciprocal technical support commitments (e.g., co-engineering and failure-analysis SLAs).
- Qualification & Design: Start or accelerate qualification programs in H1 2026 for any platforms targeting 2028–2029 production. Treat qualification as a strategic barrier — securing early-qualified suppliers locks-in supply and reduces rework risk. Design teams should standardize interfaces to allow late-stage downgrades/upgrades (e.g., UFS-capable controllers that can operate with eMMC during shortage scenarios).
- Technology choices: Align storage architecture to product tiers. For high-performance IVI and ADAS domains, favor UFS generations that provide the necessary throughput and power efficiency. For cost-sensitive telematics or entry-level modules, validated eMMC solutions still offer compelling TCO. However, avoid rigid bifurcation: build BOM flexibility that anticipates rapid UFS adoption.
- Inventory & hedging: Consider strategic buffer stocks for critical SKUs and negotiate price-collar or index-linked contracts to mitigate spot price swings. Where capacity is tight, allocate a portion of your spend to upstream partners to secure wafer or die-level allocations as part of a vertical sourcing strategy.
- Supplier portfolio and partnerships: Diversify across vertically integrated NAND leaders and specialized controller vendors. Prioritize suppliers with proven automotive qualifications, ASIL support and demonstrated validation on target SoC platforms. For OEMs pursuing cockpit differentiation, early co-development agreements with controller/IP vendors can be a competitive advantage.
- M&A & innovation plays: For companies looking to enter or scale in this space, target assets that shorten qualification cycles (e.g., controller IP, firmware teams) or provide unique value-add (secure storage, endurance-enhancing firmware). Smaller acquisitions can be effective bolt-ons to accelerate time-to-market without incurring the long lead-time of in-house development.
- Risk & compliance: Embed scenario planning for geopolitical shock, export-control changes and supplier outages into 2026 budgeting cycles. Build dual-source and near-shore options for critical programs where feasible.
Decision roadmap and timing for 2026
- Immediate (Q1–Q2 2026): Freeze qualification roadmaps for 2028-bound platforms; initiate allocation negotiations with primary suppliers; conduct BOM flexibility audits.
- Near term (Q3–Q4 2026): Execute multi-year contracts with allocation and price mechanics; begin co-validation with chosen controller partners; formalize inventory hedging where justified.
- Medium term (2027): Operationalize supplier partnerships in production-intent runs; reassess portfolio by product tier and transition modules to higher-performance UFS where ROI and supply permit.
What we are deliberately withholding — and why
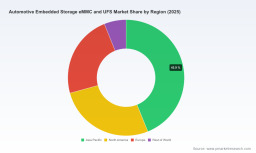
In keeping with the “trailer” principle that guides PW Consulting’s release strategy, this public summary intentionally highlights macro sizing, concentration metrics and strategic implications while withholding granular subsegment tables and raw numerical worksheets (e.g., detailed regional splits, application-specific revenue lines and per-supplier volumetric allocations). Those detailed datasets and interactive models are essential for program-level procurement negotiations and engineering BOM decisions; they are available exclusively in the full report and accompanying data workbook. The intent is to provide enough diagnostic clarity to inform executive strategy while preserving the detailed intelligence that operational teams require to execute supplier selection and contractual arrangements.
Final note — why 2026 matters
Decisions made in 2026 will disproportionately shape supplier relationships, product architectures and cost curves through the late-2020s. With a market expanding at roughly 15% annually and facing persistent supply-side stressors, OEMs and Tier-1s who coordinate procurement, qualification and design strategy now will gain preferential access to capacity, protect margins and accelerate time-to-market for differentiated cockpit and ADAS experiences. PW Consulting’s full Automotive Embedded Storage (eMMC & UFS) Market report provides the granular forecasting, supplier scorecards and commercial tools needed to operationalize these strategic recommendations. For teams preparing 2026 budgets and sourcing plans, the question is not whether to act — but how quickly and with which partners.
For detailed analysis of this topic, please visit the official page: Automotive Embedded Storage (eMMC and UFS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com