

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Healthy Lifestyle
Food Leavening Agents: Asia Pacific Tops at $360.17M, Market to Reach $998.41M by 2032 (3.8% CAGR)
By pmarketresearch, 2026-07-09
Food Leavening Agent Market — Strategic Preview for 2026 Decision-Makers
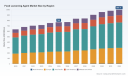
As the global food industry recalibrates for the post‑pandemic recovery and rising consumer demand for convenience and premium baked goods, the food leavening agent market is transitioning from steady commodity dynamics to an innovation‑led, channel‑sensitive growth phase. PW Consulting’s latest research (base year 2025) tracks a clear macro trajectory: the market expanded from an estimated USD 638.17 Million in 2020 to roughly USD 769.0 Million in 2025 and is forecast to approach approximately USD 998.4 Million by 2032, driven by a projected compound annual growth rate (CAGR) of 3.8% across the 2026–2032 forecast window.
Food Leavening Agent Market
Why this study matters for 2026 strategy
-
Decision clarity in a crowded field: With mid‑single‑digit CAGR and uneven growth pockets across product types and channels, executives must choose between efficiency plays (scale and commodity sourcing) and differentiation (clean‑label, specialty yeasts, premixes).
Food Leavening Agent Market -
Timing investments: 2026 is a tipping point year for capacity and product investments. Our report aligns operational timing with demand inflection points and regulatory timelines so capital deployments are synchronized with market uptake.
Food Leavening Agent Market -
Regulatory and raw‑material shocks: The interplay of organic standards, GRAS classifications, and sourcing constraints for bicarbonates and ammonium salts requires integrated risk mitigation across procurement, formulation, and labeling.
Market trajectory and structural signals
The market’s steady baseline growth is underpinned by two parallel forces. First, volume growth in industrial and in‑store bakery channels is being supplemented by premiumization — demand for clean‑label premixes, specialty yeasts, and formulation innovations that improve shelf quality and texture. Second, supply‑side consolidation and scale advantages are generating a concentrated landscape: the top three firms capture a materially high share of the market, with the top five firms commanding an even larger portion—an important structural consideration for entrants and mid‑tier suppliers contemplating M&A, distribution partnerships, or co‑manufacturing agreements.
These structural signals mean that price competition will remain intense in commodity segments (standard bicarbonates and basic chemical leaveners), while margin expansion opportunities will exist in proprietary blends, instant dry yeasts, and specialty premixes serving artisanal and foodservice customers.
Segmentation lens (selective—high level)
-
Type dynamics: The market comprises chemical, biological (yeast‑based), and physical leavening solutions. Chemical leaveners continue to dominate volumes due to broad utility and low cost, while biological solutions are the fastest area for product innovation and clean‑label marketing.
-
Application pathways: Core applications include traditional bakery categories such as bread, biscuits/cookies, cakes/pastries, and rolls/pies. Each application reflects distinct formulation needs, procurement cadences, and shelf‑life considerations—factors we map precisely in the full report.
-
Regional implications: Growth pockets vary by cluster—mature markets emphasize process efficiency and clean labeling, while developing markets are driven by rising retail penetration and industrialization of baking. For confidentiality of competitive segmentation, the report’s granular regional and channel splits are reserved for subscribers.
Competitive landscape — who matters and why
The leavening agent ecosystem mixes global ingredient majors, specialized yeast houses, and regional brand incumbents. Market concentration metrics indicate a high share held by the leading players, making strategic positioning around channel control, brand reputation, and formulation IP critical.
-
Large agribusiness and ingredient players (e.g., major processors of sodium and ammonium bicarbonate) provide scale, strong logistics, and cost advantage for commodity leaveners. These firms are natural suppliers to industrial bakers and premix producers.
-
Specialized yeast manufacturers and baking ingredient houses emphasize technical collaboration with bakers, R&D for premixes, and service models (product training, formulation support). These firms are where the market’s highest margin innovation typically originates.
-
Regional brands and legacy names continue to capture retail trust and home‑baker demand; their brand equity enables price premiums in specific channels.
Key companies profiled in our landscape include leading global yeast and baking ingredient suppliers, household baking brands, and diversified ingredient processors. Each profile includes strategic positioning, product portfolios, route‑to‑market analysis, recent corporate developments, and likely next‑move scenarios for 2026–2028. Noteworthy recent developments captured in the study include the commissioning of new specialty yeast capacity by a major yeast producer in 2026 and targeted product launches in selected markets in 2025—both of which have immediate ramifications for supply, pricing and innovation cycles.
Regulatory and raw‑material dynamics — actionable risk factors
-
Raw materials: Ammonium bicarbonate and sodium bicarbonate remain foundational to formulations across pancakes, biscuits and muffin categories. Their availability, quality specifications and handling requirements are assessed in the report’s procurement risk module.
-
Regulatory guardrails: Several leavening agents and supporting substances have explicit regulatory treatments that affect labeling eligibility in organic and processed organic claims. For example, certain ammonium salts are permitted only under specific organic program provisions until regulatory reassessment dates; parallel GRAS affirmations and allowed uses exist for bicarbonates.
-
Packaging and shelf‑life: Commodity storage practices and packaging decisions (e.g., baking soda shelf life under standard handling) materially affect inventory turns and obsolescence risk for manufacturers and distributors.
Our regulatory module cross‑maps these constraints to product portfolios and go‑to‑market claims, enabling legal and regulatory teams to prioritize reformulation or labeling changes before market or compliance breaches occur.
What the full report delivers (practical, executable content)
-
Market forecast model: Scenario‑based projections to 2032 with sensitivity levers for raw‑material shocks, regulatory changes, and adoption rates of clean‑label alternatives.
-
Demand segmentation toolkit: Channel and application demand drivers, buyer personas, and unit economics for industrial vs. artisan segments (note: our publicly circulated preview omits granular regional and application revenue splits—these are available in the subscriber dataset).
-
Supplier scoring and sourcing playbook: Comparative supplier heatmaps, cost benchmarking, and negotiation tactics to secure bicarbonates and specialty yeast supply under variable lead times.
-
Product and innovation roadmap: Priority product concepts, estimated development timelines, and go‑to‑market positioning for clean‑label premixes and high‑purity leavening blends.
-
M&A and partnership playbook: Acquisition targets, valuation heuristics, and integration checklists for buyers seeking to consolidate mid‑market manufacturing or to enter high‑growth specialty segments.
-
Regulatory watchlist and contingency plans: A rolling calendar of regulatory review dates, labeling risks, and recommended compliance actions mapped to product lines.
Strategic priorities for 2026 — an executive playbook
-
Prioritize margin expansion in specialty products: Shift R&D and commercial resources toward yeast‑based and clean‑label premixes where technical support and brand partnerships can protect margins.
-
Secure upstream inputs with flexible contracts: Hedge exposure to bicarbonate availability by diversifying suppliers and incorporating volume‑based pricing triggers; consider strategic inventory for peak seasons.
-
Pursue targeted capacity moves: Use selective capex or tolling arrangements to accelerate time‑to‑market for specialty blends—especially where regulatory labeling windows create temporary market access advantages.
-
Deploy channel segmentation: Separate commercial strategies and KPIs for industrial bakers, artisan/professional bakers, and home‑use retail channels. Tailored packaging, logistics, and training programs improve uptake and stickiness.
-
Prepare for regulatory shifts: Assign cross‑functional owners to monitor organic labeling windows and GRAS‑related updates that could affect product eligibility and marketing claims.
-
Evaluate consolidation opportunities: Given the market concentration of leading players, mid‑tier firms should consider bolt‑on acquisitions or exclusive distribution partnerships to build scale quickly.
How to use this intelligence
Leaders in procurement, R&D, corporate development and commercial functions will find immediate value in the report’s intersectional insights—combining demand forecasts, supplier risk mapping, and innovation roadmaps into executable quarter‑by‑quarter plans. We designed the deliverables so that a CPG product lead can move from insight to pilot in 90 days, and a corporate development team can prepare an acquisition thesis within 60 days.
Note on data scope: this preview purposely surfaces strategic conclusions and macro metrics (including market size trajectory and concentration indices) while withholding detailed revenue splits across regions, product sub‑types and applications. These granular datasets and interactive models are available in the full report package and are essential for granular investment decisions, pricing models, and go‑to‑market allocation.
Next steps
-
Request the full dataset and interactive forecast model to run custom scenarios for your portfolio.
-
Schedule a strategy workshop with PW Consulting to translate findings into a 12‑month action plan tailored to your position in the value chain.
-
Engage our M&A advisory team to explore consolidation targets and valuation frameworks aligned with the market’s concentration dynamics.
For access to the complete Food Leavening Agent Market study—including the subscriber‑only regional and application revenue matrices, supplier scorecards, and an editable scenario model—visit the PW Consulting report page or contact our industry team to arrange a confidential briefing.
For detailed analysis of this topic, please visit the official page: Food Leavening Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Glycoprotein Market to hit USD 0.84B by 2032 at 3.75% CAGR
By pmarketresearch, 2026-07-09
Glycoprotein Market 2026: Strategic Imperatives and Decision Frameworks for Life‑Science Leaders
As PW Consulting’s Senior Strategic Advisor and Head of Industry Analysis, I present an executive overview of our latest Glycoprotein Market study — a practitioner’s playbook for executive teams making capital, product and partnership decisions in 2026. The glycoprotein landscape is at an inflection point: modest compound annual growth, accelerating analytical complexity, and a wave of instrument- and process‑level innovations are reshaping where value will accrue over the coming investment cycle. This introduction summarizes the strategic value of the research, key market signals, competitive dynamics, and precisely how this intelligence should change decision-making in 2026 — while intentionally holding back the full segment‑level tables and datasets to preserve the report’s commercial depth.
Glycoprotein Market
Macro snapshot you can act on
-
Market scale and trajectory: The global glycoprotein market reached approximately USD 0.65 Billion in our base year (2025). Under the forecast window (2026–2032) the market is projected to expand at a compound annual growth rate (CAGR) of 3.75%, reaching roughly USD 0.84 Billion by 2032. These rates reflect steady, application‑driven adoption rather than a single transformational demand shock.
Glycoprotein Market -
Historic momentum: From 2020 through 2025 the market moved from early commercialization into broader adoption across therapeutics, diagnostics and research workflows. That foundation matters: incremental product innovations and regulatory pressures — not volume surges alone — will determine winners.
Glycoprotein Market -
Competitive structure: The market exhibits moderate concentration, with a handful of established suppliers anchoring product and services ecosystems while numerous niche specialists compete on depth of analytical support, custom offerings, and speed to result.
Why this research matters for 2026 decisions
-
Capital allocation and R&D prioritization. With growth steady but not explosive, capital deployed into glycoprotein‑related capabilities must be justified by either margin expansion (e.g., premium analytics, platformized reagents), defensible cost advantage (scale in bioprocess analytics) or strategic lock‑in (ecosystem partnerships with instrument vendors). Our models translate market growth rates into IRR sensitivities for R&D and manufacturing projects under three plausible adoption scenarios.
-
Regulatory preparedness. Recent and forthcoming guidances are materially affecting analytical scope. Notably, authorities have raised expectations for glycan characterization in biosimilarity and comparability workstreams. These requirements increase the analytic burden on sponsors and their service providers, creating near‑term demand for validated, scalable glycosylation workflows — and reopening the procurement conversation for contract labs and instrumentation vendors.
-
Product and go‑to‑market sequencing. The roadmap for launching reagents, assays, or instrumentation must now balance speed (time‑to‑lab adoption) against validation rigor demanded by regulated manufacturers. Our report includes practical go‑to‑market playbooks that map product features to buyer personas, required validation evidence, and pricing frameworks.
Key market dynamics shaping 2026 strategy
-
Analytical intensification. Regulatory guidance and biosimilar comparability requirements have raised the baseline for glycan and glycoprotein characterization. Organizations without validated high‑throughput workflows will find licensing, bridging and release timelines elongated. This is a near‑term growth lever for providers of automated assays, mass‑spec platforms and validated kits.
-
Platform consolidation vs. best‑of‑breed. Instrumentation vendors are bundling software and analytics (e.g., unified glycoproteomic data platforms) to sell solution value beyond hardware. At the same time, niche reagent suppliers continue to win early‑stage research and discovery work. Strategic responses differ: incumbents should invest in software/analytics to maintain customer lock‑in; specialized firms should pursue partnerships or certification routes that accelerate adoption in regulated labs.
-
Process analytics and manufacturing impact. Inline and continuous PAT approaches for monoclonal antibody (mAb) production are moving from pilots to commercial scale. Early industrial validations report tangible process improvements — yield increases and glycation control — which translate to both cost savings and improved product consistency. This dynamic increases demand for analytical consumables as well as advanced sensors and chemometrics.
-
Geographic and therapeutic expansion. Market growth is being driven by expanded use of glycoprotein‑targeted therapeutics and by diagnostic sophistication in established markets. Parallel growth in several emerging biopharma clusters is creating new licensing and collaboration opportunities for suppliers with global regulatory coverage and local partnerships.
Competitive landscape — what matters to buyers and partners
Our vendor analysis synthesizes company profiles, recent product and process developments, strategic positioning, and execution risk. The following are high‑level strategic takeaways for boards and commercial leaders evaluating partnership or procurement strategies in 2026.
-
Thermo Fisher Scientific — strategic scale and process integration. Thermo Fisher’s investments in validated process analytical technologies demonstrate a clear play to capture value across discovery, development and manufacturing. Their validated continuous Raman solutions and broad portfolio (from isolation kits to high‑resolution mass specs) position them as a one‑stop vendor for biopharma customers seeking end‑to‑end validated workflows.
-
Bruker — platform differentiation through software. Bruker’s introduction of the timsOmni mass spectrometer with integrated GlycoScape software emphasizes the growing importance of software‑enabled analytics. For buyers, Bruker’s integrated platform reduces downstream data harmonization costs — a meaningful advantage in regulated characterization campaigns.
-
R&D Systems (Bio‑Techne), ACROBiosystems, Sigma‑Aldrich and others — reagents and recombinant supply strength. These suppliers continue to dominate research and early development with deep catalogs of recombinant glycoproteins, standards and ELISA kits. Their strategic choices — portfolio expansion versus targeted co‑development with instrument vendors — will determine how much of the commercial‑scale market they capture.
-
Creative Diagnostics, Enzo Life Sciences, Epitope Diagnostics, BD Biosciences — niche and clinical bridge players. These firms serve distinct buyer segments (custom antibody services, diagnostic kits, flow cytometry reagents). Their proximity to clinical labs and diagnostic OEMs makes them attractive partners for rapid regulatory validation pathways.
Recent developments that change the 2026 calculus
-
Validated PAT for commercial mAb upstream processes: Leading vendors have published process validations demonstrating meaningful titer gains and glycation control. These prove‑points accelerate adoption of inline glycosylation monitoring and alter OKR targets for manufacturing teams.
-
New rapid characterization methods: Industry announcements of ultra‑rapid glycan characterization protocols compress analytical turnaround, lowering the cost of compliance and enabling more frequent release testing — an operational advantage for firms competing on speed.
-
Regulatory tightening on glycan comparability: Updated guidances have increased the quantity and depth of data expected for biosimilarity assessments. This creates demand for validated, high‑confidence analytics and increases the value of vendor services that can supply both instruments and validated methods.
Actionable recommendations for executive teams in 2026
-
For instrument and software vendors: prioritize validated end‑to‑end workflows and regulatory documentation. Buyers increasingly value out‑of‑box compliance evidence — invest in method validation studies and co‑development pilots with marquee biopharma partners.
-
For reagent and specialty providers: focus on certification pathways that enable use in regulated labs (kit validations, ISO/GLP traceability). Consider channel partnerships with instrument OEMs to bundle offerings and accelerate adoption.
-
For biopharma developers and CMOs: reframe analytical budgets as yield and release acceleration levers. Invest selectively in PAT and high‑throughput glycan analytics where payback comes from fewer comparability risks and shortened release timelines.
-
For private equity and corporate development teams: use the moderate growth profile and identifiable de‑risking pathways to create value via roll‑up strategies that combine scalable reagent supply, software analytics and niche CDMO capabilities.
What the full PW Consulting Glycoprotein Market report delivers
The published study contains granular, operationally focused deliverables: multiple forecast scenarios (including sensitivity to regulatory and technology adoption inflection points), commercial‑grade TAM and SAM models, segment‑level buyer persona maps, vendor assessment matrices, M&A playbooks, and ready‑to‑use slide decks for board and investor presentations. It also includes detailed annexes with methodology, primary interview transcripts, and validation datasets. To preserve the report’s commercial value and to comply with the “trailer” principle of this executive brief, detailed segment splits and numeric breakdowns by region, type and application are available only in the full report and online data portal.
Closing perspective
The glycoprotein market in 2026 offers steady growth and high strategic optionality. The most valuable moves are not merely launching another reagent or instrument; they are the orchestrated bets that combine validated analytics, software‑enabled value capture, and regulatory‑grade evidence. For decision‑makers, our research reframes the conversation: invest to de‑risk comparability and validation, partner to scale faster, and prioritize offerings that convert regulatory burden into commercial lock‑in. PW Consulting’s full report supplies the quantitative maps and tactical playbooks you need to execute those choices with precision.
To access the complete dataset, vendor scorecards, and customizable financial models referenced here, please visit the PW Consulting research portal or contact our industry team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Glycoprotein Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vaccine Adjuvants Market to Reach USD 2,206.5M by 2032 at 6.5% CAGR
By pmarketresearch, 2026-07-09
Vaccine Adjuvants Market: Strategic Imperatives for 2026 Decision-Makers
As the life sciences industry enters 2026, vaccine adjuvants have moved from a niche technical detail to a central strategic lever in vaccine R&D, commercialization and public-health preparedness. PW Consulting’s new market research — anchored on a 2025 base year and projecting through 2032 — quantifies the momentum: the global vaccine adjuvants market is estimated at approximately USD 1.44 billion in 2025 and is forecast to reach roughly USD 2.21 billion by 2032, expanding at a compound annual growth rate (CAGR) of 6.5% over the forecast horizon. These headline numbers understate the structural shifts now driving value creation, risk concentration and opportunity windows that corporate leaders must act on this year.
Vaccine Adjuvants Market
Why this research matters in 2026
- Portfolio prioritization: Biotech and big pharma leaders must decide which antigen-adjuvant pairings to advance into clinical development and where to allocate limited CMC and regulatory resources.
- Manufacturing investments: With demand for adjuvanted vaccines rising (both for infectious disease and immuno-oncology indications), manufacturers face critical capacity and sourcing choices — decisions with multi-year payback horizons.
- M&A, partnerships and licensing: The adjuvants ecosystem is consolidating around platform owners and specialized suppliers; strategic transactions executed in 2026 will shape competitive positioning for the rest of the decade.
Key macro dynamics shaping strategy
- Platform differentiation is now a commercial advantage. Proprietary platforms (e.g., Matrix‑M, AS01/AS03, MF59, CpG 1018) are more than efficacy enhancers: they are commercial enablers, lowering antigen dose requirements, broadening target populations and improving vaccine durability. Recent regulatory and commercial wins have validated this dynamic and accelerated platform adoption.
- Regulatory complexity lengthens timelines. Regulators in major markets continue to impose stringent expectations for novel and combination adjuvants, particularly for lipid- and protein-based systems. Firms must budget for extended nonclinical packages, additional comparability studies and more intensive post-marketing commitments — factors that materially affect go/no-go timing and net present value.
- Supply-chain fragility is a live risk. Key raw material sources remain geographically concentrated. For example, commercially used saponin adjuvants are still derived from Quillaja saponaria bark, exposing programs to biological, environmental and geopolitical supply shocks. That reality elevates the value of vertically integrated supply strategies and validated synthetic or semi-synthetic alternatives.
- Reimbursement and pricing dynamics are tightening. Public payers and large purchasers increasingly scrutinize incremental clinical benefit from adjuvanted vaccines relative to cost; reimbursement rules and seasonal vaccine price-setting mechanisms will influence commercialization strategies, particularly in developed markets.
- Manufacturing scale and partnerships matter. Recent capacity-expansion deals underscore a market moving from bespoke lab-scale production to GMP mass manufacturing. Companies with proven scale-up pathways or strategic partnerships with CDMOs will be positioned to capture near-term demand shocks and longer-term market growth.
Competitive landscape — who matters and why
The adjuvants market is moderately concentrated: the top three suppliers account for a material share of market value, and the top five increase that concentration further. This creates both entry barriers and partnership opportunities. Our analysis highlights three archetypes among incumbent and emerging players:
Vaccine Adjuvants Market
- Platform holders with clinical-validated systems: Companies that own licensed, clinically proven adjuvant platforms are in the strongest position to extract premium pricing and negotiate antigen-agnostic partnerships. These players drive innovation through platform improvements and cross-licensing.
- Specialist suppliers and component houses: Firms focused on specific adjuvant chemistries or manufacturing capabilities (e.g., aluminum-based adjuvants, TLR agonists, emulsion systems) function as critical supply-chain nodes. Their technical excellence makes them attractive partners for antigen developers and CDMOs.
- R&D enablers and preclinical suppliers: Providers of research-grade adjuvant components and assay platforms enable early-stage screening and translational work, shaping which platforms advance to clinical evaluation.
Representative companies that feature prominently in our competitive maps include platform-centric innovators such as Novavax (Matrix‑M), GlaxoSmithKline (AS01/AS03), and CSL (MF59) — firms that combine regulatory track records with commercial-scale manufacturing. Complementary suppliers and technology specialists — including developers of QS‑21 derivatives, CpG platforms, aluminum-based products and a range of TLR agonists — round out the ecosystem. Recent market events (regulatory approvals, platform launches and capacity partnerships) validate the strategic trajectories of these firms and confirm where competitive tensions will be fiercest.
Vaccine Adjuvants Market
Recent developments that change the playbook
- Regulatory validation accelerates platform adoption: A high-profile, protein‑based vaccine recently received regulatory approval that leverages an established adjuvant platform — an event that has immediate implications for licensing demand and for the commercial appetite of antigen developers.
- Platform innovation and product launches: Major players have introduced new adjuvant platforms intended to enhance efficacy across multiple vaccine candidates, signaling intensified competition at the platform level.
- Capacity expansion through partnerships: Strategic alliances between adjuvant developers and CDMOs are expanding the pool of available GMP manufacturing capacity for adjuvants, which de-risks commercialization timelines for later-stage vaccine candidates.
What the report delivers — practical, actionable intelligence
PW Consulting’s report is structured to convert insight into action. Key deliverables include:
- Top-line market sizing and verified forecasts (2020–2025 historical analysis; 2026–2032 forecast) with scenario variants that stress-test the impact of regulatory delay, supply disruption and accelerated platform adoption.
- Technology landscape maps that identify leading platforms, their clinical validation status, and technology gaps where investment or licensing could create differentiation.
- Regulatory pathways and dossier playbooks for novel vs. established adjuvants, including recommended nonclinical comparability studies and post‑market surveillance frameworks.
- Supply‑chain risk heatmaps and mitigation strategies, including sourcing diversification plans and candidate synthetic alternatives for supply‑constrained inputs.
- Commercial models and reimbursement sensitivity analyses to estimate net revenue under varying pricing and payer scenarios.
- Competitive benchmarking and a partner/target shortlist for licensing, co-development and M&A, aligned to specific corporate objectives (e.g., speed-to-market, margin expansion, or pipeline breadth).
- Operational playbooks — 90/180/365 day actions — tailored for R&D heads, CMC leaders and corporate development teams to implement immediately.
Note: This executive preview highlights the research’s strategic value but does not disclose the segmented tables and granular regional or application-level splits contained within the full report. Those segment-level models and company-level revenue breakouts are available in the complete study.
How executives should use this research in 2026
- CEOs and corporate development: Use the market-sizing scenarios and concentration analysis to set acquisition thresholds, identify priority partnership targets and calibrate bid pricing for platform assets.
- R&D and clinical teams: Leverage the technology maps and regulatory playbooks to select adjuvant partners and design early‑phase packages that reduce regulatory risk and preserve optionality.
- Manufacturing and supply‑chain leaders: Implement the supply‑risk mitigation strategies and CDMO selection criteria to protect timelines for pivotal trials and initial commercial launches.
- Commercial and pricing teams: Apply the reimbursement sensitivity models to forecast launch economics in major payer jurisdictions and to structure tender and private‑market strategies.
Bottom line — the strategic bets for 2026
The vaccine adjuvants market sits at an inflection point. The sector’s steady macro growth (a mid-single-digit CAGR through 2032) masks a bifurcation: platform owners with validated clinical outcomes and secure supply chains will command growing commercial premiums, while smaller suppliers without scale or regulatory depth face margin compression and acquisition pressure. For decision-makers in 2026, the imperative is clear: secure access to clinically validated platforms; de‑risk critical raw materials; align regulatory strategies to the most likely payer environments; and prioritize partnerships that accelerate manufacturing readiness.
PW Consulting’s full report operationalizes these imperatives with the data, scenario models and playbooks leaders need to make confident, high‑impact choices this year. For corporate leaders ready to convert insight into advantage, the complete study provides the granular segmentation, partner scorecards and executable roadmaps that will determine who wins in the adjuvants‑enabled vaccine marketplace.
For detailed analysis of this topic, please visit the official page: Vaccine Adjuvants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Disposable Laparoscopic Trocars Market to reach USD 849M by 2032 at 7.2% CAGR
By pmarketresearch, 2026-07-09
Disposable Laparoscopic Trocars Market — Strategic Outlook for 2026: A PW Consulting Briefing
As hospitals accelerate minimally invasive procedures and OEMs sharpen portfolios for cost-conscious procurement, disposable laparoscopic trocars sit at the intersection of clinical demand, regulatory scrutiny, and manufacturing scale. Our new market study, built on a comprehensive 2020–2025 historical base and a 2026–2032 forecast horizon, converts that complexity into a practical playbook for 2026 decision-making. Below we synthesize the headline dynamics, competitive posture of leading players, and the specific levers executives should prioritize to convert market growth into sustainable advantage — while preserving the core, segment-level datasets for subscribers who download the full report.
Disposable Laparoscopic Trocars Market
Market trajectory — the macro view
Between 2020 and 2025 the disposable laparoscopic trocar market exhibited steady expansion consistent with broader adoption of minimally invasive surgery and hospital preference for single-use devices that reduce cross-contamination risk and sterilization overhead. Our model shows clear momentum through the base year (2025) and into the forecast window: the market grows at a compound annual growth rate of approximately 7.2% thereafter, with the base market moving from mid-three-hundreds (USD millions) in 2020 to just over half a billion by 2025, and continuing to expand toward the high hundreds by the end of the forecast period.
Disposable Laparoscopic Trocars Market
Two practical deductions flow from this trajectory for 2026 planning. First, total-addressable-market expansion is driven by a combination of elective surgical volume recovery, substitution of reusable devices in some settings, and incremental uptake of procedure types that favor trocar-based access. Second, the growth rate is healthy but not hyperbolic — meaning that share gains will be earned through execution (product differentiation, supply reliability, and targeted commercial coverage), not by riding a runaway market tailwind.
Disposable Laparoscopic Trocars Market
Why this report matters to 2026 enterprise decisions
- Portfolio prioritization: With steady market growth, management teams must decide which trocar variants and adjacent access technologies to prioritize. Our study translates macro growth into short- and medium-term revenue opportunity maps, enabling resource reallocation decisions that maximize ROI within 12–24 months.
- Manufacturing & sourcing strategy: Single-use devices are sensitive to unit economics and logistical friction. The report identifies where scale matters most and where nearshoring or dual-sourcing unlocks margin resiliency versus competitive exposure.
- Regulatory and quality assurance posture: Recent regulatory events in the sector underscore the importance of post-market surveillance and packaging controls. We profile regulatory risk vectors and provide a remediation checklist suitable for 510(k)-driven portfolios and international markets.
- M&A and partnership screening: A measured market growth profile favors bolt-on acquisitions and technology partnerships to access differentiated features quickly. Our actionable target framework prioritizes candidates based on clinical fit, regulatory status, and integration risk.
- Commercial models & procurement playbooks: Hospitals prize reliability and predictable pricing. The analysis identifies profitable pricing structures and procurement levers (consignment, value-based contracting, bundled procedure pricing) that sales teams should institutionalize in 2026 negotiations.
Competitive landscape — who matters and why
The competitive set is diverse: global medtech majors with broad surgical portfolios sit alongside specialist device manufacturers and regional low-cost producers. This heterogeneity creates strategic choices for incumbents and challengers alike.
- Medtronic (Dublin, Ireland) — Leverages a broad access instruments franchise and proven bladeless designs to compete on brand familiarity, clinical training programs, and integrated OR offerings. Strength: scale and clinical relationships; risk: commoditization pressure in basic trocar segments.
- Ethicon / Johnson & Johnson (Cincinnati, Ohio) — Emphasizes manufacturing robustness and leak-mitigation engineering in its disposable trocar family. Strength: deep surgical channel and established pricing power; risk: exposure to bundled procurement negotiations by health systems.
- B. Braun Melsungen (Melsungen, Germany) — Offers a wide single-use trocar range and benefits from strong European hospital penetration. Notably, a packaging control issue prompted a Class 2 recall in January 2024 for a Hasson trocar product — a reminder that quality lapses materially affect reputation and access. Strength: portfolio breadth; risk: reputational/regulatory event impacts.
- CONMED (Largo, Florida) — Focuses on access systems such as BluView cannulas and optimized trocar kits, seeking differentiation through complementary instrument ecosystems.
- Teleflex (Wayne, Pennsylvania) — Competes with bladeless access ports and small-form factor systems, positioning for percutaneous and ambulatory surgery use cases.
- Applied Medical (Rancho Santa Margarita, California) — Known for its Kii Fios system and fixation technology; competes on rapid desufflation and first-entry performance.
- Purple Surgical (UK) — A smaller specialist focused on optical trocar lines with direct-vision safety features; competes on niche clinical preference and value pricing in select markets.
- Xinwell Medical & Changzhou Ankang (China) — Represent the increasing role of China-based suppliers. Changzhou Ankang’s receipt of FDA 510(k) clearance in mid-2023 is a notable demonstration of capability to serve regulated markets. Strength: low-cost manufacturing and supply agility; risk: perception and regulatory due diligence hurdles for Western hospital procurement.
Strategically, the market is neither fully consolidated nor atomized: the largest global players collectively approach half the industry’s revenue while the top five represent a clear majority. That mix makes both scale plays and focused specialization viable — but each requires distinct go-to-market discipline.
Regulatory & quality dynamics — practical implications
Two recent items warrant executive attention in 2026 planning:
- Regulatory enforcement and recalls can produce rapid share shifts in hospital contracts. The January 2024 Class 2 recall involving an Aesculap (B. Braun) Hasson trocar highlights the operational and reputational costs of packaging and change-control lapses.
- Market entry pathways remain accessible but demanding. The 510(k) clearance secured by Changzhou Ankang in June 2023 demonstrates a viable route for emerging suppliers to gain access to regulated markets — but due diligence and lifecycle support commitments are prerequisites for procurement teams.
Actionable implication: Companies must invest in traceability, supplier audit capacity, and packaging controls now, not later. For buyers, contract language tied to quality metrics and recall remediation speed should be standardized.
What the PW Consulting report delivers (practical, executable content)
This study is designed as a go-to operational tool for commercial, R&D, and corporate development teams. Highlights include:
- Detailed market sizing and 2026–2032 forecasts with scenario sensitivity to elective procedure rates, reimbursement shifts, and supply-chain disruption.
- Segment- and product-level demand drivers, with adoption curves and feature-preference matrices that link clinical needs to willingness-to-pay.
- Competitive benchmarking and capability maps for leading manufacturers; supplier scorecards for regulatory history, manufacturing footprint, and commercial reach.
- Pricing & margin models and procurement negotiation playbooks that translate market dynamics into immediate commercial actions.
- Regulatory timeline tracker and quality-risk checklist derived from real-world recall and clearance events.
- M&A and partnership shortlist methodology with quantified integration risk and transaction economics (NPV and payback analyses).
- Implementation playbooks: six prioritized 90/180/360-day actions for market entry, share defense, or product-line expansion.
To preserve the report’s strategic premium and respect client confidentiality, the core segment-level tables (type-by-application-by-region breakouts, detailed pricing curves, and target company valuation sensitivity) are available only in the full report. The summary here provides the directional insight needed to act immediately; the detailed intelligence enables execution.
Recommended 2026 initiatives — a pragmatic checklist
- Prioritize product features that demonstrably reduce OR time and leakage rates — invest in clinical validation studies targeted at high-frequency procedures.
- Strengthen packaging and change-control governance; conduct immediate supplier audits and update recall playbooks.
- Pursue supply diversification pilots in regions where single-source exposure is highest; model the unit-economics impact within 60 days.
- Embed outcome-based clauses in tender responses for high-value accounts to reduce commodity pressure and align on shared savings.
- For growth-seeking corporates, evaluate tuck-in acquisitions in adjacent access technologies and Asian contract manufacturers with proven regulatory pathways.
Next steps — how to use the study
If your agenda for 2026 includes deciding where to invest R&D dollars, how to defend pricing against aggressive tendering, or which manufacturing footprint to scale, the full PW Consulting report is constructed as an executable decision-support tool. We recommend three immediate engagements:
- An executive briefing tailored to your portfolio (60 minutes): maps our forecast to your SKU-level P&L and highlights 3 near-term moves with estimated ROI.
- A commercial deep-dive (working session): uses our procurement playbook and competitor scorecards to prepare for upcoming tenders or account renewals.
- A regulatory & supply-chain stress test: operationalizes our compliance checklist and runs scenario simulations for recall and supplier failure events.
In sum, the disposable laparoscopic trocar market offers steady growth and multiple pathways for value creation in 2026 — but advantage will accrue to organizations that combine clinical-led product design, rigorous quality systems, supply resilience, and surgical-channel commercial discipline. The full PW Consulting study contains the proprietary segment analytics, competitive scorecards, and implementation templates required to turn those strategic insights into delivered performance. For access to the complete datasets and tailored advisory support, visit the report page or contact our healthcare strategy team to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Disposable Laparoscopic Trocars Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Sanger Sequencing Service Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
The Sanger sequencing services market is re-accelerating into the mid-2020s as a stable, mission‑critical segment of genomics infrastructure. Our base-year assessment (2025) places the market squarely above the billion‑dollar threshold (USD Million scale), and the forecast through 2032 projects a sustained compound annual growth rate of approximately 13.35%. That trajectory reflects a market that is large enough to attract diversified global providers, yet sufficiently fragmented to reward focused capabilities, service quality, and tactical partnerships.
Sanger Sequencing Service Market
Why this study matters for 2026 strategic choices
Executives planning 2026 resource allocations face three linked realities: accelerating demand for targeted and regulatory-compliant sequencing; consolidation and selective acquisition among established service providers; and the persistence of decentralized, contract-based delivery models across academia, industry, and clinical environments. This report is designed to translate those realities into actionable choices across five priority decisions:
Sanger Sequencing Service Market
- Capacity and capital planning: when to expand internal sequencing versus outsource, and which outsourcing models minimize time-to-result for priority workflows.
- Go-to-market and pricing: how to position service tiers (rapid turnaround, GLP/GMP/regulatory, high-quality difficult-template solutions) to defend margin while addressing commoditization pressures.
- M&A and partnership screening: which targets or alliances create defensible value (geography, regulatory credentials, specialized application depth) without duplicative cost bases.
- Operational risk and compliance: how to align lab quality systems, sample handling, and data governance with shifting regulatory expectations and enterprise procurement requirements.
- Product and service portfolio choices: which adjacent services (e.g., synthesis, fragment analysis, integrated sample-to-insight pipelines) should be layered onto Sanger offerings to increase customer lifetime value.
Market dynamics: what the numbers tell us (high level)
From 2020 through our base year, the market expanded steadily, reflecting both the ongoing need for gold‑standard single‑read validation in research and a resurgent role for Sanger in diagnostic confirmation, biomarker verification, and regulated workflows. The projection into 2026–2032 shows an amplified growth phase driven by three structural factors: (1) increasing diagnostic and biomarker testing volumes that require confirmatory methods; (2) outsourcing by institutions and labs optimizing capital utilization; and (3) new service models that blend speed, regulatory compliance, and integrated data outputs.
Sanger Sequencing Service Market
Importantly, the market concentration metric indicates a moderate degree of consolidation: several large providers account for a meaningful share of revenue while a long tail of regional and specialty providers remains active. That balance produces differentiated competitive opportunities — scale and integrated portfolios matter, but niche service excellence continues to capture premium demand.
What the full report delivers (practical outputs)
This study is written for commercial leaders, procurement heads, lab directors, and corporate development teams who must translate market movement into a 12–36 month plan. Key deliverables include:
- Top-line market sizing and growth scenarios (base year and forecast to 2032) with sensitivity analysis across conservative, base, and accelerated adoption cases.
- Segment-level demand drivers and risk maps for applications, end‑users, and delivery channels — with prioritized use cases for near‑term investment.
- Pricing and cost benchmarks (banded and contextualized) to guide commercial negotiation and internal transfer pricing design — presented without raw contract-level disclosure but with practitioner-ready guidance.
- Operational playbooks for insourced vs outsourced sequencing, including sample logistics, QC gating, and turnaround SLAs that materially impact downstream projects.
- Regulatory and reimbursement pathways mapped to service types and clinical claims, and a compliance checklist tailored to 2026 audit expectations.
- Vendor landscaping and scorecards — capability matrices, regulatory credentials, geographic reach, and integration readiness — framed to inform RFP design and short‑list selection.
- M&A and partnership frameworks with valuation multipliers, integration risk factors, and recommended diligence questions specific to sequencing service targets.
Competitive landscape — how incumbent and emergent providers are positioning
The commercial field is anchored by long‑standing laboratories that combine high throughput with regulatory competencies, and specialist operators that compete on speed or vertical focus. Several strategic archetypes have emerged:
- Global full‑service incumbents that bundle Sanger with broader genomics portfolios (sequencing, synthesis, data analytics), pursuing consolidation through acquisitions and continent‑spanning service centers.
- Rapid‑turnaround specialists offering tightly engineered workflows and service SLAs to capture time‑sensitive R&D and QC workflows.
- Regionally dominant providers that leverage local regulatory knowledge and institutional relationships to serve clinical and academic markets.
- Niche operators targeting domain‑specific demand such as agricultural genomics, difficult-template sequencing, or low-volume clinical confirmations.
Our vendor chapter profiles a curated set of providers representative of these archetypes, assessing their strategic intent, capability gaps, and likely moves in 2026. Highlights include:
- Providers with regulatory‑grade offerings and GLP/GMP pathways that are most attractive to biopharma and clinical customers seeking validated workflows for submissions and QC.
- Operators that have invested in speed‑centric platforms and processes to deliver rapid turnarounds for R&D verification and plasmid/PCR product checks.
- Global service networks that combine local lab presence with centralized quality systems — a configuration increasingly favored by multinational R&D organizations.
Recent industry moves and their strategic implications
The market is experiencing active reshaping through several notable events that inform immediate strategy:
- Several academic cores have begun to sunset in‑house Sanger operations and redirect demand toward commercial providers — a shift that creates near‑term volume opportunities for external labs and underscores the importance of scalable intake, transparent pricing, and academic contracting familiarity.
- Acquisitions and portfolio integrations among major service providers are expanding regulatory and NGS-complementary capabilities, signaling that buyers will increasingly evaluate sequencing suppliers on end‑to‑end genomics service breadth rather than siloed capabilities alone.
- New platform and service launches that blur the line between classical Sanger services and personalized healthcare offerings are creating adjacent revenue possibilities — particularly where mobile or consumer-facing workflows are integrated with clinical pipelines.
- Strategic partnerships that stitch sample-to-insight workflows (including data interpretation layers) are reducing friction for customers and raising the bar for standalone sequencing vendors who cannot offer downstream analytics or integrated reporting.
Strategic recommendations for 2026
Based on the convergence of demand growth, selective consolidation, and buyer sophistication, we recommend that organizations frame 2026 strategies around three pragmatic pillars:
- Prioritize differentiated service packages. Design three to four discrete tiers (e.g., rapid‑turnaround R&D, regulatory/GLP, difficult-template/complex cases, and bundled sample‑to‑report offerings) with distinct pricing and SLAs. Seats at the premium table will go to providers who can prove consistent quality under audit.
- Build flexible capacity strategies. Avoid binary make‑vs‑buy decisions; instead, model blended capacity where core internal capability covers critical clinical or IP‑sensitive workflows while modular outsourcing handles volume spikes and commodity runs.
- Treat M&A and partnerships as capability accelerators, not just market share plays. Target assets that bring complementary regulatory credentials, specialized application expertise, or logistical footprints that reduce time‑to‑service across key accounts.
What we deliberately withhold here — and why you should consult the full report
This preview is intentionally high level. To preserve the utility of the full study for operational and procurement execution, we have not published the granular regional breakdowns, application‑level revenue splits, detailed per‑reaction pricing matrices from benchmark sources, or the raw vendor scorecard data. The full report includes:
- Detailed segment volumes and growth rates by application, end‑user, and region (2020–2032).
- Pricing band analysis and procurement case studies with anonymized contract comparisons and structure recommendations.
- Comprehensive vendor scorecards, including capability heatmaps, SLA evidence, and integration readiness assessments.
- M&A target shortlist with financial proxies, integration checklists, and modeled synergies under multiple transaction scenarios.
These elements are necessary for procurement negotiations, board‑level capital approvals, and corporate development diligence — and are available via the full PW Consulting report.
Next steps for decision-makers
If your 2026 plan requires a defensible sequencing strategy — whether to scale, outsource, partner, or acquire — use this report to accelerate evidence‑based decision making. The research transforms market momentum into operational moves: where to place capital, how to structure supplier relationships, and which capability gaps to close first. For organisations that must act quickly, our advisory team can provide condensed briefings, model customization, and vendor short‑lists tailored to your risk appetite and geography.
PW Consulting’s Sanger Sequencing Service Market study is framed to be immediately actionable while preserving the in‑depth, proprietary data necessary for execution. Contact our advisory desk to unlock the full dataset, vendor scorecards, and tailored scenario models for 2026 planning.
For detailed analysis of this topic, please visit the official page: Sanger Sequencing Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Radiopharmaceutical Market to reach USD 344.8M by 2032 at 7.85% CAGR
By pmarketresearch, 2026-07-09
Radiopharmaceutical Market: Strategic Preview for 2026 Decision-Makers
As the radiopharmaceutical market enters a phase of accelerated commercialization and capacity reshaping, strategic clarity in 2026 will separate winners from laggards. Our PW Consulting market study — grounded on a 2025 base year and projecting through 2032 — shows a resilient market trajectory with a compound annual growth rate of 7.85%. The global market expanded from roughly USD 163.2 Million in 2020 to USD 215.0 Million in 2025, and is projected to continue upward into the next decade, reflecting both diagnostic and therapeutic momentum as well as the commercialization of novel isotopes and theranostic pairings.
Radiopharmaceutical Market
Why this study matters for decisions made in 2026
- Time-sensitive capital allocation: 2026 is a pivotal inflection point for plant investments, isotope sourcing and commercial rollouts — the report translates growth trajectories into investment horizons and breakeven timing.
- Regulatory and reimbursement synchronization: recent policy moves require coordinated regulatory, clinical and pricing strategies; our study maps the operating levers that materially affect launch economics.
- Competitive positioning and M&A: consolidation and targeted capacity plays are likely to accelerate. Our analysis identifies strategic adjacencies and capability gaps that pragmatically inform M&A and partnership prioritization.
- Operational resilience: supply chain and isotope scarcity risks are now front‑and‑center. The report provides playbooks to de‑risk production and distribution for 2026–2028 commercialization windows.
What the report delivers — practical, transaction-ready intelligence
- Forward-looking market model (2026–2032) with scenario variants reflecting reimbursement shifts, isotope supply shocks, and therapeutic approvals.
- Decision frameworks and financial tools: supply-risk-adjusted NPV models, capex prioritization matrices, and an M&A valuation checklist optimized for radiopharmaceutical assets.
- Regulatory and reimbursement roadmaps for major markets — including detailed pathways for outsourcing facilities, repackaging/compounding guidance and Schedule C implementation — tied to tactical submission timelines.
- Manufacturing and logistics playbook: capacity sizing guidance, facility footprint options, and cold-chain requirements calibrated to isotope half-lives and distribution economics.
- Commercialization blueprints: evidence generation sequencing (pivotal studies vs. real-world evidence), KOL engagement templates, and hospital adoption playbooks for diagnostic and therapeutic launches.
- Competitor dossiers and capability heatmaps that profile manufacturing footprint, proprietary isotopes, and strategic intentions across the market’s leading players.
Data-driven insights shaping strategy in 2026
- Growth dynamics: At a near 8% CAGR, the radiopharmaceutical market is large enough to attract diversified capital (both strategic and financial) but remains sufficiently fragmented that targeted investments can yield outsized returns. The growth is driven by expanded PET utilization, therapeutic radiopharmaceutical approvals, and the emergence of higher-value isotopes.
- Policy levers matter: Recent U.S. reimbursement changes are immediate game-changers. For example, CMS finalized an add-on payment for domestically produced Tc‑99m doses and set a per-day cost threshold for separate payment for diagnostic radiopharmaceuticals — moves that materially improve the economic case for local production and narrow the cost disadvantage of specialty supply chains.
- Regulatory clarity is improving — and accelerating commercialization windows. Notable regulatory milestones include Health Canada’s roadmap for radiopharmaceutical drugs and recent FDA guidance on compounding and repackaging by 503B outsourcing facilities; these reduce regulatory uncertainty but require operational alignment.
- Supply-side scale-up is underway: Significant capacity investments — from new research/manufacturing facilities to multi-hundred-million-dollar isotope plants — are reshaping the supply landscape. These investments signal both impending supply relief for some isotopes and increasing competition for specialized feedstocks and skilled personnel.
- Concentration and competitive dynamics: The market has a moderate level of concentration among the largest players. While incumbents maintain advantages in scale and distribution, the share captured by the top firms leaves room for challengers to specialize or vertically integrate and capture adjacent value pools.
Competitive landscape — who matters and why
Our study profiles leading manufacturers, their strategic postures, and capability implications for partners and acquirers. Below are the key strategic archetypes represented among incumbent and growth firms:
Radiopharmaceutical Market
- Established multinational manufacturers: Firms with broad portfolios and global distribution networks are likely to defend premium segments through bundled services (imaging agents + logistics + clinical support). They remain attractive acquisition targets for companies seeking immediate scale.
- Specialist innovators: Companies focused on high-value tracers and neuroimaging or prostate cancer diagnostics take concentrated clinical and reimbursement risk but can capture premium margins if they secure adoption among centers of excellence.
- Manufacturing and isotope builders: New facility investments from private and public players signal an opportunity to secure long-term isotope supply. These players will command strategic value beyond immediate revenue — particularly where they can contract supply to diagnostic and therapeutic manufacturers.
Representative company vignettes (strategic implication):
Radiopharmaceutical Market
- Tri‑Med Americas — a U.S.-based manufacturer with FDA-approved radiopharmaceuticals; strategically positioned for domestic supply-demand shifts.
- Curium — global supplier with diversified isotope capabilities; an anchor player for partnerships and scale manufacturing.
- Life Molecular Imaging and Eli Lilly — leaders in neuroimaging agents with differentiated clinical evidence; candidates for premium pricing and focused clinical partnerships.
- Blue Earth Diagnostics, Lantheus, Telix, Novartis and GE Healthcare — firms with concentrated oncology imaging and theranostic playbooks; attractive partners for integrated diagnostic-therapeutic value chains.
- BWXT — a specialist in radiolabeling materials and feedstock; critical in supply chain resilience strategies for inflammatory and niche imaging markets.
Strategic implications and recommended 2026 actions
- Prioritize supply-security investments now: With reimbursement incentives for domestic production and sizeable greenfield projects in motion, firms should fast-track supply contracts or equity stakes in isotope facilities where the timing aligns with their launch windows.
- Lock in regulatory-compliant manufacturing capacity: Use the new FDA 503B guidance and Health Canada roadmap to accelerate licensing for outsourcing facilities; factor regulatory lead times into the capital schedule.
- Design reimbursement-first launch plans: Structure pricing, evidence generation and coding engagement around known policy levers (including CMS thresholds) to avoid launch erosion and to capture favorable hospital reimbursement.
- Pursue focused M&A and partnerships: Look for targets that close capability gaps (isotope supply, distribution networks, clinical trial experience) rather than broad revenue hunting — this delivers faster path-to-profit in a specialised market.
- Operationalize a supply-risk-adjusted ROI framework: Integrate isotope scarcity scenarios, cold-chain costs, and reimbursement variability into investment appraisals to avoid optimistic upside bias.
- Invest in commercialization enablers: KOL networks, hospital adoption pilots, and rapid RWE programs will be decisive in converting clinical efficacy into durable utilization.
Decision frameworks and next steps
For teams making 2026 resource allocation choices, we recommend three immediate initiatives:
- 90‑day supply and regulatory sprint — map all critical isotopes, identify alternative feedstock/suppliers, and initiate at-risk regulatory submissions aligned to 503B and Schedule C timelines.
- Investment gating process — adopt a 3‑layer gateway for facility investments: (1) Strategic fit and reimbursement alignment, (2) supply-risk and talent availability, (3) commercial traction and contracting pipeline.
- M&A/partner heatmap — shortlist targets that materially reduce time-to-market or materially increase margin through vertical integration; apply our radiopharma-specific due diligence checklist to reveal hidden liabilities tied to isotope logistics and regulatory compliance.
Our report intentionally balances disclosure and commercial prudence. This preview demonstrates the depth of insight available in the full study — including the granular segmentation, regional dynamics, and proprietary financial models that are essential for point decisions in 2026. For executives evaluating capital projects, partnerships or market entry, the full PW Consulting Radiopharmaceutical Market report provides the validated inputs and executable playbooks required to convert market growth into shareholder value.
To obtain the complete dataset, segmentation tables, and our scenario models that power the recommendations above, please visit the PW Consulting research portal or contact our advisory team for a briefing tailored to your strategic priorities.
For detailed analysis of this topic, please visit the official page: Radiopharmaceutical Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Operating Tables Market—3.5% CAGR to USD 196.8M by 2032
By pmarketresearch, 2026-07-09
Operating Tables Market — Strategic Briefing for 2026 Decision-Makers
As hospitals and integrated health systems prioritize operating room modernization, the operating tables market has moved from a commoditized equipment purchase to a strategic asset that shapes clinical capability, workflow efficiency, and capital allocation. PW Consulting’s Operating Tables Market study (base year 2025, historical window 2020–2025, forecast 2026–2032) synthesizes market performance, regulatory inflection points, supplier dynamics, and practical tools you can use to make confident procurement, integration, and financing decisions in 2026.
Operating Tables Market
Top-line market trajectory (what the numbers are signaling)
The market expanded from approximately USD 130.0 Million in 2020 to USD 155.0 Million in 2025, reflecting steady, healthcare-driven demand for upgraded surgical infrastructure. Our forecast assumes a 3.5% compound annual growth rate across the 2026–2032 horizon, with a projected market size approaching USD 197.0 Million by 2032 under the base scenario. These macro trends reflect a convergence of capital refresh cycles, hybrid OR investments, and selective replacement of legacy tables for robotics- and imaging-compatible platforms.
Operating Tables Market
Market concentration metrics show moderate supplier concentration (CR3 ~38%, CR5 ~52%), which signals that a handful of global vendors exert meaningful influence on pricing, standards, and aftermarket depth — but there remains sufficient competitive space for regional specialists, value players, and niche innovators to capture share via focused clinical differentiation or service models.
Operating Tables Market
What the PW Consulting report delivers — practical, executable content
- Actionable 7‑year forecasts (2026–2032) with scenario runs calibrated to capital availability, reimbursement adjustments, and regulatory change.
- Procurement playbook: RFP templates, vendor scorecards, total cost of ownership (TCO) models, and CapEx prioritization matrices for hospital networks.
- Technical and clinical decision frameworks: modularity vs. specialization, imaging/radiolucency requirements, robotics compatibility, and OR footprint planning.
- Regulatory and reimbursement impact analysis: compliance gap checklists, documentation templates, and billing scenario modeling reflecting 2026 code updates and quality management expectations.
- Competitive intelligence: vendor positioning maps, strengths/weaknesses, likely moves, and supplier risk heatmaps (service coverage, spare-parts lead times, and aftermarket margins).
- Operational tools: clinical training needs assessment, service contract negotiation playbook, and timelines for phased rollouts to minimize surgical downtime.
- Executive summary and board-ready briefing decks tailored for CFOs, CMOs, and clinical engineering leaders.
Note: the report contains granular segmentation by region, product type, and clinical application to support site-level decisions. To preserve strategic value in this briefing we intentionally omit the granular splits here — full segment-level tables and model-level pricing are available in the full report.
Key market dynamics that will shape decisions in 2026
- Regulatory tightening: The implementation of an updated Quality Management System regulation (effective 2 Feb 2026) raises the bar for documentation and process validation for powered tables. Buyers must require evidence of compliant design control and validation artifacts as part of procurement.
- Reimbursement adjustments: HCPCS code updates (effective 1 Jan 2026) change the economics of certain OR billings. Institutions should refresh their procedure-level reimbursement models and align capital requests to net revenue impacts.
- Hybrid OR and imaging integration: Carbon-fiber tabletops and radiolucent designs are no longer niche: they are integral for hybrid suites. Raw-material availability and supplier capability to deliver carbon-fiber components are a source of risk and differentiation.
- Labor and skills: Advanced motorized and robotic-compatible tables increase the need for clinician and biomed training. Expect incremental O&M and training budgets post-purchase, and ensure vendor-led competency programs are contractually defined.
- CapEx prioritization: Hospitals increasingly bundle operating table upgrades into broader OR modernization capital programs. Procurement teams must balance one-off table acquisitions against integrated systems that deliver ROI via throughput gains or procedure mix shifts.
Competitive landscape — strategic implications for procurement
The current vendor field blends multinational incumbents with specialized OEMs. Procurement teams should evaluate not just headline specifications but the total delivery ecosystem: service reach, integration interfaces, future-proofing (modularity, upgradeability), and aftermarket economics.
- STERIS plc (Ireland) — Strengths: broad portfolio of general and radiolucent fluoroscopic tables, orthopedic extensions, and all-electric operation. Strategic implication: strong for hospitals prioritizing imaging workflows and comprehensive service packages; expect premium pricing for integrated X‑ray-ready platforms.
- Hill-Rom Holdings, Inc. (United States) — Strengths: TruSystem series with ISO-center motion and mobile models designed for precision positioning and robotic interplay. Strategic implication: a front-runner for sites planning robotic integrations and centers of excellence focused on minimally invasive surgery.
- Getinge AB (Sweden) — Strengths: Maquet Magnus platform emphasizing modularity and carbon-fiber tabletops for hybrid ORs. Strategic implication: compelling where hybrid imaging and interdisciplinary workflows are a strategic priority; trade-offs often involve higher integration engineering effort.
- SCHMITZ medical GmbH (Germany) — Strengths: electrically driven, robust universal tables with emphasis on precision tilt and German engineering. Strategic implication: attractive to hospitals valuing durability, ergonomics, and deterministic performance for high-utilization theatres.
- Mindray DS USA, Inc. (United States) — Strengths: ergonomic, versatile models positioned for general and bariatric procedures with competitive pricing. Strategic implication: value-oriented choice for cost-conscious systems seeking modern features without the high premium of flagship platforms.
- Mizuho OSI (United States) — Strengths: specialized systems for orthopedic and spine indications with modularity for complex positioning. Strategic implication: best-in-class for specialty surgical centers and academic hospitals with a high volume of spine/orthopedics.
Given the CR3/CR5 concentration dynamics, expect continued consolidation pressure in adjacent segments (imaging, OR integration software, and robotics). Buyers should build vendor scorecards that weight not only product specs but also pension on geographic service coverage, spare-parts exposure, and regulatory readiness.
Practical recommendations for 2026 procurement and executive leaders
- Align capital requests with an OR modernization roadmap that accounts for hybrid imaging and robotics; structure approvals to enable modular upgrades rather than full replacement where possible.
- Embed regulatory compliance requirements into vendor contracts (design history files, process validation evidence, and post-market surveillance obligations) to meet the 2026 Quality Management expectations.
- Update reimbursement models post-HCPCS changes and stress-test budgets under alternative utilization scenarios to estimate payback horizons accurately.
- Negotiate service-level agreements with explicit KPIs for uptime, response times, and parts lead-time guarantees; include training packages and credentialing support for clinical staff.
- Mitigate supply risk for carbon-fiber and other specialty components by requiring dual-sourcing options or confirmed lead-time commitments in purchase orders.
- Use pilot programs to validate integration with imaging and robotic systems before large-scale rollouts; capture real-world data on procedure time savings and positioning accuracy to support broader adoption.
- Standardize interfaces and consumables across site networks where possible to lower inventory and maintenance complexity and to improve negotiating leverage.
How PW Consulting supports your 2026 roadmap
PW Consulting offers a suite of services designed to convert the study’s insights into executable programs: tailored procurement workshops, vendor RFI/RFP management, TCO and CapEx optimization, regulatory readiness audits, and clinical-technical integration planning. For clients executing multi-site rollouts, we provide project governance templates, staging schedules to minimize OR disruption, and post-implementation performance baselines to measure success.
This briefing has showcased the strategic contours of the operating tables market while reserving granular segmentation data, model-level pricing, and the full vendor scorecards for the complete report. If your 2026 decisions require validated segment splits, model comparators, or a supplier-selection deep dive, the full PW Consulting Operating Tables Market report provides those assets along with downloadable tools and executive-ready decks.
Accessing the full report will equip your procurement, clinical engineering, and executive teams with the detailed numeric intelligence and practical templates needed to act decisively in 2026. Contact PW Consulting to request the full dossier, scorecards, and the operational toolset that accompanies this strategic analysis.
For detailed analysis of this topic, please visit the official page: Operating Tables Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Rugged Handheld Device Market: Strategic Imperatives for 2026
As organizations restart large-scale capex and digitalization programs in 2026, rugged handheld devices occupy a critical hinge point between operational reliability and next‑generation edge computing. PW Consulting’s new market study — grounded in a 2020–2025 historical series and a 2026–2032 forecast — positions decision‑makers to convert field-level resilience into measurable enterprise value. At the aggregate level, the market reached approximately USD 1,950 million in 2025 and is forecast to continue expanding at a compound annual growth rate (CAGR) of 7.2% through the 2026–2032 horizon, reaching just over USD 3,150 million by 2032. This research is intentionally tactical: it shows where value will be created and captured without giving away the granular slices reserved for the full report.
Rugged Handheld Device Market
Why this research matters for enterprise leaders in 2026
-
Timing and scale of refresh cycles — Procurement and asset‑management teams must align device refresh waves with evolving wireless standards (5G, Wi‑Fi 6/6E) and enterprise software roadmaps. Our analysis clarifies the tradeoffs between shorter refresh cycles for performance gains and longer cycles for depreciation and sustainability goals.
Rugged Handheld Device Market -
Risk‑adjusted supplier selection — Supply‑chain managers face concentrated manufacturing and components risk. The study translates market concentration and supplier capabilities into procurement levers that reduce single‑source exposure while preserving TCO predictability.
Rugged Handheld Device Market -
Operational resilience and compliance — Public safety, utilities, oil & gas, and defense stakeholders require devices validated to MIL‑STD‑810H and appropriate IP and hazardous‑location certifications. We map certification requirements to procurement checklists to avoid field delays and costly retrofits.
-
Platform strategy for edge intelligence — Technology leaders must choose between rugged Android, Arm‑based Windows, and specialized IoT stacks. The report frames that choice in terms of application portability, security posture, and long‑term manageability.
Market trajectory and the forces shaping 2026 decisions
The market’s historical momentum — growing from around USD 1,400 million in 2020 to USD 1,950 million in 2025 — is now being reinforced by two structural shifts. First, the convergence of connectivity (5G and Wi‑Fi 6), on‑device AI accelerators, and higher fidelity sensing (scanners, cameras, environmental sensors) turns rugged handhelds into distributed compute nodes rather than simple data capture terminals. Second, enterprise buyers are demanding modularity and serviceability to reduce lifecycle costs and adapt to rapid workflows changes.
Regulation and certification are non‑negotiable constraining factors. Devices intended for military or heavy‑industry use increasingly require pre‑shipment verification under MIL‑STD‑810H and ingress protection at IP65 or higher; many end markets additionally require C1D2 or ATEX/IECEx approvals for hazardous atmospheres. These technical thresholds not only determine vendor eligibility but create margins of competitive differentiation for manufacturers who can operationalize certification at scale.
On the supply side, semiconductor availability, bespoke component sourcing (ruggedized displays, battery cartridges), and contract manufacturing capacity are the primary near‑term bottlenecks. On the demand side, migration to contactless workflows, warehouse automation, and field workforce enablement will sustain revenue expansion through 2032. Our forecast – a steady CAGR of 7.2% — incorporates scenarios for component constraints, accelerated digitalization, and defense procurement cycles.
Competitive landscape: who moves the dial
The market exhibits moderate concentration — the top three players capture a meaningful share of revenue while the top five further amplify market control. This structure favors established incumbents that combine product breadth, certification capabilities, and global service footprints, but it also leaves room for specialist players to win in verticalized niches.
-
Zebra Technologies — Offers ultra‑rugged Android/Windows handhelds and tablets (TC‑series, ET‑series) engineered for warehouse, retail, logistics, and field workflows with robust MIL‑STD and IP ratings. Zebra’s value proposition centers on enterprise integration and lifecycle services.
-
Honeywell — Deploys the CT and RT10 series with Wi‑Fi 6 and integrated data capture. Honeywell competes on interoperability with warehouse management systems and on-field device management at scale.
-
Getac Technology — Distinguishes itself with fully rugged tablets and handhelds (B300, F‑series) designed for extreme environments and hazardous locations. Recent product moves emphasize AI‑ready hardware and Arm Windows devices to address defense and utilities.
-
Panasonic — The Toughbook lineage focuses on modular 5G/AI designs for construction, logistics, and public safety where ruggedness and compute headroom are critical.
-
Datalogic — Specializes in enterprise data capture with rugged PDAs and scanners built for retail and manufacturing environments, coupling protective materials with high‑accuracy scanning engines.
-
Winmate — Competes on compact, battery‑optimized Android handhelds with high ingress protection and price value for warehouse and field service operators.
Notable recent moves that shape vendor positioning include Getac’s 2025 announcements of AI‑ready fully rugged Copilot+ PCs and new Arm‑based Windows tablets with hazardous‑location certifications, and Winmate’s launches of compact, IP68‑rated Android handhelds in late 2025. These developments accelerate competition around edge compute, certification breadth, and device ergonomics.
What the PW Consulting report delivers — practical content for 2026 action
-
Macro to micro demand mapping: historical baseline (2020–2025), validated 2026 market snapshot, and scenario‑based forecasts to 2032 (CAGR 7.2%).
-
Vertical use‑case playbooks: deployment architectures, app stacks, procurement templates, and KPI scorecards for manufacturing, logistics, retail, defense, and field services.
-
Certification and compliance matrix: MIL‑STD‑810H, IP ratings, C1D2/ATEX/IECEx requirements, and pre‑shipment testing implications for sourcing and lead times.
-
Vendor benchmarking and go‑to‑market heatmap: independent assessment of product portfolios, service ecosystems, channel strength, and partnership fit.
-
Supply‑chain stress tests and mitigation playbook: component risk scoring, alternative sourcing strategies, and nearshoring vs. cost arbitrage decision frameworks.
-
TCO and financing models: capex vs. opex assessments, buy vs. lease calculus, and total lifecycle cost drivers including service, repairs, and software maintenance.
-
M&A and investment opportunities: pockets of consolidation, differentiating capabilities to acquire, and integration risk checklists.
How to turn insight into 2026 decisions: three executive plays
-
Right‑size your refresh wave: Use the report’s TCO models to design staggered refreshes that align high‑value workloads (real‑time scanning, edge AI inference) with latest hardware while deferring lower‑risk assets to extend useful life. This reduces near‑term capex and smooths supply exposure.
-
Certify once, deploy many: Prioritize vendors that commit to in‑house MIL‑STD and hazardous‑location testing and offer pre‑qualified device families. Standardizing on a certified platform shortens deployment cycles and cuts field failures.
-
Design for edge evolution: Specify modular expansion (swappable radios, compute modules) and an OS strategy that preserves application portability. The report’s vendor scorecards identify suppliers with the best roadmap alignment for AI and 5G use cases.
Strategic risks and early warning indicators
Key risks to monitor through 2026 include sudden semiconductor allocation shifts, changes in defense procurement budgets, and steep component price inflation. Early warning indicators we track in the report include contract‑manufacturer backlog rates, lead‑time deltas for ruggedized displays/batteries, escalation in certification lead times, and changes in the CR3/CR5 concentration metrics. Monitoring these indicators allows procurement and strategy teams to trigger contingency supplier engagements or accelerate stockpile strategies with minimal disruption.
Where to find the hidden details
This article highlights the strategic takeaways we expect to shape enterprise decisions in 2026. The full PW Consulting Rugged Handheld Device Market report contains the granular segmentation tables, regional and application splits, vendor scorecards with quantitative ratings, and downloadable financial models that support scenario planning. That detailed intelligence is gated intentionally: it is used by procurement teams, CIOs, product managers, and M&A advisors to execute competitive plays with confidence.
Contact PW Consulting or download the full report to access the data tables, supplier matrices, and step‑by‑step implementation checklists that convert the market’s 7.2% growth trajectory into operational advantage.
For detailed analysis of this topic, please visit the official page: Rugged Handheld Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Prosthetic Liners Market to Reach USD 4,475.11M by 2032 at 6.8% CAGR
By pmarketresearch, 2026-07-09
Prosthetic Liners Market — Strategic Preview for 2026 Decision-Makers
Executive summary
As PW Consulting’s senior strategy team, we present a focused preview of our full Prosthetic Liners Market study (base year 2025) to guide executive action in 2026. The market has moved from a modest specialty niche in 2020 to a multi‑hundred‑million USD category by 2025, and our forecasts indicate sustained expansion through 2032 at a compound annual growth rate (CAGR) of 6.8%. The trendline—from early‑stage product innovation to broader clinical and reimbursement acceptance—creates a strategic window for product innovation, reimbursement positioning, and selective vertical integration.
Prosthetic Liners Market
Why this matters for 2026 planning
-
Acceleration and scale: The prosthetic liners market has exhibited accelerating topline growth in the 2020–2025 historical window, and is forecast to expand materially during 2026–2032. For companies evaluating capacity investments, the trajectory supports staged scaling rather than one‑time heavy capex—provided R&D and reimbursement efforts are synchronized with manufacturing rollouts.
Prosthetic Liners Market -
Regulatory and reimbursement inflection points are unlocking demand: Regulatory refinements and reimbursement policy updates over the past 24 months have lowered technical and commercial barriers. These changes reduce time‑to‑market for incremental product improvements and make value propositions tied to clinical outcomes and cost offsets more compelling to payors.
Prosthetic Liners Market -
Technology is changing the value equation: Advances in materials chemistry and embedded sensors are shifting differentiation away from commoditized fit toward data‑enabled comfort, moisture management, and objective outcome measurement—areas that translate directly into higher willingness‑to‑pay and improved reimbursement positioning.
Data snapshot (what you can act on)
-
Market base: The report anchors on 2025 as the base year and analyzes historical dynamics from 2020–2025 and scenarios for 2026–2032.
-
Growth expectation: At a 6.8% CAGR, the category’s scale and supplier economics materially change between 2026 and 2032; this should influence multi‑year capital allocation, R&D roadmaps, and partnership timelines.
-
Key drivers: reimbursement policy shifts; FDA/standards clarification that reduces redundant testing; supplier innovation in silicone and elastomer chemistries; and the emergence of embedded sensing and analytics.
Industry dynamics and technology inflection points
-
Reimbursement dynamics: Recent policy updates broaden coverage criteria for certain prosthetic components, which increases predictability for manufacturers and clinicians deploying higher‑performance liners. For companies that establish billing pathways and clinical value documentation in 2026, early penetration advantages can translate into durable revenue streams.
-
Regulatory simplification: Refinements in device testing expectations for intact‑skin devices have reduced redundant testing costs. That reallocates cash toward product features with commercial salience (moisture control, tear resistance, sensor integration), shortening commercial lead times for differentiated launches.
-
Materials and supply chain: Medical‑grade silicones, urethanes, and thermoplastic elastomers continue to improve on tear resistance and water‑vapor transmission. Suppliers are bringing chemistries that meet higher biocompatibility standards, reducing barrier risk for new formulations and enabling product families that prioritize patient comfort and longevity.
-
Digital and sensor augmentation: The first wave of liners integrating micro‑sensors demonstrates the commercial viability of outcome measurement. These systems enable objective evidence of fit and function—an increasingly important input for payors and large prosthetic service providers.
Competitive landscape — what leaders are doing
The market features a mix of global prosthetics leaders, specialized liner manufacturers, and emerging tech‑enabled entrants. Competitive moves in 2024–2025 illustrate two parallel playbooks: (1) incumbents layering functional innovation onto existing distribution and clinic networks; and (2) specialist producers focusing on materials science and user comfort.
-
Product innovation leaders: Established prosthetics firms have introduced next‑generation liners with embedded sensing and materially improved moisture management. These launches highlight a shift from purely mechanical fit toward integrated sensor data as a commercial differentiator.
-
Reimbursement playbook: Some firms secured coding and billing approvals to simplify reimbursement for clinicians and suppliers, lowering the friction for adoption in clinical practice. Firms that prioritize PDAC/HCPCS engagement and clinical evidence generation will better capture the business mix of institutional and payor‑driven demand.
-
Manufacturing and quality positioning: Several suppliers emphasize ISO 13485 and GMP alignment, targeting both regulatory compliance and strategic customers who require consistent, scalable supply. Compliance is table stakes for large institutional contracts.
Report — practical content you can deploy in 2026
The full PW Consulting study goes beyond high‑level forecasts to provide a playbook you can operationalize. Highlights include:
-
Actionable market modeling: Scenario models that link product development timelines, reimbursement pathways, and manufacturing ramp profiles to revenue outcomes across 2026–2032.
-
Go‑to‑market playbooks: Evidence‑based strategies for clinician engagement, coding and reimbursement sequencing, and distributor negotiations—prioritized by ROI and execution complexity.
-
R&D prioritization matrix: Comparative value mapping of material innovation, sensor integration, and digital services—ranked by impact on adoption, margin expansion, and IP defensibility.
-
M&A and partnership scout: A curated list of targets and cooperation models (JV, licensing, white‑label) tailored to buyers seeking speed‑to‑market or specialty capabilities.
-
Operational playbook for manufacturers: Quality, scale-up, and cost reduction templates aimed at compressing time‑to‑profitability while maintaining regulatory compliance.
Strategic imperatives for 2026 (prioritized)
-
Secure reimbursement levers early. Invest in the clinical evidence and coding engagement required to position new liners within established payor pathways. Early reimbursement wins reduce commercial friction and justify premium pricing for measurable outcomes.
-
Differentiate through materially relevant features. Prioritize moisture management, tear resistance, and sensor‑based outcome tracking over incremental comfort claims. These attributes map directly to clinician preference and payor value assessments.
-
Opt for staged manufacturing scale. Use contract manufacturing to de‑risk initial launches, reserving in‑house scale investments for validated designs and confirmed reimbursement positions.
-
Form alliances across the value chain. Partner with clinical networks, materials suppliers, and analytics vendors to accelerate adoption and create bundled value propositions that are harder for competitors to replicate.
-
Embed measurement into product roadmaps. Design products with data capture as a core function—objective data accelerates payer acceptance and feeds iterative product improvements.
What we withhold here — why you need the full study
This preview intentionally outlines strategic direction, market movement, and practical playbooks while withholding the granular regional, type and application split tables, detailed competitor share breakdowns, and transaction‑level valuation benchmarks. Those detailed segmentations and company metrics are central to precise go‑to‑market decisions and M&A execution and are included only in the full PW Consulting report.
How PW Consulting can accelerate your 2026 agenda
-
Custom scenario modeling tied to your product pipeline and distribution footprint.
-
Assistance with reimbursement dossier development and payer pilots, leveraging our evidence synthesis templates.
-
Targeted M&A diligence and integration playbooks focused on prosthetic liners and adjacent prosthetics components.
For executives and investors preparing 2026 commitments, the choices made this year—on R&D focus, reimbursement engagement, and partner selection—will determine whether you capture the high‑growth segments of the prosthetic liners market or remain a low‑margin commodity supplier. Access the full PW Consulting Prosthetic Liners Market report for the complete data set, proprietary segment models, and tactical execution templates required to convert the 6.8% CAGR opportunity into a defensible market position.
For detailed analysis of this topic, please visit the official page: Prosthetic Liners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aquaculture Cages Market to Reach USD 464M by 2032 (6.8% CAGR)
By pmarketresearch, 2026-07-09
Aquaculture Cages Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise strategic preview of the Aquaculture Cages Market intended to orient senior executives, investors, and operations leaders preparing decisions in 2026. This preview showcases the analytical depth of our forthcoming market study while deliberately withholding detailed subsegment tables and proprietary forecasts that sit behind our paywall. Think of this as the trailer: enough insight to plan your next moves with confidence, but you’ll need the full report to execute with precision.
Aquaculture Cages Market
Market Snapshot — Macro Readings You Can Use Today
Built on a 2025 base year, our market model shows the aquaculture cages market expanding at a steady compound annual growth rate (CAGR) of 6.8% through the 2026–2032 forecast horizon. The market has shown consistent recovery and expansion since 2020, reflecting rising protein demand, investments in farmed seafood, and technology adoption that improves yield and compliance. In revenue terms (USD, Million), the market is transitioning from the high‑to‑low hundreds in the mid‑2020s toward a substantially larger base by the end of the decade. Market concentration metrics confirm a fragmented supplier landscape: the top three firms account for roughly a quarter of market value (CR3 ≈ 24.5%) and the top five remain below 30% (CR5 ≈ 28.5%). That fragmentation creates both risk and opportunity for incumbents and new entrants alike.
Aquaculture Cages Market
Why 2026 Is a Strategic Inflection Point
- Regulatory stringency meets premium market access. Tightening rules on water quality, waste, and disease control are accelerating the adoption of advanced cage designs and real‑time monitoring. Simultaneously, certification regimes such as ASC and BAP are increasingly gatekeeping premium procurement channels. Companies that can demonstrate compliance and traceability will win margin‑rich contracts and offtake agreements.
- Material economics are reshaping capex decisions. HDPE has emerged as the dominant material for marine cages because of its durability and ability to withstand exposed conditions. While initial material costs are higher relative to older alternatives, service life improvements reduce total cost of ownership — a classic capex vs. lifecycle cost tradeoff executives must model explicitly in 2026 procurement cycles.
- Technology convergence demands system-level thinking. Floating closed cages, semi‑closed designs, submersible nets, and integrated RAS (recirculating aquaculture systems) are no longer niche. Customers now buy integrated production solutions: containment hardware, sensors, automation, and service contracts. Suppliers who compete only on hardware risk being marginalized unless they broaden into system services or partner strategically.
Structural Drivers and Market Dynamics
Several interlocking dynamics underpin the forecast trajectory:
Aquaculture Cages Market
- Sustainability and certification: Access to premium buyers increasingly requires ASC/BAP compliance. That is pushing producers to upgrade pen design, waste‑management, and monitoring capabilities, creating demand for advanced cage systems and compliance services.
- Raw material and lifecycle economics: HDPE and high‑performance fibers (e.g., Dyneema®, UHMWPE) are preferred in many marine applications for longevity and resistance to biofouling and mechanical stress. Buyers are trading higher upfront cost for lower replacement frequency and reduced operational disruption.
- Regulatory constraint and ecological concerns: In select jurisdictions, stricter rules around stocking densities, prohibited areas, and environmental impact are predicted to restrain growth in certain nearshore models. This sets up regionalized demand for offshore, closed, or land‑based solutions.
- Fragmented supply base: A relatively low CR5 means many local and specialist suppliers coexist with global systems integrators. This fragmentation encourages acquisition strategies by larger firms and presents opportunities for niche technology providers to capture premium segments.
Competitive Landscape — Who Matters and Why
The competitive field combines global integrators, specialist fabricators, and regional manufacturers. Below are the strategic profiles of core players you’ll observe in our market map and why they matter for 2026 strategy:
- AKVA Group (Norway) — A global leader in plastic pens and complete cage systems; strong in HDPE solutions and system integration. Their strength is breadth: combining hardware with control systems and service offerings makes them a natural partner for large producers targeting certified markets. ( https://www.akvagroup.com/)
- Badinotti Group (Italy) — Specialist in net cages and submersible systems, with recent M&A to broaden containment capabilities. Their acquisition activity signals consolidation among high‑end containment specialists. ( https://www.badinotti.com/)
- Selstad AS (Norway) — Supplier of multiple cage geometries and high‑strength materials. Their product breadth across nylon, HDPE, Dyneema®, and UHMWPE positions them to serve bespoke projects where design and material selection are critical. ( https://selstad.no/)
- AquaMaof (Israel) — Focus on floating closed systems and RAS integration, representing the growing intersection between offshore and land‑based technologies. Their offerings illustrate the premium placed on biosecurity and containment. ( https://www.aquamaof.com/)
- Qingdao Qihang Fishing Cage Co., Ltd (China) — Volume manufacturer of offshore HDPE cages; key supplier for large scale projects where unit economics matter. ( https://qhfishing.com/)
- Hunan Xinhai Co., Ltd (China) and Zhejiang Honghai (China) — Regional manufacturers catering to large domestic and export demand, often competing on price and lead time.
- Garware Technical Fibres Ltd (India) — Material supplier of high‑performance synthetic netting, an essential upstream player for nets and containment systems. ( https://www.garwarepolyester.com/)
Recent market activity underscores strategic themes you should consider: product supply agreements that create bundled offerings (November 2024), and acquisitions that expand technical capability and market reach (September 2024). These moves are consistent with a market in which system capability and geographic reach increasingly determine contract awards.
Operational and Commercial Implications for 2026 Decision Cycles
- Procurement: move from unit price to lifecycle cost models. Expect procurement teams and lenders to demand lifecycle projections that explicitly incorporate HDPE longevity, replacement cycles, and operational downtime. Financial models that fail to include these will misprice projects.
- Product strategy: prioritize modularity and serviceability. Designs that enable on‑site maintenance, sensor upgrades, and phased migration to closed or semi‑closed systems will win larger long‑term contracts.
- Partnerships and M&A: tilt toward capability fills. For hardware specialists, a tilt toward partnerships with automation, sensing, and biosecurity providers is a rational route to sustaining value capture. Acquisitions that fill technological gaps in monitoring, nets, or mooring systems will be accretive.
- Supply chain resilience: Locking material supply (HDPE resin, high‑strength fibers) and diversifying fabrication capacity across geographies will be necessary to manage lead times and price volatility in 2026 procurement windows.
- Regulatory strategy: Firms should invest in regulatory intelligence and certification roadmaps to accelerate market access for premium buyers. Early investment in ASC/BAP compliance provides pricing leverage and de‑risking for financiers.
What PW Consulting’s Full Report Delivers
Our complete Aquaculture Cages Market report (base year 2025) is structured to convert insight into action for 2026 decisions. Highlights include:
- Proprietary market sizing and seven‑year forecasts at product, application, and regional levels (2026–2032).
- Supply‑side mapping and competitive benchmarking with capability and financial proxies for major global and regional players.
- Scenario models for regulatory tightening, raw material price shocks, and accelerated certification adoption — with actionable sensitivities for project finance teams.
- Vendor selection frameworks and TO‑BE purchase decision matrices that align technical specifications with lifecycle economics.
- Commercial playbooks for OEMs, integrators, and producers, including partnership archetypes, M&A screening checklists, and go‑to‑market strategies tailored to different buyer segments.
Note: This preview intentionally omits the granular segment tables, region/application revenue splits, and proprietary pricing schedules that underwrite our revenue forecasts. These items are included only in the licensed report to preserve the competitive advantage they confer. If your planning horizon requires executable numbers (e.g., tender bids, capex approval, or acquisition underwriting), access to those tables is essential.
Actionable Next Steps for Executives in 2026
- Commission an internal lifecycle cost analysis now that HDPE and high‑performance fibers dominate product selection. Use scenario runs to test vendor proposals against 7–10 year service life assumptions.
- Prioritize partnerships with system integrators or sensor providers to offer bundled, certified solutions to premium buyers.
- Evaluate M&A targets among specialist containment designers and net‑material manufacturers to close capability gaps quickly.
- Institute a supply‑risk audit covering resin and fiber suppliers, and redesign procurement contracts to include price adjustment clauses and capacity guarantees.
- Invest in certification roadmaps for target production sites to access ASC/BAP channels and secure higher offtake prices.
PW Consulting’s full Aquaculture Cages Market report equips you with the precise tables, scenario models, and vendor scorecards required to operationalize the strategies above. For teams preparing capital allocations, OEM sourcing, or strategic M&A in 2026, that level of granularity is non‑negotiable.
To request the full report, licensing options, or a tailored executive briefing that applies these insights to your portfolio, contact PW Consulting’s Market Intelligence team. Our next cohort of advisory engagements begins in Q3 2026 — seats for bespoke modeling are limited.
For detailed analysis of this topic, please visit the official page: Aquaculture Cages Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com