

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Prosthetic Liners Market to Reach USD 4,475.11M by 2032 at 6.8% CAGR

Prosthetic Liners Market — Strategic Preview for 2026 Decision-Makers
Executive summary
As PW Consulting’s senior strategy team, we present a focused preview of our full Prosthetic Liners Market study (base year 2025) to guide executive action in 2026. The market has moved from a modest specialty niche in 2020 to a multi‑hundred‑million USD category by 2025, and our forecasts indicate sustained expansion through 2032 at a compound annual growth rate (CAGR) of 6.8%. The trendline—from early‑stage product innovation to broader clinical and reimbursement acceptance—creates a strategic window for product innovation, reimbursement positioning, and selective vertical integration.
Prosthetic Liners Market
Why this matters for 2026 planning
-
Acceleration and scale: The prosthetic liners market has exhibited accelerating topline growth in the 2020–2025 historical window, and is forecast to expand materially during 2026–2032. For companies evaluating capacity investments, the trajectory supports staged scaling rather than one‑time heavy capex—provided R&D and reimbursement efforts are synchronized with manufacturing rollouts.
Prosthetic Liners Market -
Regulatory and reimbursement inflection points are unlocking demand: Regulatory refinements and reimbursement policy updates over the past 24 months have lowered technical and commercial barriers. These changes reduce time‑to‑market for incremental product improvements and make value propositions tied to clinical outcomes and cost offsets more compelling to payors.
Prosthetic Liners Market -
Technology is changing the value equation: Advances in materials chemistry and embedded sensors are shifting differentiation away from commoditized fit toward data‑enabled comfort, moisture management, and objective outcome measurement—areas that translate directly into higher willingness‑to‑pay and improved reimbursement positioning.
Data snapshot (what you can act on)
-
Market base: The report anchors on 2025 as the base year and analyzes historical dynamics from 2020–2025 and scenarios for 2026–2032.
-
Growth expectation: At a 6.8% CAGR, the category’s scale and supplier economics materially change between 2026 and 2032; this should influence multi‑year capital allocation, R&D roadmaps, and partnership timelines.
-
Key drivers: reimbursement policy shifts; FDA/standards clarification that reduces redundant testing; supplier innovation in silicone and elastomer chemistries; and the emergence of embedded sensing and analytics.
Industry dynamics and technology inflection points
-
Reimbursement dynamics: Recent policy updates broaden coverage criteria for certain prosthetic components, which increases predictability for manufacturers and clinicians deploying higher‑performance liners. For companies that establish billing pathways and clinical value documentation in 2026, early penetration advantages can translate into durable revenue streams.
-
Regulatory simplification: Refinements in device testing expectations for intact‑skin devices have reduced redundant testing costs. That reallocates cash toward product features with commercial salience (moisture control, tear resistance, sensor integration), shortening commercial lead times for differentiated launches.
-
Materials and supply chain: Medical‑grade silicones, urethanes, and thermoplastic elastomers continue to improve on tear resistance and water‑vapor transmission. Suppliers are bringing chemistries that meet higher biocompatibility standards, reducing barrier risk for new formulations and enabling product families that prioritize patient comfort and longevity.
-
Digital and sensor augmentation: The first wave of liners integrating micro‑sensors demonstrates the commercial viability of outcome measurement. These systems enable objective evidence of fit and function—an increasingly important input for payors and large prosthetic service providers.
Competitive landscape — what leaders are doing
The market features a mix of global prosthetics leaders, specialized liner manufacturers, and emerging tech‑enabled entrants. Competitive moves in 2024–2025 illustrate two parallel playbooks: (1) incumbents layering functional innovation onto existing distribution and clinic networks; and (2) specialist producers focusing on materials science and user comfort.
-
Product innovation leaders: Established prosthetics firms have introduced next‑generation liners with embedded sensing and materially improved moisture management. These launches highlight a shift from purely mechanical fit toward integrated sensor data as a commercial differentiator.
-
Reimbursement playbook: Some firms secured coding and billing approvals to simplify reimbursement for clinicians and suppliers, lowering the friction for adoption in clinical practice. Firms that prioritize PDAC/HCPCS engagement and clinical evidence generation will better capture the business mix of institutional and payor‑driven demand.
-
Manufacturing and quality positioning: Several suppliers emphasize ISO 13485 and GMP alignment, targeting both regulatory compliance and strategic customers who require consistent, scalable supply. Compliance is table stakes for large institutional contracts.
Report — practical content you can deploy in 2026
The full PW Consulting study goes beyond high‑level forecasts to provide a playbook you can operationalize. Highlights include:
-
Actionable market modeling: Scenario models that link product development timelines, reimbursement pathways, and manufacturing ramp profiles to revenue outcomes across 2026–2032.
-
Go‑to‑market playbooks: Evidence‑based strategies for clinician engagement, coding and reimbursement sequencing, and distributor negotiations—prioritized by ROI and execution complexity.
-
R&D prioritization matrix: Comparative value mapping of material innovation, sensor integration, and digital services—ranked by impact on adoption, margin expansion, and IP defensibility.
-
M&A and partnership scout: A curated list of targets and cooperation models (JV, licensing, white‑label) tailored to buyers seeking speed‑to‑market or specialty capabilities.
-
Operational playbook for manufacturers: Quality, scale-up, and cost reduction templates aimed at compressing time‑to‑profitability while maintaining regulatory compliance.
Strategic imperatives for 2026 (prioritized)
-
Secure reimbursement levers early. Invest in the clinical evidence and coding engagement required to position new liners within established payor pathways. Early reimbursement wins reduce commercial friction and justify premium pricing for measurable outcomes.
-
Differentiate through materially relevant features. Prioritize moisture management, tear resistance, and sensor‑based outcome tracking over incremental comfort claims. These attributes map directly to clinician preference and payor value assessments.
-
Opt for staged manufacturing scale. Use contract manufacturing to de‑risk initial launches, reserving in‑house scale investments for validated designs and confirmed reimbursement positions.
-
Form alliances across the value chain. Partner with clinical networks, materials suppliers, and analytics vendors to accelerate adoption and create bundled value propositions that are harder for competitors to replicate.
-
Embed measurement into product roadmaps. Design products with data capture as a core function—objective data accelerates payer acceptance and feeds iterative product improvements.
What we withhold here — why you need the full study
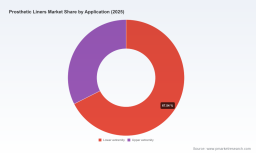
This preview intentionally outlines strategic direction, market movement, and practical playbooks while withholding the granular regional, type and application split tables, detailed competitor share breakdowns, and transaction‑level valuation benchmarks. Those detailed segmentations and company metrics are central to precise go‑to‑market decisions and M&A execution and are included only in the full PW Consulting report.
How PW Consulting can accelerate your 2026 agenda
-
Custom scenario modeling tied to your product pipeline and distribution footprint.
-
Assistance with reimbursement dossier development and payer pilots, leveraging our evidence synthesis templates.
-
Targeted M&A diligence and integration playbooks focused on prosthetic liners and adjacent prosthetics components.
For executives and investors preparing 2026 commitments, the choices made this year—on R&D focus, reimbursement engagement, and partner selection—will determine whether you capture the high‑growth segments of the prosthetic liners market or remain a low‑margin commodity supplier. Access the full PW Consulting Prosthetic Liners Market report for the complete data set, proprietary segment models, and tactical execution templates required to convert the 6.8% CAGR opportunity into a defensible market position.
For detailed analysis of this topic, please visit the official page: Prosthetic Liners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com