

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Glycoprotein Market to hit USD 0.84B by 2032 at 3.75% CAGR

Glycoprotein Market 2026: Strategic Imperatives and Decision Frameworks for Life‑Science Leaders
As PW Consulting’s Senior Strategic Advisor and Head of Industry Analysis, I present an executive overview of our latest Glycoprotein Market study — a practitioner’s playbook for executive teams making capital, product and partnership decisions in 2026. The glycoprotein landscape is at an inflection point: modest compound annual growth, accelerating analytical complexity, and a wave of instrument- and process‑level innovations are reshaping where value will accrue over the coming investment cycle. This introduction summarizes the strategic value of the research, key market signals, competitive dynamics, and precisely how this intelligence should change decision-making in 2026 — while intentionally holding back the full segment‑level tables and datasets to preserve the report’s commercial depth.
Glycoprotein Market
Macro snapshot you can act on
-
Market scale and trajectory: The global glycoprotein market reached approximately USD 0.65 Billion in our base year (2025). Under the forecast window (2026–2032) the market is projected to expand at a compound annual growth rate (CAGR) of 3.75%, reaching roughly USD 0.84 Billion by 2032. These rates reflect steady, application‑driven adoption rather than a single transformational demand shock.
Glycoprotein Market -
Historic momentum: From 2020 through 2025 the market moved from early commercialization into broader adoption across therapeutics, diagnostics and research workflows. That foundation matters: incremental product innovations and regulatory pressures — not volume surges alone — will determine winners.
Glycoprotein Market -
Competitive structure: The market exhibits moderate concentration, with a handful of established suppliers anchoring product and services ecosystems while numerous niche specialists compete on depth of analytical support, custom offerings, and speed to result.
Why this research matters for 2026 decisions
-
Capital allocation and R&D prioritization. With growth steady but not explosive, capital deployed into glycoprotein‑related capabilities must be justified by either margin expansion (e.g., premium analytics, platformized reagents), defensible cost advantage (scale in bioprocess analytics) or strategic lock‑in (ecosystem partnerships with instrument vendors). Our models translate market growth rates into IRR sensitivities for R&D and manufacturing projects under three plausible adoption scenarios.
-
Regulatory preparedness. Recent and forthcoming guidances are materially affecting analytical scope. Notably, authorities have raised expectations for glycan characterization in biosimilarity and comparability workstreams. These requirements increase the analytic burden on sponsors and their service providers, creating near‑term demand for validated, scalable glycosylation workflows — and reopening the procurement conversation for contract labs and instrumentation vendors.
-
Product and go‑to‑market sequencing. The roadmap for launching reagents, assays, or instrumentation must now balance speed (time‑to‑lab adoption) against validation rigor demanded by regulated manufacturers. Our report includes practical go‑to‑market playbooks that map product features to buyer personas, required validation evidence, and pricing frameworks.
Key market dynamics shaping 2026 strategy
-
Analytical intensification. Regulatory guidance and biosimilar comparability requirements have raised the baseline for glycan and glycoprotein characterization. Organizations without validated high‑throughput workflows will find licensing, bridging and release timelines elongated. This is a near‑term growth lever for providers of automated assays, mass‑spec platforms and validated kits.
-
Platform consolidation vs. best‑of‑breed. Instrumentation vendors are bundling software and analytics (e.g., unified glycoproteomic data platforms) to sell solution value beyond hardware. At the same time, niche reagent suppliers continue to win early‑stage research and discovery work. Strategic responses differ: incumbents should invest in software/analytics to maintain customer lock‑in; specialized firms should pursue partnerships or certification routes that accelerate adoption in regulated labs.
-
Process analytics and manufacturing impact. Inline and continuous PAT approaches for monoclonal antibody (mAb) production are moving from pilots to commercial scale. Early industrial validations report tangible process improvements — yield increases and glycation control — which translate to both cost savings and improved product consistency. This dynamic increases demand for analytical consumables as well as advanced sensors and chemometrics.
-
Geographic and therapeutic expansion. Market growth is being driven by expanded use of glycoprotein‑targeted therapeutics and by diagnostic sophistication in established markets. Parallel growth in several emerging biopharma clusters is creating new licensing and collaboration opportunities for suppliers with global regulatory coverage and local partnerships.
Competitive landscape — what matters to buyers and partners
Our vendor analysis synthesizes company profiles, recent product and process developments, strategic positioning, and execution risk. The following are high‑level strategic takeaways for boards and commercial leaders evaluating partnership or procurement strategies in 2026.
-
Thermo Fisher Scientific — strategic scale and process integration. Thermo Fisher’s investments in validated process analytical technologies demonstrate a clear play to capture value across discovery, development and manufacturing. Their validated continuous Raman solutions and broad portfolio (from isolation kits to high‑resolution mass specs) position them as a one‑stop vendor for biopharma customers seeking end‑to‑end validated workflows.
-
Bruker — platform differentiation through software. Bruker’s introduction of the timsOmni mass spectrometer with integrated GlycoScape software emphasizes the growing importance of software‑enabled analytics. For buyers, Bruker’s integrated platform reduces downstream data harmonization costs — a meaningful advantage in regulated characterization campaigns.
-
R&D Systems (Bio‑Techne), ACROBiosystems, Sigma‑Aldrich and others — reagents and recombinant supply strength. These suppliers continue to dominate research and early development with deep catalogs of recombinant glycoproteins, standards and ELISA kits. Their strategic choices — portfolio expansion versus targeted co‑development with instrument vendors — will determine how much of the commercial‑scale market they capture.
-
Creative Diagnostics, Enzo Life Sciences, Epitope Diagnostics, BD Biosciences — niche and clinical bridge players. These firms serve distinct buyer segments (custom antibody services, diagnostic kits, flow cytometry reagents). Their proximity to clinical labs and diagnostic OEMs makes them attractive partners for rapid regulatory validation pathways.
Recent developments that change the 2026 calculus
-
Validated PAT for commercial mAb upstream processes: Leading vendors have published process validations demonstrating meaningful titer gains and glycation control. These prove‑points accelerate adoption of inline glycosylation monitoring and alter OKR targets for manufacturing teams.
-
New rapid characterization methods: Industry announcements of ultra‑rapid glycan characterization protocols compress analytical turnaround, lowering the cost of compliance and enabling more frequent release testing — an operational advantage for firms competing on speed.
-
Regulatory tightening on glycan comparability: Updated guidances have increased the quantity and depth of data expected for biosimilarity assessments. This creates demand for validated, high‑confidence analytics and increases the value of vendor services that can supply both instruments and validated methods.
Actionable recommendations for executive teams in 2026
-
For instrument and software vendors: prioritize validated end‑to‑end workflows and regulatory documentation. Buyers increasingly value out‑of‑box compliance evidence — invest in method validation studies and co‑development pilots with marquee biopharma partners.
-
For reagent and specialty providers: focus on certification pathways that enable use in regulated labs (kit validations, ISO/GLP traceability). Consider channel partnerships with instrument OEMs to bundle offerings and accelerate adoption.
-
For biopharma developers and CMOs: reframe analytical budgets as yield and release acceleration levers. Invest selectively in PAT and high‑throughput glycan analytics where payback comes from fewer comparability risks and shortened release timelines.
-
For private equity and corporate development teams: use the moderate growth profile and identifiable de‑risking pathways to create value via roll‑up strategies that combine scalable reagent supply, software analytics and niche CDMO capabilities.
What the full PW Consulting Glycoprotein Market report delivers
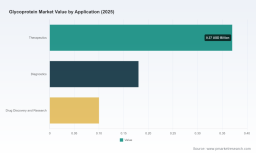
The published study contains granular, operationally focused deliverables: multiple forecast scenarios (including sensitivity to regulatory and technology adoption inflection points), commercial‑grade TAM and SAM models, segment‑level buyer persona maps, vendor assessment matrices, M&A playbooks, and ready‑to‑use slide decks for board and investor presentations. It also includes detailed annexes with methodology, primary interview transcripts, and validation datasets. To preserve the report’s commercial value and to comply with the “trailer” principle of this executive brief, detailed segment splits and numeric breakdowns by region, type and application are available only in the full report and online data portal.
Closing perspective
The glycoprotein market in 2026 offers steady growth and high strategic optionality. The most valuable moves are not merely launching another reagent or instrument; they are the orchestrated bets that combine validated analytics, software‑enabled value capture, and regulatory‑grade evidence. For decision‑makers, our research reframes the conversation: invest to de‑risk comparability and validation, partner to scale faster, and prioritize offerings that convert regulatory burden into commercial lock‑in. PW Consulting’s full report supplies the quantitative maps and tactical playbooks you need to execute those choices with precision.
To access the complete dataset, vendor scorecards, and customizable financial models referenced here, please visit the PW Consulting research portal or contact our industry team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Glycoprotein Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com