

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Radiopharmaceutical Market to reach USD 344.8M by 2032 at 7.85% CAGR

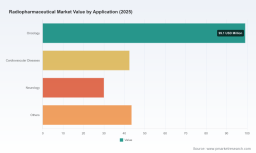
Radiopharmaceutical Market: Strategic Preview for 2026 Decision-Makers
As the radiopharmaceutical market enters a phase of accelerated commercialization and capacity reshaping, strategic clarity in 2026 will separate winners from laggards. Our PW Consulting market study — grounded on a 2025 base year and projecting through 2032 — shows a resilient market trajectory with a compound annual growth rate of 7.85%. The global market expanded from roughly USD 163.2 Million in 2020 to USD 215.0 Million in 2025, and is projected to continue upward into the next decade, reflecting both diagnostic and therapeutic momentum as well as the commercialization of novel isotopes and theranostic pairings.
Radiopharmaceutical Market
Why this study matters for decisions made in 2026
- Time-sensitive capital allocation: 2026 is a pivotal inflection point for plant investments, isotope sourcing and commercial rollouts — the report translates growth trajectories into investment horizons and breakeven timing.
- Regulatory and reimbursement synchronization: recent policy moves require coordinated regulatory, clinical and pricing strategies; our study maps the operating levers that materially affect launch economics.
- Competitive positioning and M&A: consolidation and targeted capacity plays are likely to accelerate. Our analysis identifies strategic adjacencies and capability gaps that pragmatically inform M&A and partnership prioritization.
- Operational resilience: supply chain and isotope scarcity risks are now front‑and‑center. The report provides playbooks to de‑risk production and distribution for 2026–2028 commercialization windows.
What the report delivers — practical, transaction-ready intelligence
- Forward-looking market model (2026–2032) with scenario variants reflecting reimbursement shifts, isotope supply shocks, and therapeutic approvals.
- Decision frameworks and financial tools: supply-risk-adjusted NPV models, capex prioritization matrices, and an M&A valuation checklist optimized for radiopharmaceutical assets.
- Regulatory and reimbursement roadmaps for major markets — including detailed pathways for outsourcing facilities, repackaging/compounding guidance and Schedule C implementation — tied to tactical submission timelines.
- Manufacturing and logistics playbook: capacity sizing guidance, facility footprint options, and cold-chain requirements calibrated to isotope half-lives and distribution economics.
- Commercialization blueprints: evidence generation sequencing (pivotal studies vs. real-world evidence), KOL engagement templates, and hospital adoption playbooks for diagnostic and therapeutic launches.
- Competitor dossiers and capability heatmaps that profile manufacturing footprint, proprietary isotopes, and strategic intentions across the market’s leading players.
Data-driven insights shaping strategy in 2026
- Growth dynamics: At a near 8% CAGR, the radiopharmaceutical market is large enough to attract diversified capital (both strategic and financial) but remains sufficiently fragmented that targeted investments can yield outsized returns. The growth is driven by expanded PET utilization, therapeutic radiopharmaceutical approvals, and the emergence of higher-value isotopes.
- Policy levers matter: Recent U.S. reimbursement changes are immediate game-changers. For example, CMS finalized an add-on payment for domestically produced Tc‑99m doses and set a per-day cost threshold for separate payment for diagnostic radiopharmaceuticals — moves that materially improve the economic case for local production and narrow the cost disadvantage of specialty supply chains.
- Regulatory clarity is improving — and accelerating commercialization windows. Notable regulatory milestones include Health Canada’s roadmap for radiopharmaceutical drugs and recent FDA guidance on compounding and repackaging by 503B outsourcing facilities; these reduce regulatory uncertainty but require operational alignment.
- Supply-side scale-up is underway: Significant capacity investments — from new research/manufacturing facilities to multi-hundred-million-dollar isotope plants — are reshaping the supply landscape. These investments signal both impending supply relief for some isotopes and increasing competition for specialized feedstocks and skilled personnel.
- Concentration and competitive dynamics: The market has a moderate level of concentration among the largest players. While incumbents maintain advantages in scale and distribution, the share captured by the top firms leaves room for challengers to specialize or vertically integrate and capture adjacent value pools.
Competitive landscape — who matters and why
Our study profiles leading manufacturers, their strategic postures, and capability implications for partners and acquirers. Below are the key strategic archetypes represented among incumbent and growth firms:
Radiopharmaceutical Market
- Established multinational manufacturers: Firms with broad portfolios and global distribution networks are likely to defend premium segments through bundled services (imaging agents + logistics + clinical support). They remain attractive acquisition targets for companies seeking immediate scale.
- Specialist innovators: Companies focused on high-value tracers and neuroimaging or prostate cancer diagnostics take concentrated clinical and reimbursement risk but can capture premium margins if they secure adoption among centers of excellence.
- Manufacturing and isotope builders: New facility investments from private and public players signal an opportunity to secure long-term isotope supply. These players will command strategic value beyond immediate revenue — particularly where they can contract supply to diagnostic and therapeutic manufacturers.
Representative company vignettes (strategic implication):
Radiopharmaceutical Market
- Tri‑Med Americas — a U.S.-based manufacturer with FDA-approved radiopharmaceuticals; strategically positioned for domestic supply-demand shifts.
- Curium — global supplier with diversified isotope capabilities; an anchor player for partnerships and scale manufacturing.
- Life Molecular Imaging and Eli Lilly — leaders in neuroimaging agents with differentiated clinical evidence; candidates for premium pricing and focused clinical partnerships.
- Blue Earth Diagnostics, Lantheus, Telix, Novartis and GE Healthcare — firms with concentrated oncology imaging and theranostic playbooks; attractive partners for integrated diagnostic-therapeutic value chains.
- BWXT — a specialist in radiolabeling materials and feedstock; critical in supply chain resilience strategies for inflammatory and niche imaging markets.
Strategic implications and recommended 2026 actions
- Prioritize supply-security investments now: With reimbursement incentives for domestic production and sizeable greenfield projects in motion, firms should fast-track supply contracts or equity stakes in isotope facilities where the timing aligns with their launch windows.
- Lock in regulatory-compliant manufacturing capacity: Use the new FDA 503B guidance and Health Canada roadmap to accelerate licensing for outsourcing facilities; factor regulatory lead times into the capital schedule.
- Design reimbursement-first launch plans: Structure pricing, evidence generation and coding engagement around known policy levers (including CMS thresholds) to avoid launch erosion and to capture favorable hospital reimbursement.
- Pursue focused M&A and partnerships: Look for targets that close capability gaps (isotope supply, distribution networks, clinical trial experience) rather than broad revenue hunting — this delivers faster path-to-profit in a specialised market.
- Operationalize a supply-risk-adjusted ROI framework: Integrate isotope scarcity scenarios, cold-chain costs, and reimbursement variability into investment appraisals to avoid optimistic upside bias.
- Invest in commercialization enablers: KOL networks, hospital adoption pilots, and rapid RWE programs will be decisive in converting clinical efficacy into durable utilization.
Decision frameworks and next steps
For teams making 2026 resource allocation choices, we recommend three immediate initiatives:
- 90‑day supply and regulatory sprint — map all critical isotopes, identify alternative feedstock/suppliers, and initiate at-risk regulatory submissions aligned to 503B and Schedule C timelines.
- Investment gating process — adopt a 3‑layer gateway for facility investments: (1) Strategic fit and reimbursement alignment, (2) supply-risk and talent availability, (3) commercial traction and contracting pipeline.
- M&A/partner heatmap — shortlist targets that materially reduce time-to-market or materially increase margin through vertical integration; apply our radiopharma-specific due diligence checklist to reveal hidden liabilities tied to isotope logistics and regulatory compliance.
Our report intentionally balances disclosure and commercial prudence. This preview demonstrates the depth of insight available in the full study — including the granular segmentation, regional dynamics, and proprietary financial models that are essential for point decisions in 2026. For executives evaluating capital projects, partnerships or market entry, the full PW Consulting Radiopharmaceutical Market report provides the validated inputs and executable playbooks required to convert market growth into shareholder value.
To obtain the complete dataset, segmentation tables, and our scenario models that power the recommendations above, please visit the PW Consulting research portal or contact our advisory team for a briefing tailored to your strategic priorities.
For detailed analysis of this topic, please visit the official page: Radiopharmaceutical Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com