

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Sanger Sequencing Market Set for 13.35% CAGR - PW Consulting Insight

Sanger Sequencing Service Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
The Sanger sequencing services market is re-accelerating into the mid-2020s as a stable, mission‑critical segment of genomics infrastructure. Our base-year assessment (2025) places the market squarely above the billion‑dollar threshold (USD Million scale), and the forecast through 2032 projects a sustained compound annual growth rate of approximately 13.35%. That trajectory reflects a market that is large enough to attract diversified global providers, yet sufficiently fragmented to reward focused capabilities, service quality, and tactical partnerships.
Sanger Sequencing Service Market
Why this study matters for 2026 strategic choices
Executives planning 2026 resource allocations face three linked realities: accelerating demand for targeted and regulatory-compliant sequencing; consolidation and selective acquisition among established service providers; and the persistence of decentralized, contract-based delivery models across academia, industry, and clinical environments. This report is designed to translate those realities into actionable choices across five priority decisions:
Sanger Sequencing Service Market
- Capacity and capital planning: when to expand internal sequencing versus outsource, and which outsourcing models minimize time-to-result for priority workflows.
- Go-to-market and pricing: how to position service tiers (rapid turnaround, GLP/GMP/regulatory, high-quality difficult-template solutions) to defend margin while addressing commoditization pressures.
- M&A and partnership screening: which targets or alliances create defensible value (geography, regulatory credentials, specialized application depth) without duplicative cost bases.
- Operational risk and compliance: how to align lab quality systems, sample handling, and data governance with shifting regulatory expectations and enterprise procurement requirements.
- Product and service portfolio choices: which adjacent services (e.g., synthesis, fragment analysis, integrated sample-to-insight pipelines) should be layered onto Sanger offerings to increase customer lifetime value.
Market dynamics: what the numbers tell us (high level)
From 2020 through our base year, the market expanded steadily, reflecting both the ongoing need for gold‑standard single‑read validation in research and a resurgent role for Sanger in diagnostic confirmation, biomarker verification, and regulated workflows. The projection into 2026–2032 shows an amplified growth phase driven by three structural factors: (1) increasing diagnostic and biomarker testing volumes that require confirmatory methods; (2) outsourcing by institutions and labs optimizing capital utilization; and (3) new service models that blend speed, regulatory compliance, and integrated data outputs.
Sanger Sequencing Service Market
Importantly, the market concentration metric indicates a moderate degree of consolidation: several large providers account for a meaningful share of revenue while a long tail of regional and specialty providers remains active. That balance produces differentiated competitive opportunities — scale and integrated portfolios matter, but niche service excellence continues to capture premium demand.
What the full report delivers (practical outputs)
This study is written for commercial leaders, procurement heads, lab directors, and corporate development teams who must translate market movement into a 12–36 month plan. Key deliverables include:
- Top-line market sizing and growth scenarios (base year and forecast to 2032) with sensitivity analysis across conservative, base, and accelerated adoption cases.
- Segment-level demand drivers and risk maps for applications, end‑users, and delivery channels — with prioritized use cases for near‑term investment.
- Pricing and cost benchmarks (banded and contextualized) to guide commercial negotiation and internal transfer pricing design — presented without raw contract-level disclosure but with practitioner-ready guidance.
- Operational playbooks for insourced vs outsourced sequencing, including sample logistics, QC gating, and turnaround SLAs that materially impact downstream projects.
- Regulatory and reimbursement pathways mapped to service types and clinical claims, and a compliance checklist tailored to 2026 audit expectations.
- Vendor landscaping and scorecards — capability matrices, regulatory credentials, geographic reach, and integration readiness — framed to inform RFP design and short‑list selection.
- M&A and partnership frameworks with valuation multipliers, integration risk factors, and recommended diligence questions specific to sequencing service targets.
Competitive landscape — how incumbent and emergent providers are positioning
The commercial field is anchored by long‑standing laboratories that combine high throughput with regulatory competencies, and specialist operators that compete on speed or vertical focus. Several strategic archetypes have emerged:
- Global full‑service incumbents that bundle Sanger with broader genomics portfolios (sequencing, synthesis, data analytics), pursuing consolidation through acquisitions and continent‑spanning service centers.
- Rapid‑turnaround specialists offering tightly engineered workflows and service SLAs to capture time‑sensitive R&D and QC workflows.
- Regionally dominant providers that leverage local regulatory knowledge and institutional relationships to serve clinical and academic markets.
- Niche operators targeting domain‑specific demand such as agricultural genomics, difficult-template sequencing, or low-volume clinical confirmations.
Our vendor chapter profiles a curated set of providers representative of these archetypes, assessing their strategic intent, capability gaps, and likely moves in 2026. Highlights include:
- Providers with regulatory‑grade offerings and GLP/GMP pathways that are most attractive to biopharma and clinical customers seeking validated workflows for submissions and QC.
- Operators that have invested in speed‑centric platforms and processes to deliver rapid turnarounds for R&D verification and plasmid/PCR product checks.
- Global service networks that combine local lab presence with centralized quality systems — a configuration increasingly favored by multinational R&D organizations.
Recent industry moves and their strategic implications
The market is experiencing active reshaping through several notable events that inform immediate strategy:
- Several academic cores have begun to sunset in‑house Sanger operations and redirect demand toward commercial providers — a shift that creates near‑term volume opportunities for external labs and underscores the importance of scalable intake, transparent pricing, and academic contracting familiarity.
- Acquisitions and portfolio integrations among major service providers are expanding regulatory and NGS-complementary capabilities, signaling that buyers will increasingly evaluate sequencing suppliers on end‑to‑end genomics service breadth rather than siloed capabilities alone.
- New platform and service launches that blur the line between classical Sanger services and personalized healthcare offerings are creating adjacent revenue possibilities — particularly where mobile or consumer-facing workflows are integrated with clinical pipelines.
- Strategic partnerships that stitch sample-to-insight workflows (including data interpretation layers) are reducing friction for customers and raising the bar for standalone sequencing vendors who cannot offer downstream analytics or integrated reporting.
Strategic recommendations for 2026
Based on the convergence of demand growth, selective consolidation, and buyer sophistication, we recommend that organizations frame 2026 strategies around three pragmatic pillars:
- Prioritize differentiated service packages. Design three to four discrete tiers (e.g., rapid‑turnaround R&D, regulatory/GLP, difficult-template/complex cases, and bundled sample‑to‑report offerings) with distinct pricing and SLAs. Seats at the premium table will go to providers who can prove consistent quality under audit.
- Build flexible capacity strategies. Avoid binary make‑vs‑buy decisions; instead, model blended capacity where core internal capability covers critical clinical or IP‑sensitive workflows while modular outsourcing handles volume spikes and commodity runs.
- Treat M&A and partnerships as capability accelerators, not just market share plays. Target assets that bring complementary regulatory credentials, specialized application expertise, or logistical footprints that reduce time‑to‑service across key accounts.
What we deliberately withhold here — and why you should consult the full report
This preview is intentionally high level. To preserve the utility of the full study for operational and procurement execution, we have not published the granular regional breakdowns, application‑level revenue splits, detailed per‑reaction pricing matrices from benchmark sources, or the raw vendor scorecard data. The full report includes:
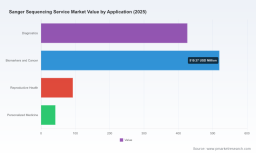
- Detailed segment volumes and growth rates by application, end‑user, and region (2020–2032).
- Pricing band analysis and procurement case studies with anonymized contract comparisons and structure recommendations.
- Comprehensive vendor scorecards, including capability heatmaps, SLA evidence, and integration readiness assessments.
- M&A target shortlist with financial proxies, integration checklists, and modeled synergies under multiple transaction scenarios.
These elements are necessary for procurement negotiations, board‑level capital approvals, and corporate development diligence — and are available via the full PW Consulting report.
Next steps for decision-makers
If your 2026 plan requires a defensible sequencing strategy — whether to scale, outsource, partner, or acquire — use this report to accelerate evidence‑based decision making. The research transforms market momentum into operational moves: where to place capital, how to structure supplier relationships, and which capability gaps to close first. For organisations that must act quickly, our advisory team can provide condensed briefings, model customization, and vendor short‑lists tailored to your risk appetite and geography.
PW Consulting’s Sanger Sequencing Service Market study is framed to be immediately actionable while preserving the in‑depth, proprietary data necessary for execution. Contact our advisory desk to unlock the full dataset, vendor scorecards, and tailored scenario models for 2026 planning.
For detailed analysis of this topic, please visit the official page: Sanger Sequencing Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com