

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Vaccine Adjuvants Market to Reach USD 2,206.5M by 2032 at 6.5% CAGR

Vaccine Adjuvants Market: Strategic Imperatives for 2026 Decision-Makers
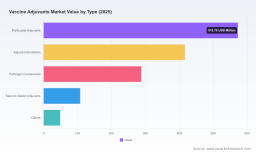
As the life sciences industry enters 2026, vaccine adjuvants have moved from a niche technical detail to a central strategic lever in vaccine R&D, commercialization and public-health preparedness. PW Consulting’s new market research — anchored on a 2025 base year and projecting through 2032 — quantifies the momentum: the global vaccine adjuvants market is estimated at approximately USD 1.44 billion in 2025 and is forecast to reach roughly USD 2.21 billion by 2032, expanding at a compound annual growth rate (CAGR) of 6.5% over the forecast horizon. These headline numbers understate the structural shifts now driving value creation, risk concentration and opportunity windows that corporate leaders must act on this year.
Vaccine Adjuvants Market
Why this research matters in 2026
- Portfolio prioritization: Biotech and big pharma leaders must decide which antigen-adjuvant pairings to advance into clinical development and where to allocate limited CMC and regulatory resources.
- Manufacturing investments: With demand for adjuvanted vaccines rising (both for infectious disease and immuno-oncology indications), manufacturers face critical capacity and sourcing choices — decisions with multi-year payback horizons.
- M&A, partnerships and licensing: The adjuvants ecosystem is consolidating around platform owners and specialized suppliers; strategic transactions executed in 2026 will shape competitive positioning for the rest of the decade.
Key macro dynamics shaping strategy
- Platform differentiation is now a commercial advantage. Proprietary platforms (e.g., Matrix‑M, AS01/AS03, MF59, CpG 1018) are more than efficacy enhancers: they are commercial enablers, lowering antigen dose requirements, broadening target populations and improving vaccine durability. Recent regulatory and commercial wins have validated this dynamic and accelerated platform adoption.
- Regulatory complexity lengthens timelines. Regulators in major markets continue to impose stringent expectations for novel and combination adjuvants, particularly for lipid- and protein-based systems. Firms must budget for extended nonclinical packages, additional comparability studies and more intensive post-marketing commitments — factors that materially affect go/no-go timing and net present value.
- Supply-chain fragility is a live risk. Key raw material sources remain geographically concentrated. For example, commercially used saponin adjuvants are still derived from Quillaja saponaria bark, exposing programs to biological, environmental and geopolitical supply shocks. That reality elevates the value of vertically integrated supply strategies and validated synthetic or semi-synthetic alternatives.
- Reimbursement and pricing dynamics are tightening. Public payers and large purchasers increasingly scrutinize incremental clinical benefit from adjuvanted vaccines relative to cost; reimbursement rules and seasonal vaccine price-setting mechanisms will influence commercialization strategies, particularly in developed markets.
- Manufacturing scale and partnerships matter. Recent capacity-expansion deals underscore a market moving from bespoke lab-scale production to GMP mass manufacturing. Companies with proven scale-up pathways or strategic partnerships with CDMOs will be positioned to capture near-term demand shocks and longer-term market growth.
Competitive landscape — who matters and why
The adjuvants market is moderately concentrated: the top three suppliers account for a material share of market value, and the top five increase that concentration further. This creates both entry barriers and partnership opportunities. Our analysis highlights three archetypes among incumbent and emerging players:
Vaccine Adjuvants Market
- Platform holders with clinical-validated systems: Companies that own licensed, clinically proven adjuvant platforms are in the strongest position to extract premium pricing and negotiate antigen-agnostic partnerships. These players drive innovation through platform improvements and cross-licensing.
- Specialist suppliers and component houses: Firms focused on specific adjuvant chemistries or manufacturing capabilities (e.g., aluminum-based adjuvants, TLR agonists, emulsion systems) function as critical supply-chain nodes. Their technical excellence makes them attractive partners for antigen developers and CDMOs.
- R&D enablers and preclinical suppliers: Providers of research-grade adjuvant components and assay platforms enable early-stage screening and translational work, shaping which platforms advance to clinical evaluation.
Representative companies that feature prominently in our competitive maps include platform-centric innovators such as Novavax (Matrix‑M), GlaxoSmithKline (AS01/AS03), and CSL (MF59) — firms that combine regulatory track records with commercial-scale manufacturing. Complementary suppliers and technology specialists — including developers of QS‑21 derivatives, CpG platforms, aluminum-based products and a range of TLR agonists — round out the ecosystem. Recent market events (regulatory approvals, platform launches and capacity partnerships) validate the strategic trajectories of these firms and confirm where competitive tensions will be fiercest.
Vaccine Adjuvants Market
Recent developments that change the playbook
- Regulatory validation accelerates platform adoption: A high-profile, protein‑based vaccine recently received regulatory approval that leverages an established adjuvant platform — an event that has immediate implications for licensing demand and for the commercial appetite of antigen developers.
- Platform innovation and product launches: Major players have introduced new adjuvant platforms intended to enhance efficacy across multiple vaccine candidates, signaling intensified competition at the platform level.
- Capacity expansion through partnerships: Strategic alliances between adjuvant developers and CDMOs are expanding the pool of available GMP manufacturing capacity for adjuvants, which de-risks commercialization timelines for later-stage vaccine candidates.
What the report delivers — practical, actionable intelligence
PW Consulting’s report is structured to convert insight into action. Key deliverables include:
- Top-line market sizing and verified forecasts (2020–2025 historical analysis; 2026–2032 forecast) with scenario variants that stress-test the impact of regulatory delay, supply disruption and accelerated platform adoption.
- Technology landscape maps that identify leading platforms, their clinical validation status, and technology gaps where investment or licensing could create differentiation.
- Regulatory pathways and dossier playbooks for novel vs. established adjuvants, including recommended nonclinical comparability studies and post‑market surveillance frameworks.
- Supply‑chain risk heatmaps and mitigation strategies, including sourcing diversification plans and candidate synthetic alternatives for supply‑constrained inputs.
- Commercial models and reimbursement sensitivity analyses to estimate net revenue under varying pricing and payer scenarios.
- Competitive benchmarking and a partner/target shortlist for licensing, co-development and M&A, aligned to specific corporate objectives (e.g., speed-to-market, margin expansion, or pipeline breadth).
- Operational playbooks — 90/180/365 day actions — tailored for R&D heads, CMC leaders and corporate development teams to implement immediately.
Note: This executive preview highlights the research’s strategic value but does not disclose the segmented tables and granular regional or application-level splits contained within the full report. Those segment-level models and company-level revenue breakouts are available in the complete study.
How executives should use this research in 2026
- CEOs and corporate development: Use the market-sizing scenarios and concentration analysis to set acquisition thresholds, identify priority partnership targets and calibrate bid pricing for platform assets.
- R&D and clinical teams: Leverage the technology maps and regulatory playbooks to select adjuvant partners and design early‑phase packages that reduce regulatory risk and preserve optionality.
- Manufacturing and supply‑chain leaders: Implement the supply‑risk mitigation strategies and CDMO selection criteria to protect timelines for pivotal trials and initial commercial launches.
- Commercial and pricing teams: Apply the reimbursement sensitivity models to forecast launch economics in major payer jurisdictions and to structure tender and private‑market strategies.
Bottom line — the strategic bets for 2026
The vaccine adjuvants market sits at an inflection point. The sector’s steady macro growth (a mid-single-digit CAGR through 2032) masks a bifurcation: platform owners with validated clinical outcomes and secure supply chains will command growing commercial premiums, while smaller suppliers without scale or regulatory depth face margin compression and acquisition pressure. For decision-makers in 2026, the imperative is clear: secure access to clinically validated platforms; de‑risk critical raw materials; align regulatory strategies to the most likely payer environments; and prioritize partnerships that accelerate manufacturing readiness.
PW Consulting’s full report operationalizes these imperatives with the data, scenario models and playbooks leaders need to make confident, high‑impact choices this year. For corporate leaders ready to convert insight into advantage, the complete study provides the granular segmentation, partner scorecards and executable roadmaps that will determine who wins in the adjuvants‑enabled vaccine marketplace.
For detailed analysis of this topic, please visit the official page: Vaccine Adjuvants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com