

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Chemical & Materials
PW Consulting PC Power Supply Market to Hit $322.2M by 2032 with 4.89% CAGR as ATX Dominates Global Revenue
By pmarketresearch, 2026-09-15
Navigating the Power Core: Strategic Insights into the 2026 PC Power Supply Market
The personal computer power supply unit (PSU) has evolved from a commoditized accessory into a critical determinant of system stability, efficiency, and performance capability. As we move through 2026, the market is experiencing a confluence of regulatory pressure, hardware evolution, and shifting demand patterns that demand careful strategic navigation. PW Consulting's latest comprehensive market research on the PC Power Supply Market offers a detailed roadmap for stakeholders aiming to capitalize on these shifts. This article outlines the macro environment, competitive dynamics, and operational realities shaping the sector, serving as a preview to the full intelligence available in our report.
Market Trajectory and Valuation Context
Understanding the magnitude of the opportunity requires a clear view of the historical growth path and the projected expansion phase. Over the historical review period from 2020 to 2025, the global market for PC power supplies demonstrated resilience despite supply chain volatility. Valued at approximately 163.15 million USD in 2020, the market climbed to 177.81 million USD in 2021. A slight correction occurred in 2022 with a valuation of 173.29 million USD, followed by a recovery trajectory that saw figures reach 193.0 million USD in 2023 and 195.33 million USD in 2024. By the base year of 2025, the market had expanded significantly to 230.67 million USD.
DIN Rail Power Supply Market
The forecast period spanning 2026 through 2032 indicates sustained growth momentum. Starting at an estimated 236.6 million USD in 2026, the market is projected to ascend steadily, reaching 259.36 million USD in 2027 and 268.41 million USD in 2028. Further projections place the valuation at 287.67 million USD in 2029, 297.72 million USD in 2030, 317.62 million USD in 2031, and culminating at 322.2 million USD in 2032. This trajectory reflects a compound annual growth rate of 4.89 percent over the forecast horizon. These figures underscore a market that is not merely recovering but structurally expanding, driven by higher wattage requirements and efficiency mandates. Our full report dissects the velocity of this growth across specific timeframes to help planners align their capacity and investment cycles.
Structural Shifts in Market Segmentation
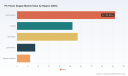
The composition of the market is undergoing significant recalibration. Historically dominated by standard desktop configurations, the landscape is now fragmented by form factor innovations and specialized industrial needs. The breadth of product types available to consumers and enterprises has widened, with standard ATX units maintaining a substantial footprint while smaller form factors like SFX are carving out niche relevance for compact builds. Additionally, the application spectrum is diversifying. While desktop computing remains the primary revenue engine, industrial applications are emerging as a distinct and growing segment, fueled by the need for robust power solutions in specialized computing environments.
Regional dynamics also play a pivotal role in shaping demand and supply chains. North America continues to represent a significant portion of market activity, reflecting high adoption rates of high-performance hardware. Europe maintains a strong presence, influenced heavily by regional regulatory frameworks. The Asia Pacific region contributes a substantial share, driven by manufacturing hubs and growing domestic consumption. Latin America and the Middle East and Africa represent emerging avenues with varying degrees of penetration. Detailed regional analysis within our study reveals specific growth vectors and potential friction points in logistics and distribution that are critical for market entry strategies.
Regulatory and Technological Dynamics
One of the most profound drivers of change in the PC power supply sector is the regulatory environment. The release of the ATX 3.1 specification in September 2023 marked a turning point. This specification introduced the 12V-2x6 connector and mandated a maximum hold-up time of 12 milliseconds to adequately support GPU power excursions. Compliance with these standards is no longer optional for manufacturers targeting the high-end segment, forcing a reevaluation of design architectures and component sourcing.
Simultaneously, energy efficiency regulations are tightening globally. The European Ecodesign Directive and California's Title 20 standards have imposed stricter no-load efficiency limits. These mandates are accelerating the adoption of advanced technologies such as digital control loops and synchronous rectification. Manufacturers must balance the cost of implementing these technologies against the competitive necessity of achieving high efficiency ratings like 80 Plus Titanium or Platinum. Our report provides a granular analysis of how these regulations impact cost structures and time-to-market for different product tiers.
Supply Chain Volatility and Cost Pressures
Operational stability is currently challenged by fluctuations in raw material costs. The passive component raw material price index, which tracks essential elements such as nickel, copper, aluminum, zinc, palladium, ruthenium, tantalum, silver, and oil, stood at 3,399 per index unit in November 2025. This represents an 8 percent rise from April 2012 levels, indicating a long-term upward pressure on input costs. Furthermore, specific supply chain disruptions have impacted critical components. Ferrite core prices within the PC PSU supply chain surged 22 percent year-over-year in the first quarter of 2026 due to supply disruptions at Asian producers.
These cost pressures necessitate sophisticated procurement strategies and pricing models. Companies that can secure stable supply lines for critical materials while maintaining margin integrity will hold a distinct advantage. The full market study includes a sensitivity analysis on raw material pricing and its potential impact on final unit economics over the forecast period.
Competitive Landscape and Key Players
The market exhibits a moderately concentrated structure, with the top three companies holding a combined share of 37.5 percent and the top five reaching 45.0 percent. This fragmentation suggests room for strategic consolidation or aggressive growth by key players. Several industry leaders are defining the pace of innovation through product launches and technological compliance.
-
FSP Group (Taiwan): A dominant force focusing on high-efficiency solutions. Their portfolio includes full modular ATX 3.1 and PCIe 5.1 ready PSUs with 80 Plus Titanium and Cybenetics Titanium efficiency. Flagship models like the MEGA TI 1650W and VITA GM 1000W exemplify their commitment to high-performance computing. In May 2026, FSP Group unveiled the FSP2000-57APB 2000W ATX 3.1 flagship power supply specifically targeting on-premise computing and AI workloads, signaling a strategic pivot toward high-density power solutions.
-
Seasonic (Japan): Renowned for premium quality, Seasonic offers fully modular ATX 3.1 compliant PSUs with 80 Plus Platinum and Cybenetics Titanium ratings. Their Prime TX and Vertex series are benchmarks for reliability. The company continues to set standards for efficiency and noise levels in the enthusiast segment.
-
be quiet! (Germany): Specializing in low-noise operations, be quiet! offers the Ultra-quiet Dark Power series and Pure Power 13 M PSUs. These units feature high-efficiency Gold to Titanium ratings meeting ATX 3.1 standards. In May 2026, they launched the Pure Power 13 M and Titan PLA series ATX 3.1 PSUs, emphasizing enhanced quiet operation and modular design.
-
Corsair (United States): A key player in the gaming and workstation space, Corsair provides HX-i, RMx, and RMe modular ATX 3.1 PSUs. These units boast 80 Plus Platinum and Cybernetics Platinum efficiency. In February 2026, Corsair introduced updated HX1500i and RMe series PSUs fully compliant with ATX 3.1 and PCIe 5.1 standards, reinforcing their position in the high-end build market.
-
Super Flower (Taiwan): Known for the Leadex Titanium and VII Platinum PRO series, Super Flower delivers full modular designs with 80 Plus Titanium and Cybenetics Platinum certifications. Their support for PCIe 5.1 ensures compatibility with the latest graphical processing units.
-
Lite-On Technology (Taiwan): Offering ATX and SFX PC power supply modules with output up to 2200W, Lite-On focuses on Platinum efficiency and full-range input for desktop and workstation applications. In May 2026, they demonstrated integrated power solutions for AI data centers and high-performance PCs at COMPUTEX 2026, highlighting their expansion into broader computing infrastructure.
PC Power Supply Market -
AcBel Polytech Inc. (Taiwan): Catering to both industrial and consumer sectors, AcBel provides PC PSUs with CRPS and slim designs. Their units reach up to 3200W with 80 Plus Titanium efficiency and include redundancy features, making them suitable for critical industrial applications.
-
Delta Electronics (Taiwan): A major electronics manufacturer, Delta supplies desktop and workstation switching PSUs. Their focus on high efficiency, 80 Plus ratings, and support for ATX 3.1 standards ensures they remain relevant in the enterprise and commercial PC segments.
-
ASRock (Taiwan): Primarily known for motherboards, ASRock has entered the PSU space with Steel Legend SL and Phantom Gaming modular PSUs. These offer ATX 3.1 compliance, Gold to Platinum efficiency, and PCIe 5.1 support, providing an integrated ecosystem option for builders.
-
Huntkey (China): Showcasing high-performance PC power supplies, Huntkey presented innovative designs for gaming and workstation applications at COMPUTEX Taipei 2025. Their focus on AI and gaming applications indicates a strategic alignment with high-growth hardware segments.
-
Enermax (Taiwan): With the Revolution III series, Enermax delivers fully modular ATX 3.1 and PCIe 5.1 PSUs. Their focus on high efficiency and low noise operation appeals to users seeking balanced performance and acoustics.
-
SilverStone (Taiwan): Offering the SX and SX Pro series, SilverStone provides high-wattage Platinum PSUs with modular cables. Their ATX 3.1 compliance ensures they meet the latest technical requirements for modern builds.
Strategic Implications for 2026 Decision Makers
For executives and strategists operating in this space, the data points to several critical action areas. First, the shift toward ATX 3.1 and PCIe 5.1 compliance is not merely a technical update but a market barrier. Products that fail to meet these specifications risk obsolescence in the high-performance segment. Second, the rising cost of raw materials suggests that vertical integration or long-term supplier contracts may become necessary to protect margins. Third, the growing importance of industrial applications and AI-related workloads suggests that diversification beyond consumer desktops could unlock significant revenue streams.
The concentration of market share among top players indicates that while the market is accessible, competing on efficiency and innovation is paramount. Companies must decide whether to compete on price in the lower tiers or differentiate through premium efficiency ratings and specialized features like those seen in the Titanium and Platinum categories. Furthermore, regional regulations require localized strategies, particularly in Europe and North America, where compliance costs can impact pricing competitiveness.
Accessing the Full Intelligence
This overview provides a snapshot of the macro trends, competitive moves, and regulatory pressures defining the PC Power Supply Market in 2026. However, the complexity of the supply chain, the nuances of regional demand, and the specific financial projections require a deeper dive. PW Consulting's full market research report contains detailed segmentation data, comprehensive company profiles, historical data tables, and forecast models that are essential for building robust business cases.
Stakeholders seeking to validate market entry strategies, optimize product portfolios, or benchmark against key competitors are advised to consult the complete study. The full report offers the granularity needed to translate these high-level insights into actionable operational plans. By leveraging this intelligence, organizations can navigate the volatility of raw material costs, align with regulatory shifts, and position themselves to capture value in a market projected to grow steadily through 2032.
As the industry continues to evolve with technological advancements and regulatory updates, staying informed with precise data is the most effective hedge against uncertainty. We invite you to explore the complete findings to ensure your strategic decisions are grounded in the most current and comprehensive market intelligence available.
For detailed analysis of this topic, please visit the official page: PC Power Supply Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial Gases Market to Reach $167.3B by 2032, Driven by 6.5% CAGR
By pmarketresearch, 2026-09-15
Navigating the Industrial Gases Landscape: Strategic Intelligence for 2026 and Beyond
The industrial gases sector stands at a critical inflection point. As global manufacturing footprints shift, energy transition mandates accelerate, and semiconductor supply chains reconfigure, the demand for oxygen, nitrogen, hydrogen, and specialty gases is evolving from a steady utility market into a strategically contested arena. PW Consulting's latest Industrial Gases Market research report offers decision-makers a comprehensive, data-driven roadmap to navigate this transformation. Covering historical performance from 2020 through 2025 and extending detailed forecasts to 2032, this analysis equips executives, investors, and supply chain leaders with the intelligence required to price risk, allocate capital, and secure long-term competitive advantage.
Macro Trajectory and Forecast Architecture
Over the past half-decade, the industrial gases market has demonstrated consistent expansion, moving from approximately 80.5 billion USD in 2020 to an estimated 108.0 billion USD by the 2025 base year. This trajectory reflects not only post-pandemic industrial recovery but also structural demand shifts driven by electronics manufacturing, clean energy infrastructure, and advanced materials processing. Looking forward, the market is projected to reach 112.85 billion USD in 2026, with growth compounding steadily through the forecast horizon to exceed 167.3 billion USD by 2032. The implied compound annual growth rate of 6.5 percent positions the sector as a resilient, above-average growth segment within broader industrial supply chains.
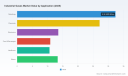
Such macroeconomic momentum, however, masks significant underlying complexity. Growth is not uniform across geographies, product categories, or end-use verticals. Strategic planners must understand where volume accumulates, which applications command premium pricing, and how regional energy economics reshape cost structures. Our report deconstructs these layers without oversimplifying them, providing scenario-based modeling that accounts for energy price volatility, capital expenditure cycles, and regulatory shifts that will define the 2026 to 2032 window.
Demand Drivers and Structural Shifts
Several interconnected forces are reshaping procurement patterns and investment priorities across the industrial gases ecosystem. First, the accelerating deployment of advanced semiconductor fabrication facilities has created sustained demand for ultra-high-purity nitrogen and specialty gas mixtures, with major supply agreements already signaling multi-year capacity commitments. Second, the global push toward decarbonization is elevating hydrogen from a niche byproduct stream to a central pillar of industrial strategy, particularly in refining, ammonia synthesis, and emerging clean mobility applications. Third, healthcare and food & beverage sectors continue to drive steady consumption of medical-grade oxygen, carbon dioxide, and argon, though margin profiles in these segments differ markedly from heavy industrial contracts.
Simultaneously, the cost environment remains a decisive factor. Electricity consumption for cryogenic air separation represents a major operating expense, and fluctuations in grid pricing directly influence producer margins. Natural gas continues to serve as the primary feedstock for many production processes, including air separation and hydrogen generation, making energy arbitrage and regional gas pricing critical variables in site selection and contract structuring. Inflationary pressures and energy cost volatility have already perturbed revenue and earnings trajectories for leading producers, while workforce dynamics have begun to stabilize, with industry headcount projections settling near 20,000 by the end of 2026. Understanding how these macroeconomic inputs propagate through pricing models, contract duration negotiations, and capital allocation decisions is essential for 2026 planning.
Competitive Landscape and Strategic Positioning
The industrial gases market is characterized by a moderately concentrated structure, with the top three players commanding approximately 55 percent of aggregate revenue and the top five entities controlling roughly 65 percent. This concentration reflects the capital intensity of production infrastructure, the value of long-term supply agreements, and the operational expertise required to maintain stringent purity and safety standards. Yet the competitive field extends beyond the largest multinational incumbents, encompassing regional specialists, integrated chemical producers, and technology-focused equipment providers that collectively shape pricing dynamics, innovation velocity, and service-level expectations.
Industrial Gases Market
Leading global providers continue to anchor the market through diversified gas portfolios and deep integration with manufacturing, chemicals, and energy sectors. Firms headquartered in France, the United States, and Ireland have historically led in scale, leveraging air separation technology, cryogenic equipment capabilities, and extensive pipeline networks to secure long-term contractual relationships. Specialized producers in Germany and Japan complement this landscape by emphasizing nitrogen, oxygen, and hydrogen production technologies tailored to specific industrial processes, while North American and Japanese manufacturers provide critical supply for electronics, healthcare, and food processing applications. Integrated chemical and energy companies also play a meaningful role, particularly where carbon dioxide and hydrogen emerge as value-added byproducts of larger processing operations.
Recent Strategic Moves and Capacity Allocation
The competitive rhythm has intensified through a series of high-profile agreements and infrastructure investments that illuminate where capital and demand are converging. In mid-2025, major suppliers executed long-term industrial gas supply agreements with leading semiconductor manufacturers, signaling multi-year commitments to support new production facilities and expanded wafer fabrication capacity. These contracts underscore the strategic importance of reliable, ultra-high-purity gas delivery in an industry where downtime carries extraordinary cost.
Simultaneously, decarbonization has moved from policy aspiration to executable project pipeline. A landmark initiative launched in early 2025 committed over one billion euros to electrolyzer units supporting green hydrogen production, reflecting a decisive shift toward low-carbon gas supply chains and signaling how traditional producers are repositioning their portfolios. In the second half of the year, additional capacity expansions were announced, including significant manufacturing and logistics center investments designed to strengthen regional supply resilience and reduce lead times for industrial customers. These moves illustrate a broader pattern: incumbents are simultaneously defending core-volume relationships in steel, chemicals, and manufacturing while building optionality in clean energy and high-purity electronics supply.
Regulatory, Operational, and Cost Dynamics
No strategic assessment of the industrial gases market is complete without confronting the regulatory and operational realities that define commercial viability. Purity and safety standards enforced by regulatory bodies such as the FDA and EMA impose specialized equipment requirements and rigorous quality control protocols, particularly for healthcare and electronics applications. Compliance is not a peripheral concern; it dictates capital intensity, validation timelines, and the cost of market entry for new facilities or product grades.
On the environmental policy front, carbon pricing mechanisms and emissions trading frameworks are beginning to reshape the economics of outsourced hydrogen and other gas supply. Benchmark reductions under evolving European regulatory structures are projected to affect free allowance distributions for significant hydrogen sales volumes, introducing new variability into pricing models and contract structures. Producers and offtakers alike must anticipate how these mechanisms will influence net costs, pass-through provisions, and the relative competitiveness of low-carbon versus conventional supply pathways.
Operationally, electricity consumption remains the dominant cost driver for cryogenic air separation plants, making energy procurement strategy a core component of margin management. Natural gas feedstock availability and pricing further influence production economics, particularly in regions where pipeline infrastructure and regional pricing dynamics diverge. Meanwhile, labor and overhead costs have experienced inflationary pressure, though industry employment levels are expected to stabilize through 2026 as automation and process optimization offset headcount expansion. Together, these dynamics create a complex optimization problem for producers seeking to balance reliability, purity, cost, and sustainability commitments.
What the Report Delivers for 2026 Decision-Making
PW Consulting's Industrial Gases Market research is designed to convert these macro trends, competitive signals, and operational constraints into actionable strategy. The report goes beyond high-level sizing to provide a detailed dissection of market architecture, including the following core components:
- Historical performance analysis spanning 2020 through 2025, establishing baseline demand patterns, pricing environments, and capacity utilization trends that inform forward-looking assumptions.
- Forecasting frameworks extending to 2032, built on scenario modeling that captures energy cost variability, regulatory evolution, and demand elasticity across major industrial verticals.
- Competitive profiling of leading global and regional players, including strategic positioning, technology focus areas, and recent contractual and investment activity that signal future market direction.
- Segment-level intelligence that explains how demand distributes across product categories and end-use applications without reducing the picture to simplistic share splits, enabling precise go-to-market and pricing strategy development.
- Regional demand assessment that contextualizes growth opportunities and cost dynamics across key markets, helping planners calibrate inventory, logistics, and local partnership strategies.
- Operational and regulatory deep dives covering purity standards, emissions framework implications, energy and feedstock cost exposure, and labor market trends that directly affect margin structures and capital planning.
Each section is engineered to support concrete decisions: whether to enter or expand in a specific geography, how to structure long-term supply agreements under volatile energy conditions, where to prioritize capital allocation for capacity upgrades, and how to anticipate regulatory cost pass-through in hydrogen and specialty gas contracts. The analysis is anchored in rigorous data handling and contextualized with industry-on-the-ground developments, ensuring that executives receive not just numbers, but interpretable intelligence.
Why This Research Matters Now
The 2026 planning cycle demands more than retrospective review. Semiconductor capacity build-outs, decarbonization project pipelines, and evolving emissions frameworks are already reshaping contractual expectations and cost baselines. Producers, offtakers, investors, and equipment suppliers must simultaneously manage near-term margin pressures while positioning for multi-year demand shifts. In this environment, the difference between reactive adjustment and proactive strategy lies in access to integrated, forward-looking intelligence that ties market sizing to competitive behavior, regulatory trajectory, and operational cost drivers.
This report provides that integration. It identifies where growth is structurally supported versus cyclically sensitive, which segments face tightening purity and compliance requirements, and how leading firms are reallocating capital to capture both traditional volume and emerging clean-energy demand. By connecting these threads, the analysis enables decision-makers to prioritize initiatives with the highest strategic return and to avoid blind spots that can erode competitiveness over the forecast horizon.
Moving from Insight to Action
The industrial gases market will not be defined solely by aggregate growth figures. It will be shaped by who secures long-term supply relationships in high-purity electronics, who executes decarbonization projects on schedule and on budget, and who manages energy and feedstock exposure with discipline. The 6.5 percent compound annual growth trajectory and the expansion from roughly 108.0 billion USD in 2025 to over 167.3 billion USD by 2032 create a substantial opportunity set, but capturing it requires granular understanding of segment dynamics, regional cost structures, and competitive intent.
Medical Gases Market
PW Consulting's full Industrial Gases Market report delivers the depth required to act confidently in 2026 and beyond. To access the complete segmentation breakdowns, company-level strategic profiles, scenario forecasts, and operational cost analysis, visit the official report page and download the full intelligence package. Equip your team with the market clarity needed to negotiate from strength, allocate capital with precision, and build resilience into your industrial gas strategy for the remainder of the decade.
For detailed analysis of this topic, please visit the official page: Industrial Gases Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Steel Grating Market Hits $227M in 2025, Projects 3.61% CAGR Through 2032
By pmarketresearch, 2026-09-15
Strategic Insights into the Global Steel Grating Market: Navigating Growth, Consolidation, and Regulatory Shifts Through 2032
Executive Overview: Positioning for the 2026 Decision Landscape
The global steel grating industry stands at a pivotal inflection point as enterprises map out capital allocation and supply chain strategies for the remainder of the decade. Building on a historical trajectory that saw the market expand from approximately 183.8 million USD in 2020 to an estimated 227.0 million USD in 2025, the sector is now projected to advance toward a 2026 baseline of 230.47 million USD and continue its measured ascent through 2032. Anchored by a forecast compound annual growth rate of 3.61 percent across the 2026 to 2032 horizon, the market narrative is no longer defined by uniform expansion. Instead, it is shaped by structural consolidation, evolving trade defenses, raw material volatility, and the operational imperative to align product portfolios with high-demand access infrastructure applications.
This analysis introduces PW Consulting’s newly released Steel Grating Market research, a decision-grade intelligence asset designed to help executives, procurement leaders, and strategic planners convert macroeconomic signals into actionable advantage. Rather than presenting a static snapshot, the study maps the interplay between capacity realignment, competitive concentration, and regional demand rhythms, equipping organizations with the foresight needed to secure margins, mitigate supply risk, and capture share in the segments that will define the next growth cycle.
Market Trajectory and Structural Forces Reshaping the Sector
The steel grating market has demonstrated resilient, if uneven, growth through the 2020 to 2025 period, with annual revenue climbing from 190.26 million USD in 2021 to 204.57 million USD in 2022 and further to 211.6 million USD in 2024. The acceleration observed in 2025, reaching 227.0 million USD, reflects a confluence of renewed industrial construction activity, sustained infrastructure maintenance spending, and the ongoing modernization of access platforms, walkways, and safety enclosures across both mature and emerging industrial corridors.
Looking forward, the 2026 to 2032 forecast period is expected to deliver incremental but strategically meaningful gains. Revenue is projected to rise from the 2026 baseline of 230.47 million USD to 249.14 million USD in 2027, 255.83 million USD in 2028, and 256.74 million USD in 2029, before continuing upward to 263.57 million USD in 2030, 289.39 million USD in 2031, and stabilizing at 289.39 million USD in 2032. The trajectory underscores a market that is broadening its addressable base rather than simply inflating existing volumes, with growth increasingly contingent on regional capacity deployment, product mix optimization, and the ability to navigate input cost cycles.
Several structural forces will determine which organizations convert this trajectory into profitability. Raw material fluctuations, particularly in carbon steel pricing, have repeatedly compressed manufacturing margins and forced producers to refine hedging strategies, forward contracting, and inventory management. At the same time, non-raw material input costs, including labor and freight, continue to escalate, compounding the pressure on grating manufacturers beyond the initial steel price shocks. On the regulatory front, the United States International Trade Commission instituted five-year reviews for steel grating from China beginning May 1, 2026, to assess whether dumping or subsidization continues and whether duty extensions remain warranted. This review introduces a renewed layer of trade policy uncertainty that can reshape import viability, domestic pricing dynamics, and sourcing strategies for North American buyers.
Environmental oversight is also recalibrating upstream conditions. The EPA finalized amendments to the National Emission Standards for Hazardous Air Pollutants concerning taconite iron ore processing in March 2024, a development that indirectly influences steel production feedstock pathways and, by extension, the cost and availability assumptions that flow through the grating value chain. Together, these dynamics create a market environment where operational agility, regulatory literacy, and procurement sophistication are no longer optional capabilities—they are competitive prerequisites.
Competitive Arena: Consolidation, Capacity, and the Convergence of Global Players
The steel grating competitive landscape is characterized by a moderately concentrated structure in which scale, fabrication expertise, and geographic footprint increasingly determine bargaining power. The market’s top three competitors hold an estimated 35.0 percent combined share, while the top five extend to approximately 55.0 percent, signaling that while fragmentation persists in regional and specialty niches, the center of gravity is shifting toward organizations that can integrate production, distribution, and engineering capabilities across broader territories.
Several established manufacturers illustrate the strategic postures shaping the market. Nucor Corporation, headquartered in Charlotte, North Carolina, produces steel bar grating through its Vulcraft and Verco divisions, maintaining an annual capacity of roughly 50,000 tons and offering standard, heavy-duty, and custom-fabricated products that serve diverse industrial requirements. IKG, operating across the United States and Mexico with more than a century of expertise, has long been recognized for pressure-locked bar grating and safety flooring and access infrastructure, supporting a full product line that includes pressure-locked and anti-slip solutions. Ohio Gratings, Inc., based in Canton, Ohio, specializes in the design, manufacturing, and custom fabrication of metal bar grating using carbon steel, stainless steel, and aluminum, and stands as the largest privately owned industrial and commercial grating provider in the United States. AMICO, the Alabama Metal Industries Corporation, continues to supply bar grating manufactured in the USA for industrial applications while expanding its catalog to encompass common bar grating items that align with high-volume procurement needs.
In Europe, JK TECHNIC, based in Sarreguemines, France, manufactures pressed gratings, electro-forged grating, and products tailored for stair treads, platforms, and industrial applications, reinforcing the technical differentiation that European producers bring to specification-driven projects. Meiser, operating as Gebrüder Meiser GmbH in Germany, is a leading steel grating manufacturer focused on high-grade products and surface refinement, including pickling, and maintains international reach through subsidiaries such as Meiser Gratings Inc. in the United States.
The competitive picture was substantially altered in early 2026 when IKG was acquired by a joint venture of Meiser and Dutco from KPS Capital Partners, a transaction that consolidated combined brands and capacity to form what is now regarded as the world’s largest grating manufacturer. This move signals a broader industry trend: capacity integration and brand convergence are accelerating as firms seek to capture economies of scale, widen geographic coverage, and strengthen their ability to serve multi-region engineering, procurement, and construction programs. At the same time, the USITC’s ongoing five-year review of Chinese steel grating introduces a regulatory variable that could reweight the competitive balance between domestic and import-dependent supply bases, particularly for buyers in North America who must weigh price competitiveness against duty exposure and supply reliability.
Structural Steel Market
Demand Architecture: Applications, Product Types, and the Regional Imperative
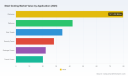
Understanding where demand concentrates is essential for prioritizing sales coverage, production scheduling, and inventory positioning. Walkways remain the most substantial application segment, reflecting the persistent need for durable, slip-resistant access infrastructure in industrial facilities, energy sites, wastewater operations, and commercial environments. Platforms represent another major demand pillar, driven by the requirement for safe, load-bearing work surfaces around processing equipment, storage systems, and elevated operational zones. Stair treads continue to hold significance as building and industrial codes prioritize both structural integrity and personnel safety, while security fences and drainage covers highlight the market’s dual role in protecting assets and managing site infrastructure. Trench covers round out the application landscape by serving utility access, roadways, and facility ground-level protection needs.
On the product side, carbon steel grating commands the largest share of the type segmentation, a reflection of its balance between structural performance, cost efficiency, and broad applicability across standard industrial installations. Stainless steel grating occupies a strategically important position for environments where corrosion resistance, hygiene, or extended service life under aggressive conditions are non-negotiable. Mild steel grating contributes to the portfolio’s versatility, particularly where lightweight or cost-sensitive structural access solutions are specified. The interplay among these product families is not static; it shifts with project specifications, lifecycle cost evaluations, and the relative pricing of base metals and finishing processes.
Regionally, the demand map reveals a pronounced concentration in Asia Pacific, where ongoing industrialization, infrastructure build-out, and expansive construction activity continue to anchor a large portion of global volume. North America maintains a significant and sophisticated demand base, shaped by industrial maintenance, energy sector activity, and an active trade policy environment that influences sourcing decisions. Europe contributes a substantial and technically discerning market, with sustained requirements in manufacturing, utilities, and specialty industrial installations. Latin America and the Middle East and Africa, while smaller in absolute terms, represent high-potential regions where economic activity, urbanization, and facility modernization can generate outsized growth when supported by reliable supply and localized service capabilities. For organizations operating across these territories, the strategic challenge is to align production and distribution networks with regional demand rhythms without overcommitting capacity to any single geography at the expense of agility elsewhere.
What the Research Delivers: A Decision-Grade Intelligence Framework
PW Consulting’s Steel Grating Market study is structured to move beyond headline figures and equip decision-makers with a practical, scenario-ready view of the market. The report integrates historical performance from 2020 through 2025 with a detailed 2026 to 2032 forecast, providing a continuous timeline that supports both near-term planning and long-range capital modeling. It examines the market through the lenses of region, product type, and application, while maintaining a deliberate focus on the interactions among these dimensions rather than treating them in isolation.
The analysis maps the competitive landscape with attention to manufacturer capabilities, capacity positioning, and the strategic implications of recent consolidation. It contextualizes raw material volatility and labor and freight cost pressure within margin and pricing dynamics, offering a structured way to evaluate how input cost cycles may influence supplier behavior, contract terms, and procurement timing. Trade and regulatory developments are assessed for their potential to alter import availability, domestic pricing, and regional sourcing preferences, with particular attention to the implications of the USITC’s five-year review and the EPA’s taconite-related amendments. The study also explores the demand hierarchy across walkways, platforms, stair treads, security fences, drainage covers, and trench covers, helping buyers and suppliers anticipate where specification requirements, service expectations, and volume concentration are likely to intensify.
Throughout, the research is designed to answer the questions that executives and planners actually face: where will growth concentrate, which product and application combinations offer the strongest margin opportunity, how will consolidation and trade scrutiny reshape supply options, and what procurement or production adjustments will best insulate an organization from cost and availability shocks. By linking market structure to operational decision points, the report enables users to test strategies against a range of plausible futures rather than relying on a single static assumption.
Strategic Implications for 2026 and the Road to 2032
As organizations enter 2026, the steel grating market rewards those who can simultaneously optimize for cost discipline, supply resilience, and segment-specific demand. The forecast trajectory suggests that growth will continue, but the value capture will increasingly depend on execution quality: aligning product mix with specification preferences, managing input cost exposure through disciplined procurement and inventory design, and positioning sales and service footprints where regional demand is most likely to expand. The recent consolidation exemplified by the formation of the world’s largest grating manufacturer through the IKG, Meiser, and Dutco joint venture illustrates the scale and integration advantages that are becoming more decisive, while the USITC review underscores the importance of monitoring trade policy as a live variable in sourcing and pricing plans.
For manufacturers, the imperative is to refine capacity utilization, strengthen differentiation through fabrication expertise and surface treatment capabilities, and build supply arrangements that can withstand raw material and freight fluctuations. For buyers and specifiers, the opportunity lies in leveraging a clearer view of competitive concentration, regional demand patterns, and regulatory risk to negotiate more effectively, diversify supply where prudent, and align specifications with total cost of ownership rather than unit price alone. In both cases, the ability to act on timely, granular intelligence will separate organizations that merely participate in the market from those that shape its outcomes.
Steel Grating Market
Access the Full Intelligence: Secure Your Strategic Edge
The overview presented here is intentionally a strategic preview. The full PW Consulting Steel Grating Market research unlocks the detailed segmentation analysis, regional demand distribution, product-type and application-level volume structures, competitor positioning, and forecast scenarios that executives need to make confident 2026 decisions and set resilient plans through 2032. To obtain the complete dataset, competitive profiles, regulatory impact assessment, and actionable recommendations, request the full report through the source page and equip your team with the intelligence required to navigate this evolving market with precision.
For detailed analysis of this topic, please visit the official page: Steel Grating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Aerospace Materials Market Hits $32B in 2025, Projects 8.2% CAGR Through 2032
By pmarketresearch, 2026-09-15
Aerospace Materials Market 2026: Strategic Intelligence for Enterprise Decision-Making
The aerospace materials sector stands at a critical inflection point as the industry navigates a transformative decade defined by evolving aircraft architectures, stringent sustainability mandates, and shifting geopolitical supply chains. For executives, investors, and operational leaders, the difference between reactive positioning and proactive strategy lies in the quality of market intelligence. Our latest Aerospace Materials Market research study delivers precisely that: a comprehensive, data-driven framework designed to inform high-stakes decisions throughout 2026 and the extended forecast horizon through 2032.
This report is not merely an aggregation of historical figures. It is a strategic navigation tool built to decode complexity, quantify opportunity, and expose the operational realities shaping material selection, capacity planning, and competitive positioning across the global aerospace value chain. Below, we outline the analytical architecture of the study, the market dynamics it captures, and why these insights carry immediate relevance for enterprise strategy in 2026.
The Macro Trajectory: What the Top-Line Data Reveals
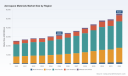
The overall market has exhibited persistent, compounding growth across the historical observation window spanning 2020 through 2025. Revenue expanded from approximately 25,504 million USD in 2020 to a baseline of 32,000 million USD by 2025. This trajectory reflects a sector resilient to cyclical aircraft delivery fluctuations, propelled instead by long-term fleet renewal programs, weight-reduction imperatives, and the gradual penetration of advanced composites into primary structural applications.
Looking forward, the forecast period from 2026 through 2032 projects continued expansion at a compound annual growth rate of 8.2 percent. Under this growth profile, market revenue is positioned to surpass 34,200 million USD in 2026 and climb toward the mid-55,000 million USD range by the close of the forecast window in 2032. These macro projections serve as the analytical backbone of the report, but they are never presented in isolation. Instead, they are contextualized against the operational realities, regulatory shifts, and competitive maneuvers that will determine which organizations capture disproportionate value as the market matures.
Decoding the Competitive Landscape
Market concentration remains a defining characteristic of the sector. The three largest players command a combined share of approximately 45.5 percent, while the top five firms collectively account for 52.8 percent of total revenue. This concentration signals a market where scale, certification depth, and long-term supplier relationships confer durable advantages, yet it also leaves meaningful room for specialized innovators, regional entrants, and vertically integrated material producers to compete on performance, cost, or technology differentiation.
The report profiles the core competitive set with granular attention to their aerospace-specific offerings and strategic positioning. Leading global suppliers of carbon fiber, prepregs, honeycomb cores, resins, and advanced composites certified for commercial aerospace primary and secondary structures anchor the upper tier of the market. Parallel to these established composites specialists, major international manufacturers have been scaling aerospace-grade carbon fiber, prepreg, and composite material production to support next-generation aircraft programs. Japanese producers contribute high-performance thermoplastics and advanced fabric architectures tailored to demanding aerospace applications. European carbon fiber reinforcement and prepreg suppliers maintain strong integration with continental aerospace and industrial ecosystems. Meanwhile, multinational specialty chemical and materials groups are intensifying development of thermoplastic composites, engineered resins, and specialty polymers designed for both structural and interior aerospace applications.
These profiles are not static descriptions. Each company assessment is framed around competitive moats, supply chain dependencies, certification status, and the strategic implications of their recent operational moves. This approach enables readers to map competitor intentions, anticipate supply-side disruptions, and identify partnership, sourcing, or investment opportunities that align with their own strategic objectives.
Recent Developments That Redefine Competitive Benchmarks
The pace of technological and commercial activity across the competitive set has accelerated markedly in recent months, and the report integrates these developments as actionable intelligence rather than isolated news items. In October 2025, a major Japanese materials producer introduced an advanced braided fabric architecture designed for lightweight aircraft structures, emphasizing improved mechanical performance and faster manufacturing throughput. Such launches signal a clear industry direction: the convergence of material performance gains with production efficiency improvements that directly impact aircraft program economics.
Aerospace Materials Market
During the Paris Air Show in May 2025, a leading composites supplier showcased new lightweight aerospace composite technologies alongside automated manufacturing systems and fuel-efficient structural concepts. Trade show activity of this caliber reflects both technological ambition and the increasing importance of demonstrating manufacturability at scale. In September 2025, an advanced materials company secured FAA-sponsored National Center for Advanced Materials Performance qualification for a next-generation epoxy resin system, reinforcing the critical role of certification milestones in accelerating material adoption. By November 2025, another specialist firm achieved full commercial availability of high-performance thermoplastic granules and powders, expanding the material toolkit for aerospace applications that demand recyclability, toughness, or simplified processing.
Capacity expansion remains equally pivotal. In December 2025, a major chemical group announced plans to expand carbon fiber production capacity across Japan and the United States to meet rising demand from commercial aviation and next-generation programs. These combined movements illustrate a market where product innovation, certification progress, and capacity builds are tightly interlocked, and where timing, geography, and regulatory alignment increasingly determine competitive outcomes.
Regulatory and Raw Material Dynamics Shaping 2026
Material costs, trade policy, and environmental compliance now exert direct influence on procurement strategy, program pricing, and supplier selection. The report treats these dynamics as first-order variables rather than peripheral context. PAN-based carbon fiber precursor prices rose approximately 3 percent in the first quarter of 2026, driven by acrylonitrile feedstock increases and logistics disruptions. Acrylonitrile upstream costs themselves climbed 2 to 3 percent in early 2026 as a result of maintenance outages and supply tightness across Asian production basins. These cost pressures ripple through composite value chains, influencing resin formulation decisions, alternate material evaluations, and negotiated pricing structures with airframe and engine manufacturers.
On the regulatory front, US tariffs on PAN-based carbon fiber imports took effect in 2025, altering cost structures for producers and raising compliance burdens for aerospace material suppliers navigating cross-border trade. At the same time, stricter environmental regulations governing graphite fiber production in developed markets, including the United States, Japan, and China, have tightened manufacturing permits and increased the operational cost of maintaining compliant output. These constraints are reshaping regional sourcing logic and encouraging dual-sourcing, regionalized production, and material substitution assessments.
Aerospace Sealants Market
Regulatory evolution is not uniformly restrictive. FAA Advisory Circular 33.15-3, issued in 2025, streamlined certification processes for established aerospace alloys and composites. For organizations with mature qualification portfolios, this development can shorten time-to-market for incremental design updates and reduce certification overhead. For newer entrants or novel material systems, the same landscape requires careful navigation of qualification pathways. The report captures these trade-offs explicitly so that readers can assess how certification strategy interacts with product roadmap decisions, supplier evaluation criteria, and regional market entry plans.
What the Study Delivers: Practical Analytical Modules
The research is structured to convert market complexity into usable decision frameworks. It combines macro market sizing with forward-looking modeling, segmentation analysis that isolates demand drivers by type and application, regional comparisons that highlight shifting center-of-gravity dynamics, and competitive intelligence that maps company strategies against market structure. Crucially, the report does not present segmentation data as static slices. It contextualizes each split against the underlying drivers, restraint factors, and adoption cycles that explain why certain material categories and application segments command disproportionate growth or resilience.
Readers gain access to structured evaluations covering material performance trends, certification and qualification pathways, supply chain sensitivities, and the strategic implications of raw material cost volatility. The study also examines how regional manufacturing capabilities, trade policy exposure, and environmental compliance requirements influence sourcing strategies and capacity planning. Each analytical module is designed to support concrete outcomes: refining procurement roadmaps, prioritizing material development investments, assessing market entry or expansion scenarios, and benchmarking internal performance against the operational rhythms of leading competitors.
Why This Research Matters for 2026 Decision-Making
Enterprise decisions in aerospace materials are increasingly interdependent. Procurement choices intersect with certification timelines. Capacity commitments must account for trade policy and feedstock volatility. Product roadmaps need to align with automated manufacturing expectations and evolving environmental regulations. In this environment, organizations that rely on fragmented intelligence or backward-looking benchmarks risk misallocating capital, misreading competitor intent, or underestimating the operational friction embedded in material transitions.
This study provides a consolidated view that connects market growth expectations with the structural forces shaping them. It enables leadership teams to evaluate where differentiation is achievable, where scale and certification confer protection, and where disruption is most likely to emerge from new material systems, regional capacity builds, or regulatory realignments. By integrating the top-line growth profile, concentration dynamics, competitive moves, and cost and compliance pressures into a single analytical narrative, the report equips decision-makers to act with greater confidence and precision throughout 2026 and beyond.
The Full Intelligence Landscape Awaits
The aerospace materials market is expanding, but its value is not distributed evenly across participants, regions, applications, or material categories. Understanding where growth concentrates, which competitive advantages are durable, and how regulatory and raw material shifts alter the playing field requires the depth and structure included in the complete study.
This preview offers a strategic overview of the macro trajectory, competitive architecture, and market dynamics that define the sector today. The full report extends far beyond this introduction, delivering the detailed segmentation context, regional analysis, company-level competitive assessments, supply-side sensitivity evaluations, and forward-looking scenario frameworks that enterprise teams need to translate market intelligence into actionable strategy. For leaders seeking to align investment, sourcing, and innovation decisions with the most current and comprehensive market picture available, the complete study provides the analytical foundation required to move decisively in 2026 and across the forecast horizon.
For detailed analysis of this topic, please visit the official page: Aerospace Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Transformer Oil Market Hits $2.53B in 2025, Rising 6.5% CAGR to $3.9B by 2032
By pmarketresearch, 2026-09-15
Strategic Imperatives in the Transformer Oil Market: Navigating Growth and Sustainability Through 2032
The global transformer oil market stands at a critical juncture where infrastructure expansion, regulatory evolution, and the push for sustainability converge. For stakeholders operating within the power transmission and distribution sector, understanding the nuanced shifts in this landscape is not merely an academic exercise but a prerequisite for strategic resilience. As we move through 2026, the decisions made today regarding supply chain partnerships, material selection, and investment allocation will define competitive positioning for the remainder of the decade. This analysis serves as an introduction to our comprehensive market study, designed to equip leadership teams with the intelligence necessary to navigate the forecast period from 2026 to 2032.
Our latest research underscores a market trajectory defined by steady expansion. Valued at approximately 2.53 billion USD in 2025, the market is projected to reach nearly 3.91 billion USD by 2032. This growth pathway reflects a compound annual growth rate of 6.5 percent over the forecast period. Such figures indicate more than just incremental gains; they signal a fundamental strengthening of demand drivers rooted in grid modernization and energy transition initiatives. However, aggregate numbers only tell part of the story. The real strategic value lies in dissecting the underlying dynamics that will dictate margin stability, supply security, and technological relevance in the coming years.
Market Trajectory and Historical Context
To understand where the market is heading, one must first appreciate the recent historical performance that sets the baseline. Between 2020 and 2025, the market demonstrated resilience despite global supply chain disruptions and fluctuating raw material costs. The valuation grew from 1.90 billion USD in 2020 to 2.53 billion USD in 2025. This period of recovery and stabilization provides a solid foundation for the accelerated growth expected through 2032.
The forecast period suggests a continued upward trend, with valuations expected to climb to 2.72 billion USD in 2026 and surpass 3.25 billion USD by 2029. By the end of the forecast window in 2032, the market is anticipated to hit 3.91 billion USD. This progression implies that demand will outpace many traditional industrial fluid markets, driven by specific needs within high-voltage infrastructure and renewable energy integration. For procurement leaders and strategic planners, this growth curve suggests that locking in supply agreements now may offer cost advantages compared to waiting as demand intensifies.
However, growth is not uniform across all segments. The interplay between different fluid types and application verticals creates pockets of high volatility and opportunity. Our report delves into these variations without relying on static snapshots, instead offering a dynamic view of how value shifts across the ecosystem. Understanding which segments are driving the bulk of this revenue growth is essential for prioritizing R&D budgets and sales focus.
Competitive Landscape and Strategic Positioning
The transformer oil market is characterized by a moderately concentrated competitive structure. The top three players hold a combined market share of approximately 46.3 percent, while the top five account for 61.2 percent. This concentration indicates that while dominant players exert significant influence over pricing and standards, there remains sufficient fragmentation for specialized entrants to carve out niche dominance, particularly in sustainability-driven segments.
Insulating Oil Market
Major global energy and chemical companies form the backbone of this supply chain. Entities such as Shell plc and ExxonMobil Corporation continue to leverage their extensive logistics networks and R&D capabilities to supply premium mineral and specialty oils. ExxonMobil, for instance, has been advancing recycling technologies under the ISCC PLUS framework, such as their Exxtend process, which aligns with broader circular economy goals. Similarly, Chevron Corporation maintains regional strength in North America and Asia-Pacific, supplying base and transformer oils derived from refined petroleum.
In Europe, Nynas AB has emerged as a pivotal player focusing on sustainability and circularity. Their portfolio includes premium mineral, naphthenic, ester, and fully circular re-refined transformer oils like NYTRO RR 900X. Recent developments highlight their strategic momentum. In March 2026, Hitachi Energy deployed Nynas circular transformer oil in its power transformers factory in Cordoba, Spain. Concurrently, Nynas supplied sustainable transformer technology to KONČAR – D&ST for Sweden's first wooden substation. These deployments are not isolated incidents but indicative of a shifting standard where circular fluids are becoming viable for major infrastructure projects. Nynas further reinforced this position with strong Q4 earnings growth and improved financial positions driven by higher product margins, followed by continued profitability improvements in Q1 2026.
Asian markets are represented by significant industrial players like Sinopec Corp and Apar Industries Limited. Sinopec provides large-scale production of transformer oils including mineral and specialized grades for domestic and export markets, capitalizing on the infrastructure boom in China. Apar Industries, based in India, manufactures the POWEROIL range covering naphthenic, iso-paraffinic, natural ester, and synthetic ester options with ultra-low sulphur and compliance to IEC and IS standards. Their focus on compliance underscores the importance of meeting varying regional regulatory requirements across developing grids.
Specialists are also reshaping the landscape. Cargill, Incorporated remains a pioneer in natural ester transformer fluids, emphasizing high fire resistance suitable for urban substations and offshore wind applications. This specialization addresses safety concerns in populated areas and harsh environments. Meanwhile, Ergon, Inc. and Calumet Specialty Products Partners maintain dominance in the US market through deep application expertise in naphthenic and mineral transformer oils, supporting regional supply chains against global volatility. TotalEnergies rounds out the major competitive set by supplying high-performance mineral and ester oils with a strong emphasis on sustainability and quality certifications.
Regulatory and Raw Material Dynamics
Market participants must navigate a complex web of regulatory and raw material dynamics that directly impact cost structures and operational compliance. Environmental regulations are tightening globally. In the United States, EPA regulations under TSCA require incineration for transformer oil containing more than 50 ppm of PCBs. This mandates rigorous testing and handling protocols, adding layers of operational complexity and cost for legacy equipment management.
In Europe, the regulatory environment is equally demanding. The EU approved new transformer energy performance regulations in February 2025, setting stricter efficiency and greenhouse gas reduction targets. These regulations push manufacturers and utilities toward fluids that not only insulate effectively but also contribute to overall system efficiency and lower carbon footprints. This regulatory pressure is a primary catalyst for the adoption of ester-based and bio-based fluids, which often possess favorable environmental profiles compared to traditional mineral oils.
Raw material volatility presents another layer of risk. Base oil prices in the USA reached 1,842 USD/MT in March 2026, reflecting upward pressure from crude oil volatility. This price point highlights the sensitivity of transformer oil pricing to broader energy markets. Historical data also shows that transformer oil prices rose 5 percent in June 2023 due to rising crude oil prices and increased demand from China. Such fluctuations require robust hedging strategies and diversified sourcing arrangements. Additionally, trade policy changes can alter import costs. All additional ad valorem duties under IEEPA on imports from certain countries were terminated effective February 2026. While this may reduce costs for some importers, the geopolitical landscape remains fluid, necessitating continuous monitoring of tariff regimes.
Application Versatility and Technology Shifts
The utility of transformer oil extends beyond traditional substations. While transformers remain the primary application driver, the demand is diversified across reactors, switchgear, and capacitors. Each application has distinct performance requirements regarding dielectric strength, thermal conductivity, and fire safety. The shift toward renewable energy integration, particularly offshore wind, is creating specific demand for fluids with high fire resistance and environmental acceptability. This is where natural ester fluids are gaining traction, offering solutions that mitigate risk in sensitive environments.
Furthermore, the type of oil used is evolving. While mineral oil remains the dominant type due to cost-effectiveness and established handling infrastructure, silicone and bio-based oils are capturing specific market segments driven by sustainability mandates and safety requirements. The choice of oil type is increasingly becoming a strategic decision linked to the asset's lifecycle cost and regulatory compliance rather than just initial procurement price. Our research provides detailed profiling of how these type preferences vary by region and application, helping stakeholders identify where the highest growth potential lies for each fluid category.
Value of the Comprehensive Study
This article serves as a high-level overview, but the full depth of opportunity and risk can only be captured through a granular analysis. Our comprehensive market research report offers detailed segmentation analysis that breaks down market size and growth rates by region, type, and application without relying on aggregate averages. This level of detail is crucial for identifying specific high-growth corridors and underserved niches.
The report includes extensive company profiling, offering insights into the strategic moves, product portfolios, and recent financial developments of key market players. By understanding the capabilities and recent activities of competitors like Nynas, Shell, and Sinopec, businesses can better anticipate market shifts and potential partnership opportunities. The inclusion of recent developments, such as the March 2026 deployments and earnings reports, ensures that the intelligence is current and actionable.
Transformer Oil Market
Furthermore, the study provides a rigorous examination of market dynamics, including regulatory frameworks and raw material price trends. This contextual information is vital for scenario planning. Whether you are looking to enter a new geographic market, launch a specialized product line, or optimize your supply chain against crude volatility, the data provided in the full report serves as the empirical foundation for those decisions.
In conclusion, the transformer oil market through 2032 offers significant opportunities for those equipped with the right intelligence. The convergence of grid expansion, regulatory pressure for sustainability, and raw material volatility creates a landscape where informed strategy is the primary differentiator. We invite you to access the full market research report to gain the specific data points, forecasts, and strategic recommendations needed to secure a competitive advantage in this evolving industry. The detailed segmentation data, competitive benchmarking, and regional analysis contained within the full document are designed to support precise decision-making for the remainder of the decade and beyond.
For detailed analysis of this topic, please visit the official page: Transformer Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hard Coating Film Market Hits $715 Million in 2025, 6.44% CAGR to Reach $1.12 Billion by 2032
By pmarketresearch, 2026-09-15
Navigating the Hard Coating Film Market: Strategic Intelligence for 2026 and Beyond
The global hard coating film industry stands at a critical inflection point. As display technologies evolve, automotive interfaces become more sophisticated, and medical devices demand higher performance standards, the protective layers that enable these innovations are experiencing sustained growth. Our latest comprehensive market research on the Hard Coating Film Market provides the strategic framework necessary for enterprise decision-makers to navigate this complex landscape through 2032 and beyond.
This analysis reveals a market that has demonstrated remarkable resilience and steady expansion. The historical trajectory from 2020 through 2025 shows consistent upward momentum, with the market growing from 520.0 million USD to 715.0 million USD. This growth reflects not merely cyclical demand but structural shifts in how industries approach surface protection, optical clarity, and functional integration. The forecast period from 2026 to 2032 projects continued expansion, with the market expected to reach 1116.0 million USD by the end of the forecast window. The compound annual growth rate of 6.44% during this period signals a market that is maturing yet still offers substantial opportunities for strategic players who can position themselves advantageously.
For executives, product managers, and investment analysts, understanding these macro trends is only the beginning. The true value lies in dissecting the drivers, constraints, competitive dynamics, and regional nuances that will determine which organizations capture market share and which fall behind. This report is designed to deliver that precision intelligence.
Market Evolution and Structural Transformation
The hard coating film sector has undergone significant transformation over the past half-decade. Early market development was driven primarily by consumer electronics applications, where scratch resistance and optical clarity were paramount. Today, the landscape has expanded considerably. The demand profile now encompasses automotive displays, medical instrumentation, industrial safety equipment, and emerging flexible electronics applications. This diversification has created a more resilient market structure while simultaneously increasing the complexity of competitive positioning.
Several technological breakthroughs are reshaping industry expectations. Self-healing coating formulations that recover from minor abrasions represent a paradigm shift in product longevity and user experience. Dual-function coatings that simultaneously address anti-glare and anti-fingerprint requirements demonstrate how multifunctional integration is becoming a competitive necessity rather than a premium differentiator. The push toward environmentally sustainable coating processes, including water-based formulations, reflects both regulatory pressure and corporate sustainability commitments that are increasingly influencing procurement decisions.
Hard Coating Film Market
These technological advances intersect with evolving regulatory frameworks across multiple jurisdictions. Safety standards for automotive and industrial applications continue to tighten, while medical device regulations demand biocompatible formulations that meet rigorous international standards. Companies that proactively align their product development with these regulatory trajectories will find themselves better positioned to serve high-value segments that prioritize compliance and certification.
Segmentation Dynamics and Growth Vectors
The market structure reveals distinct performance patterns across material types, application categories, and geographic regions. Understanding these segmentation dynamics is essential for identifying where investment capital will generate the highest returns and which segments face consolidation pressure.
Hardcoated polycarbonate film has established itself as a dominant material category, reflecting its superior impact resistance characteristics that make it indispensable for applications where mechanical durability is non-negotiable. Hardcoated polyethylene terephthalate film represents another significant segment, serving applications where specific optical and processing requirements drive material selection. The presence of diverse material formulations in the broader market indicates that no single solution fits all use cases, and successful suppliers must maintain a portfolio approach that addresses varied customer specifications.
Application segmentation tells a story of concentrated demand in certain end-use sectors alongside emerging opportunities in others. Mobile phone displays continue to represent a substantial demand center, driven by the relentless cycle of device launches and the premium positioning of protective film solutions. Touch panel applications form another significant demand pillar, while appliance overlays and membrane switches reflect the broader industrial and consumer goods penetration of hard coating technologies. Each application segment carries distinct performance requirements, pricing sensitivities, and procurement cycles that demand tailored go-to-market strategies.
Geographic distribution of market activity reveals that mature markets continue to generate substantial revenue while developing markets present growth acceleration potential. The interplay between established manufacturing hubs and emerging production centers creates both opportunities for capacity expansion and risks related to supply chain concentration. Understanding regional competitive intensity, customer density, and regulatory environments is critical for sizing market entry investments and determining whether organic growth, partnership, or acquisition represents the optimal expansion pathway.
Competitive Landscape: Key Players and Strategic Positioning
The competitive environment in the hard coating film market is characterized by a mix of specialized manufacturers and diversified industrial giants. The market concentration metrics indicate a moderately fragmented landscape where the top three players command approximately 28 percent of total revenue, while the top five collectively represent about 38 percent. This structure suggests that while scale advantages exist, there remains meaningful room for specialized competitors to differentiate through technology, service, or niche market focus.
Japanese manufacturers have established particularly strong positions in the high-performance segment of the market. Kimoto Co., Ltd. has built a reputation for precision-coated optical hard coating films serving displays, touch screens, and medical applications, with product specifications emphasizing 7H hardness ratings and ultra-thin format capabilities. Their recent expansion of the Tokyo facility by 11 million square meters demonstrates a commitment to scaling capacity in response to demand signals. Toray Industries, Inc. has positioned itself at the intersection of advanced materials science and application expertise, offering next-generation multilayer hard coating films designed for foldable OLED screens, automotive applications, and electronics. Their focus on 6H hardness with a 2.5 millimeter bending radius, combined with an environmental sustainability emphasis, illustrates how technical performance and corporate responsibility are increasingly integrated into value propositions. Toray's distribution agreement to supply hard coating films to over 120 OEMs in Europe highlights the importance of channel partnerships in penetrating established markets.
Gunze Limited has pursued a differentiated strategy by developing dual-function hard coating films that integrate anti-glare and anti-fingerprint technologies simultaneously. Their achievement of 94 percent light transmittance while delivering 68 percent fingerprint reduction demonstrates the technical sophistication that end-users increasingly demand. The shipment of 3.6 million square meters within eight months of development signals strong market receptivity to multifunctional solutions. Arisawa Manufacturing Co., Ltd. has introduced a particularly innovative product category with proprietary self-healing hard coating films capable of recovering from minor abrasions within 24 hours at room temperature. The projected 46 percent service life improvement in touchscreen applications addresses a fundamental pain point in device durability and total cost of ownership, positioning this technology for significant adoption in high-use environments.
The American market features a diverse set of competitors with varying area specializations. Tekra LLC provides Marnot and Terrapin branded hardcoated polycarbonate and polyester films for displays, medical, and industrial applications, emphasizing chemical and abrasion resistance. Vampire Coating, Inc. focuses on specialized optical and protective hard coating films for aerospace, defense, and scientific instruments, where custom formulations and extreme performance requirements justify premium pricing. SDC Technologies, Inc. offers optically clear thermal and UV-cure hard coatings with premium abrasion and chemical resistance targeting optics, medical devices, and safety applications. 3M Company leverages its vast industrial portfolio to provide hard-coated films and laminates with superior scratch resistance and durability across electronic displays, automotive, and industrial protective applications, benefiting from brand recognition and distribution scale.
Asian competitors outside Japan are also making significant strategic moves. SKC Co., Ltd. from South Korea manufactures hard-coated PET films for displays, EV touchscreens, and flexible electronics, with capacity ramps driven by demand signals from these growing end markets. Lintec Corporation supplies hard coating films with antimicrobial and self-healing properties, extending functionality into medical kiosks, electronics, and industrial surfaces. Chinese manufacturers such as Chiefway Technology and HYNT Coating Technology are developing competitive capabilities in anti-static and protective hard coating films for PET substrates using roll-to-roll processing, as well as water-based hard coating lines for anti-scratch, anti-fog, and functional films serving consumer electronics and automotive sectors. These developments reflect the broader globalization of manufacturing capability and the increasing importance of cost-competitive production in volume-driven segments.
Industry Dynamics: Drivers, Restraints, and Regulatory Influences
Several structural forces are shaping the trajectory of the hard coating film market. The proliferation of display interfaces across automotive, consumer electronics, medical, and industrial equipment continues to generate baseline demand growth. As screens become larger, more numerous, and more critical to user experience, the requirement for durable, optically clear protective coatings becomes increasingly non-negotiable. The emergence of foldable devices, transparent displays, and augmented reality interfaces introduces new performance parameters that drive innovation in coating formulations and deposition processes.
Raw material availability and cost dynamics represent ongoing considerations for market participants. Polyester substrates have captured significant market share in hard coating film production, supported by capacity investments from major material suppliers. The availability, pricing stability, and quality consistency of base materials directly influence coating manufacturers' ability to maintain competitive pricing while preserving margin structures. Companies that develop strong supplier relationships, secure long-term supply agreements, or invest in backward integration where strategically justified will enjoy advantages in cost management and supply assurance.
Regulatory compliance has evolved from a baseline requirement to a strategic differentiator in many application segments. Hardcoated polycarbonate films that meet demanding impact resistance standards and polyester hardcoated films that satisfy ANSI Z87.1 safety requirements for automotive and industrial use illustrate how regulatory frameworks shape material selection and product specification. PVC films used in certain applications must satisfy RoHS and REACH compliance for medical and consumer electronics markets, adding complexity to material sourcing and formulation development. For medical device applications, hardcoated films incorporating biocompatible polymer formulations that meet ISO 10993 standards represent a specialized niche where regulatory expertise and testing capability create meaningful barriers to entry. Companies that invest in regulatory affairs capabilities and maintain proactive compliance postures will find themselves better positioned to serve regulated industry segments that offer attractive margins and sticky customer relationships.
Sustainability considerations are gaining prominence in procurement decisions across multiple industries. Water-based coating processes, lower-VOC formulations, and recyclable substrate options are increasingly requested by customers who face their own sustainability reporting obligations and corporate responsibility commitments. Suppliers that can demonstrate environmental performance improvements without compromising technical specifications will have a competitive advantage in markets where sustainability criteria are weighted in supplier selection processes.
What This Report Delivers: A Toolkit for Strategic Action
This Hard Coating Film Market research report is structured to provide actionable intelligence at multiple levels of organizational decision-making. The analysis goes beyond descriptive market characterization to deliver the kind of granular insight that supports capital allocation, product roadmapping, competitive positioning, and market entry strategy development.
The report provides a comprehensive market sizing framework that establishes baseline revenue figures, growth trajectories, and forward projections across the full forecast horizon. This quantitative foundation enables scenario planning and sensitivity analysis that account for variations in macroeconomic conditions, technological adoption rates, and competitive intensity. The segmentation analysis dissects market performance by material type, application category, and geographic region, revealing where growth is concentrating, which segments face maturity or saturation risks, and how cross-segment dynamics influence overall market evolution.
Competitive profiling extends beyond basic company descriptions to analyze strategic positioning, technological capabilities, recent corporate developments, and inferred competitive advantages. The inclusion of recent developments such as capacity expansions, distribution agreements, product launches, and technology demonstrations provides a window into current strategic priorities and resource allocation patterns among key market participants. Understanding what competitors are investing in reveals where they see growth opportunities and how they intend to differentiate their offerings.
The report incorporates analysis of industry dynamics including driver and restraint assessments, regulatory impact evaluations, and supply chain considerations. This contextual framework helps decision-makers anticipate how external factors will influence market conditions and adjust their strategies accordingly. By connecting market data with qualitative industry intelligence, the report enables a more nuanced understanding of cause-and-effect relationships that pure quantitative analysis might miss.
Worldwide Polyester Coating Market
End-use application analysis traces demand from specific industry verticals, examining procurement patterns, specification requirements, and emerging needs that will shape future coating development priorities. This application-centric perspective is particularly valuable for suppliers seeking to align their product development pipelines with the most promising demand signals and for investors evaluating the growth potential of different market segments.
Implications for 2026 Decision-Making
As organizations plan their strategic initiatives for 2026 and the ensuing years, several implications emerge from the market intelligence presented in this research. First, the sustained growth trajectory of the hard coating film market suggests that demand tailwinds will continue to support expansion, but the distribution of growth across segments and regions will be uneven. Companies that attempt to compete broadly without clear prioritization risk spreading resources too thinly. Focusing investment on segments where technological differentiation, customer relationships, or cost position provide defensible advantages will generate better returns than undifferentiated participation across all market categories.
Second, the pace of technological innovation in coating formulations, including self-healing properties, multifunction integration, and environmentally sustainable processes, indicates that product lifecycle management must remain a strategic priority. Companies that allow their product portfolios to become technologically obsolete relative to emerging alternatives will face margin compression and customer attrition. Continuous investment in research and development, whether conducted internally or through partnerships with technology providers, is essential for maintaining competitive relevance.
Third, the geographic distribution of manufacturing capability and customer concentration creates both opportunities and vulnerabilities. The expansion of production capacity in key regions, the establishment of new distribution agreements, and the development of locally tailored product offerings all represent strategic moves that can influence regional market share dynamics. Organizations must assess whether their current geographic footprint aligns with where demand is growing and where competitive intensity is evolving.
Fourth, regulatory and compliance considerations will increasingly influence market access and customer qualification processes. Companies that proactively address regulatory requirements, invest in testing and certification capabilities, and position their products to meet emerging standards will reduce barriers to entry in high-value regulated segments. Those that treat compliance as a reactive cost center rather than a strategic capability may find themselves excluded from attractive market opportunities.
Conclusion
The Hard Coating Film Market represents a sector where sustained demand growth intersects with rapid technological evolution and increasing competitive sophistication. Success in this environment requires more than awareness of market size and growth rates. It demands deep understanding of segmentation dynamics, competitive capabilities, technological trajectories, regulatory frameworks, and regional market characteristics. The organizations that thrive will be those that translate market intelligence into focused strategy, disciplined resource allocation, and agile execution.
This research report is designed to equip decision-makers with the comprehensive intelligence necessary to make those strategic choices with confidence. By revealing the underlying structure of the market, the capabilities and intentions of key competitors, and the dynamics that will shape future growth, the report provides a foundation for planning that reduces uncertainty and increases the probability of successful outcomes. We invite you to explore the full analysis to gain the depth of insight required for navigating the hard coating film market through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Hard Coating Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Trehalose Market to Reach $275M by 2032, Growing at 5.45% CAGR
By pmarketresearch, 2026-09-15
### Strategic Trajectory of the Global Trehalose Market: Navigating Value Creation Opportunities Through 2032
Executive Perspective
In an era where ingredient functionality directly dictates product shelf-life, consumer acceptance, and formulation economics, few compounds offer the multifunctional promise of trehalose. As a non-reducing disaccharide celebrated for its moisture-retention capabilities, thermal stability, and ability to preserve structural integrity in proteins and cellular matrices, trehalose has transitioned from a specialized biochemical reagent to a cornerstone ingredient across food, nutraceutical, pharmaceutical, and cosmetic supply chains. Our latest comprehensive market intelligence report dissects this evolution with meticulous granularity, positioning procurement leaders, R&D directors, and corporate strategists to make informed capital allocations and portfolio adjustments for the 2026 horizon and beyond.
The global trehalose market has demonstrated resilient expansion over the past half-decade, climbing from a baseline valuation of 130.0 million USD in 2020 to an estimated 190.85 million USD in 2025. This trajectory reflects sustained demand pull from clean-label formulation shifts, heightened investment in biologic stabilization technologies, and the gradual commercialization of trehalose-enabled cosmetic actives. Our forecast window extends through 2032, projecting the market to reach 275.0 million USD. This expansion translates to a compound annual growth rate of 5.45 percent, a figure that underscores steady, non-speculative growth rather than erratic hype cycles. For decision-makers, this CAGR is not merely a top-line metric; it signals a mature yet still structurally expanding addressable market where early positioning, supply chain resilience, and application-specific differentiation can yield disproportionate returns.
Market Architecture and Growth Drivers
Historical Resilience and Forecast Trajectory
The historical record from 2020 through 2025 reveals a market that navigated pandemic-era logistics disruptions, raw material volatility, and shifting regulatory frameworks without losing momentum. The year-over-year progression from 146.74 million USD in 2021 to 159.09 million USD in 2022, then to 172.06 million USD in 2023, illustrates incremental but compounding demand. By 2024, the market reached 176.61 million USD, and the acceleration into 2025 at 190.85 million USD suggests that trehalose has embedded itself deeply into industrial workflows. Looking ahead, the forecast period paints a picture of sustained scaling: 204.22 million USD in 2026, 218.92 million USD in 2027, a slight recalibration to 216.8 million USD in 2028 reflecting expected short-term supply chain rebalances, and then renewed expansion toward 235.33 million USD in 2029, 243.67 million USD in 2030, 260.96 million USD in 2031, and finally 275.0 million USD in 2032. This trajectory signals that trehalose demand is not cyclical but structurally anchored in multiple end-use verticals.
Structural Segmentation Dynamics
Our report deconstructs the market into three primary segmentation dimensions: product formulation type, end-use application, and regional distribution. In the type dimension, the landscape is divided between powdered and liquid trehalose formats, each serving distinct handling, dosing, and formulation requirements. Powdered trehalose commands a larger absolute share, reflecting its versatility in bulk industrial processing, dry blend applications, and extended shelf-life storage. Liquid trehalose, meanwhile, addresses continuous-process manufacturing environments and specific beverage or liquid formulation workflows where dissolution speed and dosing precision are paramount. Both formats are expanding, but their relative attractiveness varies sharply by vertical and by regional manufacturing infrastructure.
Trehalose Market
D-Mannose Market
In the application dimension, food and beverage applications represent the largest consumption pool, driven by trehalose's function as a mild sweetener, texture modifier, and moisture stabilizer in baked goods, confectionery, and frozen desserts. Dietary supplements and nutraceuticals constitute a meaningful secondary stream, leveraging trehalose's reputation for cellular protection and metabolic neutrality. The pharmaceutical sector represents a high-value, high-specification niche where trehalose dihydrate serves as a critical cryoprotectant, lyoprotectant, and formulation stabilizer for biologics, vaccines, and cell therapies. Cosmetics and personal care applications, while smaller in absolute volume, are expanding rapidly as formulators seek naturally derived humectants and skin-barrier-supporting sugars with clean-label profiles. A residual others category captures specialized industrial and research uses that, while niche, often command premium pricing and technical service requirements.
Regionally, the market exhibits a multi-polar distribution. North America maintains a leading position, supported by advanced pharmaceutical development pipelines, well-established food ingredient distribution networks, and strong consumer demand for functional and clean-label products. Europe follows as a substantial market, shaped by stringent quality expectations, a robust cosmetics and personal care ecosystem, and growing pharmaceutical biomanufacturing activity. Asia Pacific represents a high-growth engine, where expanding food processing capacity, rising healthcare expenditure, and localized manufacturing investments are driving both volume growth and supplier diversification. Latin America and the Middle East and Africa collectively represent smaller but strategically emerging footprints, where import dependencies, regulatory evolution, and infrastructure development create both challenges and first-mover opportunities. The precise regional value distribution, application-level breakdowns, and type-specific volume allocations are mapped in exhaustive detail within the full report, enabling granular scenario modeling that goes far beyond aggregate market sizing.
Competitive Landscape and Strategic Positioning
The trehalose market is characterized by a moderately concentrated supplier base, with the top three players accounting for approximately 45 percent of total market revenue and the top five collectively commanding around 65 percent. This concentration reflects the technical barriers associated with high-purity production, enzymatic process optimization, and, in the pharmaceutical grade segment, compliance with pharmacopoeial standards and low-endotoxin specifications. Yet the remaining market share is distributed among a diverse set of regional and application-focused suppliers, creating a landscape where competitive advantage is increasingly defined by application engineering, regulatory readiness, and supply reliability rather than volume alone.
Nagase & Co., Ltd., headquartered in Tokyo, Japan, exemplifies the high-purity, application-engineered approach. Through its TREHA® brand, the company manufactures high-purity trehalose via a proprietary enzymatic process derived from starch, supplying food and beverage ingredient channels with a product designed for clean-label, texture-preserving, and flavor-modulating formulations. Nagase's positioning emphasizes technical service, regulatory documentation, and consistent quality, aligning with customers who prioritize formulation predictability and label credibility.
Shandong Fuyang Biotechnology Co., Ltd., based in Pingyuan, Shandong, China, operates within the corn deep-processing ecosystem and produces food-grade trehalose as part of a broader carbohydrate ingredient portfolio. Its export-oriented model reflects the growing integration of Asian starch-derived ingredient manufacturing into global supply chains. Meihua Holdings Group Co., Ltd., located in Langfang, Hebei, China, similarly leverages its scale and integrated processing capabilities to supply trehalose as a colloidal polysaccharide ingredient, emphasizing freshness preservation and product quality enhancement in food applications. Meihua's commitment to environmental management, evidenced by full ISO 14001 certification coverage, signals an ESG-aware supplier profile that increasingly matters to multinational procurement teams.
On the Western side, Cargill, Incorporated, headquartered in Minneapolis, USA, distributes and supplies food-grade trehalose dihydrate tailored for bakery, confectionery, and clean-label applications. Cargill's strength lies in its global distribution reach, formulation expertise, and ability to embed trehalose within broader sweetener and functional ingredient portfolios. Pfanstiehl, based in Waukegan, Illinois, USA, occupies a distinct high-value niche by manufacturing USP-NF, EP, JP, and ChP-grade high-purity, low-endotoxin trehalose dihydrate for biopharmaceutical stabilization and cryopreservation. Pfanstiehl's compliance with multiple pharmacopoeial standards and its focus on endotoxin control make it a critical partner for biotechnology and pharmaceutical customers where quality specifications are non-negotiable and batch consistency directly impacts product viability.
Additional suppliers such as Shandong Deshang Chemical Co., Ltd. and Changyi Longchang Bio-Chemical Co., Ltd., both operating from the Shandong region of China, contribute to a vibrant competitive ecology. Shandong Deshang remains an active supplier of trehalose for food applications, while Changyi Longchang manufactures trehalose as a core product for food and ingredient markets. The presence of multiple capable Chinese producers underscores the region's importance as both a manufacturing hub and a competitive pressure point on pricing and supply agility. The full report provides detailed corporate profiles, competitive positioning assessments, and strategic implication analyses for each key player, enabling clients to benchmark their own supplier relationships and identify potential partnership or substitution opportunities.
Regulatory and Industry Dynamics Shaping the Road Ahead
Trehalose's commercial expansion is being reinforced by a series of regulatory clarifications and industry-level developments that reduce uncertainty and broaden addressable use cases. Health Canada has formally notified Hayashibara International Inc. and Cargill, Inc. that it has no objection to the use of trehalose for human food applications, a determination that removes a potential barrier for Canadian market access and reinforces international regulatory alignment. Simultaneously, the pharmacopoeial landscape has consolidated around trehalose's role in high-specification pharmaceutical use. Pfanstiehl's trehalose is available in USP-NF, EP, and JP grades, reflecting the multi-jurisdictional compliance requirements of global biopharmaceutical supply chains. In parallel, Nagase Viita Co., Ltd., operating as Nagase Food Ingredients, continues to manufacture TREHA® via its proprietary enzymatic starch-conversion process, underscoring the importance of process innovation in maintaining quality consistency and cost efficiency.
Regulatory dynamics are not static, and procurement strategies must account for evolving food additive classifications, novel food notifications, and pharmacopoeial updates. Our report embeds these regulatory trajectories within the broader market dynamics section, illustrating how compliance pathways can create entry barriers, expand addressable markets, or shift competitive advantage among suppliers with differing certification portfolios.
Operational Content and Decision-Support Architecture
This market research report is designed as a decision-support instrument rather than a static data compilation. It integrates macroeconomic context, segmentation analysis, competitive profiling, and regulatory intelligence into a coherent narrative that supports actionable planning. The report content includes detailed volume and value analysis across the forecast horizon, decomposed by type, application, and region. It provides market concentration metrics and supplier share assessments that help clients evaluate bargaining power, supply risk, and partnership potential. It maps historical growth patterns against projected trajectories, enabling sensitivity analysis around demand shocks, raw material cost fluctuations, and regulatory changes.
The operational scope extends to application-specific usage patterns, formulation advantages, and technical requirements that distinguish one end-use vertical from another. For food and beverage teams, the report examines how trehalose functions as a moisture regulator, texture stabilizer, and flavor modulator, and where it can replace or complement existing ingredients without triggering label or cost penalties. For dietary supplement and nutraceutical strategists, the focus shifts to metabolic neutrality, stability in dry and liquid formats, and alignment with consumer-facing wellness narratives. For pharmaceutical and biotech decision-makers, the report addresses grade requirements, endotoxin control, cryopreservation performance, and the implications of pharmacopoeial compliance for supply chain qualification. For cosmetics and personal care developers, the analysis highlights humectant behavior, skin-barrier compatibility, and clean-label positioning in an increasingly crowded functional sugar landscape.
Beyond segmentation and application analysis, the report provides a structured view of market drivers, restraints, opportunities, and challenges. It evaluates the interplay between raw material availability, process technology maturity, regulatory clearance timelines, and end-market demand elasticity. It maps historical resilience against forward-looking risk factors, allowing procurement and strategy teams to stress-test their assumptions. All regional and application-level percentage splits, specific revenue figures by sub-segment, and granular supplier-level volume estimates are disclosed in full within the complete report. This deliberate depth ensures that clients can run their own scenario models, calibrate procurement timing, and identify the exact sub-markets where investment, reformulation, or supply diversification will generate the greatest incremental value.
Strategic Implications for 2026 and Beyond
For enterprise decision-makers, the trehalose market presents a rare combination of steady macro growth and segmented opportunity pockets. The overall 5.45 percent CAGR through 2032 signals that the market is expanding in a predictable, structurally supported manner, but predictability should not be mistaken for uniformity. The largest absolute opportunity resides in the food and beverage vertical, where trehalose's functional attributes align with clean-label reformulation, texture optimization, and shelf-life extension. The highest specification and margin potential resides in pharmaceutical and biopharmaceutical applications, where grade compliance, low-endotoxin performance, and batch reproducibility justify premium pricing and long-term supply agreements. The cosmetics and personal care segment offers a high-growth adjacency where trehalose's humectant and barrier-supporting properties can be leveraged in premium skincare, barrier repair formulations, and naturally derived ingredient narratives. Dietary supplements and nutraceuticals add a further layer of opportunity, particularly where trehalose can be positioned around cellular protection, stability, and metabolic benignity.
Regional strategy will be equally important. The leading regional markets each present distinct procurement profiles, regulatory frameworks, and supplier ecosystems. North American and European customers benefit from established distribution infrastructures and deep technical service capabilities among global suppliers, but they also face pricing and margin pressures from efficient Asian manufacturers. Asian Pacific markets offer volume growth and localized supply options, but they require careful navigation of quality assurance, export logistics, and application-specific technical support. Latin America and the Middle East and Africa, while smaller in current scale, are relevant for companies seeking geographic diversification, import substitution, or early entry into developing food and pharmaceutical manufacturing corridors. The complete report quantifies these regional dynamics and provides the sub-segment breakdowns necessary to prioritize investments by geography and application.
Competitive strategy should also account for the moderately concentrated supplier base. The top three and top five players hold significant revenue share, but the presence of multiple capable regional producers creates both collaboration and negotiation leverage. Procurement teams can use the market concentration data to assess supply security, benchmark pricing, and evaluate whether dual-sourcing or specification-tailored supplier portfolios are warranted. R&D and formulation teams can use the application and type segmentation to identify where powdered versus liquid formats are most cost-effective and where supplier technical documentation and regulatory support will accelerate time-to-market. Executive teams can use the forward-looking forecast to align capital expenditure, capacity planning, and partnership discussions with a market that is expanding but not inflating, allowing disciplined, evidence-based growth strategies.
Call to Strategic Engagement
The trehalose market is at an inflection point where functional necessity, regulatory clarity, and supplier maturity are converging to create durable growth across multiple verticals. Yet the precise magnitude of opportunity in each sub-segment, the exact regional value distribution, and the detailed supplier-level share allocations remain strategically sensitive information that can differentiate early movers from late followers. Our full market research report is built to provide that intelligence with analytical rigor, commercial relevance, and actionable structure.
This article has outlined the macro trajectory, segmentation logic, competitive architecture, and regulatory context that define the market's current shape and forward path. The complete report goes further, delivering the exact segmentation percentages, regional revenue breakdowns, application-level consumption splits, and detailed competitive profiles that enable precise procurement timing, portfolio prioritization, and risk calibration. For organizations that need to make 2026 sourcing decisions, evaluate reformulation options, assess supplier partnerships, or build long-range demand models through 2032, this research provides the evidentiary foundation required to move from assumption to confidence. We invite strategic leaders to access the complete report to unlock the full depth of market intelligence and translate structural growth into measurable commercial advantage.
For detailed analysis of this topic, please visit the official page: Trehalose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Lithium Metal Market Poised for 16% CAGR to Hit $7.29 Billion by 2032
By pmarketresearch, 2026-09-15
The Lithium Metal Market Outlook 2026: Strategic Intelligence for Next-Generation Energy Decisions
Executive Overview
The global energy transition is entering a decisive phase where material science and supply chain resilience determine competitive advantage. Lithium metal has emerged as a foundational enabler for high-energy-density storage systems, advanced alloys, and next-generation electrochemical applications. Our latest Lithium Metal Market research provides a comprehensive, forward-looking assessment of an industry experiencing structural acceleration. With a compound annual growth rate of 16.0 percent spanning the forecast horizon through 2032, the market trajectory reflects deepening integration across battery innovation, materials engineering, and regional supply chain reconfiguration. This article outlines the strategic rationale behind the study, highlights the analytical architecture, and demonstrates how enterprise leaders can convert macro-level intelligence into actionable 2026 planning.
Macro Trajectory and Market Scale
Historical performance from 2020 through 2025 illustrates a consistent expansion pattern, with revenue climbing from 1.5 billion USD to 2.6 billion USD. The acceleration observed in the base year establishes a strong foundation for the forecast period, during which valuations are projected to move from 3.04 billion USD in 2026 toward 7.29 billion USD by 2032. This scale of growth is not merely a function of incremental demand but reflects a broader technology shift toward lithium metal anodes, high-purity metallic inputs, and specialized alloy applications.
The market structure reveals meaningful concentration dynamics. Top-tier participants collectively account for a dominant share of revenue, indicating an industry where scale, process expertise, and supply chain control create durable barriers to entry. Yet concentration does not equate to stasis. Strategic partnerships, localized production initiatives, and novel refining pathways are actively reshaping competitive positioning. For decision-makers, the critical insight lies in recognizing how concentration interacts with innovation velocity: incumbents leverage manufacturing maturity while emerging players target niche performance requirements and regional supply chain independence.
Segmentation Landscape and Application Drivers
The Lithium Metal Market unfolds across distinct product forms and end-use categories. Ingots represent the dominant volume format, serving as the primary input for downstream processing and battery manufacturing. Powder and other specialized forms cater to increasingly precise electrochemical formulations, where particle morphology, purity thresholds, and surface characteristics directly influence cell performance. This structural split underscores a broader trend: customers are no longer purchasing commoditized material alone. They are procuring tailored material properties that support specific energy-density targets, thermal behavior profiles, and cycle-life requirements.
Lithium-Metal Secondary Battery Market
Application demand is heavily anchored by battery systems, which continue to command the largest share of market absorption. Alloys and other specialized applications provide meaningful supplementary vectors, supporting advanced material combinations, thermal management strategies, and specialized engineering use cases. Importantly, the relationship between application categories and growth is not linear. Battery advancement cycles, platform qualification timelines, and form-factor transitions introduce phased demand patterns that require granular planning. Our research captures these nuances by mapping application pathways to material specifications, manufacturing readiness, and regional procurement behavior without reducing the market to oversimplified share percentages.
Regional Dynamics and Supply Chain Reconfiguration
Geographically, the market reflects a diversified but unevenly distributed footprint. Asia Pacific anchors the largest portion of activity, reflecting dense manufacturing ecosystems, strong downstream demand, and rapidly scaling production capabilities. North America, Europe, Latin America, and the Middle East and Africa each contribute distinct strategic value, whether through localized supply chain initiatives, regulatory-driven procurement shifts, or specialized application clusters.
Regional analysis in this study is framed around operational realities rather than static share figures. Factors such as localized production investments, logistics constraints, material sourcing strategy, and regulatory alignment determine how demand translates into procurement decisions. The focus is on where capability is building, where dependency risks exist, and how companies can position themselves to access the right material streams under shifting trade and compliance conditions.
Recent Industry Developments and Strategic Signals
Recent operational milestones demonstrate how quickly the competitive landscape is evolving. In April 2025, a leading U.S. innovator initiated domestic production of battery-grade lithium-metal alloys and foils, establishing a fully localized, tariff-free supply chain using domestically produced alloys and sourced lithium metal. By November 2025, another vertically integrated player secured a Saudi patent covering its pure lithium metal production and lithium battery manufacturing technology, reinforcing the importance of intellectual property in advanced materials business models.
Moving into 2026,execution momentum continued. In January 2026, a sustainable refining company signed a multi-year material supply agreement for battery-grade lithium carbonate produced through its proprietary refining process, illustrating how recycling and refining innovation are being embedded directly into supply contracts. In February 2026, a composite anode materials developer and a battery technology partner formalized a memorandum of understanding to commercialize next-generation lithium-metal batteries, building on scale-up progress achieved during the prior year.
These developments share a common strategic theme: companies are reducing exposure to volatile intermediate markets by strengthening vertical integration, protecting process innovation, and securing supply agreements aligned with downstream qualification cycles. For enterprise planners, the implication is clear. Procurement strategy, partnership selection, and technology roadmapping must now account for a market where localized production, IP-protected processes, and closed-loop refining are becoming competitive differentiators.
Regulatory and Raw Material Context
Market behavior does not unfold in isolation from regulatory and commodity dynamics. Transportation compliance continues to shape logistics planning for lithium metal and lithium-ion batteries. As of January 2026, updated guidance introduced revised classification flowcharts, new test summaries, and modified state-of-charge requirements for packed equipment and lithium metal battery shipments. These changes affect packaging design, freight qualification, warehousing protocols, and cross-border shipment timelines. Firms that treat compliance as a static checklist risk operational friction; firms that integrate regulatory evolution into product launch planning and supply chain design gain predictability.
Raw material pricing also remains a relevant planning input. Market data from mid-2026 indicates lithium carbonate pricing declining to approximately 163,000 CNY per ton, reflecting a month-over-month contraction. While lithium metal markets are not perfectly synchronized with carbonate pricing, such movements influence input cost expectations, procurement timing, contract negotiation posture, and internal investment hurdle rates. The relationship is nuanced: different product forms, purity specifications, and supply routes create varying degrees of exposure. Our research addresses these sensitivities by examining how pricing trends interact with material grade requirements, regional sourcing options, and long-term contract structures.
Competitive Landscape: Differentiated Capabilities and Strategic Positioning
The competitive field spans established multinationals, specialty materials innovators, and vertically integrated challengers. Each participant is shaping the market through a distinct value proposition.
- Albemarle Corporation emphasizes ultra-thin lithium metal anodes designed for high-energy-density solid-state and lithium-metal battery platforms, positioning process precision as a performance enabler.
- Ganfeng Lithium Group Co., Ltd. focuses on high-purity lithium metal produced via oil-free vacuum melting and low-temperature vacuum distillation, reflecting an emphasis on purity control and process discipline.
- Pure Lithium Corporation pursues vertically integrated pure lithium metal anodes and batteries using brine-to-battery technology, linking upstream sourcing directly to downstream cell production.
- Lyten Inc. targets battery-grade lithium-metal alloys and foils for U.S.-localized lithium-sulfur batteries, aligning material development with regional supply chain objectives.
- Aqua Metals, Inc. contributes battery-grade lithium carbonate and nickel metal through its AquaRefining process, integrating sustainable recycling and refining into the material supply chain.
- Soelect advances lithium-metal composite anode materials for advanced high-energy-density batteries, focusing on material formulations that support next-generation cell architectures.
- Elevated Materials develops ultra-thin lithium metal films for commercial battery programs, addressing the growing demand for precision-format metallic inputs.
- Cuberg concentrates on lithium-metal cell technology for ultra-safe, high-energy-density modules in aviation and vertical takeoff and landing applications, linking material performance to demanding transport and mobility requirements.
The strategic takeaway is not simply that competition is intense, but that competition is multidimensional. Some players compete on purity and process control. Others compete on integration, localization, recycling, or application-specific cell architecture. As a result, procurement teams and technology strategists must evaluate partners against more than volume or price. Material consistency, qualification support, IP positioning, and supply continuity under regulatory change are equally relevant.
What the Report Delivers: Operational Intelligence for 2026 Planning
This study is designed as a decision-support instrument, not a broad overview. It translates market-scale data into operational context by mapping growth vectors to the practical questions enterprise teams face when planning for 2026 and beyond. The report includes analysis covering demand drivers by application pathway, product-form preferences and their manufacturing implications, regional capability building and procurement relevance, and competitive positioning based on technology readiness, integration strategy, and supply chain design.
Beyond structural assessment, the report integrates development tracking that connects corporate milestones to market consequences. Patent grants, localized production launches, multi-year supply agreements, and commercialization partnerships are examined for what they reveal about capability maturity, supply chain directionality, and the pace of market entry. Regulatory updates and raw material pricing movements are incorporated where they affect planning assumptions, with attention to how compliance shifts influence logistics and how input cost dynamics shape negotiation and sourcing strategy.
The objective is to give strategy, procurement, and technology leaders a coherent framework for evaluating opportunity, risk, and timing. Rather than leaving decision-makers with isolated figures, the study provides the connective tissue needed to interpret growth in terms of actionable market behavior: which material specifications are gaining relevance, where regional supply chain shifts are accelerating, how concentration affects access and negotiation leverage, and which development patterns indicate near-term capacity or partnership opportunities.
Lithium Metal Market
Strategic Implications for 2026 Enterprise Decisions
For organizations operating in or adjacent to the Lithium Metal Market, the 2026 planning cycle should be informed by three overarching priorities. First, align material sourcing with technology roadmaps. As battery platforms and alloy formulations continue to advance, procurement specifications increasingly need to reflect performance-sensitive characteristics rather than generic commodity procurement.
Second, incorporate regulatory and logistics evolution into product and supply planning. Updated transportation guidance, classification requirements, and state-of-charge constraints affect launch timing, packaging design, and distribution strategy. Companies that build compliance-aware supply planning into their operational cadence reduce execution risk.
Third, evaluate partnership and investment choices through the lens of integration and differentiation. Vertical integration, localized production, sustainable refining, and IP-protected processing are no longer peripheral initiatives. They are becoming core elements of supply reliability and competitive positioning. The market concentration pattern reinforces the importance of selecting partners with credible scale, process control, and continuity strategy, while the emergence of specialized innovators signals where tailored solutions and application-specific alliances may create advantage.
Conclusion
The Lithium Metal Market is moving with sufficient velocity and structural complexity that broad narratives are no longer sufficient for high-stakes planning. Growth, concentration, regional reconfiguration, regulatory updates, and corporate execution are interacting in ways that require a more disciplined intelligence framework. Our research provides that framework by linking macro trajectory to operational relevance, translating recent developments into strategic signals, and identifying the decision points that matter most for 2026.
For leaders who need the full analytical breakdown—detailed segmentation interpretation, regional capability mapping, competitive profiling, regulatory impact assessment, and development tracking with market implications—the complete report offers the depth required to convert insight into action. The market is expanding, differentiating, and reorganizing around integration, purity, localization, and application specificity. Access the full study to ground your next planning cycle in comprehensive, decision-ready intelligence.
For detailed analysis of this topic, please visit the official page: Lithium Metal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Saw Wire Market to Reach $344.8M by 2032, Growing at 6.98% CAGR from 2025
By pmarketresearch, 2026-09-15
Strategic Intelligence in the Saw Wire Market: Navigating Growth Trajectories Through 2032
The industrial landscape of precision cutting and material processing is undergoing a significant transformation. As manufacturing tolerances tighten and the demand for high-quality semiconductors and construction materials escalates, the saw wire market has emerged as a critical enabler of industrial efficiency. For executive leaders and strategic planners, understanding the nuances of this sector is no longer optional; it is a prerequisite for sustainable growth.
PW Consulting is pleased to introduce our latest comprehensive market research study focused on the Saw Wire Market. This report is designed not merely as a data repository, but as a strategic tool for decision-making in 2026 and beyond. By analyzing historical performance from 2020 through 2025 and projecting forecasts until 2032, we provide a clear lens through which stakeholders can evaluate opportunities, risks, and competitive positioning.
Market Trajectory and Growth Dynamics
The historical data indicates a robust expansion phase for the saw wire industry. Between 2020 and 2025, the market demonstrated consistent resilience and upward momentum, overcoming global supply chain disruptions and shifting economic conditions. This historical foundation sets the stage for the forecast period spanning 2026 to 2032.
Our analysis projects a Compound Annual Growth Rate (CAGR) of approximately 6.98 percent during the forecast period. This growth trajectory suggests that the market will evolve from a valuation of roughly 235.21 million USD in 2026 to nearly 344.8 million USD by 2032. For investors and corporate strategists, this implies a sustained demand environment where capacity expansion and technological innovation will be key differentiators. The steady climb in revenue underscores the material's integral role in high-value industries such as semiconductor manufacturing and advanced construction.
However, raw numbers only tell part of the story. The strategic value lies in understanding the velocity of this growth across different vectors. Our research digs into the underlying drivers that will sustain this CAGR, identifying where capital allocation will yield the highest returns. Leaders who grasp the timing of these demand waves will be better positioned to secure supply chains and optimize production schedules.
Report Scope and Operational Content
To support nuanced decision-making, this report offers a granular examination of the market ecosystem. We have structured the research to address the specific informational needs of procurement officers, product managers, and investment analysts. The study moves beyond top-line estimates to explore the mechanics of market behavior.
Key components of the analysis include:
- Historical Baseline Analysis: A detailed review of market performance from 2020 to 2025, establishing the baseline against which future growth is measured. This section contextualizes the recent recovery and stabilization phases following earlier global disruptions.
- Forecast Modeling: Projections extending to 2032 that account for varying economic scenarios. This allows stakeholders to stress-test their strategies against potential shifts in demand or regulatory environments.
- Segmentation Deep Dives: While maintaining confidentiality on specific proprietary splits, the report analyzes the structural composition of the market. We examine the relative weight of different material types and industrial applications, highlighting which segments are driving the bulk of revenue generation.
- Regional Performance Overview: The study assesses market attractiveness across major geographic zones. We evaluate how local industrial policies, infrastructure development, and manufacturing hubs influence regional revenue contributions without disclosing specific localized percentage shares.
- Competitive Intelligence: A thorough profiling of key market participants, analyzing their strategic moves, product portfolios, and geographic footprints.
By integrating these elements, the report serves as a single source of truth for stakeholders who need to align their internal strategies with external market realities.
Competitive Landscape and Corporate Strategies
The saw wire market is characterized by a mix of specialized manufacturers and diversified industrial giants. Our research identifies a competitive environment where innovation in diamond wire technology and steel composition is paramount. The market concentration indicates a fragmented yet strategically clustered environment, with the top players holding significant but not absolute sway over market direction.
Worldwide Wire Saw Market
We have identified several core enterprises that define the current competitive landscape. Firms like Well Diamond Wire Saws SA, based in Switzerland, have long established reputations for precision stainless steel wires and cutting technology since 1974. Their focus on stone and concrete applications highlights the enduring importance of construction and material processing sectors. Similarly, Asahi Diamond Industrial Co. from Japan represents the high-tech end of the spectrum, leading production of diamond wires for semiconductor wafer slicing and solar photovoltaic industries.
Other significant players include Noritake Co. Limited, also in Japan, which specializes in diamond wires and consumables for industrial sawing, and SOMOS IWT in the United States, which targets semiconductor and crystal precision applications. European presence is maintained by companies like Husqvarna Construction in Sweden, supplying premium diamond wires for concrete and marble, and Diamond WireTec, offering coil and loop options across various materials.
The United States hosts a diverse range of specialists, including MTI, known for electroplated diamond wires for scientific cutting, and Princeton Scientific Corp, focusing on lab and professional settings. Taiwanese manufacturer Ensoll Tools contributes with diamond wire saw machines, while France-based Thermocompact provides industrial diamond wire saws for professional applications. Additionally, Wire Saw Solutions Group acts as a crucial distributor and service provider, facilitating access to brands like Well Diamond.
Recent developments underscore the dynamic nature of this competition. In June 2025, Schwing introduced the MDS 5034 mobile diamond wire saw, specifically designed for on-site cutting of large natural-stone blocks in mining applications. This launch signals a push towards mobility and on-site efficiency in the mining sector. Furthermore, in late 2025, Zhejiang Jingsheng Mechanical and Electrical launched a diamond line project focused on expansion into semiconductor material and equipment manufacturing, indicating a strategic pivot towards high-growth tech sectors.
Saw Wire Market
Understanding the moves of these key companies provides valuable insight into where the industry is heading. Their investments in R and D, capacity expansion, and geographic reach serve as leading indicators for market trends. Our report analyzes these strategic maneuvers to help clients anticipate competitor actions and identify potential partnership or acquisition opportunities.
Raw Material and Regulatory Headwinds
Strategic planning in the saw wire market must account for external forces that influence cost structures and operational feasibility. Raw material volatility remains a critical concern. Recent data indicates that hot-rolled coil steel prices reached approximately 1,040 USD per ton in the week of April 2026, representing a notable increase from 905 USD per ton in the equivalent week of 2025. This upward pressure on steel costs directly impacts the production economics of wire saws.
Compounding this issue, the Producer Price Index for carbon steel wire drawing rose to 299.798 in April 2026 from 289.227 in February 2026. These inflationary trends suggest that manufacturers may need to adjust pricing strategies or invest in efficiency improvements to maintain margins.
Regulatory dynamics are equally influential. China's General Administration of Customs introduced an export license management system for steel products under at least 100 HS codes, effective January 1, 2026. This move could alter global supply chains and availability of raw materials. In Europe, the European Chemicals Agency updated the REACH SVHC candidate list to 253 substances in February 2026, impacting chemical and material compliance for wire production. Additionally, EU Regulation (EU) 2026/261 on phasing out Russian natural gas imports entered into force in January 2026, affecting global energy-related material supply chains.
These factors create a complex operating environment. Companies that proactively adjust their supply chain strategies and compliance frameworks will be better equipped to navigate these headwinds. Our report details how these regulatory and cost factors intersect with market demand to shape overall profitability.
Strategic Implications for 2026 Decision Makers
For leaders operating in 2026, the Saw Wire Market presents a landscape of calculated opportunity. The projected growth to 344.8 million USD by 2032 offers a compelling case for investment, but success will depend on precise execution. Strategic priorities should include securing stable raw material sources amidst price volatility, aligning product development with high-growth segments like semiconductor manufacturing, and monitoring regulatory shifts in key regions like China and the EU.
The fragmentation of the competitive landscape, with a CR3 of 24.6 percent and CR5 of 26.2 percent, suggests that there is room for consolidation or for niche players to capture significant value through specialization. Companies that can offer superior cutting technology or specialized consumables for precision applications will likely command premium positioning.
Furthermore, understanding the regional nuances without relying solely on aggregate numbers is crucial. Whether it is the industrial demand in Asia Pacific, the established infrastructure in North America, or the emerging opportunities in Latin America and the Middle East, each region presents unique challenges and rewards. Our report provides the contextual depth needed to evaluate these regions effectively.
Conclusion
The Saw Wire Market is at an inflection point where industrial demand, technological innovation, and regulatory complexity converge. PW Consulting's latest market research offers the depth and clarity required to navigate this environment. By leveraging our detailed analysis of market size, growth rates, competitive moves, and external dynamics, stakeholders can make informed decisions that drive long-term value.
We invite you to explore the full findings of this study to gain the comprehensive intelligence necessary for strategic planning in 2026 and beyond. The complete report contains the specific segmentation data, detailed company profiles, and granular regional analysis needed to finalize your strategic roadmap.
For detailed analysis of this topic, please visit the official page: Saw Wire Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Eco-friendly Beneficiation Reagents Market Poised to Expand at a 6.5% CAGR During 2026–2032
By pmarketresearch, 2026-08-18
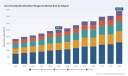
PW Consulting: Strategic Brief — Eco-friendly Beneficiation Reagents Market (2026 Outlook)
PW Consulting today publishes an executive-level briefing that crystallizes the strategic implications of our full market research report on the Eco-friendly Beneficiation Reagents Market. Built for C-suite decision-makers, sustainability leads, and M&A teams, this briefing synthesizes the dynamics that will shape procurement, R&D, and capital allocation choices in 2026 and beyond — while preserving the proprietary, granular intelligence contained in the full report.
Worldwide Big Rig Trucks Market
Executive snapshot: why 2026 matters
The eco-friendly beneficiation reagents market is moving from niche pilot programs to industrial-scale deployment. Our analysis shows the market has expanded materially over the 2020–2025 historical window and enters the 2026–2032 forecast period on a steady growth trajectory. With a compound annual growth rate (CAGR) of 6.5% across the forecast period and market value growth from the low‑single‑billion range in 2020 to a mid‑billion valuation in 2025, the segment is projected to approach the high end of the mid‑single‑billion range by 2032. This growth is sustained by tightening environmental regulation, corporate ESG commitments, and commercially viable bio-based chemistries that reduce aquatic toxicity and lifecycle impacts.
Corded Electric Chainsaws Market
What the full report delivers — practical intelligence for decision makers
- Market sizing and scenario modelling (base year 2025; forecast 2026–2032) with upside and downside scenarios tied to regulatory timelines and feedstock availability.
- A decision-ready regulatory matrix that maps jurisdictional discharge criteria, expected EHS compliance windows, and procurement risk for operators and reagent suppliers.
- Supplier and product playbooks, including techno‑economic assessments, dose-rate benchmarking, and sustainability scoring for formulation classes (collectors, frothers, depressants, pH modifiers).
- Five non-prescriptive, implementable GTM (go-to-market) strategies for incumbent chemical players and new entrants: licensing & co-development, joint piloting with miners, regional distribution partnerships, targeted bolt-on M&A, and customer-financed scale-up models.
- Procurement templates and contracting clauses to de‑risk supply, ensure performance guarantees during trials, and protect environmental liabilities.
- Case studies and pilot metrics demonstrating yield lift, reagent dosing profiles, and tailings‑water chemistry outcomes across representative ore types.
- Feedstock sourcing playbook for bio‑based inputs (lignin streams, fatty acids, sophorolipids), including upstream supplier diligence and processing constraints that affect reagent cost and supply security.
Market structure and competitive tension
The eco-friendly reagents market is neither a classic oligopoly nor a fully fragmented cottage industry. Concentration metrics indicate a market where leading chemical manufacturers hold meaningful influence but do not command majority control: the top three firms account for just over 30% of market activity, and the top five do not exceed half of the market. This mix produces robust competitive tension: global incumbents leverage breadth and distribution; specialized challengers advance differentiated low‑toxicity chemistries and rapid piloting.
Electromagnetic and Optical Navigation System Market
Strategically, this structure creates three viable routes for buyers and investors in 2026:
- Partner with incumbents that can scale production, navigate regulatory approvals, and offer integrated supply chain solutions.
- Pilot with specialized innovators to capture material downstream benefits in recovery and lifecycle impact, while managing scale-up and supply risk.
- Pursue selective M&A to acquire unique, validated chemistries or feedstock supply chains (e.g., lignin processors, biosurfactant producers) that accelerate time to market.
Competitive landscape — positioning of core players
Our report profiles industry leaders and disruptive specialists to show how product portfolios, R&D pipelines, and commercialization models map to customer needs. Key observations:
- Nouryon (Amsterdam) positions sustainability as a product development axis, progressively removing legacy ingredients and advancing lower‑impact flotation formulations with strong industrial scaling capability.
- Clariant (Muttenz) leverages targeted collector and frother platforms to address coarse‑particle flotation and higher‑energy ores, actively showcasing energy‑efficiency gains at industry forums.
- Syensqo (formerly Solvay, Brussels) combines legacy flotation chemistry know‑how with repositioned formulations targeted at base and precious metals, promoting reduced environmental profiles versus traditional xanthates.
- BASF (Ludwigshafen) focuses on reduced dose rates and improved safety (GHS) profiles, seeking to substitute or complement established reagents in phosphate and industrial mineral flowsheets.
- Arkema / ArrMaz (Colombes) and other specialty players target select minerals (phosphate, silica, glass sand) with customized depressant and collector systems emphasizing selectivity and recovery.
- Regional and technology challengers (e.g., CN‑free cyanide alternatives from Yantai, biosurfactant specialists like Locus Mining Solutions in the U.S., and several China‑based formulators) are moving from lab validation into field trials, offering alternatives to legacy toxic chemistries in precious metals and low‑grade tailings contexts.
These profiles in the full report include vendor scorecards that evaluate technical maturity, scale capability, environmental profile, and commercial terms — essential inputs for procurement and M&A diligence.
Regulatory & raw material drivers: vectors of disruption
Two systemic forces are accelerating adoption and reshaping vendor economics:
- Regulation and ESG mandates. Tighter discharge limits, chemical safety frameworks in major jurisdictions (including recent EU activity), and corporate net‑zero/value‑chain commitments are shortening the runway for legacy, high‑toxicity chemistries. Firms that proactively align product dossiers to regulatory expectations reduce time‑to‑adoption and procurement friction.
- Feedstock innovation. Lignin‑based collectors and fatty‑acid (e.g., TOFA) derivatives, plus renewable biosurfactants (sophorolipids), are emerging as feedstocks that deliver high "green" classification scores — combining biodegradability, renewable origin, and safer toxicological profiles. However, commercial-scale feedstock supply chains require upstream coordination (pulp/paper, biodiesel, forestry residues), which we map in the report.
Recent developments underscore these dynamics: Clariant showcased energy‑efficient coarse flotation reagents at a major industry conference; BASF launched a high‑performance industrial minerals flotation reagent aligned to sustainability objectives; and an academic‑industry review introduced a taxonomy for green flotation reagents that helps standardize procurement scoring. Together, these events signal accelerating technology maturation and market readiness.
Risk framework and deployment playbook for 2026
Adopting eco‑friendly reagents at scale is not a simple substitution — it requires an integrated program that addresses technical, commercial, and regulatory risk. The full report provides a four‑layer risk framework and an associated deployment playbook that includes:
- Technical gate criteria: representative bench and pilot metrics (reagent dose curve, selectivity, recovery delta vs baseline) and decision thresholds for scale‑up.
- Commercial safeguards: performance‑linked contracts, staged purchasing, and inventory buffers for new feedstock supply lines.
- Regulatory contingency planning: submission templates, ecotoxicity testing pathways, and timelines aligned with expected permitting windows.
- Stakeholder engagement tactics: community communications templates, third‑party verification options, and sustainability reporting alignment.
Investment and M&A implications
For corporate development and private equity teams, the landscape presents three attractive strategies that we quantify and stress‑test in the report (summary only here): 1) bolt‑on acquisitions to secure unique bio‑feedstock supply; 2) minority growth investments into scale‑ready reagent innovators with locked‑in pilot agreements; and 3) vertical deals that integrate reagent manufacture with water‑treatment services to realize lifecycle value. The market concentration metrics point to continued room for consolidators that can combine technical IP with distribution reach.
How to use this briefing in 2026 planning cycles
- Procurement heads: use the supplier scorecards and contracting templates to run staged trials this year and negotiate performance‑linked pricing for 2027 rollouts.
- R&D chiefs: prioritize partnerships with feedstock suppliers (lignin processors, biosurfactant fermenters) and deploy techno‑economic pilots that track both recovery and life cycle carbon impact.
- Investors and corporate development: target assets that solve feedstock scalability or offer validated field performance against sulfide and oxide ores to minimize technical risk.
Next steps and access to the full report
This briefing deliberately highlights strategic takeaways while omitting the granular segmentation and proprietary vendor scoring that support transaction‑level decisions. The full PW Consulting report contains the detailed regional and application segmentation, supplier scorecards, scenario financials, and implementation toolkits you need to execute in 2026. To access the complete analysis, model files, and workshop options for executive teams, please visit our report page or contact PW Consulting to schedule a tailored briefing session.
PW Consulting is prepared to support executive workshops, pilot selection and oversight, procurement negotiations, and M&A diligence — helping clients convert the macro momentum behind eco‑friendly beneficiation reagents into measurable operational and sustainability gains.
For detailed analysis of this topic, please visit the official page: Eco-friendly Beneficiation Reagents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com