

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Steel Grating Market Hits $227M in 2025, Projects 3.61% CAGR Through 2032

Strategic Insights into the Global Steel Grating Market: Navigating Growth, Consolidation, and Regulatory Shifts Through 2032
Executive Overview: Positioning for the 2026 Decision Landscape
The global steel grating industry stands at a pivotal inflection point as enterprises map out capital allocation and supply chain strategies for the remainder of the decade. Building on a historical trajectory that saw the market expand from approximately 183.8 million USD in 2020 to an estimated 227.0 million USD in 2025, the sector is now projected to advance toward a 2026 baseline of 230.47 million USD and continue its measured ascent through 2032. Anchored by a forecast compound annual growth rate of 3.61 percent across the 2026 to 2032 horizon, the market narrative is no longer defined by uniform expansion. Instead, it is shaped by structural consolidation, evolving trade defenses, raw material volatility, and the operational imperative to align product portfolios with high-demand access infrastructure applications.
This analysis introduces PW Consulting’s newly released Steel Grating Market research, a decision-grade intelligence asset designed to help executives, procurement leaders, and strategic planners convert macroeconomic signals into actionable advantage. Rather than presenting a static snapshot, the study maps the interplay between capacity realignment, competitive concentration, and regional demand rhythms, equipping organizations with the foresight needed to secure margins, mitigate supply risk, and capture share in the segments that will define the next growth cycle.
Market Trajectory and Structural Forces Reshaping the Sector
The steel grating market has demonstrated resilient, if uneven, growth through the 2020 to 2025 period, with annual revenue climbing from 190.26 million USD in 2021 to 204.57 million USD in 2022 and further to 211.6 million USD in 2024. The acceleration observed in 2025, reaching 227.0 million USD, reflects a confluence of renewed industrial construction activity, sustained infrastructure maintenance spending, and the ongoing modernization of access platforms, walkways, and safety enclosures across both mature and emerging industrial corridors.
Looking forward, the 2026 to 2032 forecast period is expected to deliver incremental but strategically meaningful gains. Revenue is projected to rise from the 2026 baseline of 230.47 million USD to 249.14 million USD in 2027, 255.83 million USD in 2028, and 256.74 million USD in 2029, before continuing upward to 263.57 million USD in 2030, 289.39 million USD in 2031, and stabilizing at 289.39 million USD in 2032. The trajectory underscores a market that is broadening its addressable base rather than simply inflating existing volumes, with growth increasingly contingent on regional capacity deployment, product mix optimization, and the ability to navigate input cost cycles.
Several structural forces will determine which organizations convert this trajectory into profitability. Raw material fluctuations, particularly in carbon steel pricing, have repeatedly compressed manufacturing margins and forced producers to refine hedging strategies, forward contracting, and inventory management. At the same time, non-raw material input costs, including labor and freight, continue to escalate, compounding the pressure on grating manufacturers beyond the initial steel price shocks. On the regulatory front, the United States International Trade Commission instituted five-year reviews for steel grating from China beginning May 1, 2026, to assess whether dumping or subsidization continues and whether duty extensions remain warranted. This review introduces a renewed layer of trade policy uncertainty that can reshape import viability, domestic pricing dynamics, and sourcing strategies for North American buyers.
Environmental oversight is also recalibrating upstream conditions. The EPA finalized amendments to the National Emission Standards for Hazardous Air Pollutants concerning taconite iron ore processing in March 2024, a development that indirectly influences steel production feedstock pathways and, by extension, the cost and availability assumptions that flow through the grating value chain. Together, these dynamics create a market environment where operational agility, regulatory literacy, and procurement sophistication are no longer optional capabilities—they are competitive prerequisites.
Competitive Arena: Consolidation, Capacity, and the Convergence of Global Players
The steel grating competitive landscape is characterized by a moderately concentrated structure in which scale, fabrication expertise, and geographic footprint increasingly determine bargaining power. The market’s top three competitors hold an estimated 35.0 percent combined share, while the top five extend to approximately 55.0 percent, signaling that while fragmentation persists in regional and specialty niches, the center of gravity is shifting toward organizations that can integrate production, distribution, and engineering capabilities across broader territories.
Several established manufacturers illustrate the strategic postures shaping the market. Nucor Corporation, headquartered in Charlotte, North Carolina, produces steel bar grating through its Vulcraft and Verco divisions, maintaining an annual capacity of roughly 50,000 tons and offering standard, heavy-duty, and custom-fabricated products that serve diverse industrial requirements. IKG, operating across the United States and Mexico with more than a century of expertise, has long been recognized for pressure-locked bar grating and safety flooring and access infrastructure, supporting a full product line that includes pressure-locked and anti-slip solutions. Ohio Gratings, Inc., based in Canton, Ohio, specializes in the design, manufacturing, and custom fabrication of metal bar grating using carbon steel, stainless steel, and aluminum, and stands as the largest privately owned industrial and commercial grating provider in the United States. AMICO, the Alabama Metal Industries Corporation, continues to supply bar grating manufactured in the USA for industrial applications while expanding its catalog to encompass common bar grating items that align with high-volume procurement needs.
In Europe, JK TECHNIC, based in Sarreguemines, France, manufactures pressed gratings, electro-forged grating, and products tailored for stair treads, platforms, and industrial applications, reinforcing the technical differentiation that European producers bring to specification-driven projects. Meiser, operating as Gebrüder Meiser GmbH in Germany, is a leading steel grating manufacturer focused on high-grade products and surface refinement, including pickling, and maintains international reach through subsidiaries such as Meiser Gratings Inc. in the United States.
The competitive picture was substantially altered in early 2026 when IKG was acquired by a joint venture of Meiser and Dutco from KPS Capital Partners, a transaction that consolidated combined brands and capacity to form what is now regarded as the world’s largest grating manufacturer. This move signals a broader industry trend: capacity integration and brand convergence are accelerating as firms seek to capture economies of scale, widen geographic coverage, and strengthen their ability to serve multi-region engineering, procurement, and construction programs. At the same time, the USITC’s ongoing five-year review of Chinese steel grating introduces a regulatory variable that could reweight the competitive balance between domestic and import-dependent supply bases, particularly for buyers in North America who must weigh price competitiveness against duty exposure and supply reliability.
Structural Steel Market
Demand Architecture: Applications, Product Types, and the Regional Imperative
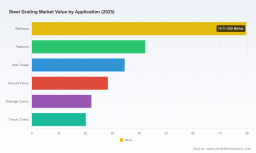
Understanding where demand concentrates is essential for prioritizing sales coverage, production scheduling, and inventory positioning. Walkways remain the most substantial application segment, reflecting the persistent need for durable, slip-resistant access infrastructure in industrial facilities, energy sites, wastewater operations, and commercial environments. Platforms represent another major demand pillar, driven by the requirement for safe, load-bearing work surfaces around processing equipment, storage systems, and elevated operational zones. Stair treads continue to hold significance as building and industrial codes prioritize both structural integrity and personnel safety, while security fences and drainage covers highlight the market’s dual role in protecting assets and managing site infrastructure. Trench covers round out the application landscape by serving utility access, roadways, and facility ground-level protection needs.
On the product side, carbon steel grating commands the largest share of the type segmentation, a reflection of its balance between structural performance, cost efficiency, and broad applicability across standard industrial installations. Stainless steel grating occupies a strategically important position for environments where corrosion resistance, hygiene, or extended service life under aggressive conditions are non-negotiable. Mild steel grating contributes to the portfolio’s versatility, particularly where lightweight or cost-sensitive structural access solutions are specified. The interplay among these product families is not static; it shifts with project specifications, lifecycle cost evaluations, and the relative pricing of base metals and finishing processes.
Regionally, the demand map reveals a pronounced concentration in Asia Pacific, where ongoing industrialization, infrastructure build-out, and expansive construction activity continue to anchor a large portion of global volume. North America maintains a significant and sophisticated demand base, shaped by industrial maintenance, energy sector activity, and an active trade policy environment that influences sourcing decisions. Europe contributes a substantial and technically discerning market, with sustained requirements in manufacturing, utilities, and specialty industrial installations. Latin America and the Middle East and Africa, while smaller in absolute terms, represent high-potential regions where economic activity, urbanization, and facility modernization can generate outsized growth when supported by reliable supply and localized service capabilities. For organizations operating across these territories, the strategic challenge is to align production and distribution networks with regional demand rhythms without overcommitting capacity to any single geography at the expense of agility elsewhere.
What the Research Delivers: A Decision-Grade Intelligence Framework
PW Consulting’s Steel Grating Market study is structured to move beyond headline figures and equip decision-makers with a practical, scenario-ready view of the market. The report integrates historical performance from 2020 through 2025 with a detailed 2026 to 2032 forecast, providing a continuous timeline that supports both near-term planning and long-range capital modeling. It examines the market through the lenses of region, product type, and application, while maintaining a deliberate focus on the interactions among these dimensions rather than treating them in isolation.
The analysis maps the competitive landscape with attention to manufacturer capabilities, capacity positioning, and the strategic implications of recent consolidation. It contextualizes raw material volatility and labor and freight cost pressure within margin and pricing dynamics, offering a structured way to evaluate how input cost cycles may influence supplier behavior, contract terms, and procurement timing. Trade and regulatory developments are assessed for their potential to alter import availability, domestic pricing, and regional sourcing preferences, with particular attention to the implications of the USITC’s five-year review and the EPA’s taconite-related amendments. The study also explores the demand hierarchy across walkways, platforms, stair treads, security fences, drainage covers, and trench covers, helping buyers and suppliers anticipate where specification requirements, service expectations, and volume concentration are likely to intensify.
Throughout, the research is designed to answer the questions that executives and planners actually face: where will growth concentrate, which product and application combinations offer the strongest margin opportunity, how will consolidation and trade scrutiny reshape supply options, and what procurement or production adjustments will best insulate an organization from cost and availability shocks. By linking market structure to operational decision points, the report enables users to test strategies against a range of plausible futures rather than relying on a single static assumption.
Strategic Implications for 2026 and the Road to 2032
As organizations enter 2026, the steel grating market rewards those who can simultaneously optimize for cost discipline, supply resilience, and segment-specific demand. The forecast trajectory suggests that growth will continue, but the value capture will increasingly depend on execution quality: aligning product mix with specification preferences, managing input cost exposure through disciplined procurement and inventory design, and positioning sales and service footprints where regional demand is most likely to expand. The recent consolidation exemplified by the formation of the world’s largest grating manufacturer through the IKG, Meiser, and Dutco joint venture illustrates the scale and integration advantages that are becoming more decisive, while the USITC review underscores the importance of monitoring trade policy as a live variable in sourcing and pricing plans.
For manufacturers, the imperative is to refine capacity utilization, strengthen differentiation through fabrication expertise and surface treatment capabilities, and build supply arrangements that can withstand raw material and freight fluctuations. For buyers and specifiers, the opportunity lies in leveraging a clearer view of competitive concentration, regional demand patterns, and regulatory risk to negotiate more effectively, diversify supply where prudent, and align specifications with total cost of ownership rather than unit price alone. In both cases, the ability to act on timely, granular intelligence will separate organizations that merely participate in the market from those that shape its outcomes.
Steel Grating Market
Access the Full Intelligence: Secure Your Strategic Edge
The overview presented here is intentionally a strategic preview. The full PW Consulting Steel Grating Market research unlocks the detailed segmentation analysis, regional demand distribution, product-type and application-level volume structures, competitor positioning, and forecast scenarios that executives need to make confident 2026 decisions and set resilient plans through 2032. To obtain the complete dataset, competitive profiles, regulatory impact assessment, and actionable recommendations, request the full report through the source page and equip your team with the intelligence required to navigate this evolving market with precision.
For detailed analysis of this topic, please visit the official page: Steel Grating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com