

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Eco-friendly Beneficiation Reagents Market Poised to Expand at a 6.5% CAGR During 2026–2032

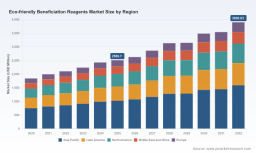
PW Consulting: Strategic Brief — Eco-friendly Beneficiation Reagents Market (2026 Outlook)
PW Consulting today publishes an executive-level briefing that crystallizes the strategic implications of our full market research report on the Eco-friendly Beneficiation Reagents Market. Built for C-suite decision-makers, sustainability leads, and M&A teams, this briefing synthesizes the dynamics that will shape procurement, R&D, and capital allocation choices in 2026 and beyond — while preserving the proprietary, granular intelligence contained in the full report.
Worldwide Big Rig Trucks Market
Executive snapshot: why 2026 matters
The eco-friendly beneficiation reagents market is moving from niche pilot programs to industrial-scale deployment. Our analysis shows the market has expanded materially over the 2020–2025 historical window and enters the 2026–2032 forecast period on a steady growth trajectory. With a compound annual growth rate (CAGR) of 6.5% across the forecast period and market value growth from the low‑single‑billion range in 2020 to a mid‑billion valuation in 2025, the segment is projected to approach the high end of the mid‑single‑billion range by 2032. This growth is sustained by tightening environmental regulation, corporate ESG commitments, and commercially viable bio-based chemistries that reduce aquatic toxicity and lifecycle impacts.
Corded Electric Chainsaws Market
What the full report delivers — practical intelligence for decision makers
- Market sizing and scenario modelling (base year 2025; forecast 2026–2032) with upside and downside scenarios tied to regulatory timelines and feedstock availability.
- A decision-ready regulatory matrix that maps jurisdictional discharge criteria, expected EHS compliance windows, and procurement risk for operators and reagent suppliers.
- Supplier and product playbooks, including techno‑economic assessments, dose-rate benchmarking, and sustainability scoring for formulation classes (collectors, frothers, depressants, pH modifiers).
- Five non-prescriptive, implementable GTM (go-to-market) strategies for incumbent chemical players and new entrants: licensing & co-development, joint piloting with miners, regional distribution partnerships, targeted bolt-on M&A, and customer-financed scale-up models.
- Procurement templates and contracting clauses to de‑risk supply, ensure performance guarantees during trials, and protect environmental liabilities.
- Case studies and pilot metrics demonstrating yield lift, reagent dosing profiles, and tailings‑water chemistry outcomes across representative ore types.
- Feedstock sourcing playbook for bio‑based inputs (lignin streams, fatty acids, sophorolipids), including upstream supplier diligence and processing constraints that affect reagent cost and supply security.
Market structure and competitive tension
The eco-friendly reagents market is neither a classic oligopoly nor a fully fragmented cottage industry. Concentration metrics indicate a market where leading chemical manufacturers hold meaningful influence but do not command majority control: the top three firms account for just over 30% of market activity, and the top five do not exceed half of the market. This mix produces robust competitive tension: global incumbents leverage breadth and distribution; specialized challengers advance differentiated low‑toxicity chemistries and rapid piloting.
Electromagnetic and Optical Navigation System Market
Strategically, this structure creates three viable routes for buyers and investors in 2026:
- Partner with incumbents that can scale production, navigate regulatory approvals, and offer integrated supply chain solutions.
- Pilot with specialized innovators to capture material downstream benefits in recovery and lifecycle impact, while managing scale-up and supply risk.
- Pursue selective M&A to acquire unique, validated chemistries or feedstock supply chains (e.g., lignin processors, biosurfactant producers) that accelerate time to market.
Competitive landscape — positioning of core players
Our report profiles industry leaders and disruptive specialists to show how product portfolios, R&D pipelines, and commercialization models map to customer needs. Key observations:
- Nouryon (Amsterdam) positions sustainability as a product development axis, progressively removing legacy ingredients and advancing lower‑impact flotation formulations with strong industrial scaling capability.
- Clariant (Muttenz) leverages targeted collector and frother platforms to address coarse‑particle flotation and higher‑energy ores, actively showcasing energy‑efficiency gains at industry forums.
- Syensqo (formerly Solvay, Brussels) combines legacy flotation chemistry know‑how with repositioned formulations targeted at base and precious metals, promoting reduced environmental profiles versus traditional xanthates.
- BASF (Ludwigshafen) focuses on reduced dose rates and improved safety (GHS) profiles, seeking to substitute or complement established reagents in phosphate and industrial mineral flowsheets.
- Arkema / ArrMaz (Colombes) and other specialty players target select minerals (phosphate, silica, glass sand) with customized depressant and collector systems emphasizing selectivity and recovery.
- Regional and technology challengers (e.g., CN‑free cyanide alternatives from Yantai, biosurfactant specialists like Locus Mining Solutions in the U.S., and several China‑based formulators) are moving from lab validation into field trials, offering alternatives to legacy toxic chemistries in precious metals and low‑grade tailings contexts.
These profiles in the full report include vendor scorecards that evaluate technical maturity, scale capability, environmental profile, and commercial terms — essential inputs for procurement and M&A diligence.
Regulatory & raw material drivers: vectors of disruption
Two systemic forces are accelerating adoption and reshaping vendor economics:
- Regulation and ESG mandates. Tighter discharge limits, chemical safety frameworks in major jurisdictions (including recent EU activity), and corporate net‑zero/value‑chain commitments are shortening the runway for legacy, high‑toxicity chemistries. Firms that proactively align product dossiers to regulatory expectations reduce time‑to‑adoption and procurement friction.
- Feedstock innovation. Lignin‑based collectors and fatty‑acid (e.g., TOFA) derivatives, plus renewable biosurfactants (sophorolipids), are emerging as feedstocks that deliver high "green" classification scores — combining biodegradability, renewable origin, and safer toxicological profiles. However, commercial-scale feedstock supply chains require upstream coordination (pulp/paper, biodiesel, forestry residues), which we map in the report.
Recent developments underscore these dynamics: Clariant showcased energy‑efficient coarse flotation reagents at a major industry conference; BASF launched a high‑performance industrial minerals flotation reagent aligned to sustainability objectives; and an academic‑industry review introduced a taxonomy for green flotation reagents that helps standardize procurement scoring. Together, these events signal accelerating technology maturation and market readiness.
Risk framework and deployment playbook for 2026
Adopting eco‑friendly reagents at scale is not a simple substitution — it requires an integrated program that addresses technical, commercial, and regulatory risk. The full report provides a four‑layer risk framework and an associated deployment playbook that includes:
- Technical gate criteria: representative bench and pilot metrics (reagent dose curve, selectivity, recovery delta vs baseline) and decision thresholds for scale‑up.
- Commercial safeguards: performance‑linked contracts, staged purchasing, and inventory buffers for new feedstock supply lines.
- Regulatory contingency planning: submission templates, ecotoxicity testing pathways, and timelines aligned with expected permitting windows.
- Stakeholder engagement tactics: community communications templates, third‑party verification options, and sustainability reporting alignment.
Investment and M&A implications
For corporate development and private equity teams, the landscape presents three attractive strategies that we quantify and stress‑test in the report (summary only here): 1) bolt‑on acquisitions to secure unique bio‑feedstock supply; 2) minority growth investments into scale‑ready reagent innovators with locked‑in pilot agreements; and 3) vertical deals that integrate reagent manufacture with water‑treatment services to realize lifecycle value. The market concentration metrics point to continued room for consolidators that can combine technical IP with distribution reach.
How to use this briefing in 2026 planning cycles
- Procurement heads: use the supplier scorecards and contracting templates to run staged trials this year and negotiate performance‑linked pricing for 2027 rollouts.
- R&D chiefs: prioritize partnerships with feedstock suppliers (lignin processors, biosurfactant fermenters) and deploy techno‑economic pilots that track both recovery and life cycle carbon impact.
- Investors and corporate development: target assets that solve feedstock scalability or offer validated field performance against sulfide and oxide ores to minimize technical risk.
Next steps and access to the full report
This briefing deliberately highlights strategic takeaways while omitting the granular segmentation and proprietary vendor scoring that support transaction‑level decisions. The full PW Consulting report contains the detailed regional and application segmentation, supplier scorecards, scenario financials, and implementation toolkits you need to execute in 2026. To access the complete analysis, model files, and workshop options for executive teams, please visit our report page or contact PW Consulting to schedule a tailored briefing session.
PW Consulting is prepared to support executive workshops, pilot selection and oversight, procurement negotiations, and M&A diligence — helping clients convert the macro momentum behind eco‑friendly beneficiation reagents into measurable operational and sustainability gains.
For detailed analysis of this topic, please visit the official page: Eco-friendly Beneficiation Reagents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com