

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Hard Coating Film Market Hits $715 Million in 2025, 6.44% CAGR to Reach $1.12 Billion by 2032

Navigating the Hard Coating Film Market: Strategic Intelligence for 2026 and Beyond
The global hard coating film industry stands at a critical inflection point. As display technologies evolve, automotive interfaces become more sophisticated, and medical devices demand higher performance standards, the protective layers that enable these innovations are experiencing sustained growth. Our latest comprehensive market research on the Hard Coating Film Market provides the strategic framework necessary for enterprise decision-makers to navigate this complex landscape through 2032 and beyond.
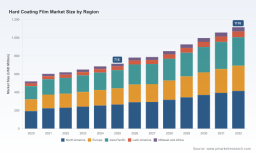
This analysis reveals a market that has demonstrated remarkable resilience and steady expansion. The historical trajectory from 2020 through 2025 shows consistent upward momentum, with the market growing from 520.0 million USD to 715.0 million USD. This growth reflects not merely cyclical demand but structural shifts in how industries approach surface protection, optical clarity, and functional integration. The forecast period from 2026 to 2032 projects continued expansion, with the market expected to reach 1116.0 million USD by the end of the forecast window. The compound annual growth rate of 6.44% during this period signals a market that is maturing yet still offers substantial opportunities for strategic players who can position themselves advantageously.
For executives, product managers, and investment analysts, understanding these macro trends is only the beginning. The true value lies in dissecting the drivers, constraints, competitive dynamics, and regional nuances that will determine which organizations capture market share and which fall behind. This report is designed to deliver that precision intelligence.
Market Evolution and Structural Transformation
The hard coating film sector has undergone significant transformation over the past half-decade. Early market development was driven primarily by consumer electronics applications, where scratch resistance and optical clarity were paramount. Today, the landscape has expanded considerably. The demand profile now encompasses automotive displays, medical instrumentation, industrial safety equipment, and emerging flexible electronics applications. This diversification has created a more resilient market structure while simultaneously increasing the complexity of competitive positioning.
Several technological breakthroughs are reshaping industry expectations. Self-healing coating formulations that recover from minor abrasions represent a paradigm shift in product longevity and user experience. Dual-function coatings that simultaneously address anti-glare and anti-fingerprint requirements demonstrate how multifunctional integration is becoming a competitive necessity rather than a premium differentiator. The push toward environmentally sustainable coating processes, including water-based formulations, reflects both regulatory pressure and corporate sustainability commitments that are increasingly influencing procurement decisions.
Hard Coating Film Market
These technological advances intersect with evolving regulatory frameworks across multiple jurisdictions. Safety standards for automotive and industrial applications continue to tighten, while medical device regulations demand biocompatible formulations that meet rigorous international standards. Companies that proactively align their product development with these regulatory trajectories will find themselves better positioned to serve high-value segments that prioritize compliance and certification.
Segmentation Dynamics and Growth Vectors
The market structure reveals distinct performance patterns across material types, application categories, and geographic regions. Understanding these segmentation dynamics is essential for identifying where investment capital will generate the highest returns and which segments face consolidation pressure.
Hardcoated polycarbonate film has established itself as a dominant material category, reflecting its superior impact resistance characteristics that make it indispensable for applications where mechanical durability is non-negotiable. Hardcoated polyethylene terephthalate film represents another significant segment, serving applications where specific optical and processing requirements drive material selection. The presence of diverse material formulations in the broader market indicates that no single solution fits all use cases, and successful suppliers must maintain a portfolio approach that addresses varied customer specifications.
Application segmentation tells a story of concentrated demand in certain end-use sectors alongside emerging opportunities in others. Mobile phone displays continue to represent a substantial demand center, driven by the relentless cycle of device launches and the premium positioning of protective film solutions. Touch panel applications form another significant demand pillar, while appliance overlays and membrane switches reflect the broader industrial and consumer goods penetration of hard coating technologies. Each application segment carries distinct performance requirements, pricing sensitivities, and procurement cycles that demand tailored go-to-market strategies.
Geographic distribution of market activity reveals that mature markets continue to generate substantial revenue while developing markets present growth acceleration potential. The interplay between established manufacturing hubs and emerging production centers creates both opportunities for capacity expansion and risks related to supply chain concentration. Understanding regional competitive intensity, customer density, and regulatory environments is critical for sizing market entry investments and determining whether organic growth, partnership, or acquisition represents the optimal expansion pathway.
Competitive Landscape: Key Players and Strategic Positioning
The competitive environment in the hard coating film market is characterized by a mix of specialized manufacturers and diversified industrial giants. The market concentration metrics indicate a moderately fragmented landscape where the top three players command approximately 28 percent of total revenue, while the top five collectively represent about 38 percent. This structure suggests that while scale advantages exist, there remains meaningful room for specialized competitors to differentiate through technology, service, or niche market focus.
Japanese manufacturers have established particularly strong positions in the high-performance segment of the market. Kimoto Co., Ltd. has built a reputation for precision-coated optical hard coating films serving displays, touch screens, and medical applications, with product specifications emphasizing 7H hardness ratings and ultra-thin format capabilities. Their recent expansion of the Tokyo facility by 11 million square meters demonstrates a commitment to scaling capacity in response to demand signals. Toray Industries, Inc. has positioned itself at the intersection of advanced materials science and application expertise, offering next-generation multilayer hard coating films designed for foldable OLED screens, automotive applications, and electronics. Their focus on 6H hardness with a 2.5 millimeter bending radius, combined with an environmental sustainability emphasis, illustrates how technical performance and corporate responsibility are increasingly integrated into value propositions. Toray's distribution agreement to supply hard coating films to over 120 OEMs in Europe highlights the importance of channel partnerships in penetrating established markets.
Gunze Limited has pursued a differentiated strategy by developing dual-function hard coating films that integrate anti-glare and anti-fingerprint technologies simultaneously. Their achievement of 94 percent light transmittance while delivering 68 percent fingerprint reduction demonstrates the technical sophistication that end-users increasingly demand. The shipment of 3.6 million square meters within eight months of development signals strong market receptivity to multifunctional solutions. Arisawa Manufacturing Co., Ltd. has introduced a particularly innovative product category with proprietary self-healing hard coating films capable of recovering from minor abrasions within 24 hours at room temperature. The projected 46 percent service life improvement in touchscreen applications addresses a fundamental pain point in device durability and total cost of ownership, positioning this technology for significant adoption in high-use environments.
The American market features a diverse set of competitors with varying area specializations. Tekra LLC provides Marnot and Terrapin branded hardcoated polycarbonate and polyester films for displays, medical, and industrial applications, emphasizing chemical and abrasion resistance. Vampire Coating, Inc. focuses on specialized optical and protective hard coating films for aerospace, defense, and scientific instruments, where custom formulations and extreme performance requirements justify premium pricing. SDC Technologies, Inc. offers optically clear thermal and UV-cure hard coatings with premium abrasion and chemical resistance targeting optics, medical devices, and safety applications. 3M Company leverages its vast industrial portfolio to provide hard-coated films and laminates with superior scratch resistance and durability across electronic displays, automotive, and industrial protective applications, benefiting from brand recognition and distribution scale.
Asian competitors outside Japan are also making significant strategic moves. SKC Co., Ltd. from South Korea manufactures hard-coated PET films for displays, EV touchscreens, and flexible electronics, with capacity ramps driven by demand signals from these growing end markets. Lintec Corporation supplies hard coating films with antimicrobial and self-healing properties, extending functionality into medical kiosks, electronics, and industrial surfaces. Chinese manufacturers such as Chiefway Technology and HYNT Coating Technology are developing competitive capabilities in anti-static and protective hard coating films for PET substrates using roll-to-roll processing, as well as water-based hard coating lines for anti-scratch, anti-fog, and functional films serving consumer electronics and automotive sectors. These developments reflect the broader globalization of manufacturing capability and the increasing importance of cost-competitive production in volume-driven segments.
Industry Dynamics: Drivers, Restraints, and Regulatory Influences
Several structural forces are shaping the trajectory of the hard coating film market. The proliferation of display interfaces across automotive, consumer electronics, medical, and industrial equipment continues to generate baseline demand growth. As screens become larger, more numerous, and more critical to user experience, the requirement for durable, optically clear protective coatings becomes increasingly non-negotiable. The emergence of foldable devices, transparent displays, and augmented reality interfaces introduces new performance parameters that drive innovation in coating formulations and deposition processes.
Raw material availability and cost dynamics represent ongoing considerations for market participants. Polyester substrates have captured significant market share in hard coating film production, supported by capacity investments from major material suppliers. The availability, pricing stability, and quality consistency of base materials directly influence coating manufacturers' ability to maintain competitive pricing while preserving margin structures. Companies that develop strong supplier relationships, secure long-term supply agreements, or invest in backward integration where strategically justified will enjoy advantages in cost management and supply assurance.
Regulatory compliance has evolved from a baseline requirement to a strategic differentiator in many application segments. Hardcoated polycarbonate films that meet demanding impact resistance standards and polyester hardcoated films that satisfy ANSI Z87.1 safety requirements for automotive and industrial use illustrate how regulatory frameworks shape material selection and product specification. PVC films used in certain applications must satisfy RoHS and REACH compliance for medical and consumer electronics markets, adding complexity to material sourcing and formulation development. For medical device applications, hardcoated films incorporating biocompatible polymer formulations that meet ISO 10993 standards represent a specialized niche where regulatory expertise and testing capability create meaningful barriers to entry. Companies that invest in regulatory affairs capabilities and maintain proactive compliance postures will find themselves better positioned to serve regulated industry segments that offer attractive margins and sticky customer relationships.
Sustainability considerations are gaining prominence in procurement decisions across multiple industries. Water-based coating processes, lower-VOC formulations, and recyclable substrate options are increasingly requested by customers who face their own sustainability reporting obligations and corporate responsibility commitments. Suppliers that can demonstrate environmental performance improvements without compromising technical specifications will have a competitive advantage in markets where sustainability criteria are weighted in supplier selection processes.
What This Report Delivers: A Toolkit for Strategic Action
This Hard Coating Film Market research report is structured to provide actionable intelligence at multiple levels of organizational decision-making. The analysis goes beyond descriptive market characterization to deliver the kind of granular insight that supports capital allocation, product roadmapping, competitive positioning, and market entry strategy development.
The report provides a comprehensive market sizing framework that establishes baseline revenue figures, growth trajectories, and forward projections across the full forecast horizon. This quantitative foundation enables scenario planning and sensitivity analysis that account for variations in macroeconomic conditions, technological adoption rates, and competitive intensity. The segmentation analysis dissects market performance by material type, application category, and geographic region, revealing where growth is concentrating, which segments face maturity or saturation risks, and how cross-segment dynamics influence overall market evolution.
Competitive profiling extends beyond basic company descriptions to analyze strategic positioning, technological capabilities, recent corporate developments, and inferred competitive advantages. The inclusion of recent developments such as capacity expansions, distribution agreements, product launches, and technology demonstrations provides a window into current strategic priorities and resource allocation patterns among key market participants. Understanding what competitors are investing in reveals where they see growth opportunities and how they intend to differentiate their offerings.
The report incorporates analysis of industry dynamics including driver and restraint assessments, regulatory impact evaluations, and supply chain considerations. This contextual framework helps decision-makers anticipate how external factors will influence market conditions and adjust their strategies accordingly. By connecting market data with qualitative industry intelligence, the report enables a more nuanced understanding of cause-and-effect relationships that pure quantitative analysis might miss.
Worldwide Polyester Coating Market
End-use application analysis traces demand from specific industry verticals, examining procurement patterns, specification requirements, and emerging needs that will shape future coating development priorities. This application-centric perspective is particularly valuable for suppliers seeking to align their product development pipelines with the most promising demand signals and for investors evaluating the growth potential of different market segments.
Implications for 2026 Decision-Making
As organizations plan their strategic initiatives for 2026 and the ensuing years, several implications emerge from the market intelligence presented in this research. First, the sustained growth trajectory of the hard coating film market suggests that demand tailwinds will continue to support expansion, but the distribution of growth across segments and regions will be uneven. Companies that attempt to compete broadly without clear prioritization risk spreading resources too thinly. Focusing investment on segments where technological differentiation, customer relationships, or cost position provide defensible advantages will generate better returns than undifferentiated participation across all market categories.
Second, the pace of technological innovation in coating formulations, including self-healing properties, multifunction integration, and environmentally sustainable processes, indicates that product lifecycle management must remain a strategic priority. Companies that allow their product portfolios to become technologically obsolete relative to emerging alternatives will face margin compression and customer attrition. Continuous investment in research and development, whether conducted internally or through partnerships with technology providers, is essential for maintaining competitive relevance.
Third, the geographic distribution of manufacturing capability and customer concentration creates both opportunities and vulnerabilities. The expansion of production capacity in key regions, the establishment of new distribution agreements, and the development of locally tailored product offerings all represent strategic moves that can influence regional market share dynamics. Organizations must assess whether their current geographic footprint aligns with where demand is growing and where competitive intensity is evolving.
Fourth, regulatory and compliance considerations will increasingly influence market access and customer qualification processes. Companies that proactively address regulatory requirements, invest in testing and certification capabilities, and position their products to meet emerging standards will reduce barriers to entry in high-value regulated segments. Those that treat compliance as a reactive cost center rather than a strategic capability may find themselves excluded from attractive market opportunities.
Conclusion
The Hard Coating Film Market represents a sector where sustained demand growth intersects with rapid technological evolution and increasing competitive sophistication. Success in this environment requires more than awareness of market size and growth rates. It demands deep understanding of segmentation dynamics, competitive capabilities, technological trajectories, regulatory frameworks, and regional market characteristics. The organizations that thrive will be those that translate market intelligence into focused strategy, disciplined resource allocation, and agile execution.
This research report is designed to equip decision-makers with the comprehensive intelligence necessary to make those strategic choices with confidence. By revealing the underlying structure of the market, the capabilities and intentions of key competitors, and the dynamics that will shape future growth, the report provides a foundation for planning that reduces uncertainty and increases the probability of successful outcomes. We invite you to explore the full analysis to gain the depth of insight required for navigating the hard coating film market through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Hard Coating Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com