
Blogs
PW Consulting: Worldwide Cloud VPN Market to Reach $42.16B by 2032 with 15% CAGR
By pmarketresearch, 2026-09-16
Navigating the Secure Cloud Frontier: Strategic Insights from the 2026 Worldwide Cloud VPN Market Report
The enterprise networking landscape is undergoing a structural transformation. As organizations accelerate their migration to hybrid and multi-cloud environments, the traditional perimeter has dissolved, replaced by dynamic, identity-centric security models. At the heart of this shift lies the Cloud VPN market, a critical infrastructure layer that ensures secure connectivity across distributed assets. PW Consulting is proud to introduce our latest comprehensive study, the Worldwide Cloud VPN Market Report, designed to equip C-suite executives, network architects, and investment strategists with the intelligence needed to navigate the complexities of 2026 and beyond.
This report is not merely a collection of statistics. It is a strategic roadmap intended to decode the velocity of market evolution, the intensifying competitive dynamics, and the regulatory headwinds that will define the next seven years. By analyzing historical trajectories from 2020 through 2025 and projecting forward to 2032, we provide a clear lens through which to evaluate opportunity costs and growth vectors.
Worldwide Cloud VPN Market
Macro Trajectory and Market Magnitude
The scale of the opportunity is substantial. Our analysis indicates that the global Cloud VPN market has experienced robust expansion over the past half-decade, driven by the relentless adoption of cloud services and the heightened necessity for secure remote access protocols. Starting from a foundation of approximately 7.85 billion USD in 2020, the market has climbed steadily to reach an estimated 15.85 billion USD in 2025. This historical growth underscores the critical dependency organizations now place on encrypted tunneling solutions to maintain operational continuity.
Looking ahead, the forecast period from 2026 to 2032 suggests continued momentum. Projections indicate the market will surpass 18.16 billion USD in 2026, accelerating towards a valuation exceeding 42.16 billion USD by the end of the forecast window in 2032. This trajectory implies a Compound Annual Growth Rate (CAGR) of roughly 15.0 percent over the forecast period. For strategic planners, this rate signals more than just revenue potential; it indicates a maturing ecosystem where consolidation, technological differentiation, and regulatory compliance will become the primary battlegrounds for market share.
Architectural Shifts and Segmentation Dynamics
Understanding where value is generated within this ecosystem is vital for allocation decisions. The market is broadly defined by distinct component categories, primarily split between Software and Platform solutions and Professional and Managed Services. Our deep dive reveals how the balance between these components is shifting as enterprises seek turnkey security stacks rather than discrete tools.
Furthermore, connectivity types are evolving. The market encompasses both Site-to-Site Cloud VPN solutions, which remain critical for hybrid cloud architectures, and Remote Access Cloud VPN, which has seen sustained demand due to persistent flexible work models. However, the nuance lies in how these segments interact with emerging Zero Trust frameworks. The report details how traditional tunneling is being augmented, and in some cases replaced, by identity-aware proxies and software-defined perimeters. We analyze the revenue implications of these architectural transitions without oversimplifying the complex trade-offs between performance, latency, and security posture.
Regional dynamics also play a pivotal role in shaping demand. While North America continues to represent a significant portion of market activity, reflecting its high density of cloud infrastructure and enterprise adoption, other regions are exhibiting unique growth patterns driven by local data sovereignty laws and digital transformation initiatives. Europe and Asia Pacific present distinct challenges and opportunities, particularly regarding infrastructure capacity and regulatory alignment. The report contextualizes these regional variances, helping global organizations tailor their deployment strategies to local realities rather than applying a one-size-fits-all approach.
Competitive Landscape and Strategic Positioning
The vendor ecosystem is a mix of hyperscale cloud providers, established security giants, and innovative niche players. The market concentration is notable, with the top three players holding a significant share of the landscape, while the top five approach half of the total market value. This consolidation suggests that scale and interoperability are becoming increasingly important differentiators.
Key industry participants include technology behemoths such as Cisco Systems, Microsoft Corporation, Amazon Web Services, and Google LLC. These companies leverage their existing cloud ecosystems to embed VPN capabilities directly into broader networking and security portfolios. For instance, solutions like Azure VPN Gateway and AWS VPN Concentrator are designed to streamline hybrid connectivity within their respective clouds. Similarly, Cisco and Google focus on integrating secure connectivity into wider SASE and dynamic routing frameworks.
The competitive field also includes specialized security vendors like Palo Alto Networks, Fortinet, Zscaler, and Check Point Software Technologies. These players often emphasize the convergence of VPN with next-generation firewall capabilities or Zero Trust Network Access (ZTNA). Zscaler and Cloudflare, for example, are positioning cloud-native alternatives that challenge traditional VPN paradigms by offering secure application access without backhauling traffic through centralized tunnels. Oracle Corporation and Huawei Technologies also maintain significant footprints, catering to specific enterprise cloud environments and regional networking needs. Array Networks rounds out the competitive view with specialized application delivery and secure access gateways.
Strategic moves within this cohort are frequent and telling. Recent industry activity highlights the pace of innovation. In November 2025, Amazon Web Services launched a VPN Concentrator for Site-to-Site VPN, enabling efficient connections for up to 100 low-bandwidth remote sites via a single Transit Gateway attachment. This product launch illustrates the industry focus on simplifying scale and reducing operational overhead for distributed enterprises. Meanwhile, in February 2026, Cloudflare partnered with Mastercard to extend comprehensive cyber defense capabilities, including application security tools relevant to secure cloud connectivity, specifically targeting critical infrastructure and small businesses. Such developments signal a broader trend where VPN technology is becoming intertwined with broader cyber resilience and partnership ecosystems.
Ssl Vpn Gateway Market
Regulatory and Infrastructure Headwinds
No strategic assessment of the Cloud VPN market is complete without addressing the external forces that constrain and shape deployment. Our report dedicates significant attention to the regulatory and infrastructure realities that executives must factor into their 2026 roadmaps.
Data sovereignty and regulatory compliance are no longer optional considerations. Initiatives requiring local data processing and storage are expanding globally, influencing cloud VPN deployment strategies to ensure adherence to local laws. In the European Union, the Digital Operational Resilience Act (DORA), effective January 2025, imposes strict requirements on ICT providers including cloud services for financial entities. This impacts the resilience and auditability of cloud VPN solutions, requiring vendors and users alike to demonstrate robust risk management frameworks.
Simultaneously, the United States has introduced new data transfer restrictions. The U.S. Department of Justice Bulk Data Rule, effective in 2025 with full compliance mandated by October 2025, restricts certain bulk sensitive personal data transfers to countries of concern. This directly affects cross-border cloud data flows used in VPN architectures, compelling multinational organizations to rethink their tunneling paths and data routing policies to avoid compliance violations.
Infrastructure constraints also loom large. The physical backbone supporting cloud VPN services faces significant pressure. U.S. data centers are projected to see electricity demand nearly double from 80 GW to 150 GW between 2025 and 2028. This surge significantly impacts operational costs for cloud infrastructure supporting VPN services. In regions with high data center concentration, such as parts of Virginia, data centers accounted for nearly 40 percent of total electricity consumption in 2024, contributing to localized wholesale electricity price increases of up to 267 percent over five years. These cost dynamics influence pricing models and availability, making energy efficiency a hidden but critical variable in vendor selection and architecture design.
Operationalizing the Intelligence for 2026 Decision-Making
The value of this report lies in its actionable granularity. We move beyond high-level aggregates to provide the specific intelligence needed for tactical execution. The study includes detailed profiles of key companies, analyzing their product portfolios, strategic focus, and recent developments. This allows competitive intelligence teams to benchmark their positions against rivals and identify potential partnership or acquisition targets.
Our segmentation analysis breaks down the market by component, connectivity type, and organization size, providing a multi-dimensional view of demand drivers. This helps product managers understand which layers of the stack are seeing the most investment and where service gaps may exist. The regional analysis offers a nuanced look at market maturity and growth catalysts across North America, Europe, Asia Pacific, and emerging regions, enabling leaders to prioritize geographic expansion or resource allocation.
Additionally, the report integrates industry context noise, such as labor cost fluctuations and infrastructure constraints, into the market dynamics discussion. By understanding how electricity costs and regulatory shifts impact the supply side of cloud VPN services, procurement and strategy teams can better negotiate contracts and plan for long-term scalability.
Conclusion: The Imperative for Informed Strategy
As we move through 2026, the Worldwide Cloud VPN market stands at a critical juncture. The convergence of legacy connectivity needs with modern Zero Trust principles, coupled with stringent regulatory environments and infrastructure cost pressures, creates a complex decision matrix for enterprise leaders. Relying on outdated assumptions or generalized market data is a risk that organizations cannot afford.
This PW Consulting report provides the depth, accuracy, and strategic context required to make informed choices. Whether you are evaluating vendor partnerships, planning network architecture upgrades, or assessing market entry opportunities, the insights contained herein are calibrated to support high-stakes decision-making. We invite you to access the full report to unlock the complete dataset, detailed forecasts, and comprehensive competitive profiles that will define your strategy for the remainder of the decade. The future of secure cloud connectivity is being written now; ensure your organization has the blueprint to navigate it successfully.
For detailed analysis of this topic, please visit the official page: Worldwide Cloud VPN Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Fire and Gas Detection Market Hits $7.5B in 2025, Driven by 6.5% CAGR to $11.65B by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Decade Ahead: Navigating the Global Fire and Gas Detection System Market 2026-2032
In an era where operational safety, regulatory compliance, and technological integration define industrial resilience, the fire and gas detection sector stands at a critical inflection point. For executives, investors, and engineering leaders charting strategy through the remainder of the decade, understanding the structural trajectory of this market is no longer optional—it is a prerequisite for risk mitigation and growth allocation. Our latest research publication, Worldwide Fire and Gas Detection System Market , delivers a comprehensive, data-backed assessment designed to translate macro-level momentum into actionable corporate strategy for 2026 and beyond.
Gas Detectors Market
This analysis does not merely project numbers. It maps the interplay between evolving safety standards, sensor innovation cycles, regional deployment pacing, and competitive positioning. By aligning historical performance with forward-looking modeling, the report equips decision-makers with the clarity required to prioritize capital, evaluate supply chain exposure, and anticipate where value creation will concentrate over the 2026–2032 forecast horizon.
Market Trajectory and Growth Architecture
The global fire and gas detection ecosystem has demonstrated consistent expansion over the past half-decade, underpinned by tightening occupational safety mandates, accelerated industrial automation, and heightened risk awareness in high-hazard environments. Historical tracking from 2020 through 2025 reveals a mature yet resilient revenue curve, with the market establishing a firm baseline as it enters the current forecast cycle.
Building on this foundation, our forward-looking modeling projects sustained valuation growth through 2032. The compound annual growth rate (CAGR) is estimated at 6.5 percent across the forecast window, reflecting steady demand pull from process industries, infrastructure modernization programs, and the integration of advanced detection platforms into broader safety instrumented systems. By 2026, projected revenue climbs to approximately 7,987.5 million USD, and the trajectory continues upward, reaching an estimated 11,654.91 million USD by 2032.
These figures are not abstract benchmarks. They represent converging investment signals: capital expenditure tied to facility compliance, retrofit cycles for aging detection infrastructure, and the gradual migration from legacy standalone alarms to networked, software-enabled monitoring architectures. The report dissects the structural drivers behind this arc, enabling leaders to separate cyclical noise from durable growth fundamentals.
Structural Segmentation and Value Concentration
Effective strategy requires understanding where revenue originates, how it is distributed across technology families, and which application verticals anchor demand. Our segmentation analysis isolates the primary axes that shape procurement behavior, pricing dynamics, and competitive targeting.
From a product architecture perspective, the market is anchored by gas detection solutions, flame detection hardware, and the control systems and software layer that orchestrates them. Gas detection continues to command the largest revenue share, reflecting the breadth of hazardous gas monitoring requirements across chemical processing, refining, and confined-space operations. Flame detection maintains a critical niche in high-speed fire scenarios, particularly where hydrocarbon, hydrogen, and outdoor exposure conditions demand rapid optical response. Meanwhile, control systems and software represent the integration layer that is increasingly dictating total cost of ownership, maintenance efficiency, and regulatory reporting capability.
Application-side, oil and gas remains the dominant deployment context, driven by the sector’s risk profile, asset density, and stringent process safety expectations. Industrial and manufacturing follows as a substantial demand center, where continuous production environments require reliable detection coverage and seamless integration with plant automation. Commercial and institutional facilities contribute a meaningful share as building safety codes evolve and multi-hazard monitoring becomes standard practice. Energy and power installations round out the application base, with detection systems supporting generation, transmission, and distribution infrastructure where uninterrupted monitoring is mission-critical.
Regional demand patterns further illuminate deployment priorities and supply chain considerations. North America maintains a leading revenue position, supported by mature industrial bases, active compliance ecosystems, and sustained capital programs. Asia Pacific represents a substantial and rapidly expanding footprint, shaped by industrialization scales, infrastructure build-out, and growing adoption of integrated safety systems. Europe continues to reflect high regulatory discipline and technology-led procurement, while Latin America and the Middle East and Africa contribute emerging growth vectors tied to energy development, mining activity, and industrial modernization initiatives.
Importantly, the market exhibits moderate-to-firm concentration among leading providers, with the top three firms accounting for an estimated 42.5 percent of revenue and the top five reaching approximately 58.75 percent. This concentration has strategic implications: it signals the presence of scaled platforms, established certification portfolios, and entrenched customer relationships, while also highlighting the space for specialized innovators and regional challengers to compete on technology differentiation, service models, and application-specific performance.
Competitive Landscape: Incumbents, Specialists, and the Innovation Race
The fire and gas detection market is defined by a layered competitive structure. Global incumbents bring breadth across hardware, software, and service networks. Mid-tier specialists and technology-focused players compete through sensor performance, detection range, and environmental resilience. Automation and building safety conglomerates extend the category by embedding detection into wider control and facility platforms.
Honeywell International Inc. continues to advance comprehensive fixed and portable fire and gas detection portfolios, spanning flame detectors, toxic and combustible gas sensors, and integrated safety solutions for oil and gas, chemical, and industrial use cases. MSA Safety Incorporated reinforces its industrial safety positioning with fixed gas and flame detection platforms, open path and ultrasonic gas detection capabilities, and integrated solutions aligned with standards such as NFPA. Drägerwerk AG & Co. KGaA brings specialized expertise in optical flame detection, multi-gas instruments, and fixed monitoring systems engineered for hazardous environments across maritime, oil and gas, and industrial settings. Emerson Electric Co. delivers detection as part of process automation and safety instrumented systems, with emphasis on integrated solutions for oil and gas and petrochemical operations. Siemens AG contributes fire detection and gas monitoring offerings, including Cerberus platforms for industrial and building applications, while ABB Ltd. supplies detection systems integrated with automation and control solutions for process safety. Johnson Controls International expands the addressable space through fire detection and suppression systems with gas detection capabilities within broader building and industrial safety portfolios. Autronica Fire and Security AS maintains a strong global footprint in detection systems tailored for maritime, oil and gas, and commercial sectors, and Teledyne Gas and Flame Detection provides advanced instruments and systems for industrial safety applications.
The competitive field also includes highly specialized providers that compete on performance engineering rather than scale alone. Fire & Gas Detection Technologies Inc. focuses on UV/IR and IR3 flame detectors designed for hydrocarbon, hydrogen, and high-speed industrial fires. ESP Safety Inc. concentrates on detection technologies and systems for hazardous environments, while Industrial Scientific emphasizes portable and fixed gas detection with connected safety and real-time monitoring capabilities.
Recent industry activity underscores the pace of differentiation. In June 2026, MSA Safety exhibited at the NFPA Conference & Expo with a session addressing NFPA 72 updates that integrate gas detection, open path gas detection, ultrasonic gas detection, and smoke detection technologies into fire alarm standards. In April 2026, Patol / Optect introduced the world’s first optically enhanced long-range flame detector, the LR16, targeting specialist fire detection applications. In February 2026, Macurco Gas Detection was scheduled to exhibit at the AHR Expo, showcasing gas detection systems for HVACR professionals. These developments illustrate a broader pattern: competition is increasingly won on sensor performance, integration readiness, standards alignment, and application-specific engineering rather than commodity hardware alone.
Worldwide Fire and Gas Detection System Market
Dynamics Shaping the Next Cycle
Several forces are converging to reshape procurement priorities and technology roadmaps across the fire and gas detection sector. Understanding these dynamics is essential for evaluating supplier selection, product lifecycle planning, and market entry timing.
Regulatory and standards evolution remains a primary demand catalyst. Stringent occupational safety requirements and industry-specific benchmarks, including API and IEC frameworks, continue to drive demand for reliable detection in high-risk sectors such as oil and gas and chemicals. At the same time, updates to fire alarm standards are increasingly incorporating gas detection, open path gas detection, ultrasonic gas detection, and smoke detection technologies, expanding the scope of integrated compliance and pushing end users toward multi-sensor architectures.
Technology advancement is accelerating along multiple vectors. Sensor development emphasizes miniaturization, IoT connectivity, wireless capabilities, and AI-enabled predictive maintenance. These capabilities are transforming detection from a passive alarm function into an active monitoring and diagnostics layer, reducing false alarms, extending service intervals, and enabling centralized visibility across distributed assets. The implications for lifecycle cost, uptime, and operator safety are significant, especially for organizations managing large, dispersed, or remote installations.
Raw material and component dependencies also influence supply chain strategy. Gas detection systems rely heavily on specialized sensors—including electrochemical, infrared, semiconductor, and catalytic types—whose manufacturing involves semiconductor materials and precision optics components. As demand scales and performance expectations rise, sourcing resilience, component qualification, and manufacturing precision become differentiators that affect lead times, reliability, and total cost of ownership.
The result is a market where value is increasingly determined by how well detection platforms connect to broader operational systems, how effectively they adapt to complex hazard profiles, and how efficiently they can be deployed, maintained, and upgraded over time. Companies that treat detection as a standalone accessory risk underinvesting in integration, while those that treat it as a core safety and data layer are better positioned to capture sustained demand.
What the Report Delivers for 2026 Decision-Makers
This market study is built to support concrete strategic action. Rather than providing a high-level overview, it delivers a structured intelligence framework that connects market sizing, segmentation, competitive behavior, and technology direction to business decision processes. Key practical components include:
- Detailed revenue tracking and forecast modeling across the 2026–2032 period, anchored in a 6.5 percent CAGR and supported by historical continuity from 2020–2025.
- Segment-level analysis covering type, application, and regional demand structures, clarifying where revenue concentrates and how deployment priorities differ by sector and geography.
- Competitive profiling of leading and specialized providers, with coverage of product orientation, application focus, and strategic positioning across the global landscape.
- Assessment of recent industry developments, including standards-related updates, product launches, and exhibition activity that signal near-term commercialization and compliance trends.
- Examination of market dynamics such as sensor innovation, connectivity adoption, predictive maintenance, regulatory integration, and component supply considerations.
- Concentration analysis that helps evaluate incumbent strength, barriers to entry, and opportunities for differentiation.
For corporate strategists, the report supports market entry evaluation, competitive benchmarking, and capital allocation planning. For technology and procurement leaders, it provides context on integration requirements, sensor technology direction, and standards alignment. For investors and analysts, it offers a structured basis for assessing growth durability, segment attractiveness, and the shifting balance between scale players and specialized innovators.
How to Use This Intelligence
The value of this research lies in its applicability. Leadership teams can use the forecast trajectory to test expansion assumptions, evaluate partnership opportunities, and stress-test revenue models against realistic demand pacing. Engineering and safety leaders can align architecture decisions with the direction of integration, connectivity, and multi-sensor compliance. Procurement and supply chain teams can use the segmentation and concentration insights to anticipate vendor dynamics, specification requirements, and sourcing constraints.
Most importantly, the study is designed to prevent decision-making in the dark. In a market where safety performance, regulatory expectations, and technological capability are evolving simultaneously, relying on fragmented information creates strategic exposure. A consolidated, forward-looking view enables organizations to act earlier, prioritize more precisely, and align investments with the segments and capabilities most likely to shape the next phase of market growth.
The complete report provides the full depth of segmentation data, detailed forecasts by segment and region, comprehensive competitive profiles, and extended analysis of market dynamics and recent industry developments. Organizations seeking to operationalize this intelligence for 2026 planning can access the full dataset and methodology through the source publication, where the complete intelligence package is available for download and review.
For detailed analysis of this topic, please visit the official page: Worldwide Fire and Gas Detection System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Glass Fiber Sizing Agent Market to Reach $1,059.21M by 2032, Growing at 6.18% CAGR
By pmarketresearch, 2026-09-16
Strategic Imperatives in the Global Glass Fiber Sizing Agent Market: Navigating Growth and Innovation Through 2032
The glass fiber sizing agent market stands at a critical inflection point, driven by the escalating demand for high-performance composites across transportation, renewable energy, and advanced manufacturing sectors. As materials science evolves to meet stricter regulatory standards and performance thresholds, the role of sizing agents has shifted from a mere processing aid to a foundational element determining composite integrity, resin compatibility, and environmental compliance. This analysis synthesizes the trajectory of the market through 2032, highlighting the strategic nuances that decision-makers must address to capitalize on emerging opportunities.
Market Trajectory and Macroeconomic Context
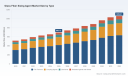
The global market for glass fiber sizing agents has demonstrated resilient expansion over the past half-decade, transitioning from a post-pandemic recovery phase into a sustained growth cycle. Valued at approximately 515.42 million USD in 2020, the market reached 696.12 million USD by 2025, reflecting a compound annual growth rate that underscores the sector's maturity and expanding application base. Looking ahead, the forecast period from 2026 to 2032 projects continued momentum, with the market size anticipated to approach 1.06 billion USD by the end of the decade. This growth is underpinned by a CAGR of 6.18 percent, signaling steady demand escalation rather than volatile spikes. Such a trajectory suggests that investments in sizing technology are no longer optional but essential for manufacturers aiming to secure supply chain stability and performance reliability.
Segmentation Dynamics: Type, Chemistry, and Application Drivers
Understanding the structural composition of the market reveals where value is being created and where competitive pressures are intensifying. The segmentation landscape is defined by distinct categories that reflect both historical usage patterns and emerging technological shifts.
Type-Based Segmentation
The market is broadly categorized by the functional role of the sizing agent. Film formers constitute the largest share of the market, reflecting their critical function in protecting glass fibers during processing and ensuring optimal adhesion to resin matrices. Coupling agents follow as a significant segment, vital for enhancing interfacial strength between inorganic fibers and organic polymers. Lubricants and antistatic agents, while smaller in volume, play indispensable roles in processing efficiency and safety, particularly in high-speed manufacturing environments. The interplay between these types dictates formulation strategies, with leading manufacturers often blending multiple functionalities to meet specific customer requirements.
Chemistry-Based Segmentation
Chemistry defines the performance envelope of sizing agents. Epoxy-based formulations lead the chemistry segment, driven by their prevalence in high-strength composite applications where thermal and mechanical stability are paramount. Polyurethane-based chemistries represent a robust secondary segment, prized for their versatility in both thermoset and thermoplastic systems, as well as their compatibility with waterborne formulations that align with environmental regulations. Polyester, polypropylene, and vinyl ester-based agents serve niche but critical roles, often selected for specific resin compatibility or cost-performance balances. The shift toward low-VOC and waterborne polyurethanes is particularly notable, reflecting industry-wide pressure to reduce emissions without compromising performance.
Application-Based Segmentation
The demand for sizing agents is inextricably linked to the health and direction of end-use industries. Transportation remains the dominant application driver, fueled by the lightweighting initiatives in automotive and aerospace sectors that rely on glass fiber-reinforced composites to improve fuel efficiency and reduce emissions. Wind energy stands as a second pillar of growth, with the expansion of turbine blade manufacturing requiring sizing agents that can withstand extreme environmental stresses while maintaining structural integrity during production. Aerospace and defense applications demand high-specification sizing solutions that meet rigorous certification standards. Construction and infrastructure, electrical and electronics, and industrial applications round out the demand profile, each imposing unique requirements on durability, processing speed, and chemical resistance. The diversity of applications suggests that suppliers must maintain a broad portfolio or specialize deeply to capture value in specific verticals.
Worldwide Glass Fiber Sizing Agent Market
Regional Analysis and Geographic Concentration
Geographically, the market exhibits a clear concentration of activity, with Asia Pacific commanding the largest share of revenue. This dominance is attributable to the region's massive manufacturing base, rapid industrialization, and significant investments in infrastructure and renewable energy. Europe and North America represent mature but steadily growing markets, where demand is driven by high-performance applications, stringent regulatory environments, and the presence of advanced composite manufacturers. Latin America and the Middle East and Africa, while smaller in absolute terms, offer pockets of growth aligned with specific industrial development and energy projects. The regional distribution highlights the importance of localized supply chains and formulation adaptations to meet varying regulatory and climatic conditions.
Competitive Landscape: Key Players and Strategic Positioning
The market is characterized by a moderately concentrated competitive environment. The top three companies account for approximately 38.45 percent of the market, while the top five firms capture around 56.12 percent. This concentration indicates that while consolidated players hold significant influence, there remains ample room for specialized competitors and regional players to carve out niches. The strategies of leading companies reveal distinct approaches to value creation, ranging from product innovation and regulatory compliance to global supply chain integration.
Glass Fibers Market
Company Profiles and Strategic Moves
Several key enterprises define the competitive contours of the industry. Celanese stands as a benchmark for quality in thermoset reinforcement, offering emulsion polymers such as Resyn and Vinamul for glass fiber sizing. Their products are supplied to producers across Europe, the Americas, and Asia, emphasizing superior handling and composite performance. Michelman provides a comprehensive suite of film-forming dispersions, binders, and lubricants, including the Hydrolube series and FGLASS X90, specifically engineered for chopped and continuous fiberglass. Their solutions optimize protection, adhesion, and compatibility with both thermoplastic and thermoset resins. Notably, in February 2026, Michelman introduced Hydrosize 1202, a single sizing solution designed to serve both chopped strand and continuous fibers across various types, signaling a push toward versatility and process simplification.
Evonik Industries supplies silane-based DYNASYLAN and VPS additives that are critical for glass fiber sizing and protection. Their products prevent breakage during high-speed production and enable strong bonding with polymer matrices, addressing key pain points in manufacturing efficiency and composite quality. BYK, part of the ALTANA Group, produces MAH-grafted polymers and film formers exclusively for glass fiber sizing of chopped strands and continuous fibers. Their offerings are distinguished by the lowest VOC content available, enhancing mechanical properties in polyolefin composites while maintaining regulatory compliance. Production capabilities span Europe, the USA, and China, supporting a global customer base.
Covestro contributes to the market with Baybond waterborne polyurethane dispersions, which function as film formers and crosslinkers for glass fiber sizing. These products are tailored for protection and adhesion in thermoplastic and thermoset composites, with specific grades approved for food contact, reflecting the growing intersection of composite materials and consumer safety standards. Great Eastern Resins Industrial, based in Taiwan, manufactures aqueous polyurethane dispersions for fiberglass sizing agents characterized by high solid content, low viscosity, and excellent chemical and weather resistance, catering to specialized formulation needs. Emsland Group offers starch-based sizing solutions, such as the Emglass series derived from pea and potato starches, primarily for pre-sizing and warp sizing of glass fibers in the electronics industry textiles sector. This diversification into bio-based options highlights a broader industry trend toward sustainable raw materials.
Industry Dynamics: Regulation, Raw Materials, and Innovation
The operational environment for glass fiber sizing agents is shaped by a confluence of regulatory pressures, raw material considerations, and technological innovation. Regulation plays a pivotal role, with the EU REACH legislation driving the development of compliant chemicals in sizing formulations. This regulatory framework aims to enhance human and environmental protection while maintaining the performance standards required by composite manufacturers. Compliance is no longer a checkbox but a strategic differentiator, influencing formulation choices and supply chain decisions.
In terms of raw materials, sizing formulations typically comprise water, silane coupling agents for glass, film formers, and a suite of additives including surfactants, plasticizers, anti-static agents, antifoams, and rheology modifiers. These components are applied at a concentration of 0.5 to 5 percent of the composite weight, making the efficiency and selection of sizing agents critical to the overall economics and performance of the final product. The industry is witnessing a pronounced shift toward waterborne polyurethane dispersions, which support low-VOC and food-contact compliance under standards such as EU 10/2011. This transition aligns with broader sustainability goals and customer demands for safer manufacturing environments. Furthermore, the adoption of MAH-grafted polymer film formers from suppliers like BYK exemplifies the push for lowest VOC content, demonstrating how chemical innovation can address both performance and environmental objectives simultaneously.
Strategic Value of Comprehensive Market Intelligence
For organizations operating in or adjacent to the glass fiber sizing agent market, the complexity of these dynamics necessitates a depth of intelligence that goes beyond surface-level data. The strategic value of a rigorous market study lies in its ability to translate macro trends into actionable insights. Decision-makers need to understand not just the size of the market or the headline CAGR, but the underlying forces shaping segmentation growth, the specific technological advancements that are resetting competitive benchmarks, and the regional nuances that affect supply chain resilience and market entry strategies.
A detailed analysis provides the granularity required to identify high-growth pockets within the application landscape, evaluate the threat posed by regulatory shifts on specific chemistries, and assess the positioning of competitors who are leveraging innovation to capture market share. The data on market concentration, for instance, hints at the competitive intensity and the potential for consolidation or fragmentation depending on how companies respond to trends like bio-based sizing or low-VOC formulations. Similarly, understanding the regional revenue distributions helps in prioritizing investment in manufacturing capacity, sales infrastructure, and R&D focus.
Conclusion: Positioning for the Future
The glass fiber sizing agent market is poised for sustained growth through 2032, driven by the structural demands of lightweighting, renewable energy expansion, and advanced material requirements. However, realizing value in this environment requires more than passive observation. It demands a proactive strategy that integrates regulatory foresight, chemistry innovation, and application-specific expertise. Companies that can navigate the trade-offs between performance, cost, and compliance will be best positioned to thrive. The insights contained within our full market research report offer the comprehensive roadmap needed to make these strategic decisions with confidence. By delving into the detailed segmentation analysis, competitive profiling, and regional breakdowns, stakeholders can uncover the specific opportunities and risks that will define their success in the coming years. The market is moving forward; the question is whether your strategy is aligned with the trajectory of innovation and demand that lies ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Glass Fiber Sizing Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide 1-Decanol Market to Reach USD 436.36 Million by 2032 at 6.5% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Decade Ahead: Inside the Worldwide 1-Decanol Market Research 2026-2032
The global chemical landscape is undergoing a structural rewiring. Border adjustments, feedstock volatility, and sustainability mandates are no longer peripheral concerns; they are central drivers of competitive positioning. For executives navigating the specialty chemicals and oleochemical sectors, clarity on 1-Decanol requires more than a snapshot of today's prices. It demands a disciplined view of how capacity, regulation, and demand vectors will interact through 2032. Our newly released Worldwide 1-Decanol Market research is built for that purpose.
This introduction previews the analytical architecture of the report and explains why it is designed as a decision-grade instrument for 2026 strategy cycles. The objective is not to overwhelm with fragmented figures, but to equip leadership teams with a coherent framework for capacity planning, supplier selection, regulatory preparedness, and regional prioritization. Select data points are shared here to establish the report's scope and rigor. The complete segmentation, scenario modeling, and company-level intelligence are reserved for the full publication, where they can be evaluated in context.
Why This Research Matters for 2026 Decision-Making
2026 is a hinge year. Several forces converge: trade policy recalibration, evolving chemical safety requirements, and an accelerating shift toward certified sustainable feedstocks. Companies that rely on ad hoc market intelligence risk misreading margin trajectories, overcommitting to suboptimal sourcing routes, or underestimating compliance timelines. This report is structured to reduce those blind spots.
The study covers historical performance from 2020 through 2025 and extends forecasts to 2032. Revenue is expressed in USD Million. The framework integrates top-down market sizing with bottom-up validation from capacity announcements, feedstock behavior, and application-side demand signals. Rather than presenting a single line of forecast, the analysis layers in sensitivity considerations so that procurement, strategy, and finance teams can test how changes in input costs, trade tariffs, or certification adoption alter outcomes.
For 2026 specifically, the research translates macro trends into operational questions: Which applications are expanding fastest in volume versus value? Where do regional cost structures and regulatory burdens create advantage or risk? How should buyers balance natural versus synthetic sourcing in a year when sustainability claims and trade measures both carry financial weight? These are the questions the report is built to answer.
Market Trajectory: A Decade of Structural Growth
The market has moved through a clear growth arc. Between 2020 and 2025, revenue progressed from 205.14 to 280.8, reflecting consistent demand expansion across multiple end-use sectors. The trajectory does not plateau after 2025. The forecast indicates a rise to 290.35 in 2026, followed by continued expansion to 319.31 in 2027, 338.1 in 2028, 362.35 in 2029, and 409.71 in 2030. The path continues toward 395.7 in 2031 and reaches 436.36 by 2032.
The compound annual growth rate across the forecast horizon is 6.5 percent. That figure is not merely a headline; it is a planning anchor. For capital allocation, it suggests that demand volume will continue to justify capacity reinforcement and route optimization. For procurement, it signals that securing resilient supply chains will matter as much as unit price negotiation. For commercial teams, it frames the importance of aligning product grades and certifications with the applications that are driving incremental growth.
Importantly, the forecast is presented alongside the structural factors that could accelerate or temper realized outcomes. Feedstock behavior, certification adoption, and regulatory submission deadlines are integrated into the narrative so that readers can see where upside and downside pressures originate. The full report isolates these forces by region and application, but the overarching message is consistent: growth is durable, yet unevenly distributed across pathways.
Segmentation Logic and What the Numbers Reveal
A market of this scale only becomes actionable when it is decomposed correctly. The report segments the 1-Decanol market by region, by source, and by application, then cross-references these lenses to identify where volume, value, and strategic relevance are concentrated.
Regional Structure
The regional view captures how demand and production economics diverge across major markets. The study maps the relative weight of Asia Pacific, Europe, North America, Latin America, and the Middle East and Africa, then examines what drives those shares in terms of end-use demand, manufacturing footprint, and trade flows. Rather than presenting isolated percentage splits, the analysis connects each region to its dominant applications, its exposure to feedstock origins, and its sensitivity to policy changes. That approach helps leadership teams decide where to prioritize distributor relationships, where to monitor tariff exposure, and where certification requirements are most likely to alter sourcing strategies.
Source Pathways: Natural Versus Synthetic
The source segmentation distinguishes between natural oleochemical routes and synthetic petrochemical routes. The report quantifies the respective market contributions of each pathway and then explores the operational and strategic implications. The natural route is closely tied to fatty alcohol portfolios derived from vegetable oil feedstocks, while the synthetic route relies on processes designed for high-purity industrial grades.
This distinction matters for 2026 because the two pathways face different pressure points. Natural-sourced supply is influenced by vegetable oil markets and certification dynamics, while synthetic supply is shaped by petrochemical feedstock availability and process economics. The research does not treat these as interchangeable. It evaluates them as distinct strategic options with different risk profiles, sustainability narratives, and cost behaviors under changing conditions.
Application Demand: Where Value and Volume Intersect
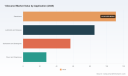
The application view breaks down the market across plasticizers, lubricants and greases, surfactants and detergents, and flavor and fragrances. The report examines not only how these segments compare in size, but also how their growth logic differs. Some applications are driven by industrial formulation requirements and process performance. Others are shaped by consumer-facing product trends, regulatory scrutiny, or downstream substitution dynamics.
By separating volume behavior from value behavior, the study helps clients identify where demand is structurally expanding versus where it is being reshaped by reformulation, certification, or regulatory compliance. That distinction is crucial for anyone planning product grades, packaging, or long-term offtake arrangements, because the same market size can hide very different underlying forces.
Competitive Landscape: Concentration, Capability, and Recent Moves
The 1-Decanol market is not fragmented in the way some commodity chemicals are. The report measures concentration and uses it to frame competitive behavior. The top three participants account for 42.5 percent of the market, while the top five collectively represent 61.8 percent. That level of concentration indicates that pricing, capacity signaling, and certification positioning can be influenced by a relatively small group of capable manufacturers, even as regional and application-specific niches create room for specialized players.
The study profiles the companies shaping this landscape, including BASF SE, Evonik Industries AG, KLK Oleo, Musim Mas Group, PT Sinar Mas Oleochemical, Eco Services Operations, LLC, and Godrej Industries Limited. Rather than offering generic corporate summaries, the report connects each profile to its strategic relevance in 1-Decanol: the applications it serves, the source pathway it emphasizes, and the geographic markets where its footprint matters most.
Recent company developments are integrated directly into the competitive analysis so that readers can interpret moves in context:
- In November 2024, KLK Oleo announced an expansion of fatty alcohol production capacity, including 1-Decanol, at its Seri Ulu Langat facility to meet Asia-Pacific demand.
- In September 2024, Evonik Industries received RSPO Mass Balance certification for sustainable 1-Decanol grades supplied to European markets.
- In June 2024, Musim Mas launched a high-purity 1-Decanol variant for pharmaceutical excipient applications.
These moves are not isolated news items. They illustrate three distinct strategic levers: capacity reinforcement in a high-growth region, sustainability certification to secure access to regulated demand, and grade specialization to enter higher-value application niches. The report evaluates each move in terms of its likely impact on regional supply balance, competitive positioning, and downstream procurement options.
Market Dynamics and External Pressures Shaping 2026 Outcomes
No forecast is useful if it ignores the environment in which it will play out. The research embeds market dynamics as active variables, not background commentary. Several developments are particularly relevant for 2026 planning.
Feedstock Volatility and Cost Exposure
Natural 1-Decanol production is closely linked to coconut oil and lauric acid markets. Coconut oil prices, a key feedstock for natural 1-Decanol, rose 12 percent to 1,450 per metric ton in the fourth quarter of 2025 due to supply constraints in the Philippines. At the same time, lauric acid, an upstream material for 1-Decanol hydrogenation, averaged 1,200 per metric ton FOB Indonesia in February 2026. These cost signals are presented in the report not as temporary noise, but as indicators of where margin pressure and sourcing resilience will be tested. The study maps how such movements affect the relative attractiveness of natural versus synthetic routes in different applications and regions.
Regulation and Compliance Timelines
Regulatory frameworks are becoming more prescriptive, and the report treats compliance as a strategic variable. EU REACH regulation requires 1-Decanol producers to submit updated exposure scenarios by the second quarter of 2026 for surfactant uses. That deadline has direct implications for suppliers serving European markets and for buyers who depend on those grades for downstream formulations. The analysis explains how submission requirements can affect time-to-market, grade availability, and the relative attractiveness of certified supply options.
The study also addresses labeling and consumer-product exposure. California Proposition 65 lists 1-Decanol for potential reproductive toxicity labeling in consumer products as of the 2025 update. While this does not equate to a blanket restriction, it introduces new considerations for formulation, risk communication, and product positioning in markets where consumer sensitivity and retailer standards are tightening. The report examines how such listings can alter demand patterns in sensitive applications without triggering broad market disruption.
Trade Policy and Regional Cost Structures
Trade measures continue to reshape cost competitiveness across regions. US tariffs on Chinese fatty alcohols, including 1-Decanol, increased to 25 percent under Section 301 in January 2026. For buyers and manufacturers with cross-border supply chains, this change alters landed-cost comparisons and may accelerate shifts toward alternative sourcing origins or regional supply partnerships. The report incorporates this development into its regional assessment so that teams can evaluate how tariff exposure interacts with existing logistics, certification status, and application requirements.
Worldwide 1-Decanol Market
What the Report Delivers: Practical Intelligence for Strategy Teams
The full research is organized to support concrete decisions rather than abstract observation. It combines market sizing, segmentation, competitive profiling, and environmental analysis into one integrated reference. The content is designed for use across strategy, procurement, sales, and compliance functions.
Key operational contents include:
- Historical market sizing and forecast pathways with explicit base year, historical coverage, and forecast horizon parameters
- Segment-level analysis by region, source, and application, presented with strategic interpretation rather than raw splits alone
- Company profiles that connect portfolio focus, geographic presence, and recent strategic actions to competitive impact
- A market concentration assessment that frames pricing influence, supply reliability, and niche positioning
- Integration of raw material trends, regulatory deadlines, and trade changes as decision-relevant variables
- Scenario-aware commentary that helps readers test how changes in feedstock costs, tariffs, or certification adoption could alter outcomes
The report is written for readers who need to move from insight to action. It does not simply describe the market; it explains where the leverage points are likely to be in 2026 and beyond, and where the risks of relying on outdated assumptions are greatest.
Who Should Use This Research and How
This study is most valuable for teams responsible for market entry, expansion, sourcing strategy, product grading, and regulatory readiness. For strategy leaders, it provides a structured view of where growth is concentrated and where competitive dynamics are intensifying. For procurement and supply chain teams, it offers context on source pathways, feedstock sensitivity, and the implications of certification and trade measures. For commercial and marketing teams, it clarifies application-side demand trends and the role of sustainability claims in securing preferred supplier status.
1-Octanol Market
The analysis is also intended to support coordination across functions. Because the report ties market structure to external pressures, it gives leadership a common reference point for discussing capacity commitments, supplier diversification, grade selection, and compliance timelines. That shared framework reduces the risk of decisions made in silos.
How to Read the Full Study for Maximum Value
The preview above highlights the structure and strategic logic of the research. What it does not do is expose the full density of the dataset. The complete report contains the detailed segmentation, regional interpretation, application-level trajectory, and company-specific intelligence needed to turn the macro view into operational plans. Those details matter because market growth is only useful when it is connected to where, how, and for whom it is occurring.
For teams preparing 2026 plans, the full publication provides the granularity required to evaluate sourcing trade-offs, anticipate regulatory impacts, and assess where competitor actions are likely to reshape supply and demand conditions. The macro figures establish the scale and growth rate of the opportunity. The segmented and company-level analysis explains how to position for it.
Closing Perspective
The Worldwide 1-Decanol Market research is built around a simple premise: in a market shaped by feedstock volatility, sustainability certification, trade policy, and regulatory deadlines, strategy quality depends on the depth of intelligence behind it. The market is expanding at a 6.5 percent CAGR through 2032, but the strategic story is not just about growth. It is about concentration, source pathways, application differentiation, and the external pressures that will determine which participants capture value most effectively.
This introduction offers the framework. The complete report delivers the full intelligence set needed to translate that framework into 2026 decisions. For organizations that need to move beyond general market awareness into precise, actionable planning, the full study is the next step.
For detailed analysis of this topic, please visit the official page: Worldwide 1-Decanol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Intelligence for the Next Decade: Navigating the Global Nefopam Hydrochloride Landscape
The global pharmaceutical market is undergoing a structural recalibration, driven by a dual mandate: the escalating crisis of opioid dependency and the simultaneous demand for robust, effective pain management protocols. Within this complex environment, the Worldwide Nefopam Hydrochloride Market presents a compelling case study of niche specialization meeting broad clinical necessity. As enterprise decision-makers finalize their strategic roadmaps for the 2026 fiscal year and beyond, understanding the nuances of this non-opioid analgesic sector is no longer optional—it is imperative.
To support this critical decision-making process, PW Consulting has released a comprehensive Worldwide Nefopam Hydrochloride Market Research report. This document serves as more than a static snapshot; it is a dynamic strategic tool designed to illuminate the path from 2025 through 2032. By synthesizing historical performance data with forward-looking projections, this research equips stakeholders with the intelligence required to mitigate risk, identify partnership opportunities, and capitalize on emerging regulatory and clinical shifts.
Market Trajectory and Quantitative Outlook
The macroeconomic signals surrounding Nefopam Hydrochloride indicate a steady, resilient growth trajectory. Based on historical data captured between 2020 and 2025, the market has demonstrated a consistent ability to expand despite broader pharmaceutical supply chain volatility. The baseline year of 2025 sets a robust starting point for the forecast period, with total revenue figures reflecting a mature yet expanding market presence.
Our analysis projects a Compound Annual Growth Rate (CAGR) of 5.5% over the forecast window extending to 2032. This growth rate suggests that while the market may not be experiencing hyper-exponential expansion, it possesses a stable, predictable upward momentum that appeals to long-term investors and supply chain planners. The projected revenue scale by the end of the forecast period underscores the increasing integration of Nefopam into standard pain management protocols globally. For strategic leaders, this trajectory implies a need to scale production capabilities and distribution networks in lockstep with this anticipated rise, ensuring that capacity constraints do not become bottlenecks for market capture.
Understanding these macro trends is essential, but granular visibility is where competitive advantage is won. Our report dissects the revenue streams not just by total volume, but by the specific structural components that drive value, allowing clients to pinpoint exactly where growth is originating and where margin pressure may develop.
Product Form and Application Dynamics
The market structure is defined by a bifurcation in product forms, primarily split between injectable solutions and oral tablet formulations. Each form factor serves distinct clinical pathways and operational requirements. Injections, often utilized in acute hospital settings for immediate pain relief, represent a significant portion of the revenue base, reflecting the high-intensity demand within surgical and emergency care environments. Conversely, tablets offer a pathway for outpatient management and chronic care regimens, providing a stable, recurring revenue stream that is less susceptible to the volatility of acute procedural volumes.
In terms of therapeutic application, the market is heavily anchored by Post-operative Pain Management. This segment remains the primary driver of volume, leveraging Nefopam's reputation as a non-opioid centrally-acting analgesic. Clinical data increasingly highlights its role in opioid-sparing strategies, where it helps reduce the total dosage of opioids required post-surgery—a metric that is becoming increasingly important for hospitals aiming to meet safety and recovery benchmarks. Beyond the operating theater, the report details the growing utilization in Chronic Pain Treatment and Acute Musculoskeletal Pain, segments that are expanding as clinicians seek alternatives to traditional NSAID or opioid therapies for long-term patient management.
Regional Revenue Concentration and Strategic Geography
Geographic diversification is a cornerstone of resilient market strategy. The research delineates revenue distribution across major global regions, revealing a landscape where established pharmaceutical markets hold significant weight, yet emerging regions present lucrative growth vectors. Europe currently commands a substantial share of the market revenue, underpinned by established healthcare infrastructure and favorable regulatory positioning for non-opioid analgesics within the EU member states.
Asia Pacific represents the next largest revenue block, reflecting both the massive patient population and the growing manufacturing capacity located within the region. Latin America and the Middle East and Africa, while currently representing smaller shares of the total revenue pie, offer strategic entry points for companies looking to expand their footprint in developing healthcare markets. For strategic planners, the key takeaway is not merely which region is largest, but how the growth rates differ across these geographies. The report provides the context needed to understand where regulatory hurdles might be lower, where reimbursement pathways are clearer, and where local manufacturing partnerships could yield the highest return on investment.
Competitive Landscape and Key Player Analysis
The Nefopam Hydrochloride market is characterized by a moderately concentrated competitive environment. With a CR3 of 58.4% and a CR5 of 74.2%, the market indicates that while there are dominant players, there remains room for specialized entrants and agile manufacturers to carve out niches. The barrier to entry is influenced significantly by regulatory certifications and the ability to maintain consistent API quality.
Several key companies define the current competitive architecture. Polpharma , based in Poland, stands out as a producer of Nefopam Hydrochloride API with a strong emphasis on regulatory compliance, holding GMP, EDMF/ASMF, and other certifications. They are positioned as an active commercial-scale supplier focused on the non-opioid analgesics sector. Similarly, PMC Isochem in France offers API manufacturing with CEP/COS and JDMF regulatory filings, catering to markets that require stringent European compliance documentation.
In the Indian pharmaceutical ecosystem, several manufacturers are active. Global Calcium operates as a manufacturer and exporter of Nefopam HCL, serving both domestic and international markets. Emcure Pharmaceuticals and Micro Labs Limited represent integrated and diversified healthcare companies with manufacturing capabilities for the API, while Maiden Group is engaged in the development and manufacturing of Nefopam-related products. Taj Pharma is notable for moving beyond API into finished formulations, manufacturing Nefopam Hydrochloride Injection and Tablet formulations. Additionally, Guangzhou Green Cross Pharmaceutical Co., Ltd. in China contributes to the global supply of Nefopam Hydrochloride API.
Other entities such as CF Pharma and PRG Pharma are listed as suppliers of the API, contributing to the broader supply chain availability. For procurement officers and business development teams, tracking the capacity expansions, certification renewals, and supply reliability of these specific entities is critical. The report provides detailed profiles and capability assessments for each, enabling stakeholders to vet potential partners or assess competitive threats with precision.
Recent Developments and Innovation Vectors
The landscape is not static; it is punctuated by specific events that can shift market positioning overnight. Our research integrates recent developments to provide a living view of the industry. In February 2025, Maxona Pharmaceuticals received a grant for their fifth patent regarding an optimized formulation of nefopam hydrochloride (MAX-001) intended for acute and chronic pain management, with plans for a Phase 2 clinical program. This signals ongoing R&D investment aimed at enhancing the therapeutic profile of the drug.
Worldwide Nefopam Hydrochloride Market
Simultaneously, clinical validation continues to accumulate. In June 2025, Siriraj Hospital published a randomized placebo-controlled double-blind clinical trial evaluating nefopam for analgesia following cardiac surgery. Positive outcomes in such specialized surgical contexts can accelerate formulary adoption and expand the addressable market within specific hospital networks. Furthermore, reimbursement and formulary positioning remain dynamic. In April 2025, the Lancashire and South Cumbria Formulary updated its new medicine assessment for Nefopam Hydrochloride 30 mg tablets, including cost and positioning data referencing the Drug tariff December 2024. In the UK, the drug tariff cost for a 90-tablet course is noted at £3.18 if taken daily as of December 2024, providing a concrete benchmark for cost-effectiveness analyses in that region.
Regulatory Framework and Market Access
Regulatory status is perhaps the most critical variable for international strategy. A key constraint identified in the market intelligence is that Nefopam Hydrochloride is not approved by the US FDA for marketing in the United States. This exclusion fundamentally shapes the strategic geography of the market, directing focus toward European, Asian, and other approved jurisdictions. Within the EU, Nefopam Hydrochloride 30 mg film-coated tablets hold nationally authorised medicinal product status in multiple countries under various marketing authorisation holders, including Crescent Pharma Limited and Generics [UK] Limited.
Additionally, regulatory nuances such as the paediatric investigation plan waiver granted by the EMA in January 2021 for a nefopam hydrochloride/paracetamol fixed-dose combination illustrate the evolving safety and usage profiles. Understanding these regulatory textures is vital for companies planning to launch new formulations or expand existing ones. Misalignment with local regulatory expectations can result in costly delays, making the regulatory analysis section of this report a high-value asset for compliance and market access teams.
Strategic Value for 2026 Decision-Making
Acquiring the Worldwide Nefopam Hydrochloride Market Research report is an investment in clarity amidst complexity. For 2026, the strategic priorities for pharmaceutical executives should revolve around three pillars: supply chain resilience, regulatory alignment, and clinical differentiation.
First, with revenue projections extending to 2032, manufacturers must assess whether their current production capacities for both API and finished formulations (injections and tablets) can meet the projected demand without compromising quality. The concentration levels in the market suggest that supply disruptions from key players could have outsized effects on the broader ecosystem.
Second, the regulatory landscape requires continuous monitoring. With specific approvals varying by region and the notable absence of US FDA approval, market entry strategies must be highly localized. Decision-makers need to know not just where the market is, but where it is legally permissible to operate, and where reimbursement structures support cost-effective patient access.
Third, clinical positioning is evolving. The reported opioid-sparing effect of 38% across reviewed studies provides a powerful value proposition for marketing and formulary committees. Aligning product messaging with this clinical benefit can differentiate offerings in a crowded analgesic market.
This report synthesizes these elements into a cohesive intelligence package. It moves beyond raw numbers to provide the narrative context necessary for strategic planning. Whether you are evaluating M&A targets, planning capacity expansion, negotiating supply contracts, or formulating market entry strategies, the granular data and competitive profiles contained within this research are designed to reduce uncertainty and accelerate decision velocity.
To access the full depth of segmentation data, complete competitive profiles, and detailed forecast models that underpin these insights, we invite you to download the complete Worldwide Nefopam Hydrochloride Market Research report from our portal. Equip your organization with the specific intelligence needed to lead in the 2026-2032 cycle.
Buprenorphine Hydrochloride Market
For detailed analysis of this topic, please visit the official page: Worldwide Nefopam Hydrochloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Pt Paste Market Hits $110M in 2025, Forecasts 6.45% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Imperatives in a High-Growth Niche: Unpacking the Worldwide Pt Paste for Gas Sensor Market Outlook Through 2032
The global landscape for platinum-based thick film materials is currently navigating a period of pronounced reconfiguration. For stakeholders operating within the gas sensor value chain, the convergence of escalating automotive electrification, tightening environmental emissions standards, and persistent precious metal supply constraints has created a complex decision-making environment. Our latest comprehensive research, Worldwide Pt Paste for Gas Sensor Market, delivers a rigorous, data-driven assessment of this specialized sector. By tracing performance trajectories from the historical base period through the 2026 to 2032 forecast horizon, this study transforms fragmented industry signals into a coherent strategic framework. The market documented in this report has expanded from approximately 74.5 million USD in 2020 to a projected 119.95 million USD in 2026, reflecting a compound annual growth rate of 6.45% across the entire forecast window. This trajectory is not merely an indicator of steady expansion; it signals a structural re-rating of a material segment that serves as a critical enabler for combustion monitoring, industrial safety systems, and next-generation environmental detection platforms. Understanding where value is accumulating, which formulation architectures are outpacing legacy technologies, and how leading suppliers are navigating raw material volatility is essential for capacity planning, partnership evaluation, and long-term margin protection.
Macro Trajectory and Structural Expansion Drivers
Over the past half-decade, the Pt paste for gas sensor sector has demonstrated consistent upward momentum, with revenue climbing steadily from 82.4 million USD in 2021 through 86.02 million USD in 2022 and 94.71 million USD in 2023. Growth accelerated notably as 2024 recorded 105.73 million USD, followed by a base-year valuation of 110.0 million USD in 2025. The forward-looking phase indicates sustained capitalization, with the market scaling to 122.34 million USD by 2027, crossing 127.97 million USD in 2028, and reaching 141.26 million USD by 2029. Continued upward progression brings the valuation to 148.6 million USD in 2030, advancing to 154.45 million USD in 2031, and ultimately approaching 170.38 million USD by 2032. This pattern reflects more than cyclical demand recovery. It is anchored by durable investment in sensor infrastructure across regulated emission environments, expanding deployment of oxygen and nitrogen oxide detection systems in modern powertrain architectures, and broadening industrial utilization of continuous gas monitoring networks. Simultaneously, the research highlights how formulation differentiation is reshaping competitive positioning. High-temperature co-fired ceramic architectures continue to capture a substantial share of fabrication workflows due to their robustness under extreme thermal cycling, while low-temperature variants and thick film alternatives are carving out specialized roles in applications requiring distinct sintering profiles, finer line resolution, or modified conductivity thresholds. The study systematically maps these technical dichotomies, providing engineering and procurement leaders with a clear view of how material selection influences yield, long-term stability, and total cost of ownership.
Worldwide Pt Paste for Gas Sensor Market
Techno-Commercial Segmentation and Application Value Mapping
A central strength of this analysis lies in its ability to connect material architectures to end-use requirements without reducing complex engineering trade-offs to oversimplified comparisons. The report dissects the revenue distribution across primary categorization dimensions, revealing how distinct product families align with specific sensor performance mandates. High-temperature co-fired ceramic platinum paste formulations remain the dominant technical pathway, supported by their compatibility with aggressive firing schedules and proven reliability in harsh gas detection environments. Low-temperature co-fired ceramic variants represent a strategically important alternative, particularly where thermal budget constraints, substrate limitations, or multi-layer integration requirements dictate a gentler processing window. Thick film platinum paste solutions round out the landscape, offering manufacturers flexibility in screen-printing parameters, line definition, and post-firing conductivity characteristics. On the application side, the research underscores the heavy weighting of automotive oxygen and nitrogen oxide sensor deployments within overall consumption patterns, reflecting the ongoing tightening of tailpipe emissions regulations and the gradual but persistent penetration of advanced exhaust monitoring architectures. Industrial gas monitoring applications form a significant secondary pillar, driven by process safety mandates, chemical handling requirements, and facility environmental compliance programs. Environmental and home safety sensor deployments, while representing a smaller fraction of total material consumption, are gaining strategic relevance as residential and commercial building standards increasingly integrate continuous air quality and leak detection systems. By presenting these relationships through structured comparative frameworks rather than isolated percentage breakdowns, the study equips strategy teams with the analytical depth required to evaluate where capacity expansion, technology licensing, or targeted sales investments will generate the highest marginal returns.
Competitive Architecture and Supplier Capability Assessment
The vendor landscape for Pt paste in gas sensor applications is characterized by a concentrated yet highly differentiated competitive field. Our proprietary market concentration analysis indicates that the top three participants collectively command approximately 58.2% of industry revenue, while the leading five firms extend their combined footprint to roughly 74.5%. This concentration does not imply a homogeneous market. Rather, it reflects divergent material science competencies, regional manufacturing footprints, and specialized formulation capabilities that reward deep technical alignment over generalist positioning. Japanese materials specialists have built strong reputations by offering a broad portfolio of screen-printable platinum chemistries, ranging from low-resistance variants optimized for electrode and heater structures to high-resistance configurations tailored for thermal management subsystems. Their product engineering emphasizes high-temperature firing compatibility, RoHS-compliant compositions, and tightly controlled particle size distributions that support consistent print fidelity and reproducible electrical characteristics. European technology providers contribute complementary capabilities through thick film conductor systems that incorporate pure platinum and platinum-containing alloy architectures for gas sensing, positional sensing, and temperature measurement applications. Their recent documentation enhancements have further clarified performance parameters for solderable AuPtPd conductor pastes, highlighting surface uniformity, chemical resistance, and post-fabrication solderability as critical considerations for fuel sensor integration. British material developers have carved out distinct positioning with fritted platinum conductor pastes engineered for zirconia oxygen sensor circuitry and high-temperature dielectric substrates. Their formulations support firing windows spanning 850 to 1300 degrees Celsius, fine-line printing capability down to approximately 100 micrometers, and dense fired layer formation on alumina and advanced ceramic platforms. Additional participants from North America, Europe, and Asia extend the strategic portfolio through precision thick film engineering, platinum group metal recycling expertise, electrochemical material support, and specialized paste formulations targeting flat oxygen sensors and solid oxide fuel cell interfaces. The report evaluates these capabilities through a structured lens, enabling procurement leaders to benchmark particle fineness, solid content ratios, firing profile tolerance, and alloy customization potential against application-specific performance thresholds.
Material Economics, Regulatory Alignment, and Supply Chain Resilience
No strategic assessment of Pt paste demand can be conducted without addressing the upstream economics that govern cost structure and margin durability. Platinum metal serves as the foundational feedstock for paste production, with catalytic specifications, surface area requirements, and particle morphology commanding material premiums that directly influence formulation economics. The broader platinum supply environment has reinforced this sensitivity. Market data from recent reporting cycles highlights a third consecutive year of significant supply shortfall in 2025, with primary supply declining approximately 3% amid constraints in South African PGM output. This structural tightening coincided with a sharp price escalation through the year, driven by persistent deficits, geopolitical risk premiums, and reduced above-ground inventory levels. These dynamics elevate the strategic importance of sourcing discipline, hedging frameworks, and closed-loop recycling programs for manufacturers reliant on high-performance platinum architectures. At the same time, regulatory alignment remains a non-negotiable requirement for global market access. Contemporary Pt paste formulations must satisfy RoHS2 directive restrictions on lead and regulated substances, meaning that supplier qualification increasingly hinges on documented lead-free production standards, verified compliance documentation, and transparent material disclosures. The research integrates these feedstock, pricing, and compliance variables into a cohesive cost-risk narrative, helping organizations distinguish between temporary price fluctuations and longer-term structural pressures that require strategic inventory planning, dual-sourcing architecture, or formulation re-engineering. By treating raw material volatility as a strategic design parameter rather than a peripheral procurement concern, the study provides executive teams with the context needed to protect profitability across the full forecast horizon.
Operational Intelligence Built for 2026 Decision Cycles
This market study is designed to function as an operational reference for cross-functional teams that must translate market signals into executable strategy. The report delivers granular technology roadmaps that connect paste architecture choices to sensor performance expectations, integrating firing behavior, electrical conductivity profiles, adhesion characteristics, and compatibility with high-temperature dielectric substrates. It maps procurement pathways across formulation sourcing, alloy customization, and powders-to-paste manufacturing integration, allowing leadership to evaluate which supplier relationships offer the strongest alignment with volume scaling, technical support depth, and regulatory documentation standards. Competitive benchmarking modules assess product range breadth, application-specific customization capacity, and regional service infrastructure, giving strategy teams a structured way to compare incumbents and emerging participants without relying on superficial marketing claims. The analysis also incorporates forward-looking scenario modeling that links automotive emissions roadmap shifts, industrial monitoring adoption rates, and environmental safety sensor proliferation patterns to demand sensitivity across different formulation families. Combined with recent supplier documentation updates, market commentary on platinum deficits, and evolving compliance expectations, the study provides a consolidated platform for revenue forecasting, capacity planning, and risk-adjusted partnership evaluation. Decision-makers in manufacturing, R&D, supply chain governance, and corporate strategy will find a consistent analytical language that connects technical specifications, regional execution realities, and commercial viability within a single evaluative framework.
Electrode Paste Market
Why This Research Matters for 2026 Strategy Formation
The worldwide Pt paste for gas sensor market is entering a phase in which historical benchmarks and incremental forecasting are no longer sufficient for competitive advantage. Growth measured at a 6.45% CAGR across the 2026 to 2032 window, supported by a projected market trajectory advancing toward 170.38 million USD by the end of the forecast period, reflects durable structural demand rather than temporary expansion. Yet the real strategic challenge lies in identifying which formulation pathways, application segments, and supplier ecosystems will compound value most efficiently under realistic constraints of feedstock pricing, firing-process compatibility, and regulatory compliance. Our research removes ambiguity from that evaluation by delivering a complete diagnostic of technology differentiators, competitive concentration dynamics, and application-led demand sensitivities. This publication is structured to support direct integration into 2026 planning cycles, empowering stakeholders to align R&D roadmaps with material performance realities, optimize procurement exposure in a constrained platinum environment, and prioritize partnerships that translate formulation expertise into measurable cost and reliability advantages. Organizations that treat Pt paste selection as a strategic capability rather than a commoditized input will be best positioned to capture share in a market where technical differentiation and supply resilience increasingly determine long-term commercial outcomes.
For detailed analysis of this topic, please visit the official page: Worldwide Pt Paste for Gas Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Global Rail Components Market Reaches $72.45 Billion in 2025 to Hit $99.6 Billion by 2032 at 4.65% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Railway Era: Inside the Worldwide Rail Components Market 2026-2032
Executive Overview
The global railway components sector stands at a critical inflection point. As governments and private operators accelerate fleet modernisation, signalling digitisation, and heavy-haul capacity expansion, procurement leaders face a complex matrix of material volatility, evolving regulatory mandates, and shifting demand centres. Our latest Worldwide Rail Components Market study is designed to cut through this complexity, delivering a decision-ready intelligence framework that maps revenue trajectories, competitive positioning, and structural catalysts across the decade. Rather than offering static snapshots, the report translates historical momentum into forward-looking scenario planning, enabling executives to align capital allocation, supply chain resilience, and partnership strategy with verified market mechanics.
The Trajectory of Global Market Expansion
Historical revenue patterns reveal a market that has demonstrated remarkable resilience amid macroeconomic turbulence, supply chain realignments, and fluctuating infrastructure budgets. From 2020 through 2025, worldwide components revenue climbed from approximately 58.12 billion USD to a base-year level near 72.45 billion USD, reflecting sustained maintenance backlogs, fleet renewal cycles, and targeted public investment in high-capacity corridors. The forecast window extends through 2032, anchored by a compound annual growth rate of 4.65 percent and a projected end-period valuation approaching 99.6 billion USD. This trajectory is not linear; it is shaped by procurement pacing, delivery lead-time normalisation, and the interplay between legacy fleet upkeep and next-generation platform adoption. Readers examining the full report will encounter granular year-by-year revenue mapping that isolates organic volume growth from pricing effects, enabling precise budget forecasting and sensitivity testing across multiple procurement horizons.
Regionally Anchored Demand Patterns
Market activity does not distribute uniformly across geographies. Asia Pacific continues to command the largest absolute revenue share, driven by high-speed network rollouts, metro system expansions, and domestic manufacturing scale. Europe maintains a substantial footprint shaped by cross-border interoperability requirements, signalling modernisation, and regulated tender cycles. North American component consumption remains tightly coupled to freight network efficiency programmes, heavy-haul infrastructure upgrades, and locomotive fleet optimisation. Latin America and the Middle East & Africa collectively represent growing but structurally distinct opportunity pools, often influenced by concession models, sovereign funding priorities, and targeted component substitution initiatives. The complete study breaks down regional revenue architecture without oversimplifying local procurement realities, mapping demand intensities, delivery channel preferences, and policy-driven procurement windows. Decision-makers requiring jurisdiction-specific pricing contexts, tender cycle timing, and regional supplier concentration metrics will find the full dataset essential for market entry, sourcing diversification, and partnership sequencing.
Worldwide Rail Components Market
Component Architecture and Train-Type Demand Correlations
The components landscape is defined by technical specialisation, lifecycle economics, and platform compatibility. Bogie and wheelsets constitute the largest component revenue segment, reflecting their centrality to ride quality, load distribution, and track interface performance. Propulsion and power systems follow closely, underscoring the industry-wide shift toward electrification, energy-efficient traction designs, and integrated power management architectures. Braking systems maintain a robust share, propelled by safety regulation mandates, friction material innovation, and retrofit demand on mature fleets. Interior and body structures, alongside couplers and ancillary hardware, round out the component palette, each responding to tailored operational profiles and route-specific performance requirements. Demand further diverges by train type, with passenger rolling stock capturing the broadest revenue pool, freight wagons sustaining steady procurement tied to logistics volume and wagon lifecycle replacement, and locomotives reflecting concentrated but high-value expenditure on traction, control, and reliability upgrades. Our full analysis dissects these relationships with component-level revenue mapping, technical substitution trends, and platform-specific procurement drivers, allowing engineering and sourcing teams to align specification strategies with verified demand patterns rather than generalised assumptions.
Competitive Dynamics in a Consolidated Landscape
The supplier ecosystem is characterised by meaningful concentration, yet it remains highly differentiated by technical capability, geographic reach, and vertical integration depth. Industry concentration metrics indicate that a relatively small group of multinational players commands a substantial share of total revenue, creating a market environment where scale, certification portfolios, and platform-standard compliance heavily influence winning positions. Alstom maintains a broad components portfolio spanning bogies, braking solutions, pantographs, couplers, and signalling-related hardware, with a strong foothold across both passenger and freight applications. Siemens Mobility reinforces its position through electrification, signalling, automation, and traction component offerings that increasingly intersect with digital rail operations. Wabtec Corporation and Knorr-Bremse compete at the core of braking, friction, and auxiliary system markets, while voestalpine Railway Systems holds notable influence in rail profiles, switches, turnouts, and track-side monitoring solutions. Thales contributes critical signalling, communication, and security technologies that increasingly shape component specification by enabling interoperability and operational automation. CRRC Corporation Limited and Hitachi Rail extend competitive pressure through high-speed and freight traction components, digital signalling integration, and large-scale platform supply capabilities. Additional specialists such as Lucchini RS, Greenbrier Companies, Trinity Industries, Titagarh Rail Systems, Stadler Rail, Nippon Steel, and ArcelorMittal Rails & Accessories reinforce the market with focused expertise in wheelsets, freight car structures, underframes, regional bogie designs, premium rail steels, and global infrastructure profiles.
Recent Catalyst Events Reshaping the Supplier Landscape
Recent corporate activity demonstrates how quickly competitive advantage can be reconfigured through product launches, strategic acquisitions, certification wins, and platform-level joint development. Siemens Mobility advanced driverless operational readiness by introducing GoA4 automation platform components for unattended rail operations, signalling a structural shift toward higher levels of automation in metro and regional contexts. Knorr-Bremse expanded its compact braking footprint by acquiring VYC Industrial, strengthening its portfolio for metro vehicle brake calipers and related subsystems. voestalpine achieved AREMA certification for its 390HH premium rail, reinforcing its eligibility for North American heavy-haul deployments and illustrating how standards compliance directly unlocks market access. Wabtec secured a supply agreement with Union Pacific for Trip Optimizer software and friction products, highlighting the growing intersection between digital optimisation tools and mechanical component supply. Alstom formalised a joint development agreement with Indian Railways to develop indigenous bogie designs, reflecting a broader push toward localisation, design sovereignty, and platform-specific engineering partnerships. The complete report places these events within a structured competitive analysis, mapping each move to market share implications, capability expansion, and downstream procurement effects.
Rail Market
Regulatory, Material, and Sustainability Forces Redefining Procurement
Beyond vendor dynamics, external forces are reshaping specification priorities, cost structures, and delivery planning. Raw material pressures remain a persistent concern, with pearlitic rail steel prices climbing year over year in Europe as energy costs and input volatility continue to influence alloy pricing. At the same time, demand for bainitic rail steels has risen for high-speed applications, reflecting performance requirements that reward durability and reduced maintenance overhead. On the regulatory front, the EU TSI LOC&PAS framework mandates ERTMS Baseline 3 compliance for new signalling components from 2025, creating a clear technical threshold that influences specification cycles and supplier qualification. In the United States, FRA requirements for PTC 2.0 interoperability introduce additional interoperability expectations across Class I networks, affecting both onboard and wayside component planning. From a trade and sustainability angle, the EU Carbon Border Adjustment Mechanism introduces meaningful cost implications for imported rail steel with embedded carbon intensity beginning in 2026, prompting procurement teams to reconsider sourcing geography, material certification, and lifecycle carbon accounting. The full study translates these dynamics into actionable procurement implications, linking regulatory deadlines, material pricing trends, and sustainability requirements to real-world sourcing and specification decisions.
What the Study Delivers for Strategic Decision-Makers
This research is built for executives, procurement directors, engineering leads, and competitive intelligence teams who require more than headline figures. The report integrates revenue forecasts, historical baselines, segmentation architecture, concentration metrics, and company-level profiling into a cohesive market operating picture. Readers will gain access to component-level demand mapping, train-type revenue correlations, regional consumption structures, and supplier capability comparisons, all organised to support scenario planning and internal alignment. The study also captures recent corporate developments that matter for sourcing strategy, including automation platform introductions, acquisition-driven capability expansion, standards-based certification milestones, major contract awards, and joint development agreements that signal localisation trends. By connecting these events to broader market structure, the report helps teams evaluate not just where revenue is heading, but who is best positioned to capture it and under what procurement conditions.
Conclusion: Why This Intelligence Matters for 2026 and Beyond
The worldwide rail components market is moving through a period where technical compliance, material economics, regional procurement rhythms, and competitive consolidation all influence winning strategy. For organisations planning fleet investments, component sourcing, platform specification, or market expansion, the difference between reactive and proactive decision-making lies in the quality of the underlying intelligence. Our Worldwide Rail Components Market study provides that foundation, combining verified market sizing, structured segmentation, competitive profiling, and regulatory context into a decision-ready format. To access the complete dataset, detailed segmentation breakdowns, and full company-level analysis, we invite readers to visit the source page and download the full report. In a market defined by long asset lifecycles and fast-moving specification requirements, timely intelligence is not an accessory to strategy; it is the basis of it.
For detailed analysis of this topic, please visit the official page: Worldwide Rail Components Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cephalosporin Intermediates Market Projected to Reach USD 567 Million by 2032 at 5.4% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence Report: Navigating the 2026-2032 Cephalosporin Intermediates GCLE Market
The global pharmaceutical supply chain stands at a critical inflection point. As we move beyond the volatility of the early 2020s, the demand for essential antibiotic intermediates has stabilized into a trajectory of steady, calculated growth. For stakeholders in the pharmaceutical manufacturing sector, understanding the nuances of the Cephalosporin Intermediates GCLE Market is no longer optional; it is a prerequisite for resilient strategic planning. This article serves as an executive preview of our latest comprehensive market research, designed to equip leadership teams with the foresight needed to navigate the forecasting period of 2026 through 2032.
Our analysis indicates that the market is poised for expansion, driven by persistent healthcare demands and evolving manufacturing dynamics. However, surface-level growth figures often mask the complex interplay of raw material dependencies, regional concentration risks, and competitive maneuvering that define actual profitability. This report dissects those layers, offering a granular view of where value is created and where vulnerabilities lie.
Market Trajectory and Historical Context
The foundation of any strategic forecast lies in a robust understanding of historical performance. Our research tracks the market revenue from 2020 through the base year of 2025, providing a five-year historical lens against which future projections are calibrated. The data reveals a market that has demonstrated resilience despite global logistical disruptions. Starting from a valuation of approximately 312.45 Million USD in 2020, the sector climbed to 392.36 Million USD by 2025. This upward trend underscores the inelastic demand for cephalosporin antibiotics, which remain a cornerstone of global infectious disease treatment protocols.
Cephalosporin Market
Looking forward, our forecast models project a consistent Compound Annual Growth Rate (CAGR) of 5.4 percent over the forecast period. By 2032, the market is expected to reach a valuation of 566.97 Million USD. While these macro figures suggest a healthy environment, the strategic value for decision-makers lies in understanding the velocity and sustainability of this growth. A 5.4 percent CAGR implies a maturing market where share gain becomes increasingly difficult, shifting the focus from pure volume expansion to efficiency, quality differentiation, and supply chain security. The transition from the historical period to the forecast period marks a shift from recovery to optimization, requiring firms to adapt their capital allocation strategies accordingly.
Cephalosporin Intermediates GCLE Market
Operational Deep Dive: Report Contents and Methodology
To support high-stakes decision-making, this research report moves beyond top-line estimates. It is structured to provide actionable intelligence across several critical dimensions. The methodology integrates primary interviews with industry participants and secondary research from regulatory filings, trade analyses, and technical literature. The following components define the scope of our operational analysis:
- Segmentation by Product Grade: The market is bifurcated into High Purity Grade, defined as above 99 percent, and Standard Grade, typically at 98 percent. The report analyzes the revenue contribution and strategic importance of each grade, highlighting how purity specifications influence downstream API manufacturing costs and regulatory compliance.
- Application-Specific Demand: We examine the consumption patterns across key synthesis pathways, including Cefixime, Cefdinir, Cefprozil, and Cefcapene Pivoxil. Understanding the specific demand drivers for each antibiotic synthesis route allows manufacturers to align production capacities with the most lucrative therapeutic segments.
- Regional Distribution Analysis: The study maps revenue flows across major geographical zones. While Asia Pacific remains a dominant force in volume, the report details the strategic nuances of Europe, North America, Latin America, and the Mideast and Africa, focusing on import dependencies and local manufacturing capabilities.
- Supply Chain Risk Assessment: A dedicated section evaluates the vulnerabilities in the raw material supply chain, specifically focusing on the procurement of key precursors and the impact of logistical factors on export expenses.
This structure ensures that readers do not merely see the size of the pie, but understand the ingredients, the bakers, and the distribution channels. For procurement officers and supply chain managers, the segmentation data offers a blueprint for negotiating contracts and securing supply lines. For strategic planners, the regional analysis highlights where capacity expansion might yield the highest return on investment relative to regulatory environments.
Competitive Landscape and Key Players
Market concentration is a vital indicator of competitive intensity and pricing power. Our analysis identifies a moderately concentrated market structure, where the top three players hold a significant portion of the revenue share, and the top five entities command a majority of the market. This concentration suggests that while there is room for new entrants, established players benefit from economies of scale and established supply chain relationships, particularly regarding critical raw materials.
The competitive field is characterized by specialized manufacturers who have invested heavily in the specific chemical synthesis routes required for GCLE production. Key companies shaping the landscape include:
- Otsuka Chemical Co., Ltd.: Headquartered in Osaka, Japan, this firm is a primary developer and manufacturer of GCLE. They operate dedicated production facilities, including a plant in India, positioning them as a critical link in the β-lactam intermediate supply chain. Their long-standing expertise makes them a benchmark for quality and technical capability.
- CSPC Cenway Tianjin Pharmaceuticals Co., Ltd. and Tianjin Gencom Pharmaceutical Co., Ltd.: Based in Tianjin, China, these entities are active suppliers of GCLE intermediates for cephalosporin API production. Their presence underscores the significance of the Tianjin region as a hub for pharmaceutical intermediates.
- Tianjin Jinkang, Ningbo Renjian Pharmaceuticals, Shandong Ruiying Pharmaceutical Group, Jiangsu Haici Biopharmaceuticals, and Xindi Bio: These listed global manufacturers represent a broad swath of production capacity across China. Their involvement in the GCLE market highlights the competitive pressure on pricing and the importance of scale in securing raw material contracts.
- Virchow Group / Virchow Petrochemicals Private Limited: Operating out of Telangana, India, this group manufactures and supplies GCLE for cephalosporin intermediates. Their presence adds a layer of diversification to the supply base outside of China, which is strategically relevant for buyers seeking to mitigate geographic concentration risk.
- Otsuka Chemical (India) Private Limited: Located in Haryana, this entity serves as a manufacturing plant focused on GCLE production, extending the Japanese parent company's reach into the Indian market, which is a key production base for export-oriented cefixime.
The presence of both Japanese technology leaders and large-scale Chinese manufacturers creates a dynamic competitive environment. Buyers must navigate the trade-offs between technical precision, cost efficiency, and supply security. The report provides detailed profiles on these entities, analyzing their production capacities, strategic positioning, and potential vulnerabilities.
Critical Market Dynamics and Constraints
Strategic decisions cannot be made in a vacuum. The GCLE market is subject to specific structural constraints and regulatory dynamics that significantly influence margin potential and supply reliability. Our research highlights several critical factors that industry leaders must monitor closely during the 2026-2032 period.
Raw Material Dependency and Penicillin-G: A fundamental constraint in GCLE production is the reliance on Penicillin-G as the key raw material. Industry data indicates that this precursor is entirely procured from China with no alternative sources currently available at scale. This creates a single-point-of-failure risk in the supply chain. Historical technical literature notes that domestic Chinese processes have faced challenges regarding high costs and quality issues in the past, leading to periods of continued reliance on imports in certain contexts. This dependency means that any disruption in the Penicillin-G supply chain directly impacts GCLE availability and pricing.
Regulatory Schemes and Export Orientation: Regulatory frameworks play a pivotal role in shaping market flows, particularly in India. Advanced authorization schemes have been implemented that allow GCLE suppliers to import Penicillin-G without minimum import price restrictions for export-oriented cefixime production. This regulatory nuance is crucial for manufacturers operating in India, as it affects the landed cost of raw materials and the competitiveness of the final exported product. Understanding these regulatory levers is essential for cost modeling and margin protection.
Logistical Factors and Regional Dominance: China dominates the export of cephalosporin API and intermediates. However, this dominance is not without friction. Logistical factors such as high international shipping costs and container shortages have historically affected export expenses. While supply chains have adapted, the potential for renewed logistical volatility remains a risk factor that must be priced into long-term contracts. The report analyzes how these logistical realities interact with regional market sizes to determine true net revenue potential for exporters versus domestic consumers.
Strategic Implications for 2026 and Beyond
As we enter the forecast period, the strategic imperative shifts from navigating crisis to managing growth amidst constraints. The projected growth from 397.57 Million USD in 2026 to nearly 567 Million USD by 2032 offers opportunity, but realizing this value requires sophisticated management of the underlying dynamics.
For procurement leaders, the concentration of raw material sourcing in China necessitates dual-sourcing strategies where possible, or stronger contractual safeguards with existing suppliers. For production planners, the distinction between High Purity and Standard Grade segments offers a pathway to margin improvement, as high-purity grades often command premium pricing in regulated markets. For executives evaluating market entry or expansion, the regional concentration suggests that proximity to key API manufacturing hubs in Asia Pacific may offer logistical advantages, though regulatory access in North America and Europe remains a key value driver.
Furthermore, the competitive landscape indicates that consolidation may continue as larger players leverage their scale to secure raw material advantages. Smaller players may need to find niches in specific application segments, such as Cefcapene Pivoxil Synthesis, where volume requirements are lower but specialization is higher. The interplay between the top five companies and the broader field of listed manufacturers will define price stability and innovation rates in the coming years.
Conclusion: The Value of Precision Intelligence
In a market defined by specific technical requirements, raw material dependencies, and regional regulatory nuances, general market intelligence is insufficient. Success in the Cephalosporin Intermediates GCLE Market during the 2026-2032 period will belong to those who understand the granular details of supply chain vulnerabilities, competitive capabilities, and segmentation dynamics.
This report provides the framework for that understanding. It bridges the gap between high-level market sizing and the operational realities of manufacturing and procurement. However, the full depth of the data, including precise revenue splits by region and application, detailed company profiles, and specific risk mitigation strategies, is contained within the full research document. For organizations committed to securing their supply chains and optimizing their market position, accessing the complete intelligence is the next logical step.
We invite stakeholders to review the full report to leverage these insights for their 2026 strategic planning cycles. The data presented here is the foundation; the complete analysis is the tool required to build a resilient future in the global pharmaceutical intermediates market.
For detailed analysis of this topic, please visit the official page: Cephalosporin Intermediates GCLE Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
5.4% CAGR: Worldwide Vorinostat Market Reaches $312.42 Million by 2032
By pmarketresearch, 2026-09-16
Strategic Horizons in the Worldwide Vorinostat Market: A 2026 Perspective
The global oncology therapeutics landscape is undergoing a period of structural transition, driven by shifting patent regimes, expanding generic footprints, and evolving clinical guidelines. Within this environment, vorinostat remains a foundational histone deacetylase inhibitor, anchoring both historical treatment paradigms and emerging research applications across hematologic and solid tumor domains. As corporate planners, procurement leaders, and R&D strategists look toward 2026 and beyond, understanding the trajectory of this specialized market requires more than headline figures. It demands a disciplined examination of competitive positioning, regulatory tailwinds, manufacturing economics, and the subtle interplay between branded legacy products and cost-optimized alternatives. Our latest Worldwide Vorinostat Market study is designed to deliver precisely that operational intelligence, equipping decision-makers with the analytical rigor needed to navigate a market defined by steady expansion and intensifying portfolio competition.
This introduction previews the strategic architecture of the full report, highlighting the analytical dimensions that matter most for enterprise planning in 2026. Rather than offering surface-level volume snapshots, the publication dissects the forces shaping demand elasticity, pricing friction, supply-chain resilience, and therapeutic substitution patterns. The objective is clear: provide a reliable foundation for capacity allocation, market-entry sequencing, partnership evaluation, and portfolio prioritization in a therapeutic area where clinical advocacy, reimbursement alignment, and generic penetration converge.
The Macro Trajectory: A Verified Expansion Curve
From a strategic standpoint, the most immediate takeaway for planners is the consistency of the market’s upward momentum. Historical tracking from 2020 through 2025 demonstrates a resilient revenue arc that has weathered supply disruptions, regulatory recalibrations, and shifting procurement preferences. Starting from a baseline of approximately 172.5 million USD in 2020, the market progressed through year-over-year gains that reflect sustained utilization in cutaneous T-cell lymphoma management and incremental absorption by adjacent oncology research channels. By 2025, the recorded revenue reached roughly 216.2 million USD, establishing a credible platform for the forecast window.
The projection period spanning 2026 through 2032 extends this trajectory with measured confidence. The forecast anticipates growth advancing toward 228.99 million USD in the immediate outlook year and continuing upward to approximately 312.42 million USD by the close of the decade. This path corresponds to a compound annual growth rate of 5.4 percent, a pace that signals durable, rather than speculative, demand creation. For enterprise strategists, the implication is twofold. First, the expansion is robust enough to justify sustained investment in distribution infrastructure, clinical support programs, and market access initiatives. Second, the moderate growth rate underscores the importance of share capture, formulation differentiation, and pricing strategy, as incremental gains will likely be contested among established manufacturers and emerging generic suppliers rather than generated solely by volume expansion.
Strategic readers will recognize that a mid-single-digit CAGR in a niche oncology segment carries distinct planning implications. It invites disciplined resource deployment rather than aggressive overexpansion. It also rewards early visibility into regional procurement cycles, formulary inclusion timelines, and therapeutic interchange dynamics. The full report translates these macro signals into actionable frameworks, enabling teams to align capacity commitments with realistic demand windows and to calibrate competitive responses ahead of product-cycle inflection points.
Segment Architecture and the Logic of Demand Distribution
A market with a specialized therapeutic anchor inevitably concentrates value along specific formulation and indication pathways. Understanding where utilization is structurally concentrated, and why, is essential for actors evaluating manufacturing priorities, labeling strategy, or commercial launch sequencing. The analysis in our study maps these structural concentrations without reducing them to simplistic proportional breakdowns. Instead, it examines the operational logic behind formulation preferences, the therapeutic rationale driving application mix, and the regional factors that shape purchasing behavior.
From a formulation perspective, the market exhibits a clear dominance pattern in capsule-based delivery relative to powder formats. This distribution reflects both clinical convenience and established prescribing habits, particularly within localized treatment protocols where oral administration aligns with patient adherence objectives and outpatient management models. At the same time, powder-related demand persists in specialized research and compounding contexts, where formulation flexibility, dosing adjustments, and investigational protocols sustain a distinct but meaningful utilization footprint. The report evaluates how these formulation splits translate into manufacturing requirements, packaging investments, and supply-chain configuration choices, allowing readers to assess the operational consequences of the current demand architecture.
By application, the market’s center of gravity clearly lies in the management of cutaneous T-cell lymphoma, a segment that draws on the drug’s long-standing regulatory history and clinical guideline recognition. The inclusion of vorinostat in authoritative oncology treatment frameworks reinforces its positioning within relapse and refractory scenarios, supporting sustained prescription continuity where alternative options may be limited. Alongside this core oncology indication, secondary demand channels in broader oncology research and HIV latency investigation contribute additional, though comparatively smaller, utilization vectors. These ancillary applications matter strategically because they connect vorinostat to innovation pipelines, academic partnerships, and exploratory trial activity that can influence future label discussions, off-label utilization norms, and cross-therapeutic R&D attention.
The regional composition of demand further shapes commercial planning. In global terms, the market reflects a distribution pattern in which certain mature markets carry disproportionate revenue weight, while emerging procurement regions contribute incremental but strategically significant volume. The study examines these geographic layers through the lens of regulatory maturity, generic availability, formulary integration, and purchasing centralization, offering planners the context needed to prioritize outreach, adapt positioning, and anticipate timing differences across markets. Rather than presenting static regional shares in isolation, the report situates each zone within its own procurement rhythm and policy environment, enabling a more practical reading of where growth will materialize and how resistance or acceleration may unfold.
Competitive Dynamics: Branded Legacy, Generic Momentum, and Strategic Response
The vorinostat competitive landscape is defined by the interaction between a historic originator and a growing roster of generic manufacturers. This structure is central to market behavior in 2026 because it directly affects pricing benchmarks, procurement negotiations, supply reliability, and portfolio positioning. Our analysis traces how these players interact across regulatory milestones, commercial launches, and global distribution footprints, giving readers a realistic view of the market’s power dynamics.
Merck & Co., Inc. remains the foundational reference point in this space as the original developer and manufacturer of Zolinza, an FDA-approved oral HDAC inhibitor indicated for cutaneous T-cell lymphoma in patients with progressive, persistent, or recurrent disease. The brand’s historical role extends beyond product supply; it also informs the clinical narrative, guideline positioning, and physician familiarity that continue to shape utilization patterns. With the composition-of-matter patent protection expiring in 2011, the market entered a structural phase in which generic entry became feasible across multiple jurisdictions. That transition did not erase the originator’s relevance, but it did introduce new competitive variables around price erosion, tender participation, and formulary segmentation.
The generic segment now includes multiple internationally active manufacturers, each pursuing distinct regional strategies and cost-centric value propositions. Accord Healthcare markets generic vorinostat capsules in regions including Europe and India for oncology applications. In October 2023, the company advanced its European footprint by launching generic vorinostat 100 mg capsules in the UK market following EMA approval. This move illustrates how regulatory clearance, combined with established distribution channels, can accelerate generic adoption in pricing-sensitive procurement environments.
Dr. Reddy's Laboratories, headquartered in Hyderabad, produces and supplies generic vorinostat for global markets with a clear focus on affordable HDAC inhibitor alternatives after patent expiry. In June 2022, the company received US FDA approval for generic vorinostat capsules in 100 mg and 400 mg presentations as AB-rated equivalents to Zolinza. This approval represents a meaningful commercial milestone because it opens access to the US procurement system, where equivalence recognition can influence institutional purchasing decisions and competitive pricing structures. The broader Indian manufacturing base also includes Hetero Drugs and Natco Pharma, both active suppliers of generic vorinostat formulations in international markets. Hetero emphasizes availability of generic formulations for CTCL treatment across export-oriented channels, while Natco underscores cost-effective oncology generics across multiple destination countries. Together, these suppliers contribute to a supply environment in which price competition, regional targeting, and manufacturing scale increasingly influence procurement outcomes.
For strategic planners, this competitive configuration raises several practical questions. Which supply partners offer the most reliable continuity for procurement programs? Where do pricing pressures intensify fastest, and what contract structures can mitigate exposure? How do branded and generic offerings coexist within hospital formularies and institutional procurement lists? The full report addresses these questions by connecting company profiles, regulatory events, and distribution behavior to market-level outcomes, allowing readers to benchmark supplier options and anticipate competitive friction before it disrupts sourcing plans.
Regulatory and Clinical Context as Market Shapers
The vorinostat market cannot be evaluated purely as a commercial volume equation because its behavior is closely tied to regulatory milestones, safety expectations, and guideline recognition. These elements structure prescribing confidence, procurement eligibility, and the practical boundaries within which manufacturers and buyers operate. Our study integrates this context directly into the market assessment so that strategic conclusions are grounded in clinical and regulatory reality rather than abstract demand modeling.
A foundational element of the market’s credibility is the 2006 accelerated approval pathway for Zolinza, which established vorinostat as a treatment option for CTCL in patients who had progressive, persistent, or recurrent disease on or following two systemic therapies. That approval created an official therapeutic anchor and, over time, reinforced the drug’s clinical familiarity. Equally important for contemporary planning is the ongoing relevance of guideline alignment. Inclusion of Zolinza in NCCN guidance for relapsed and refractory CTCL, with a category 1 recommendation for certain subtypes, strengthens formulary justification in settings where evidence hierarchy and treatment standardization matter. This type of endorsement can influence institutional purchasing preferences, particularly in structured procurement environments that weigh guideline concordance alongside price.
Worldwide Azacitidine Market
Safety considerations also shape how vorinostat is deployed in practice. The product carries black box warnings related to thromboembolism risk and QT prolongation, which require ECG monitoring and DVT prophylaxis in clinical use. From a strategic standpoint, these requirements influence hospital workflow, prescribing oversight, and the operational burden associated with therapy administration. They also affect how procurement teams evaluate supplier support services, patient management resources, and risk-mitigation materials that may accompany product supply. In mature markets especially, the effective management of safety protocols can be as important to sustained utilization as the molecule’s therapeutic efficacy.
Worldwide Vorinostat Market
Patent expiry continues to function as a structural market catalyst. With composition-of-matter protections having lapsed in 2011, the environment has shifted toward generic participation, price competition, and multi-source supply. This reality does not eliminate branded relevance, but it reframes it. Originator products now compete within a broader ecosystem where equivalence recognition, procurement consolidation, and cost control strategies determine share distribution. Understanding how these dynamics interact across jurisdictions is critical for anyone forecasting demand stability, negotiating supply terms, or planning product positioning over the 2026 to 2032 horizon.
What the Report Delivers for 2026 Decision-Making
Market research earns its value when it reduces uncertainty in real planning contexts. The Worldwide Vorinostat Market report is structured to support that objective by combining top-line market sizing with deeper operational coverage. The full publication details the historical baseline, the forecast architecture, and the segmentation logic across region, type, and application, while also translating these dimensions into planning-relevant interpretations. It examines how demand is organized, where procurement pressure is likely to intensify, and how regulatory or competitive events can alter trajectory expectations.
Beyond the quantitative spine, the report provides practical assessments of supplier behavior, approval timelines, generic entry patterns, and the procurement consequences of guideline and reimbursement environments. It addresses the market concentration profile, including the extent to which a concentrated set of participants shapes pricing and availability dynamics, and it explores the implications of that concentration for buyers seeking supply resilience. The study also contextualizes the interplay between branded legacy positioning and generic cost competition, helping teams anticipate where negotiation leverage may shift and which commercial levers are most likely to influence share outcomes.
For strategy, R&D, supply-chain, and commercial teams, the publication is designed to function as a working reference rather than a static overview. It supports capacity planning by clarifying likely demand progression, aids market-access prioritization by mapping the environments where utilization drivers are strongest, and informs partnership or sourcing decisions by highlighting supplier structures and regulatory milestones that affect reliability and cost. The full report also includes the kind of scenario-sensitive framing that enterprise planners need when preparing for multiple possible outcomes, from faster generic diffusion to slower formulary adoption in particular geographies.
Why This Study Belongs in Your 2026 Planning Cycle
In a market characterized by steady growth, established clinical use, and expanding generic participation, the strategic challenge is less about recognizing that the market exists and more about understanding how its internal architecture will evolve. The worldwide vorinostat market will continue to be shaped by the tension between therapeutic continuity, cost optimization, regulatory accommodation, and competitive supply expansion. Navigating that tension successfully requires intelligence that connects numbers to mechanisms and mechanisms to decisions.
Our study provides that linkage. It offers the macro visibility needed to set direction, the segmentation interpretation needed to prioritize effort, and the competitive and regulatory context needed to anticipate disruption. It is built to help planners avoid overreacting to isolated events while still recognizing the cumulative significance of approval milestones, generic launches, guideline reinforcement, and regional procurement trends. For organizations preparing for 2026, that combination is not optional; it is the difference between reactive positioning and deliberate strategy.
The full Worldwide Vorinostat Market report expands every dimension previewed here into a comprehensive decision-support package, with detailed coverage of market sizing, segmentation logic, competitive profiles, recent regulatory and commercial developments, and the operational implications of each factor for procurement, supply, and portfolio strategy. Readers who require precise planning inputs, supplier comparisons, and scenario-ready interpretation will find the complete study structured to support those needs directly. The report is available through our official market intelligence portal, where the full dataset, analytical commentary, and strategic frameworks can be accessed in their complete form.
For detailed analysis of this topic, please visit the official page: Worldwide Vorinostat Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Machine Tool Control Transformer Market to Hit $1,228.67M by 2032, 4.6% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the 2026 Corporate Agenda: Unlocking Latent Growth in Machine Tool Control Transformers
Navigating Macro Realities with Precision Data
As industrial manufacturing enters a phase of structural recalibration, the machine tool control transformer segment presents a unique blend of steady demand durability and hidden operational volatility. Our Worldwide Machine Tool Control Transformer Market study, anchored in a 2025 base year with historical tracking from 2020 to 2025 and a forward-looking trajectory extending through 2032, equips executive teams with the analytical scaffolding required to make informed, forward-looking decisions in 2026. The global market reached an estimated USD 896.84 million in 2025, having weathered a brief contraction in 2024 before resuming its upward momentum. Projections place the market at approximately USD 948.61 million in 2026, cascading toward a terminal valuation of USD 1,228.67 million by 2032. This long-arc expansion is underpinned by a compound annual growth rate of 4.6 percent, a figure that belies the underlying segmentation dynamics, pricing pressures, and engineering trade-offs that will define procurement strategies, capacity planning, and partnership decisions in the near term. For leadership teams operating at the intersection of automation investment, supply chain resilience, and cost optimization, the report delivers the contextual clarity necessary to move beyond headline figures and into actionable strategy.
Worldwide Machine Tool Control Transformer Market
Why This Study Matters for 2026 Decision-Making
The 2026 operating environment is characterized by intersecting forces: rising input costs, regional competitiveness shifts, and tightening automation cycles across discrete manufacturing. Machine tool control transformers sit at a critical juncture in factory electrical architecture, converting power to safe, stabilized voltages that enable motor starters, control relays, PLCs, and instrumentation to function reliably. Because these components are embedded in both legacy equipment retrofits and next-generation CNC and assembly-line deployments, demand does not simply track macro manufacturing output; it reflects nuanced decisions around maintenance cycles, production line modernization, and the replacement of aging electromagnetic control components. Understanding how the market is evolving across phase configurations, end-user applications, and geographic jurisdictions is no longer optional. The report maps these structural drivers with a granularity that supports scenario planning, contract negotiation, and product positioning. Rather than presenting a static snapshot, the analysis contextualizes historical performance from 2020 to 2025, identifies inflection patterns that shaped the 2024 correction, and walks through the 2026 to 2032 forecast window as a series of manageable, testable hypotheses. This framing allows procurement, engineering, and commercial teams to align internal assumptions with external market behavior before committing capital or renegotiating vendor terms.
Architecture of the Report: What Practitioners Can Deploy Immediately
The study is constructed to bridge high-level market intelligence with operational relevance. It opens with a consolidated market sizing and trend narrative, then layers in segmentation analysis across phase type, end-user application, and regional distribution. A dedicated competitive landscape section profiles key participants, comparing positioning, product-family breadth, compliance orientation, and engineering specialization. The report also integrates an input-cost and regulation mapping module designed to help readers anticipate margin shifts and compliance exposure rather than react to them after the fact. Each section includes structured takeaways intended for immediate transfer into business planning workflows, including demand-cycle interpretation, sourcing strategy mapping, and product-mix evaluation. By keeping the segmentation themes distinct yet interconnected, the document enables readers to trace how a change in one dimension, for example, regional procurement norms or phase configuration preferences, reverberates through pricing, specification requirements, and aftermarket service considerations. The emphasis throughout is on decision-useful clarity: enough analytical structure to support investment and sourcing choices, without reducing the market to oversimplified averages.
Segmentation Dynamics: Where Demand Is Concentrating
The demand base for machine tool control transformers is distributed across distinct configurations and use environments, each carrying different implications for specification, volume, and value capture. Across phase architectures, single-phase units have historically commanded the larger revenue share, reflecting their prevalence in control circuits for a broad range of industrial machinery and their alignment with common step-down requirements in distributed control panels. Three-phase configurations occupy a meaningful secondary position, typically associated with higher-power control applications and more demanding production-line environments. In end-user application terms, metal cutting machine tools represent a substantial demand anchor, consistent with the precision, repeatability, and electromagnetic stability requirements of CNC and machining centers. Metal forming machine tools contribute a significant second pillar, driven by press and stamping operations where control reliability intersects with equipment uptime and operator safety. Special purpose machines round out the application landscape, encompassing specialized automation and bespoke equipment where custom voltage transformation and inrush handling become differentiators. Geographically, the market spans multiple industrial regions, each with different competitive density, local compliance expectations, and procurement rhythms. The report examines how these regional and application-pattern differences interact with pricing sensitivity, specification customization, and lead-time tolerance, enabling readers to identify where demand resilience is structural and where it is more exposed to cycle risk.
Competitive Landscape: Strategic Posture Among Core Players
The market features a diversified set of manufacturers whose strategies reflect differing priorities in product architecture, compliance positioning, customization capacity, and geographic footprint. Hammond Power Solutions stands out in North America as a significant dry-type transformer manufacturer, offering molded machine tool industrial control transformers engineered for high inrush conditions across machine tools, conveyors, robotics, and production-line equipment. Its legacy molded styles also address electromagnetic components such as relays and solenoids, reinforcing breadth across control-circuit use cases. MCI Transformer Corporation operates from the United States with a focus on catalog and custom industrial control transformers designed to deliver low, safe control voltages for motor starters, timers, and similar electromagnetic devices, emphasizing adherence to stringent industry regulations. Controlled Magnetics provides a wide custom range from 100 VA to 500 kVA, targeting stepped-down voltages for machine tool control devices while highlighting inrush handling, energy efficiency, electrical isolation, and compliance with standards such as ANSI/NEMA ST-1, UL, and CSA for factory automation and machinery. SNC Manufacturing Co., Inc., now part of Allient Inc., produces single- and three-phase control transformers with step-up and step-down capabilities across specified primary and secondary voltage ranges and 50/60 Hz operation, supported by custom engineering services for industrial control circuits. Micron Industries contributes industrial control transformer offerings, including series designed for machine tool and industrial applications. PowerVolt Group Inc. designs and produces high-efficiency, UL-listed and CSA-certified control transformers for factory automation, industrial equipment, and machine tool control panels, with an emphasis on certification readiness and efficiency. Murrelektronik, with global operations anchored in Germany, offers isolation and control transformers suited to industrial and machine tool contexts. In Asia, Lushan China produces single-phase industrial control transformers for stepped-down voltages and high inrush applications, while ZHENGXI manufactures low-voltage dry-type machine tool control transformers in the 40 VA to 2500 VA range for CNC machines, automation panels, and industrial control. CNC Electric Group also competes in the Chinese market with control transformers developed using German technology for AC 50 to 60 Hz circuits. Boardman Transformers in the UK and SolaHD in the United States complete the landscape with offerings tailored to control circuits and special mounting requirements, respectively. The study examines how these players differentiate themselves through engineering focus, compliance profiles, customization capabilities, and regional presence, and it frames the competitive dynamics in terms of potential partnership, sourcing diversification, and specification strategy.
Cost Structure and Input Dynamics: The Margin Equation Under Pressure
Transformer economics are increasingly shaped by raw material trajectories and their interaction with design choices, order volumes, and regional sourcing flexibility. Copper remains a primary input for control transformers, and its price behavior directly affects production cost structures. In early 2026, copper prices briefly exceeded USD 14,500 per tonne intraday, with mid-year forecasts averaging near USD 12,075 per metric ton for the year, reflecting supply constraints and continued demand pull from electrification. At the same time, electrical steel costs have nearly doubled since 2020, driven by supply shortfalls and rising energy expenses, reinforcing cost-pressure dynamics across transformer manufacturing. Because grain-oriented silicon steel and copper together account for a substantial share of material costs in comparable transformer categories, these movements carry direct implications for pricing, margin management, and vendor negotiations. The report translates these input conditions into practical discipline for 2026 planning, emphasizing the need to evaluate specification trade-offs, volume commitments, and alternative sourcing pathways with an understanding of how material volatility may affect delivered cost over the contract horizon. It also contextualizes these pressures within broader electrification demand trends, helping readers separate cyclical price spikes from structural input-cost shifts that may persist into the forecast window.
Regulatory Context: Navigating Exemptions with Strategic Clarity
Regulatory frameworks can significantly influence testing, certification, and compliance planning, especially for components that sit close to the boundary between industrial control and distribution equipment. Importantly, U.S. Department of Energy energy conservation standards for distribution transformers explicitly exclude machine-tool control transformers from the definition and efficiency requirements. The latest final rule, published in April 2024, sets compliance obligations for covered distribution transformers beginning April 23, 2029, leaving machine-tool control transformers outside that direct mandate. Similarly, the California 2025 Energy Code exempts machine-tool control transformers from low-voltage dry-type distribution transformer certification requirements under Title 20 Appliance Efficiency Regulations. These distinctions matter because they shape how suppliers structure product documentation, how buyers evaluate efficiency claims, and where compliance resources are best allocated. The report consolidates this regulatory landscape so that engineering, quality, and procurement teams can avoid over-applying distribution-transformer assumptions to control-transformer procurement, while still tracking future rule-making that could shift the boundary over time. For companies operating across multiple jurisdictions, this clarity supports more precise compliance roadmaps and more informed evaluation criteria for both standard and custom units.
How to Use This Intelligence: From Market Map to Execution
The study is designed to feed directly into planning cycles, sourcing reviews, and competitive positioning discussions. Readers can use the segmentation and regional analysis to pressure-test demand assumptions, identify where application-specific requirements justify specification premium, and assess where procurement strategies may benefit from supplier diversification or regional nearshoring. The competitive profiles help teams benchmark their own product or sourcing positions against the broader field, highlighting where customization capability, certification readiness, or inrush-handling performance may function as competitive differentiators. The input-cost and regulatory sections provide a basis for more robust commercial modeling, enabling earlier identification of margin-risk scenarios and more disciplined compliance planning. Throughout, the report encourages a disciplined approach: use the macro trajectory and structural segmentation to frame expectations, then layer in the operational details that determine how a market-sized opportunity becomes a realized advantage in a specific product line, region, or customer segment.
A Note on Depth, Data Access, and the Next Step
This overview is intended to signal the scope, rigor, and practical orientation of the full study while preserving the detailed segmentation tables, regional breakdowns, and company-specific competitive metrics for the complete report. The strategic value of the analysis lies not only in aggregate market direction but in the way the study connects macro sizing, application and phase dynamics, regional demand patterns, input-cost pressure, and regulatory context into a single decision framework. For organizations preparing 2026 investment, procurement, or product strategy decisions, that integrated view is the difference between reacting to market headlines and anticipating the mechanics that drive them. The complete Worldwide Machine Tool Control Transformer Market report extends this foundation with the full segmentation detail, competitive comparison depth, and forecast scenarios needed to translate intelligence into execution. We invite decision-makers to access the full report to obtain the complete datasets and analytical structure required to support confident, well-timed strategic action.
Machine Tool Bearing Market
For detailed analysis of this topic, please visit the official page: Worldwide Machine Tool Control Transformer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com