
Blogs
PW Consulting: Worldwide Hot Tapping Machines Market Set to Grow at a 4.7% CAGR Through 2032
By pmarketresearch, 2026-08-18
Worldwide Hot Tapping Machines Market — Strategic Outlook 2026: A PW Consulting Intelligence Preview
PW Consulting today publishes an executive preview of our full "Worldwide Hot Tapping Machines Market" study (base year 2025, forecast 2026–2032). The global market reached approximately USD 680 Million in 2025 and, under a base-case growth trajectory, is projected to expand at a compound annual growth rate (CAGR) of roughly 4.7% through 2032. By 2032 the market is expected to be in the high hundreds of millions (USD), reflecting steady demand driven by pipeline integrity programs, water infrastructure rehabilitation, and industrial in-service interventions.
HBM Controller IP Market
Why this intelligence matters for 2026 decision-making
-
Operational resilience is now a board-level priority. Hot tapping remains one of the few reliable means to perform branch connections, repairs and interventions without service interruption—making procurement, supplier selection and deployment timing material to uptime and commercial continuity.
International Casualty Market -
Investment and procurement windows are compressing. With a predictable mid-single-digit CAGR and a shifting mix of project types, organizations that align capex and strategic sourcing with our scenario models will reduce acquisition costs, shorten lead times and improve fleet utilization.
Research Inverted Microscopes Market -
Regulatory and insurer scrutiny is intensifying. Standards and best practices put compliance and traceability at the front of RFPs; failure to demonstrate certified materials and documented testing can materially increase project costs and delay approvals.
-
M&A and consolidation optics are clear: concentration metrics in our study show a market where a handful of incumbent suppliers capture a meaningful share—creating both scale advantages for established players and niche opportunities for specialist providers.
What the full report delivers — practical, transaction-ready tools
-
Market sizing with transparent methodology: a reconciled top-down and bottom-up valuation for 2020–2025 and forward-looking scenarios for 2026–2032, enabling investors to stress-test revenue and margin outcomes under multiple demand and price environments.
-
Buyer’s playbooks and tender templates: procurement-ready scoring matrices that factor engineering capability, certification, warranty terms, spares availability and lead-time risk.
-
Supplier capability heatmaps and scorecards: comparative assessments that benchmark technical breadth, manufacturing depth, subsea and sour-service readiness, aftermarket coverage and geographical service footprints.
-
Operational checklists and field guides: inspection protocols, pre-deployment validation tests and maintenance routines tailored to high-pressure, low-pressure and municipal deployments.
-
Financial models and ROI calculators: downloadable spreadsheets for capex/opex trade-offs, shared-equipment pool economics, lifecycle cost of ownership and aftermarket revenue scenarios.
-
M&A diligence templates: a focused due-diligence pack that highlights contract liabilities, backlog quality, supplier concentration exposure and integration flags specific to hot tapping businesses.
-
Regulatory matrix and materials compliance map: line-by-line guidance showing how applicable codes and standards (including pipeline and pressure-equipment references) translate into procurement requirements and test plans.
Strategic implications and recommended plays for 2026
-
For OEMs: prioritize certification and traceability. The intersection of regulatory expectations and buyer scrutiny makes ASME/BPVC-equivalent certifications and NACE-compliant materials a non-negotiable. OEMs that invest in documented materials traceability, cryogenic/impact testing and sour-service capability will secure premium contracts and reduce warranty exposure.
-
For operators and EPCs: shift from transactional purchasing to asset-pool strategies. Given predictable demand growth, a shared-equipment model (joint ownership, regional depots, or managed service contracts) can materially reduce unit costs and idle time.
-
For aftermarket and service providers: develop bundled offerings. Combining hot tapping with line stopping, in-service welding, diagnostics and digital monitoring creates sticky revenue streams and increases lifetime customer value.
-
For investors and acquirers: screen for engineering differentiation and manufacturing control. Market concentration indicates room for bolt-on consolidation; target companies with proprietary tooling, strong in-house machining and repeatable aftermarket revenue.
Competitive landscape — what leading players signal about market direction
-
T.D. Williamson (TDW) — a broad catalog and global service network. TDW’s portfolio across large-diameter, onshore and offshore taps demonstrates the value of product breadth combined with field service capability for large operators.
-
STATS Group — specialization and in-house control. STATS’ proprietary high-pressure SureTap family and its recent manufacturing investment in Aberdeenshire underline a strategic choice: owning critical manufacturing capability to shorten delivery cycles and protect IP.
-
Reed Manufacturing and similarly focused mechanical providers — cost-effective small-diameter solutions. These firms occupy an essential position for lower-pressure civil and utility works where simplicity and reliability trump exotic capability.
-
Mueller Co., Aquatap and municipal-focused suppliers — entrenched water-sector expertise. Long-term relationships and domain knowledge in water-main interventions are strong defensive assets against new entrants.
-
Propipe, TECPESA and custom-engineering firms — high-pressure, high-temperature specialists. Their engineering-first model is attractive for petrochemical and heavy industrial clients who demand bespoke solutions.
-
Accessories and turnkey vendors such as Petersen Products, Enerpac (Mirage), 2LBin and Wheeler-Rex — they complete the ecosystem. Competitive advantage in this segment is driven by distribution reach, spares availability and modularity of systems.
-
Market activity signals: recent capital expenditure announced by a leading specialized manufacturer and industry sessions at the 2026 Pipeline Technology Conference indicate continued focus on manufacturing resilience, field reliability, and cross-disciplinary repair techniques.
Regulatory and materials landscape — compliance as a strategic asset
-
Standards and codes such as API’s hot tapping guidance and widely adopted ASME pipeline/pressure codes remain primary gating factors for field approval. Compliance is not just a checkbox; it materially affects insurability and contractors’ mobilization timelines.
-
Materials requirements matter. The use of pressure-vessel-grade steels, impact-tested components for low-temperature service and resistance to sulphide stress cracking per industry specifications are recurring procurement qualifiers in major tenders.
-
Procurement implication: request documented evidence of testing and third-party certification early in the RFP phase; failure to do so will elongate technical clarifications and increase commercial risk.
How to use this preview: three immediate next steps
-
Run a supplier readiness audit against our procurement checklist. Confirm certifications, spare-parts lead times and on-site commissioning capabilities ahead of project sanctions.
-
Model capex phasing with our mid-case CAGR assumption (4.7%) and test upside/downside scenarios for 24–36 month procurement cycles—this will identify optimal ordering windows and inventory buffers.
-
Engage with targeted OEMs for pilot programs that bundle equipment rental, service contracts and digital monitoring—pilots accelerate validation and reduce time-to-value for operators.
Access the full intelligence
This release intentionally highlights the strategic and operational insights PW Consulting provides while withholding proprietary segment-level splits and supplier scorecards that form the core of our paid study. The full report contains interactive models, vendor-level assessments, region- and application-specific forecasts, and downloadable procurement tools designed for immediate deployment by strategy teams, procurement departments and investors.
To obtain the complete report and the accompanying Excel toolset, contact PW Consulting’s research desk or visit our reports page. Our analysts stand ready to provide tailored briefings and scenario workshops to translate the findings into a 90–180 day action plan for your organization.
PW Consulting — converting market intelligence into executable strategy for the hot tapping ecosystem.
For detailed analysis of this topic, please visit the official page: Worldwide Hot Tapping Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Commercial Submersible Market Poised to Reach USD 513.25 Million by 2032, Growing at an 8.74% CAGR
By pmarketresearch, 2026-08-18
Worldwide Commercial Submersible Market: Strategic Imperatives for 2026 Decision‑Makers
PW Consulting's newest market study on the Worldwide Commercial Submersible Market serves as an operationally focused, strategy‑grade briefing for executives preparing capex decisions, product roadmaps, and M&A/partnership plays in 2026. Built on a 2020–2025 historical baseline and a 2026–2032 forecast horizon, the study synthesizes commercial dynamics, regulatory shifts, cost drivers, and supplier positioning into actionable recommendations — while preserving proprietary segment-level intelligence for subscribers.
Worldwide Cloud Management Platform (CMP) Market
Executive snapshot: What the macro picture means for your 2026 plan
-
Momentum: The commercial submersible market demonstrated consistent recovery and expansion through 2020–2025, rising from a low‑posture base to approximately USD 285.5 Million in 2025. Our forecast models, calibrated to demand drivers and regulatory tailwinds, project continued expansion to a mid‑cycle market of roughly USD 513.3 Million by 2032 at a compound annual growth rate (CAGR) of 8.74% for the 2026–2032 forecast period.
Small Popcorn Machine Market -
Concentration: Market concentration is meaningful — the three largest global suppliers account for roughly 45.5% of industry revenue, while the five largest capture about 62.3%. This creates a competitive landscape where scale, channel depth, and aftermarket capabilities materially differentiate outcomes.
Worldwide Injectable Cement Market -
Strategic timing: 2026 is a pivot year. With infrastructure spending and urbanization accelerating demand for wastewater management, dewatering, and groundwater extraction, buyers will shift procurement logic from capex minimization to lifecycle efficiency and compliance readiness.
Why this report matters to C‑suite and investment committees in 2026
-
Actionable, not academic: The study translates macro growth into decision trees for procurement, product investments, and service monetization. It avoids generic forecasts and instead maps demand scenarios to procurement windows, retrofit cycles, and capital replacement horizons relevant to municipal, commercial, and industrial operators.
-
Regulatory foresight: With energy and efficiency regulation intensifying — including the EU Ecodesign regime's MEI thresholds and U.S. DOE test/procedure emphasis on wire‑to‑water efficiency — our analysis quantifies compliance exposure and phased investment needs by pump class (full methodology included in the report).
-
Cost and supply‑chain sensitivity: We model raw material and manufacturing cost sensitivity, identify key margin pressure points, and outline hedging and sourcing strategies. Manufacturers and buyers alike can use the provided stress tests to evaluate contract pricing and vertical integration tradeoffs.
Market trajectory: evidence and interpretation
The market’s progression from the 2020 baseline into 2025 reflects a combination of deferred municipal upgrades, renewed commercial construction, and early commercialization of higher‑margin product families. Our base‑year calibration at 2025 anchors forward scenarios that show a structurally higher trajectory through 2032 driven by three converging forces: (1) rising infrastructure and urban resilience spending, (2) regulatory tightening on pump efficiency and emissions across major markets, and (3) product innovation enabling longer service intervals and new application niches.
These forces combine to elevate total addressable revenue and shift competitiveness toward firms that can offer not only hardware but predictable lifecycle performance and digital‑enabled service contracts. For buyers, the implication is clear: unit price will increasingly be a secondary metric to lifecycle cost, uptime guarantees, and regulatory proof points.
Key growth drivers and risk vectors
-
Infrastructure and urbanization: Continued public and private infrastructure investment underpins base demand for wastewater and water‑handling pump fleets.
-
Efficiency and regulation: MEI thresholds and DOE test regimes are accelerating replacement cycles for legacy equipment and favoring vendors with validated efficiency claims and certification roadmaps.
-
Materials and input cost volatility: Manufacturers face raw material cycles and capacity constraints. Our scenario work shows how component lead‑times and material price swings alter supplier margins and delivery risk.
-
Product innovation and aftermarket services: Launches of rugged stainless steel ranges, explosion‑proof wastewater lines, and abrasion‑resistant dewatering pumps are expanding addressable applications and enabling value‑added service contracts.
-
Concentration and consolidation: With the top tier controlling the majority of revenue, M&A activity and channel partnerships will be decisive — especially for regional specialists and aftermarket service providers.
Competitive landscape — who matters and why
Our competitor profiles emphasize strategic positioning rather than feature lists. Notable incumbents covered in the study include established global players with differentiated go‑to‑market models:
-
Xylem Inc. — A broad portfolio operator with recognized brand franchises focused on solids‑handling and energy‑efficient designs. Their strength lies in integrated systems and channel reach in municipal and commercial segments.
-
Grundfos — Reputation for reliability and sustainability solutions in building and infrastructure water systems; a leader where energy efficiency and long lifecycle value are procurement priorities.
-
Sulzer and Flowserve — Engineering‑heavy vendors that compete on robustness and application engineering in industrial process and treatment applications.
-
KSB and Franklin Electric — Deliver product breadth for demanding environments, from deep boreholes to abrasive dewatering; recent product introductions show renewed R&D focus on axial‑propeller motors and heavy‑duty assemblies.
-
Tsurumi, Ebara, Weir, and specialist OEMs — Each brings geographic specialization, durability narratives, or slurry/abrasion expertise that matter in specific commercial verticals.
Recent vendor activity underscores the shift toward differentiated hardware and service bundles: notable 2025 developments included rugged stainless ranges and axial‑propeller motor launches, expanded wastewater pump lineups with enhanced solids‑handling, and high‑efficiency explosion‑proof offerings showcased at major trade shows. These moves confirm that manufacturers are prioritizing regulatory compliance, field reliability, and serviceability as pathways to protect and grow share.
What’s inside the PW Consulting report (practical elements)
-
Proprietary demand model: A bottom‑up demand model calibrated across 2020–2025 and stress‑tested for 2026–2032 scenarios. The model converts infrastructure spend, urbanization, and replacement cycles into procurement timing and SKU demand curves.
-
Regulatory and test‑procedure playbook: Plain‑language implications of Ecodesign and DOE regimes, compliance impact by pump family, and certification roadmaps for product managers.
-
Cost and margin simulation: Factory‑gate cost build‑ups, material sensitivity analyses, and recommended supplier contracting strategies to protect margins under commodity swings.
-
Competitive heatmaps: Positioning maps that synthesize scale, service capability, regulatory readiness, and aftermarket potential to identify acquisition and partnership targets.
-
Commercial playbooks: Sales motions, pricing frameworks, and aftermarket monetization templates (service tiers, SLA design, and predictive maintenance economics) that commercial leaders can deploy within 90–180 days.
-
M&A and carve‑out screening: A prioritized list of targets and value drivers with return thresholds and integration risk diagnostics (full target identities and financials are provided to subscribers).
Strategic implications and recommended moves for 2026
-
Manufacturers: Prioritize certified efficiency upgrades and modular service platforms. Use 2026 to build or acquire digital diagnostics and aftermarket capabilities that convert one‑time sales into annuity streams.
-
Buyers/Operators: Shift procurement specifications to lifecycle metrics and require regulatory compliance evidence up front. Negotiate performance‑based contracts to align supplier incentives with uptime and efficiency outcomes.
-
Investors: Seek midsized OEMs with specialized application expertise and recurring service revenue potential. Our valuation scenarios show premium multiple expansion for targets that demonstrate >30% aftermarket revenue growth within three years post‑acquisition.
-
Policy and standards groups: Engage proactively with regulators. Early participation in test‑procedure discussions can shape practical, industry‑aligned compliance pathways that reduce retrofitting risk.
Information governance: what we withheld and why
Consistent with the “trailer” principle, PW Consulting displays analytical depth in the public briefing while reserving granular segment and regional breakdowns for subscribers. This includes detailed segment revenue splits, per‑region demand trajectories, and proprietary SKU‑level forecasts that clients use to calibrate tender responses, negotiate supplier contracts, and validate targets during diligence. The public summary signals opportunity and risk; the full dataset enables executable plans.
How to use this intelligence in practice
-
Integrate the demand model outputs with your procurement calendar to reorder capital projects and prioritize retrofit programs in 2026–2027.
-
Use the regulatory playbook to pre‑qualify product portfolios and avoid post‑procurement compliance costs.
-
Deploy the competitive heatmaps during vendor selection and M&A diligence to rapidly identify strategic fits and white‑space partnerships.
Next steps — accessing the full intelligence
Executives preparing 2026 budgets or evaluating buy/sell decisions should treat this briefing as an operational confidence tool and the full report as the decision‑grade dataset. The comprehensive subscription includes model files, vendor financials, SKU‑level forecasts, and a one‑day client workshop to translate findings into a 90‑day execution roadmap.
PW Consulting is available to present a tailored executive briefing and to provide bespoke scenario runs aligned to your procurement or investment constraints. For details on subscribing to the full Worldwide Commercial Submersible Market report and to schedule a workshop, please visit our report page (full subscription required to access segment‑level datasets and appendices).
In a market moving from replacement cycles to performance‑driven procurement, 2026 will reward organizations that combine technical compliance, aftermarket economics, and supply‑chain resilience. Our study gives leaders the framework and tools to make those judgments with confidence — while our proprietary datasets provide the tactical specificity that turns strategy into measurable returns.
For detailed analysis of this topic, please visit the official page: Worldwide Commercial Submersible Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Soft Ice Cream Powder Market Set to Grow at a 5.25% CAGR Through 2032
By pmarketresearch, 2026-08-18
Worldwide Soft Ice Cream Powder Market — Strategic Outlook for 2026
PW Consulting’s new market intelligence brief on the Worldwide Soft Ice Cream Powder market delivers a focused operational playbook for executives making high‑stakes decisions in 2026. Built on a transitionary base year of 2025 and a detailed historical review (2020–2025), the report synthesizes demand, supply and raw‑material pressures into a forward model that projects the market to 2032. At the headline level, the industry grew from approximately USD 658 million in 2020 to USD 845.5 million by 2025, with our forecast model pointing to continued expansion (the 2026 projection sits just under USD 900 million) and a compound annual growth rate of 5.25% through the 2026–2032 horizon.
Worldwide CNT Dispersant Market
What this report delivers — practical, transaction‑ready insight
- Integrated forecast model (2026–2032) with scenario stress tests for raw‑material shocks, regulatory shifts and rapid channel substitution.
- Procurement playbook: hedging strategies, contract structures and supplier segmentation for powdered soft‑serve ingredients.
- Go‑to‑market templates for manufacturers and co‑packers — channel strategies tailored to QSR, artisanal parlors, institutional catering and retail/HMR channels.
- M&A and partnership roadmap — valuation frameworks for targets across premix, ingredient tech and regional distribution platforms.
- Regulatory and trade heatmap including trade‑agreement impacts, tariffs and export restrictions that affect ingredient flows and competitive positioning.
- Supplier scorecards and benchmarking: manufacturing footprint risk, cost position, quality certifications and product innovation vectors (dairy, dairy‑free, sugar‑reduced).
- Commercial KPI dashboards to monitor margin pressure, SKU rationalization, and route‑to‑market ROI for 0–24 months and 24–60 months horizons.
Why this matters for 2026 decisions
2026 is shaping up to be a pivot year. The market’s steady growth to date masks three converging inflection points that will determine winners and laggards over the next 36 months:
International Casualty Market
- Input volatility: dairy ingredient supply cycles and commodity pricing volatility are creating asymmetric risk across suppliers and finished‑goods producers.
- Channel re‑mix: rapid soft‑serve adoption in non‑traditional formats (packaged dessert innovations, mobile QSR, and expanded catering use) is changing order sizes and service requirements.
- Product differentiation: accelerated demand for dairy‑free, low‑sugar and label‑clean formulations is compressing commodity margins for traditional dairy premix suppliers while creating premiumization opportunities.
For executives, this means procurement, R&D, and commercial leaders must align on a single, time‑bound plan: protect short‑term margin through tactical hedges and supplier diversification, while simultaneously investing in product platforms that capture premium growth pockets.
Artificial Turf Solutions Market
Market dynamics and near‑term risk factors
Several sector‑specific developments drive our 2026 recommendations. On the supply side, skim milk powder — a core input in many formulations — has seen a notable production uplift in early 2026 versus the prior year, tightening the interplay between domestic supply and exportable availability. Concurrently, benchmark price bands for export‑grade skim and whole milk powders remain elevated relative to historic averages, making input pass‑through and contract design critical to protecting gross margins.
Regulatory and trade policy continues to create structural frictions. Supply management mechanisms embedded in key trade agreements are constraining certain export flows, limiting arbitrage opportunities and prompting regional sourcing strategies. Meanwhile, milk‑price futures and domestic class‑price dynamics suggest further upward pressure on dairy‑linked formulations absent rapid demand contraction.
On the demand side, three demand drivers stand out: (1) QSR and convenience channels pursuing speed and consistency; (2) artisanal and premium outlets demanding clean‑label and texture innovations; and (3) institutional and retail segments experimenting with powdered formats to extend shelf life and simplify logistics. The interplay of these drivers will determine SKU proliferation, batch sizes and unit economics for co‑packers and manufacturers.
Competitive landscape — who matters and why
The market exhibits a mid‑level concentration: a small group of manufacturers exert measurable share and supply influence, but there remains significant room for regional specialists and new entrants. Our competitive matrix prioritizes firms by capability (R&D and clean‑label innovation), scale (export footprint and production capacity) and commercial reach (HoReCa vs. industrial accounts).
- Revala Ltd. (Keila, Estonia): positioned as a premium innovator, with award‑winning formulations and a strong export orientation. Their emphasis on dairy‑free variants and texture‑first recipes makes them a direct rival to specialty premium players and an attractive partner for premium QSR pilots.
- ARO Global: global manufacturing footprint and a reputation for reliable, scalable mixes. Their product set suits customers prioritizing operational consistency across geographies.
- Allwin Food (China) and Shandong Bigtree Dreyfus (Heze): large‑volume suppliers focused on commercial foodservice, where cost, supply continuity and adapted formulations for local palates drive selection.
- PreGel and Rubicone (Italy): legacy artisanal expertise, certifications and depth in premium gelato/soft‑serve technologies — critical for customers targeting premiumization and European export standards.
- Regional specialists (LYKKE, Lautan Premix, PMF, Oleo‑Fats, Keliff’s, AussieBlends, Alaskan Snow, Luigi’s Gelato): each brings differentiated strengths — rapid lead times, private‑label flexibility, machine compatibility certifications or optimized formulations for tropical climates.
Strategically, this mix creates three commercially attractive plays: (1) scale‑driven consolidation by mid‑sized players seeking export reach; (2) premium niche plays centered on clean‑label and dairy‑alternative formulations; and (3) distributed regional platforms that trade margin for delivery speed and local certification compliance. Our concentration metrics point to a market where top three firms control a meaningful share, but the top five do not preclude successful entry or carve‑out strategies by specialists.
Actionable recommendations for 2026 (prioritized)
- Immediate (0–6 months): implement layered procurement contracts tying a portion of volumes to index‑linked pricing, while securing fixed‑price coverage for critical SKUs to hedge short‑term spikes. Renegotiate supplier SLAs to include force‑majeure clarity for export disruptions.
- Near term (6–18 months): accelerate product reformulation roadmaps toward dairy‑alternative and reduced‑sugar bases where margins justify investment. Pilot co‑innovation agreements with machine OEMs to lock in texture and throughput advantages for your formulations.
- Medium term (18–36 months): pursue acquisitive growth for regional distribution platforms and mid‑market premix producers with complementary customer rosters. Prioritize targets with clean certifications and existing private‑label infrastructure.
- Commercial optimization: rationalize SKUs by channel profitability and implement channel‑specific packaging and dosing to lower logistics cost per serving in high‑velocity accounts.
- Sustainability and compliance: embed ingredient traceability into supplier scorecards to de‑risk brand exposure and open doors to premium buyers looking for audited supply chains.
How PW Consulting helps — engagement options for 2026
For teams that need execution support, PW Consulting offers three tailored engagement modules:
- Strategy Sprint (6–8 weeks): focused procurement and hedging playbook, supplier short‑list and contractual templates to deploy immediately.
- Transformation Program (6–12 months): end‑to‑end commercial optimization, SKU rationalization, pricing architecture, and M&A target screening with valuation workstreams.
- Sector Partnership (ongoing): rolling market intelligence subscription with weekly raw‑material alerts, access to supplier performance dashboards, and quarterly scenario re‑runs linked to commodity and trade developments.
Where to find the full dataset
This briefing is a strategic “trailer” designed to show line‑of‑sight and decision relevance without revealing proprietary segment‑level breakdowns and granular time‑series tables that are part of the full PW Consulting dataset. The full report contains detailed regional and application splits, supplier financial benchmarks, and downloadable forecasting models that translate the headline 5.25% CAGR and top‑line market trajectory into actionable revenue and margin scenarios for specific business models.
To access the complete dataset, proprietary segmentation tables, and bespoke advisory options tailored to your market position, please visit the PW Consulting report page or contact our industry desk for a confidential briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Soft Ice Cream Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Absorption Heat Pumps Market to Reach USD 2,845.34 Million by 2032, Driven by a 5.62% CAGR
By pmarketresearch, 2026-08-18
Worldwide Absorption Heat Pumps Market — Strategic Insights for 2026 Decision‑Makers
Executive summary
PW Consulting’s new market brief on the Worldwide Absorption Heat Pumps (AHP) market is designed as a tactical guide for corporate strategy, procurement, and product teams preparing for 2026. Built on a 2025 base year and extending through a 2026–2032 forecast horizon, the study combines an audited historical series (2020–2025), primary interviews with original equipment manufacturers (OEMs), and plant‑level performance data to deliver decision‑grade insight. The market grew from USD 1,476.6 Million in 2020 to USD 1,940.5 Million in 2025 and is forecast on a compound annual growth rate (CAGR) of 5.62% through the projection window, reaching USD 2,845.34 Million by 2032.
Ni-Cd Rechargeable Battery Market
Why this matters for 2026
2026 will be a pivotal year for organizations that must reconcile decarbonization targets with pragmatic energy systems choices. Absorption heat pumps, as thermally driven alternatives to electrically compressed systems, are increasingly relevant where waste heat, gas, or renewable thermal inputs exist. Our report translates macro demand projections into operational levers that CFOs, plant managers, and strategy teams can act on immediately — from capital allocation and retrofit prioritization to supplier selection and regulatory capture.
Embryo Holding Medium Market
Market snapshot (what the headline numbers tell you)
-
Scale and trajectory: The AHP market reached USD 1,940.5 Million in 2025 (base year) and is projected to expand at a CAGR of 5.62% across 2026–2032, culminating at an estimated USD 2,845.34 Million in 2032. These topline figures reflect a combination of renewed industrial demand for waste‑heat recovery, incremental commercial HVAC upgrades, and targeted policy incentives.
IV Training Arm Model Market -
Concentration and competition: Market concentration is moderate—our competitive analysis shows the top three firms account for approximately 48.5% of market revenue and the top five for about 62.3%—implying that while global leaders set technology standards, meaningful share remains accessible to focused niche players and integrators.
-
Report foundations: The study’s base year is 2025, it reviews 2020–2025 historical performance, and provides detailed scenario analysis and a seven‑year forecast (2026–2032).
What the report delivers — practical, transaction‑ready intelligence
PW Consulting’s analysis is built for execution. Beyond headline forecasts, the full report contains:
-
Vendor scorecards and product differentiation matrices that evaluate technology (single/double/triple effect), driving heat‑source compatibility, service models, and reliability records.
-
CapEx/OpEx and levelized cost of delivered heating/cooling models calibrated to real project data — enabling side‑by‑side comparisons of absorption systems versus electric compression alternatives and hybrid configurations.
-
Site prioritization methodology: a heat‑mapping toolkit and decision tree that converts plant utility data into ranked retrofit opportunities with estimated payback bands and carbon reduction potential.
-
Regulatory and incentives playbook that translates current energy codes and tax provisions into practical procurement and rebate capture steps for multiple jurisdictions.
-
Three distinct adoption scenarios (conservative, baseline, accelerated) and sensitivity analyses around fuel prices, waste‑heat availability, and absorbent supply shocks.
Note: To preserve strategic value for buyers and partners, this press release intentionally omits granular regional/application splits and transaction‑level market amounts. Those core segment tables and downloadable spreadsheets are included in the full report.
Strategic implications for operators and investors
-
Prioritize waste‑heat integration where available. For sites with accessible low‑to‑medium grade heat streams, AHPs unlock compelling energy savings and emissions abatements without large electrical infrastructure upgrades. Our site‑level tool identifies which facility archetypes yield shortest payback under 2026 energy price assumptions.
-
Balance technology selection with absorbent supply risk. Lithium bromide (LiBr) remains the dominant absorbent in water‑LiBr systems and thus a fulcrum for system economics. LiBr cost volatility and availability materially affect lifecycle economics versus ammonia‑water alternatives; supply chain strategies and long‑term procurement contracts should be part of any deployment plan.
-
Service‑led models will win in retrofit markets. Given the retrofit complexity and long asset lives of AHPs, OEMs and integrators offering availability guarantees, performance contracting, and remote diagnostics capture higher margin and accelerate customer adoption.
-
Regulatory arbitrage can be a near‑term value driver. Updated efficiency codes and tax incentives in key jurisdictions are actively favoring thermally driven, waste‑heat‑utilizing systems. Organizations that structure projects to capture available rebates and tax credits will shorten payback and improve IRR in 2026 procurement cycles.
-
Modularization and manufacturing scale reduce capital hurdles. Suppliers with modular skid designs and localized assembly capacity materially reduce lead times and logistic costs—a decisive advantage given ongoing supply chain volatility.
Competitive landscape — who matters and why
The AHP competitive field is a mix of legacy HVAC giants, regionally dominant manufacturers, and specialized niche players. The report’s vendor analysis profiles the market leaders and their strategic positioning:
-
Shuangliang Eco‑Energy (China) — A world leader in industrial LiBr systems with an extensive installed base and patent portfolio emphasizing high‑efficiency waste‑heat recovery. Their scale and patent moat make them a go‑to for large industrial projects with proven engineering and service networks.
-
Johnson Controls (YORK) (United States) — A diversified portfolio approach across driving heat sources positions YORK to serve both commercial and industrial segments where integrated building controls and service contracts matter.
-
BROAD Group (China) — One of the largest global manufacturers of absorption chillers and heat pumps, with an emphasis on gas‑fired and thermally driven solutions for broad commercial and civil markets. Their volume advantage and range of unit sizes are strengths for large developers.
-
Thermax Limited (India) — Triple‑effect and multi‑energy systems are a core competency, making Thermax a strong contender for high‑efficiency industrial applications across emerging markets.
-
Robur S.p.A. (Italy) — Focused on gas absorption chillers and ammonia‑based systems, Robur’s technology portfolio is notable for high seasonal performance and low global warming potential refrigerant strategies.
-
Hope Deepblue, Ebara, Berg Chilling Systems (partnered with World Energy) — Regional specialists and OEMs that differentiate on marine/offshore suitability, direct‑fired designs, or localized manufacturing and service coverage.
Recent industry movements underscore dynamic competitive conditions. Notably, Stone Mountain Technologies suspended operations in March 2026 as it pursues strategic alternatives—an event that temporarily affects North American manufacturing capacity for gas absorption heat pumps and opens short‑term acquisition or partner opportunities for firms seeking to expand locally.
Risks and near‑term uncertainties
-
Raw material and supply chain shocks — Lithium bromide pricing and lead times, along with broader component shortages, can compress margins and push project timelines.
-
Policy shifts — While many jurisdictions are tightening efficiency codes and offering incentives, policy reversals or uneven local implementation create timing risk for project approvals and rebate capture.
-
Competition from electric heat pumps — Rapid improvements in electric compression heat pump performance and grid decarbonization can alter the relative economics of thermally driven solutions in some market segments.
How to use the PW Consulting report in 2026 planning cycles
-
Capital allocation: Use our site prioritization outputs to phase capex across fiscal quarters and align with grant application windows.
-
Procurement: Leverage vendor scorecards and contract checklists to structure supply agreements with performance guarantees and parts availability clauses.
-
M&A and partnership screening: Apply our valuation templates and regional readiness maps to identify tuck‑in targets or JV partners, especially where local manufacturing footprint or service networks are weak.
-
Policy advocacy: Use the regulatory impact matrices to prioritize code change proposals and to shape local incentive programs that favor thermally driven systems.
Next steps and access
This release highlights the strategic takeaways from PW Consulting’s Worldwide Absorption Heat Pumps Market study while deliberately preserving granular segment tables and transaction‑level figures to protect the commercial utility of the full dataset. The complete report includes downloadable financial models, regional project case studies, OEM performance benchmarking, and an interactive ROI calculator. Decision‑makers preparing 2026 capital plans or vendor negotiations should consult the full report for the numerical detail required to execute.
For access to the full dataset, report appendices, and a one‑hour briefing with PW Consulting’s lead analyst team, please visit our report page or contact your PW Consulting representative. Our advisors are available to run tailored scenario analyses using your site data and to help craft procurement and deployment roadmaps targeted to your 2026 objectives.
For detailed analysis of this topic, please visit the official page: Worldwide Absorption Heat Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Zhi Mu Extract Market Poised to Reach USD 82.86 Million by 2032, Expanding at a 6.74% CAGR
By pmarketresearch, 2026-08-18
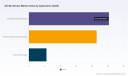
Worldwide Zhi Mu Extract Market 2026 Strategic Preview: Actionable Intelligence for Executive Decision‑Making
PW Consulting’s newest market research briefing—drawn from our full Worldwide Zhi Mu Extract Market report—translates deep primary research into a concise strategic playbook for business leaders planning for 2026. The global Zhi Mu extract market, measured in USD (Million), stabilised through 2020–2025 and reached a base‑year benchmark in 2025. Under our central scenario the market is expected to expand at a compound annual growth rate (CAGR) of 6.74% across the 2026–2032 forecast window, with a clear progression toward the end of the period. This preview surfaces the trends, risks, supplier dynamics and near‑term decision levers that matter to procurement heads, R&D teams, strategy groups and M&A advisors—while reserving the full segment tables and granular numbers for the full report.
Worldwide Tire Inflators Market
What the full report delivers — practical, executable outputs
- Market sizing and trend backbone: a transparent methodology with historical coverage (2020–2025), base year (2025) benchmarks and a detailed forecast model covering 2026–2032 (presented in USD, revenue unit: Million).
- Actionable supplier intelligence: validated profiles of incumbent and emerging producers, capability maps that connect certifications to application suitability, and a vendor evaluation matrix to accelerate sourcing decisions.
- Regulatory and trade risk playbook: scenario testing for tariff shocks, compliance checklists for major export markets, and guidance on quality control across phytochemical and contamination vectors.
- Product development & formulation briefs: extraction process choices, concentration and standardization tradeoffs, and recommended specifications for cosmetic, nutraceutical and pharmaceutical applications.
- Commercial strategies and price sensitivity analysis: go‑to‑market options, premium vs. volume positioning, and short‑term hedging approaches for raw material supply.
- M&A and partnership frameworks: value‑creation levers, target screening criteria and post‑deal integration checklists specific to botanical ingredient businesses.
Five high‑impact trends shaping 2026 decisions
- Steady underlying demand with selective premiumisation. The market’s mid‑single‑digit CAGR reflects solid, diversified end‑market interest—particularly where clean‑label, organic and clinically supported botanicals command a margin premium.
- Quality and certification as market differentiators. Buyers increasingly de‑risk formulations by selecting suppliers with pharmaceutical‑grade controls, organic accreditation or GFSI‑aligned certifications—making compliance and traceability a core procurement criterion.
- Trade policy and supply‑side vulnerability. Zhi Mu raw material and many finished extracts are primarily sourced from controlled cultivation in China. Recent trade measures have introduced step‑changes in landed costs—most notably US duties on some China‑origin botanicals that rose to a reported minimum of 145% in April 2025—forcing buyers to reappraise sourcing geographies and inventory policies.
- Form factor innovation and route to market. Liquid tinctures and alcohol‑free extracts have become important for small‑batch artisanal suppliers and direct‑to‑consumer brands, while standardized powder extracts sustain volume channels for manufacturers and contract formulators.
- Fragmentation with consolidation potential. The competitive landscape shows a broad field of regional specialists and boutique producers alongside a small group of larger exporters; the market concentration remains relatively low to moderate, leaving scope for strategic roll‑ups and vertical integration to create scale advantages.
Competitive landscape — capabilities, strategic moves, and risks
Our research validates and profiles a cross‑section of active players—from established botanical extract manufacturers in China to US‑based small‑batch tincture specialists. Key observed archetypes and strategic implications:
Medical LED Light Source Market
- Scale exporters with standardized SKUs: Companies offering standardized Zhi Mu root extracts and broad certification portfolios provide reliable volume supply for multinational formulators. Their strength lies in scale, regulatory documentation and export logistics; their challenge is margin pressure in commoditised channels.
- Specialist organic and pharma‑grade suppliers: Firms prioritizing organic certification, BRC or pharma‑oriented ISO routes serve premium segments and regulated pharmaceutical/nutraceutical demand. These suppliers can command higher prices and faster approval cycles for clinical or regulated products, but capacity for sudden demand spikes is often tighter.
- Customization and small‑batch innovators: North American small‑batch liquid extract producers offer agility for direct‑to‑consumer and craft brands—rapid iteration, formulation support and GMP‑aligned facilities in regulated jurisdictions provide local market advantages, albeit at smaller volumes.
- Regional raw material integrators: Entities that control upstream cultivation and rhizome processing reduce quality variability and provide traceability benefits. Integration helps mitigate supply shocks but requires capital and agronomic expertise.
Representative companies evaluated in the report include established extraction manufacturers, organic‑focused producers, and small‑batch tincture specialists. Recent vendor activities—such as trade show participation in Europe and the US, and catalog updates for organic lines—signal both demand outreach and product diversification strategies. These dynamics are discussed alongside vendor scorecards and supplier risk ratings in the full study.
Worldwide BPA-Free Water Bottles Market
Regulatory and supply‑chain constraints to model into 2026 plans
- Regulatory framework differences matter. In major export markets, botanical extracts may be regulated under dietary supplement law (e.g., DSHEA in the US) rather than full pharmaceutical statutes, which affects required testing, labeling and market claims. Buyers must align product specs to the target market’s regulatory classification early in the development cycle.
- Contaminant control and testing regimes. Routine testing for pesticides, heavy metals and microbial loads is non‑negotiable for cross‑border trade—our report provides a prioritized test matrix keyed to each major market.
- Tariff and non‑tariff risk. The reported tariff escalations on some China‑sourced botanicals have already altered landed cost calculus; scenario work in the full report quantifies breakpoints where near‑shoring, multisourcing, or inventory prepositioning become superior to single‑supplier strategies.
Strategic playbook for 2026 — prioritized actions
- Segment procurement by risk and margin: Classify SKUs into low‑risk volume buys (focus on cost and continuity) and high‑risk premium SKUs (focus on certification, traceability and supplier redundancy).
- Stress‑test supply chains against tariff scenarios: Run three scenarios—status quo, sustained elevated duties, and partial reversion—to identify optimal inventory days, dual‑sourcing thresholds and near‑shore substitution candidates.
- Invest selectively in supplier qualification: Allocate audit and laboratory budget to suppliers who can unlock higher‑margin channels (organic, pharma‑grade), and deploy a supplier scorecard that weights certifications, capacity, and quality history.
- Prioritize formulation dossiers for regulatory clarity: For product teams, finalize intended market classification and required dossier (safety, contaminants, claims substantiation) before scaling production contracts.
- Explore partnership structures over outright acquisition in the near term: Toll‑manufacturing, co‑development and long‑term offtake agreements often deliver quicker access to capacity and certifications than full M&A in a fragmented market.
How to use the full PW Consulting report
This article is designed as a strategic trailer: it outlines the market architecture, highlights actionable trends for 2026 and points decision makers toward the tactical playbook contained in the full report. The complete report includes:
- Segment‑level forecasts and sensitivity tables by form, application and region (interactive Excel model included).
- Comprehensive supplier dossiers with certification scans, capacity estimates and contact intelligence.
- Regulatory compliance checklists and lab testing protocols mapped to each market jurisdiction.
- Commercial templates—supplier scorecards, contract clauses for quality guarantees, and a decision framework for insourcing vs. outsourcing.
Download the full report to access the granular segmentation, price curves and model assumptions that underpin the executive recommendations above. The expanded dataset is indispensable for procurement RFPs, investor due diligence and corporate planning for 2026 and beyond.
Methodology and confidence
PW Consulting’s market model uses a base year of 2025 with a historical window of 2020–2025 and a forecast period of 2026–2032. The headline CAGR for the forecast window is 6.74%. Our analysis synthesizes primary interviews with manufacturers and buyers, customs and trade flow data, product catalog audits, and verification of certifications and lab results. The study also incorporates observed commercial activity—trade show participation and catalog updates—alongside publicly reported regulatory and tariff developments that materially affect landed costs and procurement strategy.
For strategic teams preparing budgets, supplier RFPs, or M&A screens for 2026, this briefing highlights where to focus resources now: supplier qualification, regulatory clarity and scenario planning for trade disruption. The full report delivers the underlying numbers, downloadable models and supplier scorecards necessary to convert these priorities into executable plans.
For detailed analysis of this topic, please visit the official page: Worldwide Zhi Mu Extract Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Field Pass is one of the richest sources of free rewards in Madden 27 Ultimate Team, but plenty of players never fully tap into it. Understanding how the track works and where the best rewards sit can dramatically boost your income. This guide helps you claim every free Nfl 27 Coins the Field Pass has to offer.
What the Field Pass Is
The Field Pass is a seasonal progression track that rewards you for playing Ultimate Team across the season. As you complete objectives and earn XP, you advance along the track and unlock rewards at each milestone. It is essentially free value for the playing you are already doing. The key is simply making sure you claim everything you earn.
How the Track Works
The Field Pass track is divided into levels, each unlocking a reward as you gain enough XP to reach it. The rewards grow more valuable as you progress further along the track. Understanding the pace of progression helps you set realistic goals for each season. Steady play naturally carries you through the track over time.
The Best Free Rewards
Some Field Pass rewards are worth far more than others, and knowing which ones to prioritize helps you plan. Coins, packs, and player rewards are usually the highlights, while smaller filler rewards are less important. Target the milestones that deliver real value and build your play around reaching them. A little focus turns the Field Pass into a serious income source.
Maximizing Your Progress
Maximizing Field Pass progress comes down to completing objectives efficiently and stacking them with your normal play. Every activity you do should ideally advance multiple goals at once. Check what advances the track before you play, and align your sessions accordingly. Efficient stacking is the difference between finishing the pass and falling short.
Combining Field Pass With Objectives
The Field Pass overlaps heavily with daily and weekly objectives, so combining them multiplies your rewards. A single play session can advance your daily goals, weekly goals, and the Field Pass all at once. Look for those overlaps and build your routine around them. This stacking habit quietly turns ordinary play into a rich source of income.
Free vs Paid Track Value
Most Field Passes offer a free track and a paid track, and it is worth understanding the difference before spending. The free track still contains substantial rewards, so you never need to pay to benefit. The paid track adds extra value, but only you can decide if it is worth the cost. Claim the free rewards first, then weigh the paid upgrade on its own merits.
Pacing Your Season
The Field Pass is designed to be completed over a season, so pace yourself rather than rushing. Steady, consistent play is far more sustainable than trying to finish the track in a burst. Let the rewards accumulate naturally as you enjoy the game. The players who pace themselves are the ones who actually reach the end.
The Bottom Line
The Field Pass is free value waiting to be claimed, and a little focus unlocks all of it. Understand the track, target the best rewards, and stack your objectives for maximum progress. Do that, and the Field Pass will keep your stack growing all season, alongside any Madden NFL 27 coins you choose to add.
PW Consulting Report: Worldwide Diclofenac Transdermal Patches Market Poised to Expand at a 6.5% CAGR Through 2032
By pmarketresearch, 2026-08-18
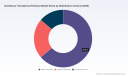
Worldwide Diclofenac Transdermal Patches Market: Strategic Imperatives for 2026
Executive summary
As healthcare systems accelerate shifts toward non-opioid pain management and payers sharpen reimbursement criteria, diclofenac transdermal patches have entered a new phase of strategic relevance. PW Consulting’s latest market study positions the worldwide diclofenac transdermal patches market at USD 648.55 Million in 2025, having grown from a mid-single‑hundred million base in 2020. Under a 6.5% compound annual growth rate (CAGR), the market is projected to approach roughly USD 1.01 Billion by 2032. This trajectory reflects a steady, durable expansion driven by clinical preference for topical NSAIDs, regulatory convergence on combination‑product quality, and new commercial pathways such as authorized generics and payer-led non‑opioid programs.
Translational Chip Testing and Sorting Machine Market
Why this report matters for 2026 decision-makers
- Actionable foresight: The study translates macro momentum into decision-ready scenarios for 2026—detailing where to prioritize manufacturing scale, commercial investment, and regulatory preparation.
- Market structure insights: While the category remains competitive, concentration metrics indicate meaningful scale benefits—top-three incumbent positions account for under half the market while the top five approach two-thirds—creating both competitive pressure and acquisition opportunities for mid‑sized players.
- Risk‑aware growth planning: The report integrates regulation, reimbursement, and safety risk layers (including the implications of boxed warnings and combination‑product oversight) into go‑to‑market models so executives can size opportunity against foreseeable constraints.
Core market dynamics shaping 2026 strategies
Four converging forces will define priorities for the coming year.
Worldwide Hydro Stoves Market
- Payer and clinical preference shifts: Public and private payers in several markets are actively emphasizing non‑opioid pain pathways in outpatient and post‑operative care. Inclusion in payer policies and favorable reimbursement criteria are increasingly decisive for adoption in ambulatory settings.
- Regulatory intensity for combination products: Transdermal diclofenac systems are regulated as combination products in several major jurisdictions, requiring stringent compliance with cGMP and device‑quality expectations. This raises the bar for manufacturing and quality assurance investments.
- Product differentiation via formulation and delivery: Hydrogel systems enabling extended (e.g., 12‑hour) relief, patch size and reservoir design, and variations in diclofenac salt forms create meaningful clinical and commercial differentiation points that affect prescribing and patient adherence.
- Commercial mechanics—brand, authorized generics, and access programs: Brand‑originator programs (including copay and direct patient assistance) coexist alongside authorized generics, creating a two‑front commercial playbook for price competitiveness and brand protection.
Strategic implications and recommended actions for 2026
- Prioritize payer engagement and evidence generation: Secure formulary placement through targeted real‑world evidence (RWE) and health economic dossiers that demonstrate topical NSAIDs’ benefits in reducing opioid exposure and improving recovery metrics.
- Invest in manufacturing and quality infrastructure: Given combination‑product regulation and the premium on consistent delivery performance, scale up cGMP‑aligned production, supplier qualification, and device testing to reduce regulatory and supply risk.
- Pursue flexible commercialization models: Evaluate authorized generic strategies, co‑promotion and licensing deals, and patient assistance programs as mechanisms to protect share while participating in price‑sensitive channels.
- Differentiate clinically and commercially: Leverage unique delivery technologies (e.g., hydrogel patches providing extended relief) and adherence‑focused support to command premium positioning versus commodity patches.
- Scan for value‑accretive M&A and manufacturing partnerships: Moderate top‑end concentration creates buy‑and‑build opportunities—target bolt‑on assets that add formulation expertise, geographic reach, or contract‑manufacturing capacity.
Competitive landscape — who matters and why
The player set comprises brand originators, global generics houses, specialist manufacturers, and integrated local producers. A succinct assessment of leading strategic positions follows:
Worldwide Anti Mould Paints Market
- IBSA Institut Biochimique SA (IBSA Pharma Inc.): The originator position remains strategically valuable because it anchors clinical recognition and payer discussions. IBSA’s branded topical system leverages hydrogel technology, extended relief claims, and proactive patient access programs—factors that sustain premium positioning even as generic alternatives proliferate. Recent updates to prescribing information and inclusion in payer policies underscore an active lifecycle management approach.
- Teva Pharmaceutical Industries Ltd.: As a major generics player, Teva’s presence with an authorized generic equivalent provides immediate scale and channel penetration. Large‑scale generics capability can rapidly commoditize pricing, making Teva a key competitor for volume‑oriented channels.
- Yaral Pharma (IBSA affiliate): Positioning as an authorized generic from the originator group enables a two‑tier commercial strategy: retain premium brand positioning while capturing price‑sensitive segments through an identical, lower‑cost alternative.
- Contract and specialist manufacturers (e.g., Teikoku Seiyaku, Sparsha Pharma, Gangwal Healthcare): Their cGMP transdermal capabilities are strategic enablers for sponsors seeking rapid scale or geographic diversification. Outsourcing to experienced patch manufacturers minimizes time‑to‑market and capital expenditure but requires careful supplier qualification to meet combination‑product expectations.
- Regional formulary players (selected local healthcare companies): Companies marketing diethylamine and sodium salt forms bring localized access and familiarity with national prescribing patterns—useful acquisition targets for players seeking market entry or broader product portfolios.
Regulatory and safety considerations
Executives must treat regulatory and safety developments as strategic variables rather than compliance checkboxes. Diclofenac topical systems carry class‑level cardiovascular and gastrointestinal safety considerations and peri‑operative contraindications that influence labeling, patient selection, and payer policy language. Notably, regulatory updates to prescribing information and payer policy inclusions over the last 18 months signal ongoing scrutiny; forward plans should include robust pharmacovigilance, targeted post‑marketing studies, and label management strategies aligned with global regulators’ combination‑product expectations.
What PW Consulting’s report delivers to operational teams
The report is structured to move executives from insight to execution. Highlights include:
- Financial models: rolling forecasts from 2026 through 2032 with scenario toggles for pricing, uptake, and reimbursement shocks calibrated to a 6.5% base CAGR and built off a 2025 market benchmark.
- Competitive playbooks: granular profiles of originators, generics, and specialist manufacturers with assessed strategic levers and likely near‑term moves.
- Go‑to‑market tools: payer engagement templates, launch sequencing plans, and contracting strategies for both branded and authorized generic approaches.
- Manufacturing and supply‑chain maps: capacity assessments, CMO shortlists, and risk mitigation checklists tailored to combination‑product production.
- Regulatory and safety matrix: jurisdictional requirements, label‑change risk assessments, and recommended post‑launch evidence strategies.
- M&A and partnership screening: diligence frameworks and candidate shortlists aligned to specific corporate objectives (scale, portfolio diversification, or capability acquisition).
To preserve competitive value for subscribing clients, the report intentionally withholds raw breakdowns of certain sub‑segment revenue shares and regional splits in this public summary. These detailed tables and interactive dashboards are accessible in the full report package.
Immediate actions recommended for 2026 planning cycles
- Embed payer evidence generation into 2026 budgets—allocate resources for targeted RWE and health economic modeling that aligns with non‑opioid performance metrics.
- Qualify at least two cGMP transdermal manufacturers for commercial supply to mitigate regulatory and capacity risk.
- Run rapid commercial scenarios evaluating authorized‑generic launch versus co‑promotion with brand originators to select the most value‑accretive pathway.
- Establish a safety‑communications and label‑management task force to proactively address regulatory updates and payer policy shifts.
- Scan and prioritize acquisition or partnership targets that fill key capability gaps—formulation science, device engineering, or regional distribution.
Concluding viewpoint
Diclofenac transdermal patches occupy a strategic intersection of clinical utility, payer interest, and manufacturing complexity. The category’s steady compound growth—anchored by a 6.5% CAGR to a near‑billion‑dollar opportunity by 2032—rewards players that combine rigorous regulatory compliance, clinical differentiation, and flexible commercial models. For 2026 planning, the signal is clear: investment in manufacturing quality, payer evidence, and differentiated delivery technology will determine which organizations capture sustainable share. PW Consulting’s report converts these high‑level signals into executable programs for teams ready to move from assessment to action.
About PW Consulting
PW Consulting is a specialty strategy advisor to healthcare executives, combining market analytics, regulatory insight, and commercial execution frameworks. This study leverages an historical data series (2020–2025), a 2025 base year, and forward projections covering 2026–2032. For access to the full dataset, segmented tables, interactive models, and bespoke advisory engagement, please consult the complete Worldwide Diclofenac Transdermal Patches Market report.
For detailed analysis of this topic, please visit the official page: Worldwide Diclofenac Transdermal Patches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Follow‑Me Autonomous Tech Propels Worldwide Hands‑Free Caddie Market to USD 587.14 Million by 2032 at 10.45% CAGR
By pmarketresearch, 2026-08-18
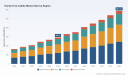
Worldwide Hands‑Free Caddie Market: Strategic Preview for 2026 — Insights from PW Consulting
PW Consulting’s latest market intelligence on the worldwide hands‑free caddie market provides a focused, decision‑ready briefing for executives planning investments, product launches, channel plays, or operational pilots in 2026. This executive summary teases the analytical depth of the full report — including validated market-sizing, forward forecasts, go‑to‑market frameworks, supplier scorecards and risk matrices — while preserving the proprietary sub‑segment detail reserved for the full dossier.
Worldwide General Medicine Education Publishing Market
Why 2026 Is a Pivotal Year
- Market momentum: After an aggressive recovery and expansion phase through the early 2020s, the market reached an estimated USD 292.8 Million (base year 2025). Our forecast shows sustained expansion over 2026–2032, with the market more than doubling from the 2025 base by the end of the forecast window.
- Structural acceleration: A measured but steady compound annual growth rate (CAGR) of 10.45% underpins this trajectory, reflecting both unit adoption and premiumization driven by autonomy, sensor integration, and service models.
- Decision timing: 2026 represents an inflection point where product maturity, regulatory attention, and buyer readiness align — making it the year to convert strategy into pilots, partnerships, and scaled deployments.
Key Market Dynamics Shaping Strategy
- Technology convergence: Hands‑free systems are converging around multi‑sensor stacks (visual AI, LiDAR/TOF, UWB/ultrasound, RF and Bluetooth) plus advanced control software. That convergence is creating a “feature battleground” in obstacle avoidance, slope management and power efficiency — areas that determine user satisfaction and course acceptance.
- Safety and standards pressure: Product safety design is no longer peripheral. Automatic downhill braking and stability systems are becoming mandatory features in leading models, and course operators now expect proof points on fail‑safe behaviors. This raises engineering costs but reduces operational risk for lessees and courses.
- Commercialization models: Leasing and fleet models for clubs and rental operators are becoming the dominant adoption path for institutional buyers, while retail and hybrid ownership remain important for individual golfers. Course operators evaluating hands‑free caddies are increasingly focused on lifecycle costs, uptime SLAs, and training/maintenance requirements.
- Consolidation and concentration: Market concentration indicates room for scale plays. Leading firms together command a meaningful share of market revenue, with the top three and top five vendors accounting for substantial portions of market revenue — a dynamic that favors well‑capitalized incumbents and disciplined consolidators.
Strategic Implications — What Leading Executives Should Do in 2026
Executives who treat 2026 as a trial‑and‑scale year will capture share and shape standards. Practical priorities include:
Worldwide Automatic Tolling Systems Market
- Prioritize partner pilots that validate safety and terrain performance. Shortlist vendors that can demonstrate robust downhill braking, obstacle avoidance and slope handling in club‑grade conditions, then run week‑long pilots across representative holes rather than single‑day demos.
- Design commercial models around total cost of ownership (TCO) and uptime. For clubs and rental fleets, make maintenance, training and spare‑parts logistics core to commercial negotiations. For consumer channels, emphasize warranty, drop‑in accessory ecosystems and trade‑in paths.
- Upgrade procurement RFPs to include standardized performance tests. Include pass/fail criteria for sensor redundancy, battery life under load, and recovery behaviors after communication loss. Use those tests in supplier scorecards to reduce post‑deployment surprises.
- Invest in a modular product roadmap. Given the rapid pace of sensor and AI improvements, companies should decouple hardware platforms from perception and autonomy stacks to accelerate feature upgrades while protecting hardware investments.
- Monitor regulatory developments and build compliance playbooks. From safety device requirements to worker‑classification implications in key markets, regulatory shifts will influence operating models, insurance and leasing structures.
Competitive Landscape — Who Matters and Why
The competitive field spans global incumbents, specialized innovators, and established outdoor/automotive OEMs pivoting into golf mobility. Below are the strategic positions of key players covered in our research and what to watch from each in 2026.
Worldwide Property & Casualty Policy Administration Systems Software Market
- MGI Golf — Australia HQ with significant US operations. MGI has pushed the envelope on productization with intelligent navigation series and a visible presence at trade events. Its January 2026 PGA Show introductions — including a LiDAR‑enabled follow/avoidance system and a lightweight on‑demand motorized pushcart — underline its dual focus on AI navigation and consumer convenience. For partners, MGI is notable for rapid market activation and strong channel execution in key markets.
- Stewart Golf — British engineering heritage. Stewart’s premium “follow” platforms emphasize mechanical stability and pace‑of‑play benefits on hilly courses. Its design and material choices support premium placements within club‑owned fleets and affluent consumer segments interested in engineered durability.
- CaddyTrek (FTR Systems) — US‑based robotic specialist. CaddyTrek’s product family includes ultrasound/RF and AI‑vision variants, offering multiple modes and proven terrain capability. Their product breadth makes them an attractive supplier for operators wanting flexible deployment options across varied course topographies.
- Robera — Product‑led innovator. Robera’s offerings prioritize gesture control and AI visual guidance with obstacle‑avoidance stacks that include iTOF/UWB. Their emphasis on robust sensor fusion positions them well where precision following and pedestrian safety are priority evaluation criteria.
- Kangaroo Golf — US‑based mass market and ergonomics focus. Kangaroo balances remote control simplicity with practical design — quick‑fold mechanisms and reliable autobrake systems — making it suitable for consumer retail channels and rental fleets seeking value and easy serviceability.
- Motocaddy, PowaKaddy, Alphard Golf, QOD Golf USA, Club Car (Ingersoll Rand) — Range of approaches from GPS‑integrated remote control to OEM‑scale deployments. These firms represent the trade‑off set between legacy electric trolley expertise and new autonomy features; some keep legacy products relevant via incremental autonomy integrations and OEM partnerships.
Regulation, Standards and Operational Risk
- Product safety requirements — including downhill braking and stability systems — are material for certification and course acceptance. Buyers should request third‑party test evidence and include safety clauses in contracts.
- Standards for follow technologies are not uniform: vendors use RF/ultrasound, visual AI, LiDAR/TOF and UWB in different combinations. Procurement teams should specify minimum sensing redundancy and obstacle‑avoidance performance rather than a single technology preference.
- Labor and insurance considerations can affect deployment models. In some jurisdictions, human caddies are subject to specific worker‑classification rules and compensation frameworks that can influence the cost calculus of shifting to autonomous fleets.
What the PW Consulting Report Includes (Practical, Actionable Deliverables)
The full report is designed as an operational toolkit for executives, including:
- Validated market sizing (historical 2020–2025 and forward 2026–2032 forecasts) and scenario analyses to stress‑test assumptions under different adoption curves.
- Go‑to‑market playbooks for three buyer archetypes: course operators (fleet/lease), consumer retail (direct and dealer), and hybrid rental marketplaces.
- Supplier diligence templates and a bespoke procurement RFP checklist that embeds performance pass/fail criteria for safety, terrain handling and maintenance economics.
- Commercial models comparing lease vs. purchase vs. managed‑service economics for club fleets, including sensitivity analyses for battery replacement, sensor upgrades and downtime penalties.
- Competitive scorecards and partnership matrices identifying best‑fit vendors by buyer need, integration complexity and scale readiness.
- Risk and compliance playbooks with recommended contract language, insurance considerations and pilot validation scripts to de‑risk rollouts.
How to Use These Insights in 90, 180 and 365 Days
- 90 days: Run a closed‑loop pilot with a single vendor across a small set of holes. Use our RFP checklist and pilot protocol to validate downhill braking, obstacle handling and service logistics.
- 180 days: Negotiate a scalable lease or managed‑service that includes spare‑parts provisioning, training and defined uptime SLAs. Use TCO models to compare vendor proposals.
- 365 days: Transition successful pilots into fleet rollouts or retail launches with staged feature upgrades. Lock in sensor‑stack modularity to preserve upgrade paths while amortizing hardware.
Next Steps and Where to Get the Full Dataset
This public briefing is a strategic preview that highlights why 2026 is a decisive year for market entry, scaling and consolidation decisions. For access to the full dataset — including the detailed segmentation tables, vendor scorecards, downloadable RFP templates, and the granular forecast model — visit PW Consulting’s report page for the Worldwide Hands‑Free Caddie Market. The full report contains the proprietary sub‑segment figures and channel‑level breakouts that underpin the recommendations summarized here.
PW Consulting’s global industry team remains available to support tailored procurement design, vendor selection facilitation, and pilot governance for organizations preparing to act in 2026. Contact us to book a briefing or to commission a custom variant of the market model aligned to your strategic objectives.
For detailed analysis of this topic, please visit the official page: Worldwide Hands-Free Caddie Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Chemical Injection Metering Pumps & Valves Market Poised to Reach USD 4,700 Million by 2025
By pmarketresearch, 2026-08-18
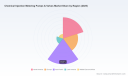
Chemical Injection Metering Pumps & Valves Market: Strategic Imperatives for 2026
As upstream activity recalibrates after successive cycles of oil price volatility, and water- and process-intensive industries accelerate digital and sustainability investments, chemical injection metering pumps and valves remain a mission‑critical element of operational integrity. PW Consulting’s latest market study—covering 2020–2025 historical performance and offering a 2026–2032 forecast—translates these dynamics into an actionable decision framework for executive teams planning capital allocation, supplier strategy, and technology adoption in 2026.
Air & Water Rinsing Machines Market
Market trajectory at a glance
Our analysis shows the global market expanding from the low billions in 2020 to an estimated USD 4.7 billion in 2025, with a projected upward trend to roughly USD 6.12 billion by 2032. The forecast period (2026–2032) is characterized by a compound annual growth rate (CAGR) of 3.85%. This mid-single-digit growth masks important inflection points: pockets of accelerated demand tied to deepwater and offshore chemical injection requirements, and episodic investment driven by water‑treatment and industrial process modernization programs.
Precious Metal Accounts Market
Importantly, the market is concentrated: the top three suppliers capture a meaningful share, and the top five command more than half of market revenues. That concentration has strategic implications for procurement leverage, qualification timelines, and M&A playbooks in 2026 and beyond.
Worldwide Coin-operated Commercial Laundry Market
Why 2026 is a pivotal year for decisions
- CapEx timing vs. operating risk: Many operators will face the classic CAPEX-versus-OPEX decision—invest today in higher‑specification, digitally enabled metering systems that reduce leak risk and maintenance burden, or continue with lower‑cost units and accept higher operational surveillance costs. Our scenarios quantify break‑even horizons for each approach under plausible oil price and service‑cost trajectories.
- Supplier selection under consolidation: With CR3 and CR5 indicating a moderately concentrated landscape, 2026 procurement strategies must weigh supplier stability, aftermarket coverage, and integration of engineered packages versus component‑level sourcing to preserve negotiating flexibility.
- Standards and compliance: API 675 remains the definitive specification for reciprocating positive‑displacement metering pumps in petroleum and petrochemical services. Tender and specification teams that align procurement language with API 675—and understand where bespoke engineering is justified—reduce specification risk and life‑cycle costs.
- Raw material volatility: Fluctuations in stainless steel and specialty alloys will affect margins and lead times. Hedging, multi‑sourcing, or strategic inventory moves are nontrivial decisions for 2026 procurement calendars.
What the PW Consulting report delivers—practical, decision‑grade content
This study is designed to be operationally useful, not just descriptive. Key deliverables include:
- Top‑level market sizing and seven‑year forecast with scenario bands that reflect differentiated demand drivers (offshore deepwater activity, water treatment modernization, chemical processing expansions).
- Vendor benchmarking that goes beyond product specs to assess API compliance, field reliability, aftermarket footprint, digital connectivity, and skid integration capability.
- Procurement playbooks with tender language templates, qualification checklists, and a risk‑weighted supplier short‑list methodology that procurement and engineering teams can use immediately.
- Technology and product roadmaps highlighting where diaphragm, piston, peristaltic and hybrid solutions are most appropriate—paired with OPEX modeling and lifecycle cost calculators.
- Supply‑chain stress tests and mitigation options to manage raw‑material and lead‑time volatility, including alternative materials, modular designs, and local assembly strategies.
- M&A and partnership screeners that identify acquisition targets and strategic alliance opportunities for component manufacturers, skid integrators, and valve specialists.
Competitive landscape—who matters and why
The vendor environment blends legacy pump specialists, engineered‑package integrators, and niche valve innovators. Our competitive analysis synthesizes company‑level strengths relevant to 2026 decisions:
- LEWA GmbH — Renowned for hermetically sealed diaphragm pumps and API‑compliant chemical injection packages. Strong in high‑pressure, critical applications where leak containment and reliability are non‑negotiable.
- IDEX Corporation (Pulsafeeder, Milton Roy, LMI) — A diversified portfolio across hydraulic diaphragm, solenoid‑driven, and mechanical metering technologies. Valuable where organizations prioritize breadth of solution and global aftermarket coverage.
- SPX Flow (Bran+Luebbe) — Excels in custom chemical injection systems for offshore applications, including double‑diaphragm designs that target high accuracy under cyclic loads.
- ProMinent GmbH — Notable for rapid product innovation and digital connectivity. Its recent beta/X launch signals the industry’s move toward lower‑footprint, connected diaphragm pumps with expanded control features.
- SkoFlo Industries — A specialist in pressure‑independent chemical injection metering valves for surface and subsea use—an increasingly important capability as field architectures consolidate pumps and distribute dosing points.
- Sidewinder, CheckPoint, Bruin Pumps — These suppliers are differentiated by ruggedized designs, solar and pneumatic offerings, and operational focus on oilfield chemicals such as methanol and corrosion inhibitors.
- Neptune (PSG) and Iwaki America — Strong positions in water treatment and industrial dosing, where precision at micro‑to‑mid flows and serviceability are priority purchase drivers.
Recent product introductions—from hydraulic API‑675 hydraulic diaphragm models to next‑generation solenoid and electronic drives—underscore supplier efforts to combine accuracy, reliability and connectivity. Our report maps these introductions to likely adoption pathways and total cost implications for field operators.
Regulation, materials, and deployment dynamics
Three external forces will shape vendor and buyer behavior in 2026:
- Standards enforcement: API 675 continues to set the bar for critical hydrocarbon applications. Tender committees that conflate “API‑style” features with true API 675 compliance expose projects to specification and warranty risk.
- Materials and cost volatility: Stainless steel and specialty alloy price swings require procurement to embed price adjustment mechanisms or design flexibilities into long‑lead contracts.
- Field architectures: Increasing deployment of pressure‑independent valves and multi‑point injection strategies will influence the balance between centralized high‑pressure pumps and distributed pumping concepts—affecting OPEX profiles and control complexity.
Actionable recommendations for C‑suite and procurement leaders in 2026
- Prioritize total‑cost‑of‑ownership analysis when approving CapEx: quantify leak‑risk, maintenance intervals, and digital monitoring ROI rather than defaulting to lowest initial cost.
- Implement a two‑track supplier strategy: maintain relationships with tier‑one API‑compliant vendors for critical duty, while qualifying regional specialists and valve innovators for lower‑risk or distributed injection points.
- Embed material‑price escalation clauses and dual‑sourcing for long‑lead components to blunt the impacts of alloy price swings.
- Accelerate pilot programs for connected metering assets that feed predictive‑maintenance outputs into existing asset‑management systems; validate expected OPEX reductions before fleet‑wide rollouts.
- Use the market concentration profile to time negotiations and partnerships—early 2026 may present a window to secure aftermarket commitments and favorable lead times before anticipated capacity investments among leading vendors.
Why PW Consulting’s study is the tactical tool your team needs
Beyond headline numbers, the report provides the blueprints procurement and engineering teams can use immediately: editable tender text, supplier‑scoring matrices, lifecycle cost models, and scenario playbooks that map supplier choice to field outcomes. We intentionally withhold granular segment tables from this press release to preserve the utility of the primary deliverable: a compact, executable intelligence product that guides supplier selection, risk mitigation and investment timing for 2026.
Next steps
Executives and technical leaders preparing budgets and supplier strategies for 2026 should review the full report to access the detailed segmentation, supplier scorecards, and downloadable procurement tools. PW Consulting also offers tailored briefings and live workshops to translate report findings into a 90‑day action plan for procurement, reliability engineering, and business development teams.
To obtain the complete study and arrange a strategy session, please visit the PW Consulting report page for Chemical Injection Metering Pumps & Valves Market. The full report contains the proprietary segment detail, company scorecards, and scenario models referenced here—essential inputs for any organization seeking to convert 2026 decisions into measurable performance gains.
For detailed analysis of this topic, please visit the official page: Chemical Injection Metering Pumps & Valves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide 3D-Printed Prosthetic Hands Market to Reach USD 371.66 Million by 2032, Growing at a 15.12% CAGR
By pmarketresearch, 2026-08-18
Worldwide 3D Printed Prosthetic Hands Market — Strategic Imperatives for 2026
PW Consulting’s latest market intelligence on the Worldwide 3D Printed Prosthetic Hands Market frames 2026 as a decision-rich year for manufacturers, payers, clinical providers, and technology partners. Our analysis shows the market at USD 138.7 Million in the 2025 base year, and, under current dynamics, on a trajectory to expand at a 15.12% CAGR through the 2026–2032 forecast window, approaching roughly USD 372 Million by 2032. This growth is being driven by simultaneous advances in additive manufacturing, clearer reimbursement signals, and stronger clinical evidence — creating both immediate opportunities and execution risks for firms that must choose where to compete, how to scale, and whom to partner with.
Worldwide Workplace Innovation Platforms Market
Why 2026 Is an Inflection Point
-
Reimbursement alignment: The September 2025 DME MACs and PDAC joint guidance recognizing additive manufacturing as an acceptable, reimbursable fabrication method for custom prosthetic devices removes a key commercial barrier. For suppliers and hospital systems, this shifts conversations from “will payers pay?” to “on what terms and for which use cases?”
Worldwide Big Data Analytics Software Market -
Commercial scale-up of digital manufacturing: Market actors are moving rapidly from prototyping to production-grade additive manufacturing. Notably, a major supplier has announced Medicare coverage while expanding in‑house 3D printing capacity fivefold using desktop resin systems, signalling that cost per unit and time-to-delivery are now management levers rather than immutable constraints.
Worldwide Asphalt Anti Strip Agent Market -
Regulatory and clinical convergence: FDA’s maturity in 3D printing guidance and a growing body of clinical literature demonstrating improved dexterity and satisfaction in upper‑limb prosthesis users make clinical adoption more defensible — but also raise the bar on quality systems, traceability, and post-market surveillance.
Market Structure and Competitive Dynamics — What Executives Need to Know
The market remains fragmented: CR3 sits below 20% and CR5 below 25%, underscoring that no single incumbent dominates the space. This fragmentation is fertile ground for focused entrants, rapid innovators and payer‑aligned partners — but it also demands disciplined portfolio choices.
-
Specialists focused on myoelectric, multi‑grip solutions are demonstrating how clinical approvals and insurance reimbursement unlock premium channels (pediatric care, orthotic‑prosthetic clinics, and major health systems).
-
Lean makers of body‑powered and partial‑hand devices are carving an adjacent low‑cost, high‑utility niche by leveraging robust additive nylon technologies and simplified mechanical designs to restore specific activities of daily living.
-
Nonprofit and humanitarian players emphasize localized printing and training models that change unit economics in low‑resource settings, influencing procurement practices and partner expectations in emerging markets.
Profiles and Strategic Implications of Core Competitors
-
Open Bionics — Clinically oriented bionics with insurance pathways and a strong product family strategy (multi‑grip hands, waterproof models, breathable sockets). Strategic implication: demonstrating the commercial value of clinically validated aesthetic and functional devices; a model to emulate for firms seeking payer coverage and pediatric focus.
-
PSYONIC — Lightweight, touch‑sensing Ability Hand leveraging 3D printed resins and now covered by Medicare, while materially scaling in‑house additive capacity. Strategic implication: combining product differentiation (haptic feedback) with scalable digital manufacturing creates a defendable cost/feature advantage — a competitive playbook for incumbents and fast followers.
-
Naked Prosthetics — Focus on durable, 3D printed body‑powered and partial‑hand devices using nylon additive technologies. Strategic implication: there is a sizable, under‑served segment where mechanical simplicity and material performance trump electronic complexity.
-
Unlimited Tomorrow — Verticalized model integrating 3D scanning, sockets, and hands to reduce cost while delivering realistic aesthetics. Strategic implication: vertical integration can compress lead times and margin leakage across the supply chain — a template for vertically minded companies or consolidators.
-
Limbitless Solutions — Innovation-led, donation-driven EMG devices that strengthen clinical trial pipelines and community goodwill. Strategic implication: philanthropic and trial activity can accelerate technology acceptance and provide low‑risk paths to evidence generation.
-
Victoria Hand Project — Low‑cost, localized printing and training solutions tailored to underserved regions. Strategic implication: humanitarian and local-manufacture models will increasingly influence pricing expectations and distribution strategies in international markets.
Operational Priorities — From Materials to Manufacturing
-
Materials and processes: Nylon and PA11 printed via SLS/MJF are the workhorses for durable, patient‑facing components; resin systems are enabling rapid iteration and embedded sensor housings. Procurement strategies should prioritize long‑term supply agreements for bio‑compatible grades and secondary certification pathways for sterilization and traceability.
-
Quality and regulatory architecture: FDA 510(k) pathways remain the most common route for externally applied prosthetics; additive manufacturing introduces process‑centric validation requirements. Firms must invest in process validation, device histories, and software change control now, not as a later add‑on.
-
Manufacturing footprint: Firms must choose between centralizing to capture scale‑economies and decentralizing to shorten clinical lead times and enable localized customization. Business models that hybridize (centralized critical components with localized final fitting) are emerging as pragmatic compromises.
Commercial and Reimbursement Playbook for 2026
-
Engage payers with evidence packages aligned to HCPCS descriptors and PDAC guidance; early alignment with DME MACs will materially reduce authorization friction for new prosthetic fabrication workflows.
-
Differentiate through service: bundled offerings combining scanning, socket customization, device fitment and follow‑up rehab services command premium positioning versus pure hardware sales.
-
Leverage clinical champions and real‑world evidence: multi‑center outcomes data demonstrating improved function and satisfaction shorten sales cycles with hospital systems and enhance payer negotiations.
-
Channel strategy: sustainable routes-to-market will include hospitals and clinics, rehab centers, direct-to-user models, and NGO partnerships — each requires different pricing, warranty and logistics planning.
Where PW Consulting’s Report Adds Tactical Value
Our full report is written for leaders making capital allocation, M&A, manufacturing, and go‑to‑market decisions in 2026. The publisher’s deliverables are purpose-built to be actionable:
-
Scenario‑based financial models that stress test manufacturing strategies, reimbursement outcomes, and pricing strategies.
-
Reimbursement playbook that walks through HCPCS alignment, PDAC submission considerations, and payer engagement timing following the 2025 guidance.
-
Supplier and technology matrix comparing SLS/MJF, resin systems, post‑processing, and material choices (with vendor benchmarking and unit‑cost sensitivities).
-
Go‑to‑market blueprints tailored to direct sales, clinical partnerships, NGO distribution, and hybrid service models, with contract templates and pilot KPIs.
-
Competitive playbooks with strategic counter‑moves for the firms profiled above, and an M&A screening tool to identify consolidation and capability‑acquisition targets.
Note: To preserve the strategic value of this briefing and to respect client confidentiality requirements, this public summary highlights aggregate market size and growth rates but does not disclose detailed regional, product, or end‑user share tables. The full report contains granular segmentation, regional revenue schedules, and unit‑level pricing models that are available only through PW Consulting’s report access channels.
Immediate Decisions for 2026
-
Prioritize quick wins in reimbursement: finalize PDAC coding strategies and pilot Medicare billing pathways now to realize revenue lift in 2026.
-
Decide on manufacturing posture: conduct a rapid make‑vs‑buy analysis that incorporates 3D printing CAPEX, capacity lead times, and labor upskilling needs.
-
Invest in outcomes data: fund at least one multi‑site real‑world outcomes study to support payer negotiations and differentiate in procurement bids.
-
Map strategic partnerships: identify clinical, technology and NGO partners that complement your chosen route-to-market and can accelerate adoption with minimal capital outlay.
PW Consulting’s Worldwide 3D Printed Prosthetic Hands Market report is designed as an operational playbook for 2026 decision‑makers who must transform regulatory and manufacturing momentum into sustainable commercial advantage. For access to the full dataset, regional and subsegment schedules, and bespoke advisory engagements, please visit our report page or contact PW Consulting directly for an executive briefing.
For detailed analysis of this topic, please visit the official page: Worldwide 3D Printed Prosthetic Hands Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com