

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Soft Ice Cream Powder Market Set to Grow at a 5.25% CAGR Through 2032

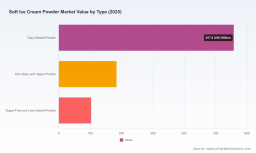
Worldwide Soft Ice Cream Powder Market — Strategic Outlook for 2026
PW Consulting’s new market intelligence brief on the Worldwide Soft Ice Cream Powder market delivers a focused operational playbook for executives making high‑stakes decisions in 2026. Built on a transitionary base year of 2025 and a detailed historical review (2020–2025), the report synthesizes demand, supply and raw‑material pressures into a forward model that projects the market to 2032. At the headline level, the industry grew from approximately USD 658 million in 2020 to USD 845.5 million by 2025, with our forecast model pointing to continued expansion (the 2026 projection sits just under USD 900 million) and a compound annual growth rate of 5.25% through the 2026–2032 horizon.
Worldwide CNT Dispersant Market
What this report delivers — practical, transaction‑ready insight
- Integrated forecast model (2026–2032) with scenario stress tests for raw‑material shocks, regulatory shifts and rapid channel substitution.
- Procurement playbook: hedging strategies, contract structures and supplier segmentation for powdered soft‑serve ingredients.
- Go‑to‑market templates for manufacturers and co‑packers — channel strategies tailored to QSR, artisanal parlors, institutional catering and retail/HMR channels.
- M&A and partnership roadmap — valuation frameworks for targets across premix, ingredient tech and regional distribution platforms.
- Regulatory and trade heatmap including trade‑agreement impacts, tariffs and export restrictions that affect ingredient flows and competitive positioning.
- Supplier scorecards and benchmarking: manufacturing footprint risk, cost position, quality certifications and product innovation vectors (dairy, dairy‑free, sugar‑reduced).
- Commercial KPI dashboards to monitor margin pressure, SKU rationalization, and route‑to‑market ROI for 0–24 months and 24–60 months horizons.
Why this matters for 2026 decisions
2026 is shaping up to be a pivot year. The market’s steady growth to date masks three converging inflection points that will determine winners and laggards over the next 36 months:
International Casualty Market
- Input volatility: dairy ingredient supply cycles and commodity pricing volatility are creating asymmetric risk across suppliers and finished‑goods producers.
- Channel re‑mix: rapid soft‑serve adoption in non‑traditional formats (packaged dessert innovations, mobile QSR, and expanded catering use) is changing order sizes and service requirements.
- Product differentiation: accelerated demand for dairy‑free, low‑sugar and label‑clean formulations is compressing commodity margins for traditional dairy premix suppliers while creating premiumization opportunities.
For executives, this means procurement, R&D, and commercial leaders must align on a single, time‑bound plan: protect short‑term margin through tactical hedges and supplier diversification, while simultaneously investing in product platforms that capture premium growth pockets.
Artificial Turf Solutions Market
Market dynamics and near‑term risk factors
Several sector‑specific developments drive our 2026 recommendations. On the supply side, skim milk powder — a core input in many formulations — has seen a notable production uplift in early 2026 versus the prior year, tightening the interplay between domestic supply and exportable availability. Concurrently, benchmark price bands for export‑grade skim and whole milk powders remain elevated relative to historic averages, making input pass‑through and contract design critical to protecting gross margins.
Regulatory and trade policy continues to create structural frictions. Supply management mechanisms embedded in key trade agreements are constraining certain export flows, limiting arbitrage opportunities and prompting regional sourcing strategies. Meanwhile, milk‑price futures and domestic class‑price dynamics suggest further upward pressure on dairy‑linked formulations absent rapid demand contraction.
On the demand side, three demand drivers stand out: (1) QSR and convenience channels pursuing speed and consistency; (2) artisanal and premium outlets demanding clean‑label and texture innovations; and (3) institutional and retail segments experimenting with powdered formats to extend shelf life and simplify logistics. The interplay of these drivers will determine SKU proliferation, batch sizes and unit economics for co‑packers and manufacturers.
Competitive landscape — who matters and why
The market exhibits a mid‑level concentration: a small group of manufacturers exert measurable share and supply influence, but there remains significant room for regional specialists and new entrants. Our competitive matrix prioritizes firms by capability (R&D and clean‑label innovation), scale (export footprint and production capacity) and commercial reach (HoReCa vs. industrial accounts).
- Revala Ltd. (Keila, Estonia): positioned as a premium innovator, with award‑winning formulations and a strong export orientation. Their emphasis on dairy‑free variants and texture‑first recipes makes them a direct rival to specialty premium players and an attractive partner for premium QSR pilots.
- ARO Global: global manufacturing footprint and a reputation for reliable, scalable mixes. Their product set suits customers prioritizing operational consistency across geographies.
- Allwin Food (China) and Shandong Bigtree Dreyfus (Heze): large‑volume suppliers focused on commercial foodservice, where cost, supply continuity and adapted formulations for local palates drive selection.
- PreGel and Rubicone (Italy): legacy artisanal expertise, certifications and depth in premium gelato/soft‑serve technologies — critical for customers targeting premiumization and European export standards.
- Regional specialists (LYKKE, Lautan Premix, PMF, Oleo‑Fats, Keliff’s, AussieBlends, Alaskan Snow, Luigi’s Gelato): each brings differentiated strengths — rapid lead times, private‑label flexibility, machine compatibility certifications or optimized formulations for tropical climates.
Strategically, this mix creates three commercially attractive plays: (1) scale‑driven consolidation by mid‑sized players seeking export reach; (2) premium niche plays centered on clean‑label and dairy‑alternative formulations; and (3) distributed regional platforms that trade margin for delivery speed and local certification compliance. Our concentration metrics point to a market where top three firms control a meaningful share, but the top five do not preclude successful entry or carve‑out strategies by specialists.
Actionable recommendations for 2026 (prioritized)
- Immediate (0–6 months): implement layered procurement contracts tying a portion of volumes to index‑linked pricing, while securing fixed‑price coverage for critical SKUs to hedge short‑term spikes. Renegotiate supplier SLAs to include force‑majeure clarity for export disruptions.
- Near term (6–18 months): accelerate product reformulation roadmaps toward dairy‑alternative and reduced‑sugar bases where margins justify investment. Pilot co‑innovation agreements with machine OEMs to lock in texture and throughput advantages for your formulations.
- Medium term (18–36 months): pursue acquisitive growth for regional distribution platforms and mid‑market premix producers with complementary customer rosters. Prioritize targets with clean certifications and existing private‑label infrastructure.
- Commercial optimization: rationalize SKUs by channel profitability and implement channel‑specific packaging and dosing to lower logistics cost per serving in high‑velocity accounts.
- Sustainability and compliance: embed ingredient traceability into supplier scorecards to de‑risk brand exposure and open doors to premium buyers looking for audited supply chains.
How PW Consulting helps — engagement options for 2026
For teams that need execution support, PW Consulting offers three tailored engagement modules:
- Strategy Sprint (6–8 weeks): focused procurement and hedging playbook, supplier short‑list and contractual templates to deploy immediately.
- Transformation Program (6–12 months): end‑to‑end commercial optimization, SKU rationalization, pricing architecture, and M&A target screening with valuation workstreams.
- Sector Partnership (ongoing): rolling market intelligence subscription with weekly raw‑material alerts, access to supplier performance dashboards, and quarterly scenario re‑runs linked to commodity and trade developments.
Where to find the full dataset
This briefing is a strategic “trailer” designed to show line‑of‑sight and decision relevance without revealing proprietary segment‑level breakdowns and granular time‑series tables that are part of the full PW Consulting dataset. The full report contains detailed regional and application splits, supplier financial benchmarks, and downloadable forecasting models that translate the headline 5.25% CAGR and top‑line market trajectory into actionable revenue and margin scenarios for specific business models.
To access the complete dataset, proprietary segmentation tables, and bespoke advisory options tailored to your market position, please visit the PW Consulting report page or contact our industry desk for a confidential briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Soft Ice Cream Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com