

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Hot Tapping Machines Market Set to Grow at a 4.7% CAGR Through 2032

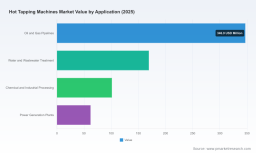
Worldwide Hot Tapping Machines Market — Strategic Outlook 2026: A PW Consulting Intelligence Preview
PW Consulting today publishes an executive preview of our full "Worldwide Hot Tapping Machines Market" study (base year 2025, forecast 2026–2032). The global market reached approximately USD 680 Million in 2025 and, under a base-case growth trajectory, is projected to expand at a compound annual growth rate (CAGR) of roughly 4.7% through 2032. By 2032 the market is expected to be in the high hundreds of millions (USD), reflecting steady demand driven by pipeline integrity programs, water infrastructure rehabilitation, and industrial in-service interventions.
HBM Controller IP Market
Why this intelligence matters for 2026 decision-making
-
Operational resilience is now a board-level priority. Hot tapping remains one of the few reliable means to perform branch connections, repairs and interventions without service interruption—making procurement, supplier selection and deployment timing material to uptime and commercial continuity.
International Casualty Market -
Investment and procurement windows are compressing. With a predictable mid-single-digit CAGR and a shifting mix of project types, organizations that align capex and strategic sourcing with our scenario models will reduce acquisition costs, shorten lead times and improve fleet utilization.
Research Inverted Microscopes Market -
Regulatory and insurer scrutiny is intensifying. Standards and best practices put compliance and traceability at the front of RFPs; failure to demonstrate certified materials and documented testing can materially increase project costs and delay approvals.
-
M&A and consolidation optics are clear: concentration metrics in our study show a market where a handful of incumbent suppliers capture a meaningful share—creating both scale advantages for established players and niche opportunities for specialist providers.
What the full report delivers — practical, transaction-ready tools
-
Market sizing with transparent methodology: a reconciled top-down and bottom-up valuation for 2020–2025 and forward-looking scenarios for 2026–2032, enabling investors to stress-test revenue and margin outcomes under multiple demand and price environments.
-
Buyer’s playbooks and tender templates: procurement-ready scoring matrices that factor engineering capability, certification, warranty terms, spares availability and lead-time risk.
-
Supplier capability heatmaps and scorecards: comparative assessments that benchmark technical breadth, manufacturing depth, subsea and sour-service readiness, aftermarket coverage and geographical service footprints.
-
Operational checklists and field guides: inspection protocols, pre-deployment validation tests and maintenance routines tailored to high-pressure, low-pressure and municipal deployments.
-
Financial models and ROI calculators: downloadable spreadsheets for capex/opex trade-offs, shared-equipment pool economics, lifecycle cost of ownership and aftermarket revenue scenarios.
-
M&A diligence templates: a focused due-diligence pack that highlights contract liabilities, backlog quality, supplier concentration exposure and integration flags specific to hot tapping businesses.
-
Regulatory matrix and materials compliance map: line-by-line guidance showing how applicable codes and standards (including pipeline and pressure-equipment references) translate into procurement requirements and test plans.
Strategic implications and recommended plays for 2026
-
For OEMs: prioritize certification and traceability. The intersection of regulatory expectations and buyer scrutiny makes ASME/BPVC-equivalent certifications and NACE-compliant materials a non-negotiable. OEMs that invest in documented materials traceability, cryogenic/impact testing and sour-service capability will secure premium contracts and reduce warranty exposure.
-
For operators and EPCs: shift from transactional purchasing to asset-pool strategies. Given predictable demand growth, a shared-equipment model (joint ownership, regional depots, or managed service contracts) can materially reduce unit costs and idle time.
-
For aftermarket and service providers: develop bundled offerings. Combining hot tapping with line stopping, in-service welding, diagnostics and digital monitoring creates sticky revenue streams and increases lifetime customer value.
-
For investors and acquirers: screen for engineering differentiation and manufacturing control. Market concentration indicates room for bolt-on consolidation; target companies with proprietary tooling, strong in-house machining and repeatable aftermarket revenue.
Competitive landscape — what leading players signal about market direction
-
T.D. Williamson (TDW) — a broad catalog and global service network. TDW’s portfolio across large-diameter, onshore and offshore taps demonstrates the value of product breadth combined with field service capability for large operators.
-
STATS Group — specialization and in-house control. STATS’ proprietary high-pressure SureTap family and its recent manufacturing investment in Aberdeenshire underline a strategic choice: owning critical manufacturing capability to shorten delivery cycles and protect IP.
-
Reed Manufacturing and similarly focused mechanical providers — cost-effective small-diameter solutions. These firms occupy an essential position for lower-pressure civil and utility works where simplicity and reliability trump exotic capability.
-
Mueller Co., Aquatap and municipal-focused suppliers — entrenched water-sector expertise. Long-term relationships and domain knowledge in water-main interventions are strong defensive assets against new entrants.
-
Propipe, TECPESA and custom-engineering firms — high-pressure, high-temperature specialists. Their engineering-first model is attractive for petrochemical and heavy industrial clients who demand bespoke solutions.
-
Accessories and turnkey vendors such as Petersen Products, Enerpac (Mirage), 2LBin and Wheeler-Rex — they complete the ecosystem. Competitive advantage in this segment is driven by distribution reach, spares availability and modularity of systems.
-
Market activity signals: recent capital expenditure announced by a leading specialized manufacturer and industry sessions at the 2026 Pipeline Technology Conference indicate continued focus on manufacturing resilience, field reliability, and cross-disciplinary repair techniques.
Regulatory and materials landscape — compliance as a strategic asset
-
Standards and codes such as API’s hot tapping guidance and widely adopted ASME pipeline/pressure codes remain primary gating factors for field approval. Compliance is not just a checkbox; it materially affects insurability and contractors’ mobilization timelines.
-
Materials requirements matter. The use of pressure-vessel-grade steels, impact-tested components for low-temperature service and resistance to sulphide stress cracking per industry specifications are recurring procurement qualifiers in major tenders.
-
Procurement implication: request documented evidence of testing and third-party certification early in the RFP phase; failure to do so will elongate technical clarifications and increase commercial risk.
How to use this preview: three immediate next steps
-
Run a supplier readiness audit against our procurement checklist. Confirm certifications, spare-parts lead times and on-site commissioning capabilities ahead of project sanctions.
-
Model capex phasing with our mid-case CAGR assumption (4.7%) and test upside/downside scenarios for 24–36 month procurement cycles—this will identify optimal ordering windows and inventory buffers.
-
Engage with targeted OEMs for pilot programs that bundle equipment rental, service contracts and digital monitoring—pilots accelerate validation and reduce time-to-value for operators.
Access the full intelligence
This release intentionally highlights the strategic and operational insights PW Consulting provides while withholding proprietary segment-level splits and supplier scorecards that form the core of our paid study. The full report contains interactive models, vendor-level assessments, region- and application-specific forecasts, and downloadable procurement tools designed for immediate deployment by strategy teams, procurement departments and investors.
To obtain the complete report and the accompanying Excel toolset, contact PW Consulting’s research desk or visit our reports page. Our analysts stand ready to provide tailored briefings and scenario workshops to translate the findings into a 90–180 day action plan for your organization.
PW Consulting — converting market intelligence into executable strategy for the hot tapping ecosystem.
For detailed analysis of this topic, please visit the official page: Worldwide Hot Tapping Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com