

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Commercial Submersible Market Poised to Reach USD 513.25 Million by 2032, Growing at an 8.74% CAGR

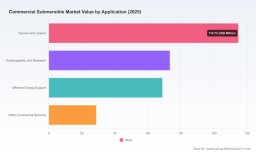
Worldwide Commercial Submersible Market: Strategic Imperatives for 2026 Decision‑Makers
PW Consulting's newest market study on the Worldwide Commercial Submersible Market serves as an operationally focused, strategy‑grade briefing for executives preparing capex decisions, product roadmaps, and M&A/partnership plays in 2026. Built on a 2020–2025 historical baseline and a 2026–2032 forecast horizon, the study synthesizes commercial dynamics, regulatory shifts, cost drivers, and supplier positioning into actionable recommendations — while preserving proprietary segment-level intelligence for subscribers.
Worldwide Cloud Management Platform (CMP) Market
Executive snapshot: What the macro picture means for your 2026 plan
-
Momentum: The commercial submersible market demonstrated consistent recovery and expansion through 2020–2025, rising from a low‑posture base to approximately USD 285.5 Million in 2025. Our forecast models, calibrated to demand drivers and regulatory tailwinds, project continued expansion to a mid‑cycle market of roughly USD 513.3 Million by 2032 at a compound annual growth rate (CAGR) of 8.74% for the 2026–2032 forecast period.
Small Popcorn Machine Market -
Concentration: Market concentration is meaningful — the three largest global suppliers account for roughly 45.5% of industry revenue, while the five largest capture about 62.3%. This creates a competitive landscape where scale, channel depth, and aftermarket capabilities materially differentiate outcomes.
Worldwide Injectable Cement Market -
Strategic timing: 2026 is a pivot year. With infrastructure spending and urbanization accelerating demand for wastewater management, dewatering, and groundwater extraction, buyers will shift procurement logic from capex minimization to lifecycle efficiency and compliance readiness.
Why this report matters to C‑suite and investment committees in 2026
-
Actionable, not academic: The study translates macro growth into decision trees for procurement, product investments, and service monetization. It avoids generic forecasts and instead maps demand scenarios to procurement windows, retrofit cycles, and capital replacement horizons relevant to municipal, commercial, and industrial operators.
-
Regulatory foresight: With energy and efficiency regulation intensifying — including the EU Ecodesign regime's MEI thresholds and U.S. DOE test/procedure emphasis on wire‑to‑water efficiency — our analysis quantifies compliance exposure and phased investment needs by pump class (full methodology included in the report).
-
Cost and supply‑chain sensitivity: We model raw material and manufacturing cost sensitivity, identify key margin pressure points, and outline hedging and sourcing strategies. Manufacturers and buyers alike can use the provided stress tests to evaluate contract pricing and vertical integration tradeoffs.
Market trajectory: evidence and interpretation
The market’s progression from the 2020 baseline into 2025 reflects a combination of deferred municipal upgrades, renewed commercial construction, and early commercialization of higher‑margin product families. Our base‑year calibration at 2025 anchors forward scenarios that show a structurally higher trajectory through 2032 driven by three converging forces: (1) rising infrastructure and urban resilience spending, (2) regulatory tightening on pump efficiency and emissions across major markets, and (3) product innovation enabling longer service intervals and new application niches.
These forces combine to elevate total addressable revenue and shift competitiveness toward firms that can offer not only hardware but predictable lifecycle performance and digital‑enabled service contracts. For buyers, the implication is clear: unit price will increasingly be a secondary metric to lifecycle cost, uptime guarantees, and regulatory proof points.
Key growth drivers and risk vectors
-
Infrastructure and urbanization: Continued public and private infrastructure investment underpins base demand for wastewater and water‑handling pump fleets.
-
Efficiency and regulation: MEI thresholds and DOE test regimes are accelerating replacement cycles for legacy equipment and favoring vendors with validated efficiency claims and certification roadmaps.
-
Materials and input cost volatility: Manufacturers face raw material cycles and capacity constraints. Our scenario work shows how component lead‑times and material price swings alter supplier margins and delivery risk.
-
Product innovation and aftermarket services: Launches of rugged stainless steel ranges, explosion‑proof wastewater lines, and abrasion‑resistant dewatering pumps are expanding addressable applications and enabling value‑added service contracts.
-
Concentration and consolidation: With the top tier controlling the majority of revenue, M&A activity and channel partnerships will be decisive — especially for regional specialists and aftermarket service providers.
Competitive landscape — who matters and why
Our competitor profiles emphasize strategic positioning rather than feature lists. Notable incumbents covered in the study include established global players with differentiated go‑to‑market models:
-
Xylem Inc. — A broad portfolio operator with recognized brand franchises focused on solids‑handling and energy‑efficient designs. Their strength lies in integrated systems and channel reach in municipal and commercial segments.
-
Grundfos — Reputation for reliability and sustainability solutions in building and infrastructure water systems; a leader where energy efficiency and long lifecycle value are procurement priorities.
-
Sulzer and Flowserve — Engineering‑heavy vendors that compete on robustness and application engineering in industrial process and treatment applications.
-
KSB and Franklin Electric — Deliver product breadth for demanding environments, from deep boreholes to abrasive dewatering; recent product introductions show renewed R&D focus on axial‑propeller motors and heavy‑duty assemblies.
-
Tsurumi, Ebara, Weir, and specialist OEMs — Each brings geographic specialization, durability narratives, or slurry/abrasion expertise that matter in specific commercial verticals.
Recent vendor activity underscores the shift toward differentiated hardware and service bundles: notable 2025 developments included rugged stainless ranges and axial‑propeller motor launches, expanded wastewater pump lineups with enhanced solids‑handling, and high‑efficiency explosion‑proof offerings showcased at major trade shows. These moves confirm that manufacturers are prioritizing regulatory compliance, field reliability, and serviceability as pathways to protect and grow share.
What’s inside the PW Consulting report (practical elements)
-
Proprietary demand model: A bottom‑up demand model calibrated across 2020–2025 and stress‑tested for 2026–2032 scenarios. The model converts infrastructure spend, urbanization, and replacement cycles into procurement timing and SKU demand curves.
-
Regulatory and test‑procedure playbook: Plain‑language implications of Ecodesign and DOE regimes, compliance impact by pump family, and certification roadmaps for product managers.
-
Cost and margin simulation: Factory‑gate cost build‑ups, material sensitivity analyses, and recommended supplier contracting strategies to protect margins under commodity swings.
-
Competitive heatmaps: Positioning maps that synthesize scale, service capability, regulatory readiness, and aftermarket potential to identify acquisition and partnership targets.
-
Commercial playbooks: Sales motions, pricing frameworks, and aftermarket monetization templates (service tiers, SLA design, and predictive maintenance economics) that commercial leaders can deploy within 90–180 days.
-
M&A and carve‑out screening: A prioritized list of targets and value drivers with return thresholds and integration risk diagnostics (full target identities and financials are provided to subscribers).
Strategic implications and recommended moves for 2026
-
Manufacturers: Prioritize certified efficiency upgrades and modular service platforms. Use 2026 to build or acquire digital diagnostics and aftermarket capabilities that convert one‑time sales into annuity streams.
-
Buyers/Operators: Shift procurement specifications to lifecycle metrics and require regulatory compliance evidence up front. Negotiate performance‑based contracts to align supplier incentives with uptime and efficiency outcomes.
-
Investors: Seek midsized OEMs with specialized application expertise and recurring service revenue potential. Our valuation scenarios show premium multiple expansion for targets that demonstrate >30% aftermarket revenue growth within three years post‑acquisition.
-
Policy and standards groups: Engage proactively with regulators. Early participation in test‑procedure discussions can shape practical, industry‑aligned compliance pathways that reduce retrofitting risk.
Information governance: what we withheld and why
Consistent with the “trailer” principle, PW Consulting displays analytical depth in the public briefing while reserving granular segment and regional breakdowns for subscribers. This includes detailed segment revenue splits, per‑region demand trajectories, and proprietary SKU‑level forecasts that clients use to calibrate tender responses, negotiate supplier contracts, and validate targets during diligence. The public summary signals opportunity and risk; the full dataset enables executable plans.
How to use this intelligence in practice
-
Integrate the demand model outputs with your procurement calendar to reorder capital projects and prioritize retrofit programs in 2026–2027.
-
Use the regulatory playbook to pre‑qualify product portfolios and avoid post‑procurement compliance costs.
-
Deploy the competitive heatmaps during vendor selection and M&A diligence to rapidly identify strategic fits and white‑space partnerships.
Next steps — accessing the full intelligence
Executives preparing 2026 budgets or evaluating buy/sell decisions should treat this briefing as an operational confidence tool and the full report as the decision‑grade dataset. The comprehensive subscription includes model files, vendor financials, SKU‑level forecasts, and a one‑day client workshop to translate findings into a 90‑day execution roadmap.
PW Consulting is available to present a tailored executive briefing and to provide bespoke scenario runs aligned to your procurement or investment constraints. For details on subscribing to the full Worldwide Commercial Submersible Market report and to schedule a workshop, please visit our report page (full subscription required to access segment‑level datasets and appendices).
In a market moving from replacement cycles to performance‑driven procurement, 2026 will reward organizations that combine technical compliance, aftermarket economics, and supply‑chain resilience. Our study gives leaders the framework and tools to make those judgments with confidence — while our proprietary datasets provide the tactical specificity that turns strategy into measurable returns.
For detailed analysis of this topic, please visit the official page: Worldwide Commercial Submersible Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com