

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Zhi Mu Extract Market Poised to Reach USD 82.86 Million by 2032, Expanding at a 6.74% CAGR

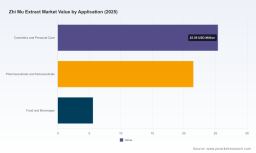
Worldwide Zhi Mu Extract Market 2026 Strategic Preview: Actionable Intelligence for Executive Decision‑Making
PW Consulting’s newest market research briefing—drawn from our full Worldwide Zhi Mu Extract Market report—translates deep primary research into a concise strategic playbook for business leaders planning for 2026. The global Zhi Mu extract market, measured in USD (Million), stabilised through 2020–2025 and reached a base‑year benchmark in 2025. Under our central scenario the market is expected to expand at a compound annual growth rate (CAGR) of 6.74% across the 2026–2032 forecast window, with a clear progression toward the end of the period. This preview surfaces the trends, risks, supplier dynamics and near‑term decision levers that matter to procurement heads, R&D teams, strategy groups and M&A advisors—while reserving the full segment tables and granular numbers for the full report.
Worldwide Tire Inflators Market
What the full report delivers — practical, executable outputs
- Market sizing and trend backbone: a transparent methodology with historical coverage (2020–2025), base year (2025) benchmarks and a detailed forecast model covering 2026–2032 (presented in USD, revenue unit: Million).
- Actionable supplier intelligence: validated profiles of incumbent and emerging producers, capability maps that connect certifications to application suitability, and a vendor evaluation matrix to accelerate sourcing decisions.
- Regulatory and trade risk playbook: scenario testing for tariff shocks, compliance checklists for major export markets, and guidance on quality control across phytochemical and contamination vectors.
- Product development & formulation briefs: extraction process choices, concentration and standardization tradeoffs, and recommended specifications for cosmetic, nutraceutical and pharmaceutical applications.
- Commercial strategies and price sensitivity analysis: go‑to‑market options, premium vs. volume positioning, and short‑term hedging approaches for raw material supply.
- M&A and partnership frameworks: value‑creation levers, target screening criteria and post‑deal integration checklists specific to botanical ingredient businesses.
Five high‑impact trends shaping 2026 decisions
- Steady underlying demand with selective premiumisation. The market’s mid‑single‑digit CAGR reflects solid, diversified end‑market interest—particularly where clean‑label, organic and clinically supported botanicals command a margin premium.
- Quality and certification as market differentiators. Buyers increasingly de‑risk formulations by selecting suppliers with pharmaceutical‑grade controls, organic accreditation or GFSI‑aligned certifications—making compliance and traceability a core procurement criterion.
- Trade policy and supply‑side vulnerability. Zhi Mu raw material and many finished extracts are primarily sourced from controlled cultivation in China. Recent trade measures have introduced step‑changes in landed costs—most notably US duties on some China‑origin botanicals that rose to a reported minimum of 145% in April 2025—forcing buyers to reappraise sourcing geographies and inventory policies.
- Form factor innovation and route to market. Liquid tinctures and alcohol‑free extracts have become important for small‑batch artisanal suppliers and direct‑to‑consumer brands, while standardized powder extracts sustain volume channels for manufacturers and contract formulators.
- Fragmentation with consolidation potential. The competitive landscape shows a broad field of regional specialists and boutique producers alongside a small group of larger exporters; the market concentration remains relatively low to moderate, leaving scope for strategic roll‑ups and vertical integration to create scale advantages.
Competitive landscape — capabilities, strategic moves, and risks
Our research validates and profiles a cross‑section of active players—from established botanical extract manufacturers in China to US‑based small‑batch tincture specialists. Key observed archetypes and strategic implications:
Medical LED Light Source Market
- Scale exporters with standardized SKUs: Companies offering standardized Zhi Mu root extracts and broad certification portfolios provide reliable volume supply for multinational formulators. Their strength lies in scale, regulatory documentation and export logistics; their challenge is margin pressure in commoditised channels.
- Specialist organic and pharma‑grade suppliers: Firms prioritizing organic certification, BRC or pharma‑oriented ISO routes serve premium segments and regulated pharmaceutical/nutraceutical demand. These suppliers can command higher prices and faster approval cycles for clinical or regulated products, but capacity for sudden demand spikes is often tighter.
- Customization and small‑batch innovators: North American small‑batch liquid extract producers offer agility for direct‑to‑consumer and craft brands—rapid iteration, formulation support and GMP‑aligned facilities in regulated jurisdictions provide local market advantages, albeit at smaller volumes.
- Regional raw material integrators: Entities that control upstream cultivation and rhizome processing reduce quality variability and provide traceability benefits. Integration helps mitigate supply shocks but requires capital and agronomic expertise.
Representative companies evaluated in the report include established extraction manufacturers, organic‑focused producers, and small‑batch tincture specialists. Recent vendor activities—such as trade show participation in Europe and the US, and catalog updates for organic lines—signal both demand outreach and product diversification strategies. These dynamics are discussed alongside vendor scorecards and supplier risk ratings in the full study.
Worldwide BPA-Free Water Bottles Market
Regulatory and supply‑chain constraints to model into 2026 plans
- Regulatory framework differences matter. In major export markets, botanical extracts may be regulated under dietary supplement law (e.g., DSHEA in the US) rather than full pharmaceutical statutes, which affects required testing, labeling and market claims. Buyers must align product specs to the target market’s regulatory classification early in the development cycle.
- Contaminant control and testing regimes. Routine testing for pesticides, heavy metals and microbial loads is non‑negotiable for cross‑border trade—our report provides a prioritized test matrix keyed to each major market.
- Tariff and non‑tariff risk. The reported tariff escalations on some China‑sourced botanicals have already altered landed cost calculus; scenario work in the full report quantifies breakpoints where near‑shoring, multisourcing, or inventory prepositioning become superior to single‑supplier strategies.
Strategic playbook for 2026 — prioritized actions
- Segment procurement by risk and margin: Classify SKUs into low‑risk volume buys (focus on cost and continuity) and high‑risk premium SKUs (focus on certification, traceability and supplier redundancy).
- Stress‑test supply chains against tariff scenarios: Run three scenarios—status quo, sustained elevated duties, and partial reversion—to identify optimal inventory days, dual‑sourcing thresholds and near‑shore substitution candidates.
- Invest selectively in supplier qualification: Allocate audit and laboratory budget to suppliers who can unlock higher‑margin channels (organic, pharma‑grade), and deploy a supplier scorecard that weights certifications, capacity, and quality history.
- Prioritize formulation dossiers for regulatory clarity: For product teams, finalize intended market classification and required dossier (safety, contaminants, claims substantiation) before scaling production contracts.
- Explore partnership structures over outright acquisition in the near term: Toll‑manufacturing, co‑development and long‑term offtake agreements often deliver quicker access to capacity and certifications than full M&A in a fragmented market.
How to use the full PW Consulting report
This article is designed as a strategic trailer: it outlines the market architecture, highlights actionable trends for 2026 and points decision makers toward the tactical playbook contained in the full report. The complete report includes:
- Segment‑level forecasts and sensitivity tables by form, application and region (interactive Excel model included).
- Comprehensive supplier dossiers with certification scans, capacity estimates and contact intelligence.
- Regulatory compliance checklists and lab testing protocols mapped to each market jurisdiction.
- Commercial templates—supplier scorecards, contract clauses for quality guarantees, and a decision framework for insourcing vs. outsourcing.
Download the full report to access the granular segmentation, price curves and model assumptions that underpin the executive recommendations above. The expanded dataset is indispensable for procurement RFPs, investor due diligence and corporate planning for 2026 and beyond.
Methodology and confidence
PW Consulting’s market model uses a base year of 2025 with a historical window of 2020–2025 and a forecast period of 2026–2032. The headline CAGR for the forecast window is 6.74%. Our analysis synthesizes primary interviews with manufacturers and buyers, customs and trade flow data, product catalog audits, and verification of certifications and lab results. The study also incorporates observed commercial activity—trade show participation and catalog updates—alongside publicly reported regulatory and tariff developments that materially affect landed costs and procurement strategy.
For strategic teams preparing budgets, supplier RFPs, or M&A screens for 2026, this briefing highlights where to focus resources now: supplier qualification, regulatory clarity and scenario planning for trade disruption. The full report delivers the underlying numbers, downloadable models and supplier scorecards necessary to convert these priorities into executable plans.
For detailed analysis of this topic, please visit the official page: Worldwide Zhi Mu Extract Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com